
 Air Audit Equipment Market | 2026-2036
Air Audit Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Audit Equipment Market Outlook
Pharmaceutical cleanroom operators are rotating toward continuous monitoring protocols, displacing periodic manual audits in legacy manufacturing facilities. Atlas Copco AB leverages its compressor-installed base to bundle audit hardware with service contracts. SUTO iTEC GmbH specializes in ISO 8573 validation tools for European food and beverage plants. Kaeser Compressors anchors its position through captive distribution and factory-trained technician networks.
Air audit equipment encompasses instruments that quantify particulate concentration, moisture content, oil vapor, and pressure dew point in compressed air and ambient environments, typically resolving contaminants at 0.1 micron or below to prevent product contamination or equipment corrosion. Gas analyzers dominate replacement demand as facilities retire electrochemical units, while laser-based technology captures the fastest expansion in semiconductor fabs where real-time particle detection prevents wafer yield loss. Pressure sensors occupy the most mature slot with thin margins, though process optimization applications concentrate margin pools in integrated systems that combine flow, pressure, and purity data on single platforms.
OSHA breathing air standards and FDA Current Good Manufacturing Practice regulations mandate documented compressed air purity in US pharmaceutical and food processing plants, forcing facilities to upgrade from paper-based logs to digital audit trails. The EU Green Deal's industrial emissions framework and REACH chemical accountability rules extend similar compliance burdens to European manufacturing clusters. Stakeholders must decide whether to build in-house calibration capabilities or outsource to accredited laboratories as certification requirements tighten across multiple jurisdictions.
Market Dynamics
Laser-based particle detection systems are decomposing the installed base of electrochemical analyzers across pharmaceutical and semiconductor cleanrooms, forcing incumbents to reposition service portfolios around real-time data architectures rather than periodic calibration contracts.
Growth Catalysts
- FDA sterility guideline enforcement:Pharmaceutical manufacturers in the United States must document compressed air purity at 0.1 micron resolution, mandating hardware upgrades from paper-based logs to digital audit trails.
- Automotive supplier network mandates:German OEMs require tier-one and tier-two suppliers to maintain ISO 8573 Class 1 certification, propagating audit equipment demand through component manufacturing clusters.
- Semiconductor wafer yield protection:Real-time contamination monitoring prevents particle-induced defects in advanced node fabrication, accelerating replacement cycles for legacy batch-sampling instruments.
Market Restraints
- Calibration infrastructure concentration:Accredited laboratories capable of certifying 0.1 micron reference standards cluster in Germany, Japan, and the United States, creating logistics bottlenecks for facilities in secondary markets.
- Sensor element supply vulnerability:Photodetector arrays and laser diodes for particle counters depend on specialized foundries in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Electrochemical sensor residual utility:Moisture and oil vapor detection in non-critical utility air systems still tolerates lower precision, delaying full technology displacement in cost-sensitive industrial segments.
Strategic Opportunities
- EU Green Deal industrial emissions framework:Carbon-intensive manufacturing clusters in Poland and the Czech Republic face new compressed air energy efficiency mandates, opening audit service bundling opportunities.
- Continuous monitoring protocol adoption:Pharmaceutical cleanroom operators are rotating from quarterly manual audits to 24/7 sensor networks, expanding recurring revenue pools for integrated platform vendors.
- Food and beverage ISO validation gap:European dairy and brewing facilities lag pharmaceutical compliance maturity, presenting first-mover advantage for validation tool specialists.
Industry Challenges
- Multi-jurisdiction certification complexity:Facilities supplying both FDA-regulated and EMA-regulated markets must maintain parallel calibration traceability chains, doubling documentation overhead.
- Legacy SCADA integration friction:Brownfield manufacturing plants run proprietary control architectures from the 1990s, requiring custom protocol gateways to connect modern audit equipment.
- Field technician skill scarcity:Competence in both compressed air system mechanics and laser optics alignment concentrates among aging workforce cohorts in industrial regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Audit Equipment Market |
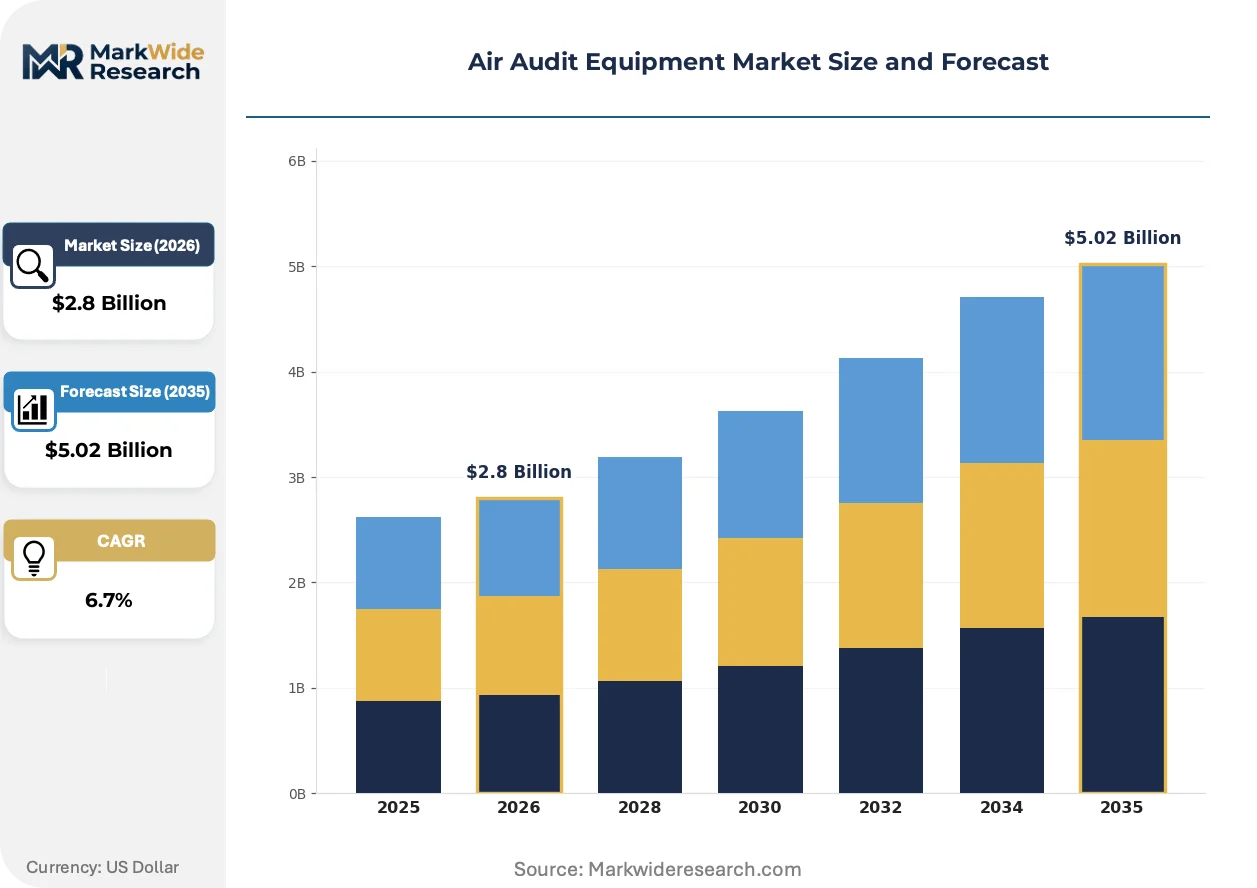
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Particulate Counters, Air Flow Meters, Pressure Sensors Technology: Laser-Based, Optical, Electrochemical, Ultrasonic End User: Manufacturing Facilities, Laboratories, Environmental Agencies, Commercial Buildings Application: Indoor Air Quality Monitoring, Emission Testing, Compliance Verification, Process Optimization |
| Companies Covered | Atlas Copco AB, Ingersoll Rand Inc., SUTO iTEC GmbH, FLIR Systems, Inc., Pentair PLC, Kaeser Compressors, Sullair, Gardner Denver, Donaldson Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Audit Equipment Market Strategic Shifts
Detection modality convergence and regulatory digitization mandates are compressing product lifecycles while expanding the addressable base beyond traditional compressed air monitoring into ambient cleanroom and process gas applications.
Photonic particle counters utilizing diode-pumped solid-state lasers are decomposing the market position of electrochemical diffusion sensors in high-precision environments. Semiconductor fabs in Taiwan and South Korea have adopted these instruments for inline wafer protection, enabling sub-0.1 micron detection thresholds that compress yield loss events from hours to seconds. The structural consequence is decomposing the historical segmentation between audit equipment and process control systems.
REACH chemical accountability rules and the EU Green Deal's industrial emissions framework are mandating documented compressed air energy efficiency across European manufacturing. Facilities must now correlate purity data with compressor power consumption, forcing equipment vendors to integrate flow, pressure, and electrical metering on unified platforms. Food processing plants in Germany and pharmaceutical operations in Ireland face the most compressed compliance timelines.
Service contract unbundling is fragmenting traditional compressor OEM aftermarket capture. End-users in the United States are separating audit hardware procurement from calibration and maintenance services, opening direct channels for specialized instrument vendors. This pattern concentrates among pharmaceutical contract manufacturers operating multi-site networks where centralized metrology teams demand equipment interoperability across supplier brands.
Air Audit Equipment Market Segmentation
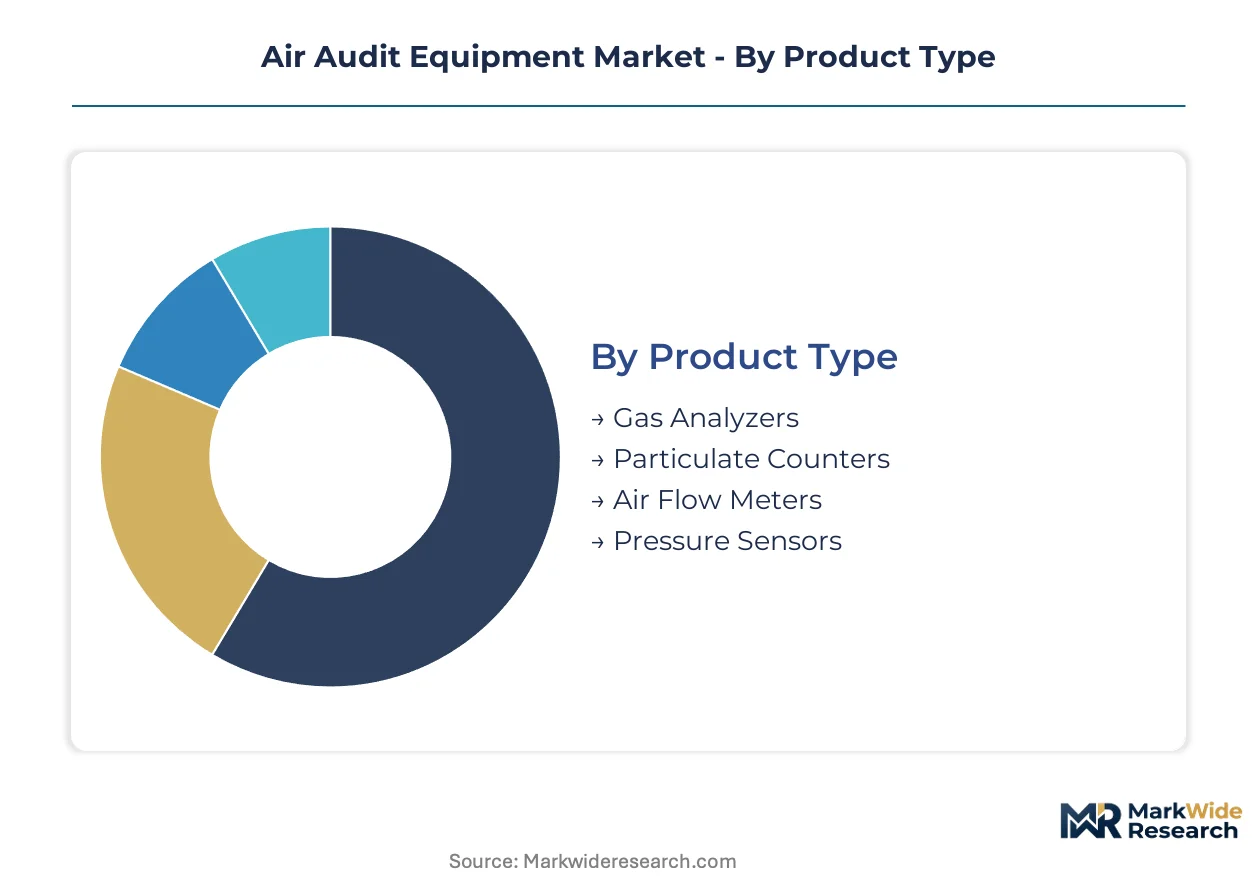
Air audit equipment segmentation reflects divergent technical requirements across precision-critical industries. Equipment specifications vary dramatically between pharmaceutical cleanrooms demanding 0.1-micron resolution and industrial utility systems tolerating coarser thresholds.
Product Type:
Domestic manufacturing clusters in Germany and the United States consume gas analyzers and pressure sensors for captive compliance programs, while particulate counters and air flow meters flow disproportionately to export markets in East Asian semiconductor fabrication.
- Gas Analyzers:These instruments quantify oil vapor, moisture content, and trace contaminants through infrared absorption or electrochemical reaction chambers. Pharmaceutical manufacturers in Ireland and North Carolina deploy these units to satisfy FDA breathing air documentation mandates, replacing legacy paper-based logging systems with digital audit trails.
- Particulate Counters:Laser-based optical detection resolves particles at 0.1 micron and below, preventing wafer yield loss in Taiwanese and South Korean semiconductor fabs. Real-time monitoring architectures displace batch-sampling instruments as facilities adopt continuous contamination surveillance.
- Air Flow Meters:Thermal mass and vortex-shedding designs measure compressed air consumption for EU Green Deal energy efficiency compliance in Polish and Czech manufacturing plants.
- Pressure Sensors:Thin-film piezoresistive elements dominate mature process optimization applications with compressed margin pools, though integrated systems combining multiple measurement modalities capture premium pricing.
Gas analyzers hold the largest share; momentum sits with particulate counters.
Technology:
Cost tier stratification separates premium laser-based systems from maintenance-intensive electrochemical units, with optical and ultrasonic methods occupying intermediate positions for specific contamination signatures.
- Laser-Based:Diode-pumped solid-state lasers enable sub-0.1-micron detection thresholds through photon-counting photodetector arrays. Semiconductor cleanrooms in Hsinchu and Pyeongtaek have standardized on these instruments for inline wafer protection, compressing yield loss events from hours to seconds.
- Electrochemical:Diffusion-based sensors for moisture and oil vapor detection retain residual utility in non-critical utility air systems where lower precision tolerates delayed technology displacement.
- Optical:Light-scattering techniques serve food and beverage ISO validation requirements in European dairy and brewing facilities with moderate precision demands.
- Ultrasonic:Time-of-flight measurement addresses flow velocity applications in compressed air distribution auditing without invasive probe insertion.
Laser-based systems command premium positioning; electrochemical methods face accelerating displacement.
End User:
Application concentration determines procurement patterns, with manufacturing facilities prioritizing integration capabilities while laboratories emphasize calibration traceability and environmental agencies demand ruggedized field portability.
- Manufacturing Facilities:Automotive OEM supplier networks in Germany enforce ISO 8573 Class 1 certification across tier-one and tier-two component manufacturers, propagating audit equipment demand through manufacturing clusters in Baden-Württemberg and Bavaria.
- Laboratories:Accredited calibration facilities in Germany, Japan, and the United States maintain 0.1-micron reference standards, creating logistics bottlenecks for secondary market facilities requiring certification services.
- Environmental Agencies:Industrial emissions monitoring under REACH and EU Green Deal frameworks drives portable audit equipment procurement for enforcement activities.
- Commercial Buildings:HVAC optimization applications represent emerging demand for indoor air quality verification in high-occupancy structures.
Manufacturing facilities dominate volume; laboratories concentrate margin through certification premiums.
Application:
Customer maturity separates compliance-driven procurement from optimization-motivated upgrades, with pharmaceutical and semiconductor segments leading continuous monitoring adoption while industrial utilities lag in periodic audit regimes.
- Indoor Air Quality Monitoring:Continuous sensor networks displace quarterly manual audits in pharmaceutical cleanrooms as operators rotate toward 24/7 contamination surveillance protocols.
- Process Optimization:Unified platforms integrating flow, pressure, purity, and electrical metering enable compressor energy efficiency correlation with air quality data.
- Compliance Verification:FDA sterility guidelines and OSHA breathing air standards mandate documented compressed air purity with digital audit trail requirements.
- Emission Testing:EU Green Deal industrial emissions frameworks extend compressed air energy efficiency mandates to carbon-intensive manufacturing clusters.
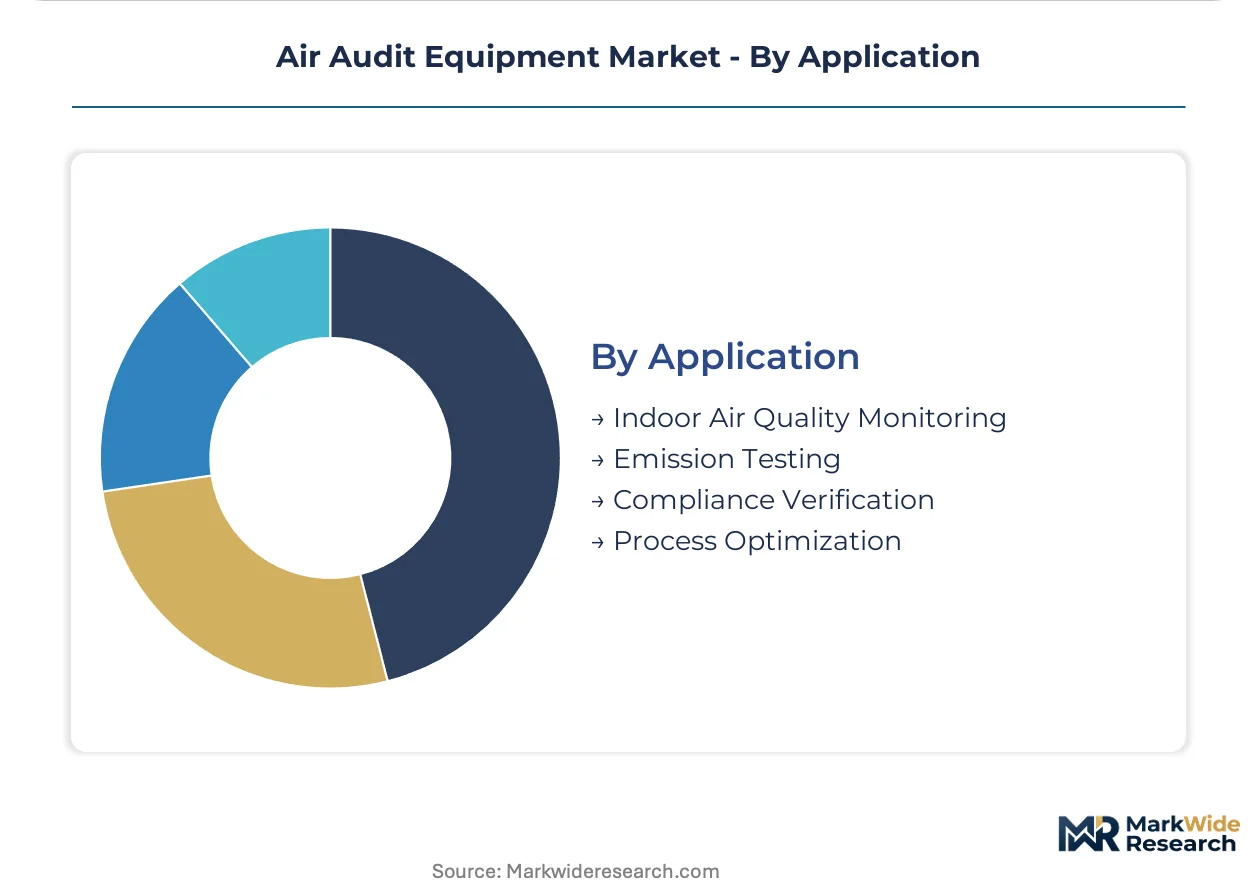
Compliance verification anchors current demand; process optimization presents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accredited calibration laboratories capable of certifying 0.1-micron reference standards cluster in Germany, Japan, and the United States. This geographic concentration shapes equipment procurement patterns and service logistics across secondary markets.
United States
Pharmaceutical contract manufacturers in North Carolina and Massachusetts drive FDA-mandated compressed air purity documentation. OSHA breathing air standards enforce digital audit trail requirements. Boston-area biotech clusters rotate from quarterly manual audits toward continuous monitoring protocols.
Germany
Automotive OEM supplier networks propagate ISO 8573 Class 1 certification through tier-one and tier-two component manufacturers. The EU Green Deal's industrial emissions framework mandates compressor energy efficiency correlation with purity data. Manufacturing clusters in Baden-Württemberg and Bavaria concentrate audit equipment demand.
Japan
Precision manufacturing facilities in Nagoya and Osaka maintain stringent contamination control for automotive and electronics applications. METI industrial standards emphasize documented compressed air quality in export-oriented production. Yokohama-based calibration facilities serve regional certification needs.
South Korea
Semiconductor fabs in Pyeongtaek and Hsinchu-adjacent operations adopt real-time particle detection for advanced node wafer protection. MFDS pharmaceutical manufacturing guidelines extend audit requirements to biologics production. Domestic photodetector array foundries supply laser-based instrument components.
China
Domestic pharmaceutical regulators tighten sterility documentation requirements for export-oriented manufacturing. Yangtze River Delta electronics clusters deploy audit equipment for process gas verification. Shenzhen and Shanghai concentrate demand for integrated flow-pressure-purity platforms.
Air Audit Equipment Market Competitive Environment
Concentration sits with diversified compressor OEMs leveraging installed bases to bundle audit hardware with service contracts. The market structure tiers across three strategic archetypes: integrated compressor manufacturers with captive distribution, specialized instrument vendors focused on ISO validation tools, and component suppliers providing sensor elements and photodetector arrays. Dominant competitive moves include service contract unbundling by end-users seeking equipment interoperability, and backward integration by platform vendors seeking captive supply of laser optics and flow measurement elements.
Among European specialists, SUTO iTEC GmbH represents the validation-tool archetype with ISO 8573-focused positioning. Atlas Copco AB anchors the integrated OEM tier through compressor-installed base leverage. Kaeser Compressors occupies a position within the captive distribution archetype, emphasizing factory-trained technician networks for aftermarket capture.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| SUTO iTEC GmbH |
| FLIR Systems, Inc. |
| Pentair PLC |
| Kaeser Compressors |
| Sullair |
| Gardner Denver |
| Donaldson Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term calibration service contracts lock in both supply access and price visibility for pharmaceutical manufacturers facing FDA sterility guideline enforcement, compressing procurement flexibility while stabilizing lifecycle costs across multi-year audit equipment deployments.
Pricing Analysis
ISO 8573 certification tiers dictate the pricing tier structure across the European automotive supplier network, separating Class 1 validation tools from standard industrial units. Three-tier pricing structure across premium laser-based, mid-grade optical, and economy electrochemical levels reflects detection precision and after-sales bundling intensity. Cost compression in the electrochemical segment is intensifying because semiconductor fabs accelerate displacement toward real-time particle monitoring. Contract manufacturers operating multi-site networks exhibit the highest price sensitivity, demanding equipment interoperability across supplier brands, while captive pharmaceutical cleanrooms show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Port congestion on the Rotterdam-Singapore trade lane elevates inbound logistics costs for photodetector arrays and laser diodes sourced from Taiwanese and South Korean foundries. Component manufacturing draws from Germany for precision pressure sensors, the United States for gas analyzer assemblies, and Japan for calibration reference standards. Single-source vulnerability concentrates in photodetector array supply from specialized Taiwanese foundries. Distribution runs through factory-trained technician networks anchored by compressor OEMs, with direct channels fragmenting as end-users unbundle hardware from service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping competitive positioning as pharmaceutical cleanroom operators demand unified flow-pressure-purity data architectures, forcing interoperability investments that favor ecosystem orchestrators over point-solution vendors.
For Market Incumbents: Secure captive supply of laser optics and photodetector arrays through backward integration into Taiwanese and South Korean component foundries, insulating against lead time volatility while defending margin position against specialized instrument vendors. Deepen ISO 8573 validation tool portfolios to capture food and beverage compliance gaps before first-mover specialists consolidate European dairy and brewing accounts. For New Entrants and Emerging Players: Anchor in Polish and Czech manufacturing clusters facing EU Green Deal compressed air energy efficiency mandates, where incumbent compressor OEMs lack localized validation expertise. Target continuous monitoring protocol adoption in pharmaceutical contract manufacturing networks as the most penetrable application, leveraging cloud-native data architectures as the primary go-to-market angle against legacy SCADA-integrated systems. For Investors and Strategic Acquirers: Capital is best deployed toward specialized instrument vendors with ISO 8573-focused positioning and software-layer differentiation, as platform convergence compresses pure hardware valuations. Watch semiconductor fab capital expenditure cycles as the signal indicating inflection in laser-based particle counter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Optics | Captive supply of photodetector arrays insulates against Taiwan Strait logistics friction. |
| Continuous Monitoring Platform Launch | Cloud-native architectures capture pharmaceutical cleanroom rotation from quarterly audits. |
| ISO 8573 Validation Tool Expansion | European food and beverage lag presents first-mover consolidation opportunity. |
| Factory-Trained Technician Network Extension | Czech and Polish clusters lack accredited calibration infrastructure for EU Green Deal compliance. |
| Interoperability Certification Investment | Multi-site pharmaceutical contract manufacturers demand cross-brand equipment compatibility. |
Study Parameters
The analysis maps gas analyzers, particulate counters, air flow meters, and pressure sensors, each validated through maintenance directors at pharmaceutical manufacturing facilities, calibration laboratory managers, automotive OEM procurement teams, and semiconductor fab facilities engineers. Primary interview insights triangulate against FDA 483 inspection observations, EU Green Deal implementation guidance, ISO 8573 certification databases, and compressor OEM service contract disclosures. Bottom-up equipment shipment tracking reconciles with top-down industrial compressed air system installation estimates.
Consistency checks validate volume and value outputs against semiconductor fab capital expenditure patterns, pharmaceutical manufacturing construction permits, and automotive supplier network certification audits across the projection horizon. Segmentation dimensions model product type, technology modality, end-user facility category, and application maturity. CAGRs derive from equipment replacement cycle compression rates and regulatory mandate implementation timelines, with laser-based technology penetration curves and continuous monitoring protocol adoption rates as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA sterility guideline enforcement and stable Taiwan-South Korea photodetector supply; material deviation in either would warrant model refresh. Semiconductor yield loss events accelerating or trade lane disruptions intensifying represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Noise Control System Market
Environmental Safety
Europe Process Safety Services Market