
 China Home Decontamination Services Market | 2026-2036
China Home Decontamination Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Home Decontamination Services Market Insights
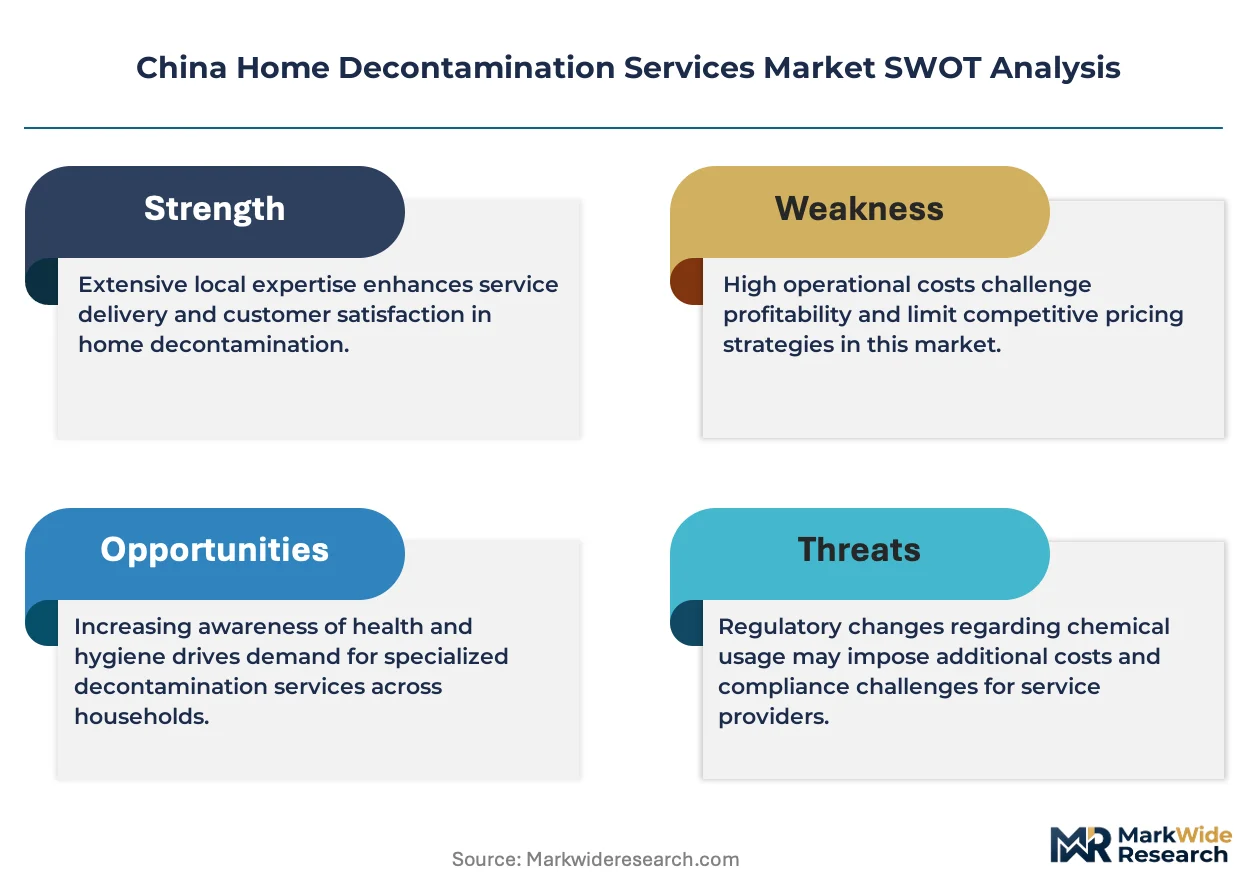
Guangdong Province is fragmenting as new decontamination service entrants crowd the Pearl River Delta manufacturing corridor. Shenzhen Zhongjia Daojia Housekeeping Group Co., Ltd. leverages its home-city logistics network to control same-day scheduling density across residential towers. Guangzhou Blue Moon Industry Co., Ltd. anchors chemical supply backward into its own formulation plants, reducing third-party fogging agent costs. Shanghai Aijun Family Services Co., Ltd. competes through bundled housekeeping-plus-decontamination subscriptions in high-rise compounds.
China home decontamination services encompass professional indoor environmental remediation using certified biocides, HEPA filtration systems, and thermal or UV-C delivery equipment to eliminate pathogens, mold colonies, and airborne contaminants from enclosed living spaces. Service crews typically apply chlorine dioxide or quaternary ammonium compounds at concentrations calibrated to GB/T 18883 indoor air quality thresholds while documenting particulate reduction below 150 μg/m³ PM10 for residential clearance. Disinfection and sanitization dominate current revenue as property managers prioritize post-occupancy clearance protocols, whereas mold remediation captures expanding margin pools in southern China's subtropical humidity belt. UV-C light technology leads capital investment among premium providers, though electrostatic spraying sustains volume leadership through lower per-deployment labor requirements.
China's Ministry of Ecology and Environment enforces dual carbon goals that push service fleets toward electric vehicle conversions and low-VOC chemical formulations, while SAMR mandates GB standard compliance for all biocidal products deployed in residential settings. The National Health Commission's post-pandemic hygiene protocols permanently embedded recurring decontamination clauses into healthcare facility and educational institution service contracts. Stakeholders must monitor how provincial BIS-equivalent quality inspections tighten technician certification requirements before committing to multi-city expansion.
Market Dynamics
Property management outsourcing in the Yangtze River Delta is compressing procurement cycles and forcing service providers to absorb equipment capex upfront while competing on bundled subscription pricing.
Growth Catalysts
- Dual carbon goals:MEE mandates for electric fleet conversion and low-VOC formulations create compliance-driven replacement demand across legacy service operators.
- Post-pandemic hygiene protocols:The National Health Commission's recurring decontamination clauses permanently embed service contracts in healthcare and educational facilities.
- Subtropical humidity belt expansion:Southern China's climate intensification drives mold remediation demand beyond traditional disinfection services.
Market Restraints
- Biocide cost volatility:Quaternary ammonium compound and chlorine dioxide prices fluctuate with petrochemical feedstock exposure, squeezing per-deployment margins.
- Certification bottleneck:Provincial BIS-equivalent quality inspections tighten technician credential requirements, slowing multi-city expansion timelines.
- Electrostatic spraying substitution ceiling:UV-C technology captures premium positioning while lower-labor electrostatic methods dominate volume, capping price realization.
Strategic Opportunities
- GB/T 18883 compliance automation:Real-time particulate monitoring integration creates differentiated service tiers for high-rise residential compounds.
- Pearl River Delta fragmentation:New entrant crowding in Guangdong Province opens acquisition targets for operators with capital discipline.
- Healthcare facility specialization:Post-pandemic institutional protocols favor providers with dedicated HEPA filtration and thermal remediation equipment.
Industry Challenges
- Technician certification lag:Provincial inspection tightening outpaces training infrastructure, creating qualified crew shortages in secondary cities.
- Equipment integration complexity:UV-C capital deployment requires reconfiguration of legacy electrostatic workflows and scheduling density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Home Decontamination Services Market |
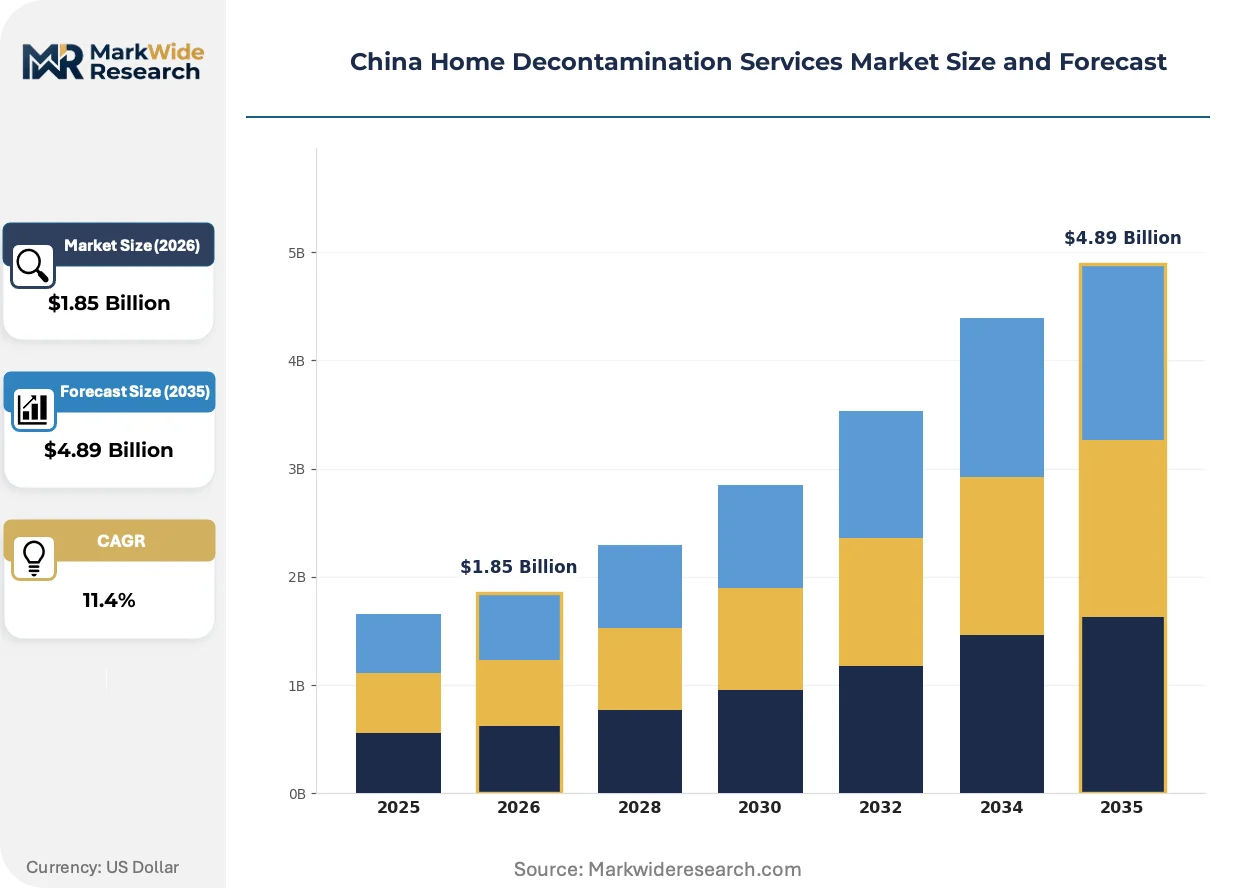
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Disinfection, Sanitization, Mold Remediation, Pest Control Technology: UV-C Light, Electrostatic Spraying, Steam Cleaning, Chemical Fogging End User: Residential, Commercial Buildings, Healthcare Facilities, Educational Institutions Application: Indoor Air Quality, Surface Treatment, Infection Prevention, Allergen Removal |
| Companies Covered | Shanghai Aijun Family Services Co., Ltd., Xiamen Small Yuja Housekeeping Co., Ltd., Shenzhen Zhongjia Daojia Housekeeping Group Co., Ltd., Dazhong Gongjiang, Guangzhou Liby Enterprise Group Co., Ltd., Guangzhou Blue Moon Industry Co., Ltd., Dongguan Ufine Daily Chemical Co., Ltd., Guangzhou Alice Daily Chemical Co., Ltd., Dongguan Quick Cleaner Daily Commodity Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Home Decontamination Services Market Trends and Innovations
Service delivery models are fragmenting across equipment-heavy premium tiers and labor-optimized volume plays, with digitized scheduling platforms compressing customer acquisition costs.
IoT-enabled air quality sensors are digitizing residential clearance protocols. Property managers in Shanghai high-rises deploy continuous PM10 monitoring to trigger automated service dispatch. This infrastructure is digitizing the traditional post-occupancy inspection model into subscription-based prevention contracts.
GB standards enforcement through SAMR is tightening biocide formulation disclosure requirements. Service providers must document active concentrations and application logs for residential deployments. The compliance burden falls heaviest on independent operators lacking captive chemical supply chains.
Subscription bundling is displacing transactional service procurement in tier-one residential compounds. Property management companies consolidate housekeeping and decontamination under single-vendor contracts to reduce vendor coordination overhead. This consolidation is most advanced in Beijing and Shanghai tower clusters with centralized procurement functions.
China Home Decontamination Services Market Segmentation
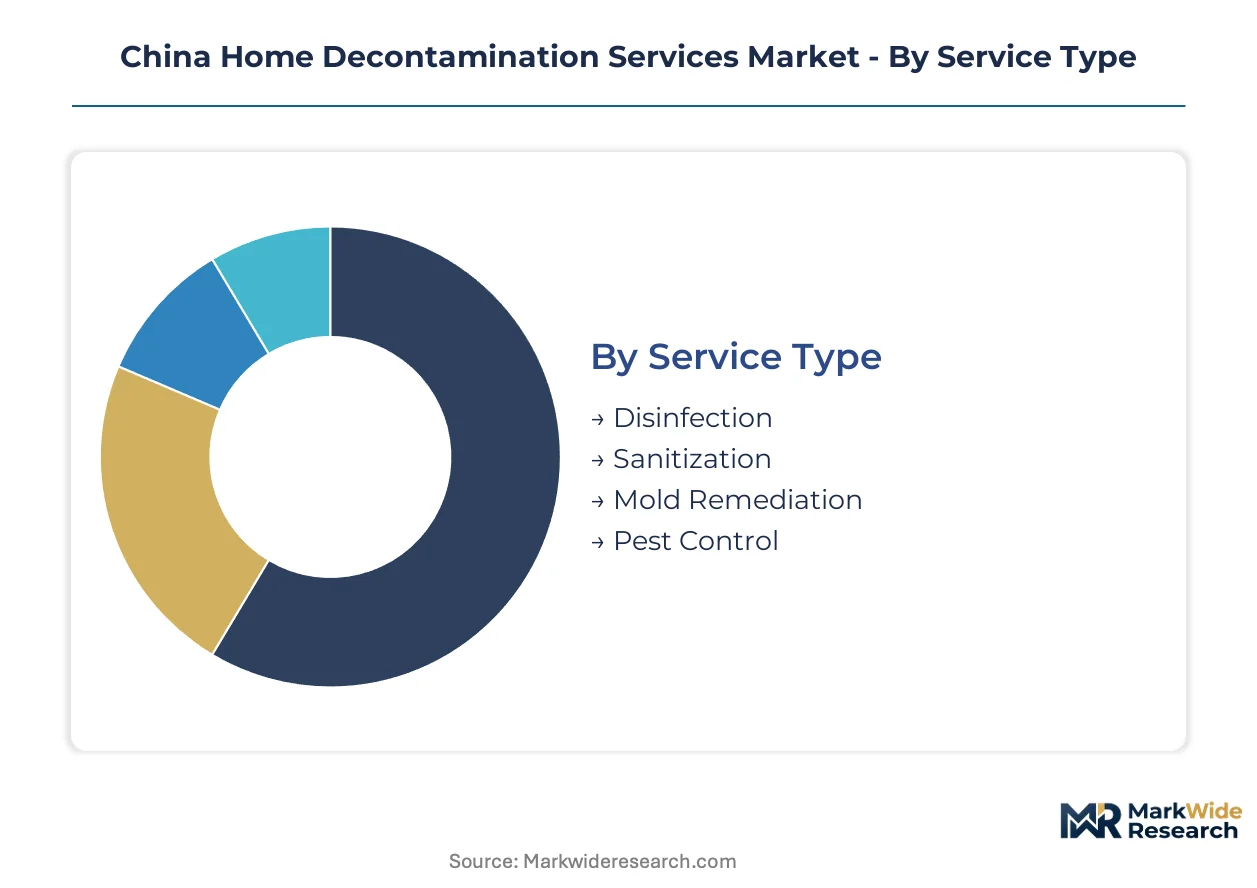
China's home decontamination market fragments across service delivery methods, equipment technologies, and institutional versus residential procurement patterns. Each segment carries distinct margin profiles and regulatory compliance burdens shaped by GB standards enforcement and MEE dual carbon mandates.
Service Type:
Mature disinfection protocols dominate established revenue streams while emerging specialty services capture premium positioning in climate-stressed geographies.
- Disinfection:Chlorine dioxide and quaternary ammonium compound applications at GB/T 18883-calibrated concentrations form the baseline residential clearance protocol. Shanghai and Beijing property managers embed recurring disinfection clauses into high-rise maintenance contracts as post-pandemic hygiene standards persist.
- Sanitization:Lower-concentration biocide treatments target routine maintenance rather than pathogen elimination events. Guangdong Province manufacturing corridor demand concentrates in Pearl River Delta worker dormitories where facility managers prioritize cost-per-square-meter over sterilization-grade outcomes.
- Mold Remediation:Southern China's subtropical humidity belt drives specialized crew deployment with HEPA containment and thermal drying equipment. Guangzhou and Shenzhen residential towers generate recurring moisture-damage contracts.
- Pest Control:Integrated vector management services merge with decontamination protocols in Yangtze River Delta agricultural interface zones.
Disinfection handles the majority of throughput; mold remediation is the fastest mover on share.
Technology:
Cost tiers separate capital-intensive premium equipment from labor-optimized volume deployment methods.
- UV-C Light:Ultraviolet-C germicidal irradiation systems deliver pathogen inactivation without chemical residue. Beijing healthcare facilities and premium Shanghai residential compounds absorb higher per-deployment costs for immediate reoccupancy clearance.
- Electrostatic Spraying:Charged particle application reduces biocide volume requirements and labor hours per square meter. Volume leadership in tier-two city residential contracts where property managers prioritize scheduling density.
- Steam Cleaning:Thermal remediation penetrates porous surfaces for allergen and dust mite elimination. Shenzhen childcare institutions specify steam protocols for chemical-sensitive environments.
- Chemical Fogging:Ultra-low volume aerosol dispersion dominates legacy operator fleets across inland provinces with lower equipment replacement rates.
Electrostatic spraying handles the majority of throughput; UV-C light is climbing the fastest on share.
End User:
Customer type stratification reflects procurement centralization versus fragmented individual decision-making.
- Residential:Individual household contracts concentrate in Beijing and Shanghai high-rises with centralized property management. Subscription bundling with housekeeping services reduces customer acquisition costs.
- Commercial Buildings:Office and retail property managers in Guangdong Province outsource decontamination alongside facilities management. Procurement cycles compress as landlord-tenant service charge structures evolve.
- Healthcare Facilities:National Health Commission post-pandemic protocols mandate dedicated HEPA filtration and thermal remediation equipment. Recurring service contracts embed permanently in hospital and clinic operating budgets.
- Educational Institutions:School districts in Yangtze River Delta cities specify GB-compliant clearance documentation for semester transitions.
Residential handles the majority of throughput; healthcare facilities are expanding most quickly on share.
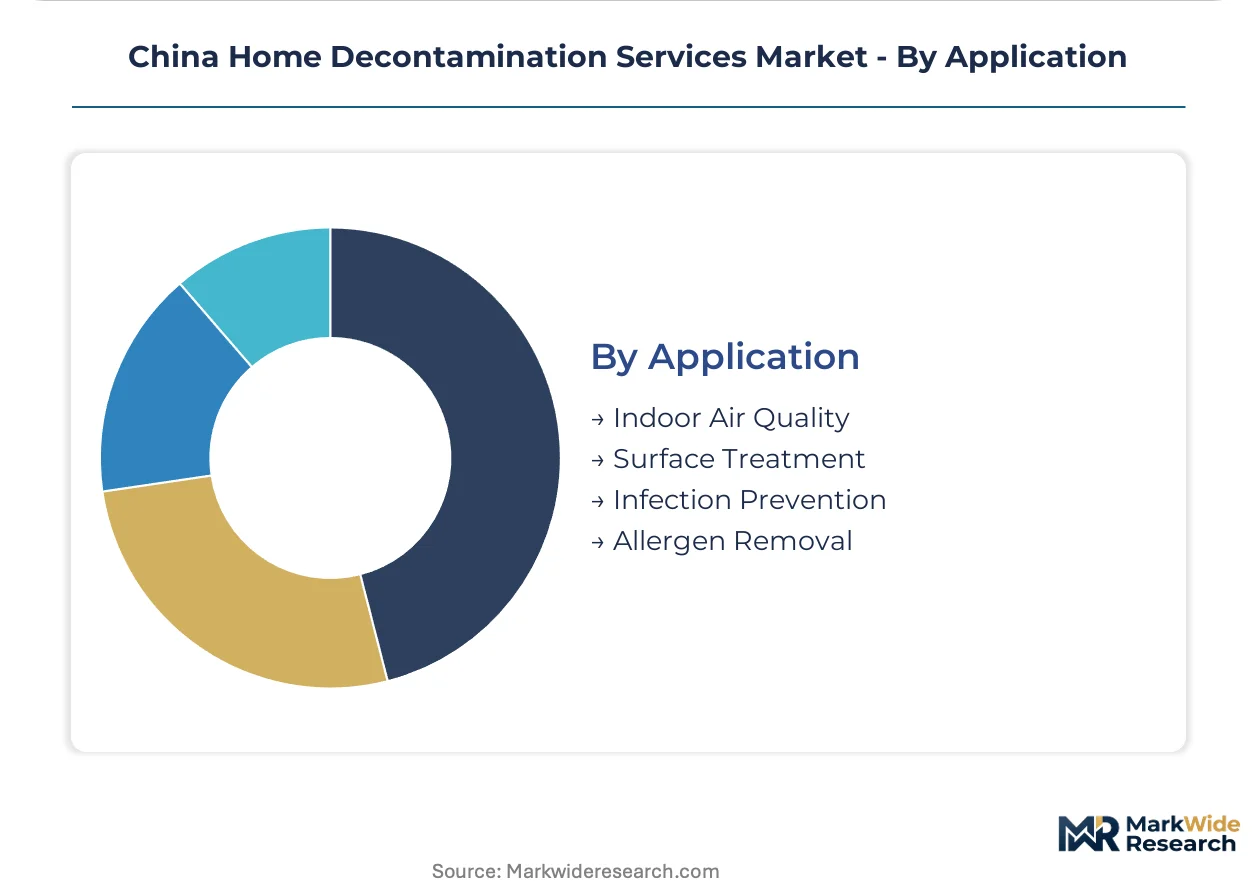
Application:
Application scope differentiates between preventive maintenance contracts and reactive remediation events.
- Indoor Air Quality:PM10 and PM2.5 reduction services integrate IoT sensor networks for automated dispatch triggering. Shanghai property managers deploy continuous monitoring infrastructure in premium tower clusters.
- Surface Treatment:High-touch point biocide application dominates high-traffic commercial settings. Electrostatic methods optimize labor deployment across large floorplates.
- Infection Prevention:Healthcare and educational institutional contracts specify outbreak-response protocols with documented clearance thresholds.
- Allergen Removal:Dust mite and pet dander remediation targets affluent residential segments with respiratory sensitivity concerns.
Surface treatment handles the majority of throughput; indoor air quality is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE dual carbon goals and GB standards enforcement anchor demand concentration in eastern China's megacity clusters. Provincial implementation varies by industrial density and property management maturity.
Yangtze River Delta
Shanghai high-rise compounds drive subscription bundling as property managers consolidate vendor contracts. SAMR biocide disclosure requirements tighten compliance documentation for residential deployments. Suzhou and Hangzhou satellite cities replicate Shanghai's centralized procurement models with lagging certification infrastructure.
Pearl River Delta
Shenzhen's logistics networks enable same-day scheduling density across residential towers. MEE electric fleet mandates accelerate equipment replacement among legacy operators. Guangzhou manufacturing corridor fragmentation creates acquisition opportunities as new entrants crowd chemical supply channels.
Beijing-Tianjin-Hebei
Healthcare facility contracts embed permanently under National Health Commission post-pandemic protocols. GB/T 18883 indoor air quality thresholds drive real-time monitoring adoption in premium compounds. Tianjin port access reduces imported HEPA equipment lead times for institutional buyers.
Sichuan-Chongqing
Western expansion lags technician certification infrastructure as provincial inspections tighten credential requirements. Chongqing's subtropical humidity drives mold remediation demand beyond baseline disinfection services. Chengdu property managers experiment with IoT-triggered dispatch models adapted from eastern coastal pilots.
China Home Decontamination Services Market Competitive Landscape
Capability concentration sits with chemical-integrated specialists; scale advantage sits with housekeeping-platform operators. The market structures around three tiers: captive supply chain owners, logistics-optimized schedulers, and equipment-heavy premium providers. Strategic moves cluster on backward integration into formulation plants and subscription bundling with property management contracts.
Within the chemical-integrated tier, Guangzhou Blue Moon Industry Co., Ltd. exemplifies backward control over biocide production. Shanghai Aijun Family Services Co., Ltd. and Shenzhen Zhongjia Daojia Housekeeping Group Co., Ltd. represent contrasting platform models—subscription bundling versus logistics density. These three anchors illustrate how competitive positioning diverges between supply chain captivity and service delivery optimization.
| Leading Market Players |
|---|
| Shanghai Aijun Family Services Co., Ltd. |
| Xiamen Small Yuja Housekeeping Co., Ltd. |
| Shenzhen Zhongjia Daojia Housekeeping Group Co., Ltd. |
| Dazhong Gongjiang |
| Guangzhou Liby Enterprise Group Co., Ltd. |
| Guangzhou Blue Moon Industry Co., Ltd. |
| Dongguan Ufine Daily Chemical Co., Ltd. |
| Guangzhou Alice Daily Chemical Co., Ltd. |
| Dongguan Quick Cleaner Daily Commodity Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Guangdong Province's chemical formulation plants compresses biocide margins while forcing service providers toward subscription bundling to escape commodity pricing traps. MEE dual carbon compliance costs and SAMR disclosure requirements layer onto input volatility, reshaping how operators structure procurement and customer contracts.
Pricing Analysis
Shanghai commands 35-40% premiums over inland tier-three cities for equivalent residential decontamination services. Three-tier pricing structure across premium, standard, and economy levels separates UV-C-equipped providers from electrostatic-spray volume operators and chemical-fogging legacy fleets. Cost compression in the standard tier intensifies because Pearl River Delta entrants crowd procurement channels with undifferentiated biocide applications. Healthcare facilities exhibit lowest price sensitivity due to National Health Commission mandate embedding; worker dormitories in manufacturing corridors show highest sensitivity to per-square-meter rates.
Supply Chain Analysis
Export-control restrictions on advanced UV-C lamp technology from Germany and Japan limit premium equipment flows into domestic service fleets. China, South Korea, and Taiwan concentrate HEPA filtration system manufacturing; chlorine dioxide precursors draw from domestic petrochemical corridors in Shandong and Jiangsu. Single-source vulnerability sits with quaternary ammonium compound supply from integrated chemical majors. Distribution runs through property management procurement platforms in tier-one cities and independent operator networks in western provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China home decontamination services function as a service-attach opportunity where recurring subscription revenue from IoT-enabled air quality monitoring expands faster than one-time disinfection deployments. Property management bundling accelerates this shift toward prevention-contract economics.
For Market Incumbents:Insulate margin pools by securing captive biocide formulation capacity before SAMR disclosure requirements tighten further. Shenzhen Zhongjia Daojia's logistics density model demonstrates how same-day scheduling infrastructure blocks price-driven challengers. Backward integration into chemical plants reduces feedstock exposure while creating compliance documentation advantages over independent operators lacking supply chain control.
For New Entrants and Emerging Players:Chongqing and Chengdu's certification infrastructure gaps represent the most penetrable entry point for operators willing to absorb technician training capex upfront. Mold remediation contracts in Sichuan's humidity-stressed residential towers offer specialty positioning away from disinfection commoditization. A go-to-market angle through IoT sensor deployment partnerships with property managers bypasses direct competition with established chemical-fogging fleets.
For Investors and Strategic Acquirers:Long-term, this sits as a compliance-utility play because GB standard enforcement and MEE carbon mandates permanently embed decontamination into building operations rather than discretionary maintenance budgets. Acquisition targets should screen for captive chemical supply or locked property management contracts rather than equipment-heavy asset bases. The signal to watch is provincial BIS-equivalent inspection timing—tightening credential requirements will force consolidation among unqualified independent operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biocide Formulation | Captive supply chains insulate margins from petrochemical volatility while satisfying SAMR disclosure mandates. |
| IoT Sensor Platform Deployment | Continuous PM10 monitoring transforms transactional disinfection into recurring prevention subscriptions in Shanghai high-rises. |
| Electric Fleet Conversion | MEE dual carbon compliance creates replacement demand that favors capitalized operators over legacy chemical-fogging fleets. |
| Healthcare Facility Specialization | National Health Commission protocols permanently embed service contracts requiring dedicated HEPA and thermal remediation equipment. |
| Pearl River Delta Acquisition Program | Fragmentation among Guangdong entrants creates targets for operators with disciplined certification infrastructure and capital reserves. |
Research Methodology
A spread of perspectives from service operations directors, property management procurement leads, chemical formulation plant managers, and SAMR compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, GB standards documentation, SEC filings of listed chemical suppliers, and MEE policy releases. Bottom-up service deployment modeling and top-down addressable market sizing were triangulated against equipment import records and property management outsourcing trend data.
Demand-supply balance framing anchored the projection methodology, with analytical framework approach across service type, technology tier, end-user segment, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from equipment replacement cycles, subscription contract renewal rates, and compliance-driven mandate expansion. Industry-specific forecast inputs included MEE electric fleet conversion timelines and provincial BIS-equivalent inspection rollout schedules.
Macroeconomic conditions sit as an overlay; deviation in property investment cycles, petrochemical feedstock pricing, or urban migration patterns would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Material shifts in GB standards revision timing or MEE carbon mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Environment Health & Safety Market