
 US Home Decontamination Services Market | 2026-2036
US Home Decontamination Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Decontamination Services Market Insights
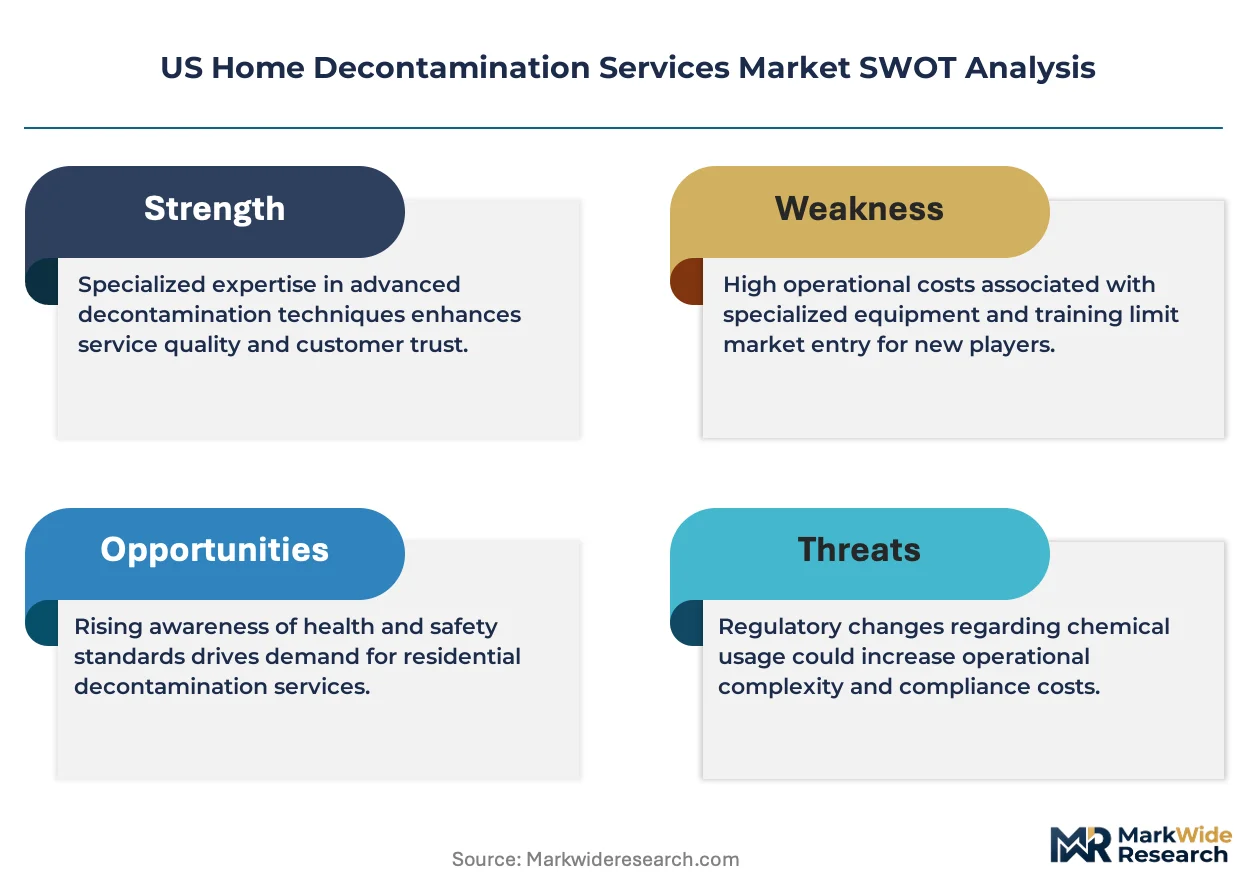
OSHA's enhanced respiratory protection standards for remediation workers is consolidating the cost-of-entry calculus, forcing independents to invest in certified equipment and training programs that erode thin margins. Servpro leverages its national franchise network and standardized protocols to sustain geographic dominance across catastrophe response and routine decontamination. Belfor anchors its position through vertical integration with property insurance carriers, streamlining claims-adjacent restoration workflows. PuroClean competes by specializing in rapid-response mold and biohazard protocols that differentiate its brand in high-anxiety customer moments.
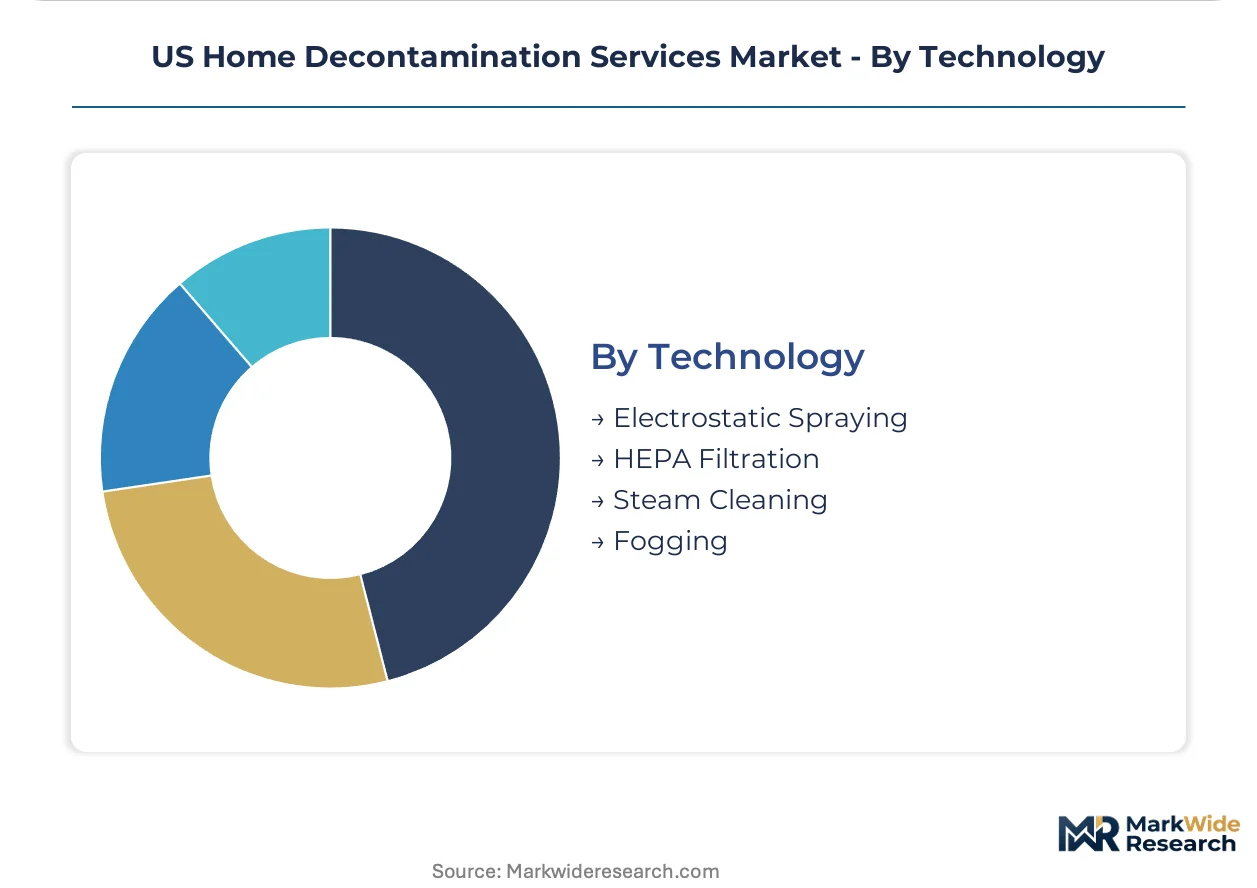
US Home Decontamination Services encompass professional remediation of biological, chemical, and particulate contaminants from residential structures using EPA-registered antimicrobial agents, HEPA containment systems, and thermal or oxidative treatment modalities. These services functionally restore indoor environmental quality to occupant-safe thresholds following water intrusion, pest infestation, infectious disease exposure, or allergen accumulation. Chemical treatment and UV sanitization command the largest revenue pools within service type segmentation due to established insurer reimbursement pathways and proven efficacy documentation. Electrostatic spraying and HEPA filtration technologies are capturing disproportionate growth within the technology dimension as property managers adopt hospital-grade protocols for multi-unit residential turnover.
EPA registration requirements under FIFRA, OSHA's mold remediation worker protection rules, and state-level contractor licensing boards collectively shape operational compliance burdens and liability exposure across the industry. The EPA's Safer Choice program and emerging state-level green chemistry mandates are redirecting procurement toward lower-toxicity antimicrobial formulations that meet dual efficacy and environmental release standards. Stakeholders must monitor evolving state insurance mandates linking decontamination certification to property policy renewals, as this regulatory vector threatens to fragment market access between certified and uncertified operators.
Market Dynamics
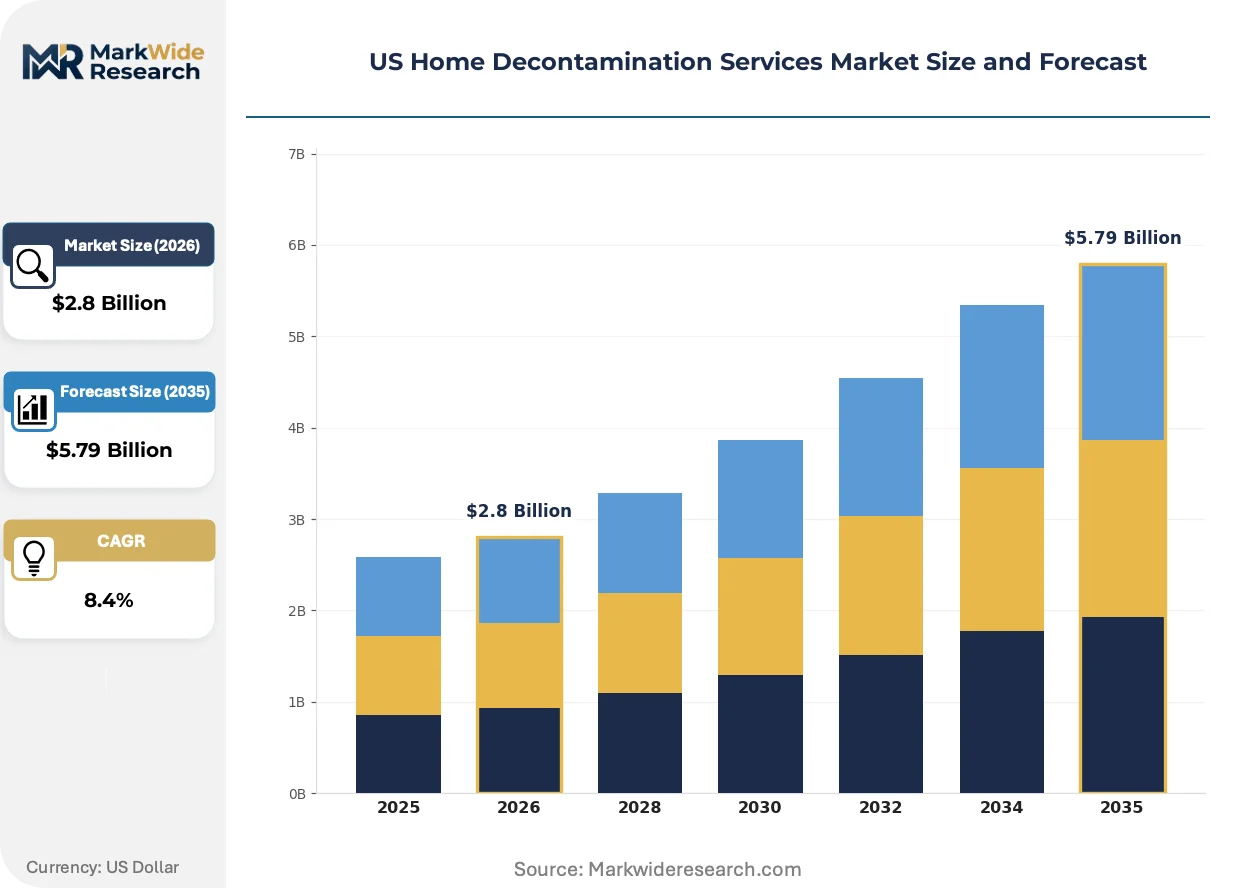
The US Home Decontamination Services Market is experiencing structural compression as EPA FIFRA registration requirements harden compliance thresholds, forcing capital-light independents toward franchise networks or exit while concentrating service provision among scaled operators with in-house regulatory affairs capabilities.
Growth Catalysts
- OSHA Respiratory Protection Mandates:Enhanced worker safety standards for mold remediation are accelerating professionalization, pushing uncertified operators out and expanding addressable market share for compliant service providers with certified equipment programs.
- Property Manager Protocol Hardening:Multi-unit residential turnover standards now embed hospital-grade decontamination as baseline expectation, creating recurring revenue streams distinct from one-time catastrophe response.
- Sun Belt Housing Expansion:Florida, Texas, and Arizona humidity-driven mold incidence intersects with rapid residential construction, concentrating demand geography where service density remains below saturation thresholds.
Market Restraints
- EPA Registration Cost Escalation:FIFRA antimicrobial pesticide compliance timelines and testing burdens have extended to 36-48 months for novel formulations, freezing innovation pipelines for smaller chemistry suppliers.
- Equipment Capital Intensity:HEPA containment systems, thermal oxidation units, and electrostatic spraying infrastructure require six-figure outlays that erode margins for operators serving sub-metro markets.
- Insurer Reimbursement Pathway Concentration:Claims-adjacent restoration workflows remain controlled by vertically integrated national networks, limiting independent access to the largest predictable revenue pool.
Strategic Opportunities
- Green Chemistry Procurement Mandates:EPA Safer Choice program alignment and emerging state-level environmental release standards are creating first-mover advantage for operators with lower-toxicity antimicrobial portfolios.
- Electrostatic-HEPA Convergence:Property managers in high-turnover multifamily assets are adopting combined application technologies that reduce labor hours per unit, opening technology licensing and training revenue streams.
- State Insurance Certification Linkage:Decontamination certification requirements tied to property policy renewals in select states threaten to fragment market access, rewarding early certifiers with protected territory status.
Industry Challenges
- Certified Technician Pipeline Scarcity:Mold remediation worker training programs and respiratory protection medical clearance protocols create 90-120 day onboarding friction that constrains expansion velocity.
- Multi-Jurisdiction Licensing Complexity:State contractor boards, EPA region-specific enforcement variations, and municipal biohazard transport permits generate compliance overhead that scales non-linearly with geographic footprint.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Decontamination Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Chemical Treatment, UV Sanitization, Thermal Remediation, Ozone Treatment End User: Residential Homes, Property Managers, Real Estate Agents, Cleaning Companies Application: Mold Remediation, Pest Control, Disinfection Services, Allergen Removal Technology: Electrostatic Spraying, HEPA Filtration, Steam Cleaning, Fogging |
| Companies Covered | Servpro, Belfor, PuroClean, ServiceMaster Restore, Stanley Steemer, Rainbow International, Paul Davis Restoration, Terminix Global Holdings, Rentokil Initial, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Decontamination Services Market Trends and Innovations
Technology convergence between established chemical treatment modalities and emerging physical decontamination systems is reconfiguring service delivery economics, while regulatory pressure and buyer professionalization reshape competitive positioning across the US market.
Electrostatic spraying technology is converging with HEPA filtration systems in integrated application platforms that reduce particle dispersion during antimicrobial deployment. Property management firms operating portfolios exceeding 500 units are piloting these combined systems for unit-turn decontamination, compressing service time per apartment by 40% while elevating documentation standards for liability defense.
EPA FIFRA registration requirements for antimicrobial pesticides have tightened efficacy documentation thresholds, extending review timelines and elevating compliance costs for novel active ingredients. Formulation suppliers are responding by redirecting R&D toward existing registered actives with expanded label claims, concentrating innovation around delivery mechanism refinement rather than chemistry breakthrough.
Residential property managers are consolidating vendor relationships around national service networks with standardized reporting protocols and centralized billing, displacing the fragmented local operator model that dominated pre-pandemic procurement. This concentration is most visible in Sun Belt metropolitan markets where institutional ownership of multifamily assets exceeds 35% and operating partners demand portfolio-level service agreements with uniform SLA documentation.
US Home Decontamination Services Market Segmentation
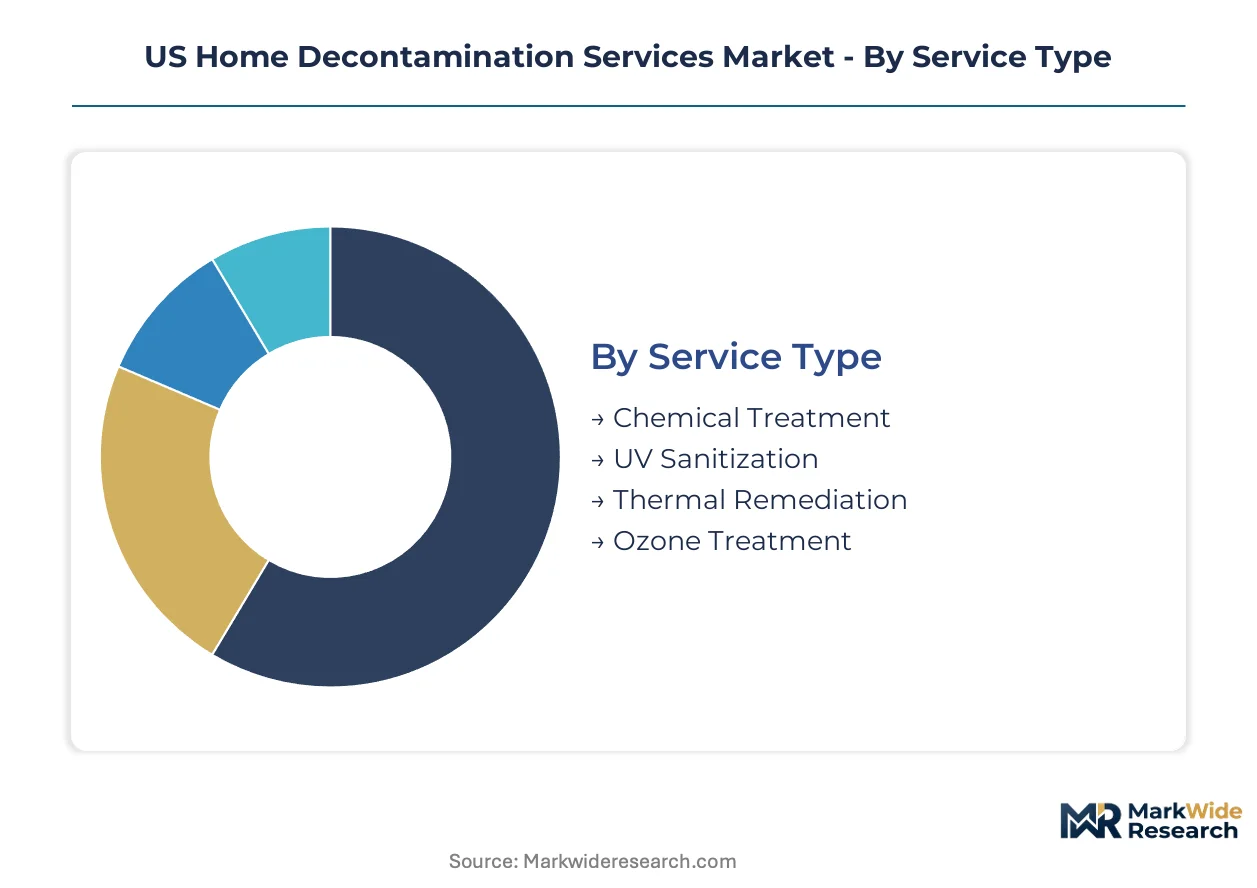
Service differentiation in US Home Decontamination Services hinges on technology modality, end-user procurement patterns, and application-specific efficacy requirements. Understanding segment boundaries reveals where capital investment concentrates and where margin compression threatens operator viability.
Service Type:
Technology modality determines equipment capital requirements, regulatory exposure under EPA FIFRA, and insurer reimbursement eligibility.
- Chemical Treatment:EPA-registered antimicrobial formulations delivered via spray or wipe application dominate revenue pools due to established efficacy documentation and insurer reimbursement pathways. Demand concentrates among property managers in Florida and Texas multi-unit portfolios where humidity-driven mold protocols require rapid turnaround with liability-grade documentation.
- UV Sanitization:Ultraviolet-C irradiation systems target surface and airborne pathogen neutralization without chemical residue, attracting residential homes with occupant sensitivities and post-infectious disease clearance requirements. Arizona retirement communities and assisted living transitions represent concentrated demand geography.
- Thermal Remediation:Heat-based decontamination elevates ambient temperatures to pathogen-lethal thresholds for bed bug eradication and deep structural sanitization.
- Ozone Treatment:Oxidative gas deployment penetrates porous materials for odor elimination and microbial reduction in unoccupied spaces.
Chemical Treatment leads on scale; UV Sanitization leads on momentum.
End User:
Procurement sophistication and contract structure vary sharply across buyer types, reshaping service delivery economics and customer acquisition costs.
- Property Managers:Institutional multifamily operators with 500-plus unit portfolios drive the steepest expansion trajectory through standardized turnover protocols and centralized vendor consolidation. Sun Belt metropolitan markets with institutional ownership exceeding 35% concentrate demand for portfolio-level service agreements with uniform SLA documentation.
- Residential Homes:Single-family owner-occupants purchase discrete event-driven services following water intrusion, infectious disease exposure, or allergen crises. Texas Gulf Coast hurricane corridors and Florida coastal counties generate geographically concentrated catastrophe-response demand.
- Real Estate Agents:Transaction-velocity professionals procure pre-listing sanitization and disclosure-grade documentation to accelerate closing timelines.
- Cleaning Companies:Commercial janitorial operators extend service portfolios through subcontracted decontamination certification or direct capability acquisition.
Property Managers command volume concentration; Residential Homes anchor revenue stability.
Application:
Contaminant category dictates containment complexity, worker protection requirements under OSHA, and liability exposure severity.
- Mold Remediation:Fungal colonization following water intrusion requires HEPA containment, negative air pressure engineering, and respiratory protection protocols. Florida's year-round humidity and Texas flash-flood corridors sustain persistent demand geography where service density remains below saturation.
- Disinfection Services:Pathogen-targeted surface and airborne treatment spans routine maintenance and acute outbreak response. Post-pandemic protocol hardening among Arizona healthcare-adjacent residential facilities sustains recurring revenue streams.
- Pest Control:Integrated pest management with decontamination components addresses allergen and pathogen vectors from rodent or insect infestation.
- Allergen Removal:Pet dander, dust mite, and pollen mitigation targets respiratory-sensitive occupants through HEPA extraction and source elimination.
Mold Remediation leads on scale; Disinfection Services leads on momentum.
Technology:
Application hardware determines labor productivity, documentation fidelity, and differentiation against commodity competitors.
- HEPA Filtration:High-efficiency particulate air containment and extraction systems form the engineering backbone of mold remediation and allergen removal, with equipment capital intensity creating six-figure barriers to compliant market entry. Property manager adoption of hospital-grade protocols for multi-unit turnover sustains equipment upgrade cycles.
- Electrostatic Spraying:Charged-particle application technology reduces chemical consumption and improves surface coverage uniformity, compressing service time per unit by approximately 40% in pilot deployments across Sun Belt multifamily portfolios.
- Steam Cleaning:Saturated vapor thermal delivery penetrates porous materials for chemical-free sanitization in sensitive-occupant environments.
- Fogging:Ultrasonic or thermal aerosol generation achieves space-filling distribution for unoccupied-area treatment.
HEPA Filtration leads on scale; Electrostatic Spraying leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified mold remediation technicians concentrate in Sun Belt metropolitan corridors where humidity-driven contamination intersects with institutional multifamily expansion.
Florida
Year-round humidity sustains persistent mold colonization risk across Tampa Bay and South Florida corridors. The Florida Department of Business and Professional Regulation enforces contractor licensing through the Construction Industry Licensing Board, mandating continuing education for mold assessors and remediators. Orlando's institutional multifamily operators now require portfolio-level decontamination SLAs with uniform documentation standards.
Texas
Hurricane-driven water intrusion along the Gulf Coast generates acute remediation demand alongside routine humidity protocols in Houston and Dallas-Fort Worth. The Texas Department of Licensing and Regulation administers mold assessor and remediator certifications with reciprocity limitations for out-of-state operators. Austin's technology sector migration has compressed apartment turnover cycles, elevating hospital-grade decontamination to baseline expectation among property managers.
Arizona
Dust-driven allergen accumulation and retirement community density sustain specialized disinfection demand in Phoenix and Tucson metropolitan areas. The Arizona Department of Health Services coordinates with county environmental health divisions on indoor air quality complaint response protocols. Scottsdale's assisted living transition corridors concentrate UV sanitization deployment for pathogen-sensitive occupant environments.
California
Wildfire smoke particulate infiltration and coastal moisture zones drive dual-contaminant remediation expertise in Los Angeles and San Francisco Bay Area markets. The California Department of Public Health maintains indoor air quality guidelines that exceed federal baselines, particularly for sensitive-occupant facilities. San Diego's military housing privatization has standardized decontamination protocols across defense-adjacent residential portfolios.
Georgia
Atlanta's institutional multifamily ownership concentration and subtropical humidity sustain recurring mold protocol demand across the metro's northern arc. The Georgia Department of Community Affairs administers contractor licensing with mold-specific endorsement requirements added in recent code revisions. Savannah's historic housing stock and tourism rental conversion create specialized lead-safe decontamination intersections with antimicrobial treatment.
US Home Decontamination Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service modalities, creating a tiered structure where national networks capture insurer-adjacent workflows while regional operators defend local catastrophe response relationships. The market consolidates around three strategic archetypes: franchise-anchored national networks with standardized protocols, insurance-vertically integrated restoration platforms, and rapid-response mold and biohazard specialists. Competitive maneuvering concentrates on geographic expansion through franchise development and technology licensing for combined electrostatic-HEPA application systems.
Within the national network tier, Servpro, Belfor, and PuroClean occupy positions that exemplify divergent specialization strategies. Servpro represents the franchise-scaling archetype with standardized catastrophe response protocols. Belfor anchors the insurance-integrated restoration workflow model. PuroClean exemplifies rapid-response specialization in high-anxiety contamination events.
| Leading Market Players |
|---|
| Servpro |
| Belfor |
| PuroClean |
| ServiceMaster Restore |
| Stanley Steemer |
| Rainbow International |
| Paul Davis Restoration |
| Terminix Global Holdings |
| Rentokil Initial |
| Others |
Pricing and Supply Chain Analysis
EPA Safer Choice program alignment gates qualified supply for premium-tier antimicrobial formulations while concentrating procurement power among operators with documented lower-toxicity portfolios. This environmental mandate bifurcates vendor access between certified and uncertified chemistry suppliers, elevating pricing power for compliant service networks.
Pricing Analysis
The bundled-vs-unbundled service split separates portfolio-level property management contracts from discrete residential event response. Pricing stratifies across premium, standard, and economy tiers based on EPA FIFRA registration tier and OSHA respiratory protection certification level. Cost compression in the standard tier is intensifying because equipment capital intensity erodes margins for sub-metro operators. Residential home buyers demonstrate highest price sensitivity while institutional property managers accept premium pricing for liability-grade documentation.
Supply Chain Analysis
Freight cost volatility for EPA-registered antimicrobial concentrates amplifies margin pressure on regional operators distant from formulation blending hubs. Active ingredient supply concentrates in China, India, and domestic specialty chemical corridors. Raw material dependencies include quaternary ammonium compounds, hydrogen peroxide precursors, and HEPA filtration media. Single-source vulnerability pervades electrostatic spraying equipment components. Distribution runs through national franchise networks and insurance-vertically integrated restoration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Home Decontamination Services Market functions as a stable compounder where post-pandemic hygiene protocol hardening sustains recurring revenue visibility across property management portfolios.
For Market Incumbents: Lock in property manager relationships through portfolio-level SLAs with standardized electrostatic-HEPA documentation protocols. Deepen backward integration into EPA-registered antimicrobial formulation supply to defend margin position against FIFRA compliance cost escalation. Acquire certified technician training capabilities to constrain expansion velocity for emerging competitors. For New Entrants and Emerging Players: Begin with rapid-response mold specialization in Sun Belt sub-metros where service density remains below saturation. Target Arizona retirement community corridors for UV sanitization deployment where institutional ownership concentration is nascent. Partner with regional insurance adjusters for claims-adjacent workflow access. For Investors and Strategic Acquirers: Roll-up economics work for regional mold remediation specialists because multi-jurisdiction licensing complexity creates fragmentation that scaled platforms can consolidate. The acquisition target archetype combines EPA FIFRA compliance infrastructure with concentrated Sun Belt geographic presence. Watch for state insurance certification linkage mandates as inflection indicator for protected territory value accretion.| Strategic Initiative | Industry Significance |
|---|---|
| Electrostatic-HEPA Technology Licensing | Property managers in 500-plus unit portfolios demand 40% faster unit-turn protocols with liability documentation. |
| EPA Safer Choice Portfolio Certification | Green chemistry procurement mandates redirect volume toward lower-toxicity antimicrobial formulations. |
| Certified Technician Training Program | OSHA respiratory protection medical clearance protocols create 90-120 day onboarding friction that constrains rival expansion. |
| Insurance Carrier Vertical Integration | Claims-adjacent restoration workflows concentrate predictable revenue pools within integrated national networks. |
| Sun Belt Franchise Territory Expansion | Florida, Texas, and Arizona humidity-driven demand intersects with rapid housing construction below service saturation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with remediation company executives, property management procurement directors, EPA regulatory affairs specialists, and insurance claims adjusters with secondary validation through EPA FIFRA registration databases, OSHA enforcement records, state contractor licensing board filings, and multifamily industry trade association reports. Bottom-up service provider revenue estimates and top-down addressable market calculations were cross-referenced for triangulation.
Comparable historical periods anchored growth trajectory assumptions across the projection horizon. The analytical framework modeled service type, end user procurement pattern, application contaminant category, and technology modality dimensions alongside regional housing stock growth and humidity-driven mold incidence patterns. CAGRs were derived from segment-level demand elasticity analysis and equipment capital intensity thresholds. Forecast inputs included EPA registration timeline delays and property manager protocol standardization velocity.
Caveats apply where EPA FIFRA registration requirement shifts or state insurance certification linkage mandates could materially shift the outlook. Forecasts reflect assumptions about technician pipeline development and institutional multifamily ownership concentration trajectories. A model refresh is warranted upon material change in OSHA respiratory protection standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Noise Control System Market
Environmental Safety
Industrial Noise Control Market