
 Home Decontamination Services Market | 2026-2036
Home Decontamination Services Market Size, Share, and Industry Trends Forecast 2026-2036
Home Decontamination Services Market Foresight
Modular service bundling is restructuring buyer choice in residential decontamination, as providers combine standalone disinfection with preventive maintenance contracts rather than one-time remediation. Servpro leverages its national franchise network to sustain rapid mobilization capacity after catastrophic events. Rentokil Initial plc anchors its portfolio through integrated pest management and hygiene services that reduce customer churn. Stanley Steemer competes on brand recognition and residential channel control, extending its carpet-cleaning customer base into microbial remediation.
Home decontamination services encompass professional remediation of biological, chemical, and particulate contaminants from residential structures using HEPA filtration, EPA-registered biocides, and thermal oxidation processes achieving log-6 pathogen reduction. These services restore habitability after infectious disease exposure, water intrusion, or fire damage while documenting compliance with insurer and landlord requirements. Chemical cleaning and fogging applications dominate current revenue as established protocols, while UV sterilization and electrostatic spraying represent the fastest-expanding technology segments as equipment costs decline and efficacy validation improves. Residential homeowners constitute the largest end-user pool, though property managers generate superior margins through recurring portfolio contracts.
EPA registration requirements under FIFRA govern biocide selection and application protocols, while OSHA's bloodborne pathogen standard mandates worker protection during biohazard remediation. State-level contractor licensing boards in Florida, Texas, and California impose supplemental certification requirements that shape market entry barriers. Stakeholders must monitor evolving federal guidance on antimicrobial resistance and emerging pathogen designation, as these frameworks will determine which technologies retain regulatory approval and reimbursement eligibility.
Market Dynamics
Permanent post-pandemic hygiene protocols in healthcare facilities and senior living communities are hardening into operational standards that require recurring professional decontamination rather than one-time remediation, reshaping contract structures toward preventive maintenance bundles.
Growth Catalysts
- EPA Emerging Contaminant Guidelines:Federal designation of new biohazards is expanding reimbursable service categories and forcing facility upgrades.
- UV-C LED Sterilization:Declining equipment costs and improved efficacy validation are accelerating adoption in residential and commercial contracts.
- Sun Belt Climate Events:Recurring mold and water damage in Florida, Texas, and Arizona metropolitan areas sustains recurring decontamination demand.
Market Restraints
- Biocide Input Volatility:EPA-registered antimicrobial chemical costs fluctuate with petrochemical feedstock prices and registration renewal timelines.
- Certification Concentration Risk:IICRC and RIA credentialing bodies control technician qualification pathways, creating bottleneck risk for labor supply.
- DIY Fogging Substitution:Consumer-grade electrostatic sprayers and ozone generators threaten low-complexity residential disinfection contracts.
Strategic Opportunities
- Integrated Pest Management Convergence:Bundling decontamination with pest control services reduces customer churn and raises contract values.
- Property Manager Channel Expansion:Multi-unit residential portfolios offer recurring revenue through standardized microbial monitoring protocols.
- OSHA Bloodborne Pathogen Standard Expansion:Broadened worker protection mandates increase mandatory professional remediation scope in commercial settings.
Industry Challenges
- Technician Certification Backlogs:IICRC microbial remediation and biohazard recovery credentials require 80+ training hours, constraining workforce scaling.
- HEPA Filtration Capex Burden:Negative air machines and containment systems demand significant equipment investment for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Decontamination Services Market |
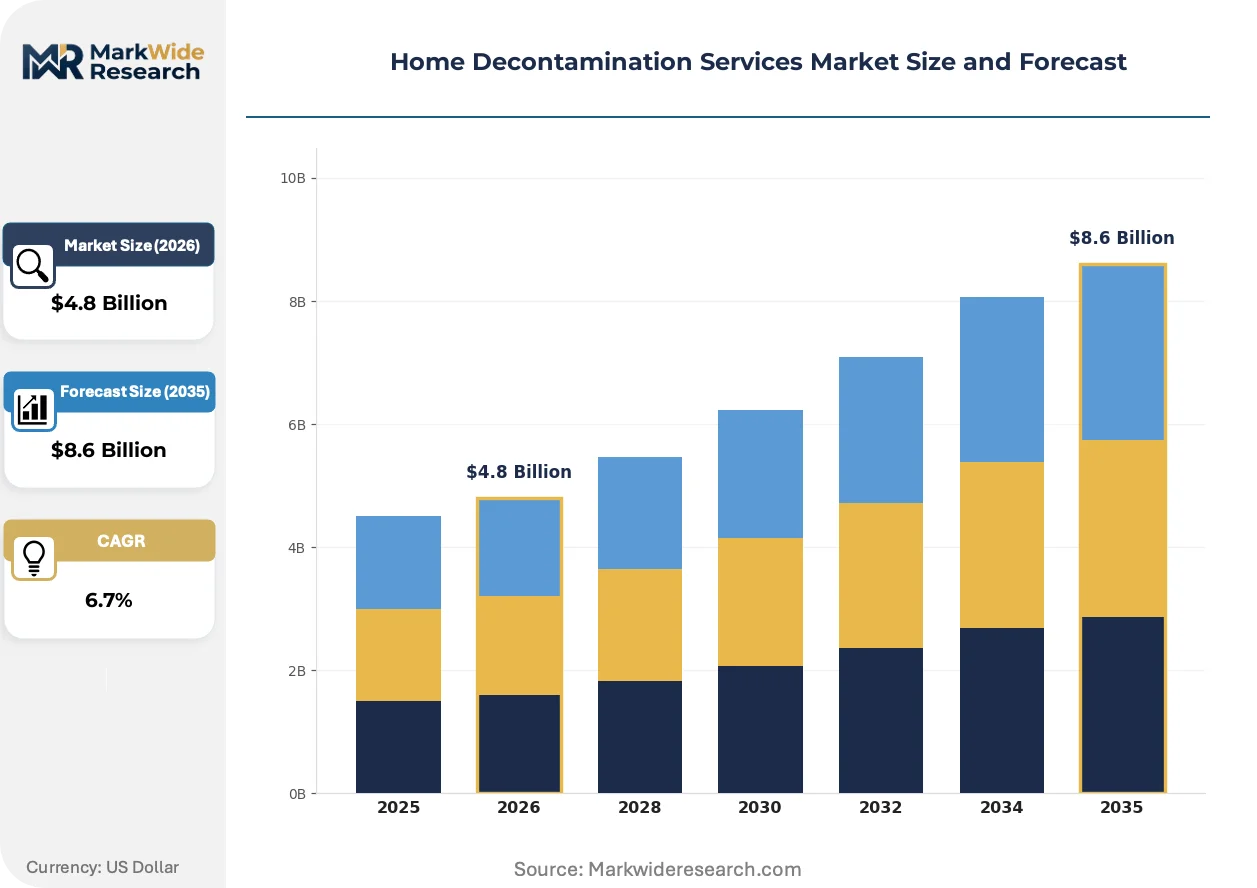
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Chemical Cleaning, HEPA Vacuuming, UV Sterilization, Fogging Technology: Electrostatic Spraying, Ozone Treatment, Thermal Fogging, Anti-Microbial Surface Coating End User: Residential Homeowners, Real Estate Agents, Property Managers, Cleaning Services Application: Post-Infection Cleanup, Pest Control, Fire Damage Restoration, Flood Damage Recovery |
| Companies Covered | Servpro, Belfor, Rentokil Initial plc, Stanley Steemer, Bio Decontamination Group Ltd., PuroClean, ServiceMaster Restore, Terminix Global Holdings, Inc., NYC Steam Cleaning, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Decontamination Services Market Shifts & Advancements
Service delivery models are fragmenting between rapid-response catastrophic event mobilization and embedded preventive maintenance contracts, with technology investment priorities diverging accordingly across provider types.
UV-C LED sterilization systems are consolidating technical specifications around 265-285 nanometer wavelength bands that optimize nucleic acid disruption while reducing mercury lamp disposal liabilities. Senior living operators and ambulatory surgery centers are adopting these systems for daily surface disinfection protocols. The technology is consolidating vendor bases by collapsing the distinction between equipment manufacturers and service providers into single-source accountability models.
REACH antimicrobial substance restrictions in the European Union are phasing out quaternary ammonium compounds in favor of peracetic acid and hydrogen peroxide-based alternatives with lower environmental persistence profiles. Biocide formulators are reformulating product lines to maintain CE marking compliance for cross-border service provision. Contract cleaning and restoration firms operating in Germany and France face accelerated retraining requirements for new application protocols.
Property managers are unbundling emergency remediation from routine microbial monitoring, creating separate procurement categories with distinct vendor qualification criteria. National multifamily REITs and institutional landlords are consolidating vendor panels to three preferred providers per metropolitan market. This concentration is most visible in Phoenix, Atlanta, and Dallas-Fort Worth where portfolio density supports dedicated service capacity commitments.
Home Decontamination Services Market Segmentation
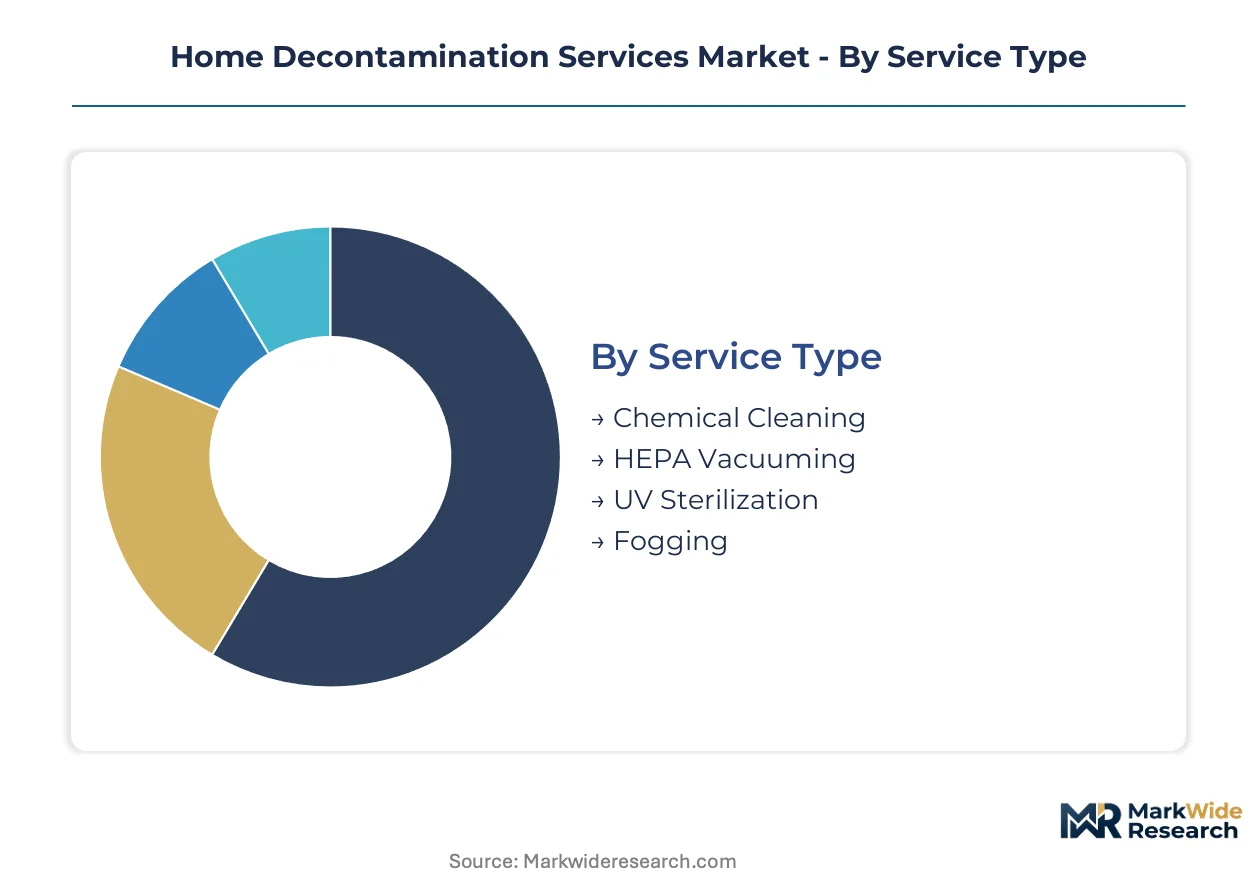
Home decontamination providers structure service portfolios around contamination severity, technology capital requirements, and contract recurrence patterns. Segmentation discipline separates emergency mobilization capabilities from preventive maintenance revenue streams.
Service Type:
Chemical cleaning and fogging applications command volume share through established protocols and lower equipment barriers. UV sterilization and HEPA vacuuming extract premium pricing from high-assurance environments.
- Chemical Cleaning:EPA-registered biocides applied through spray, wipe, or immersion protocols achieve log-4 to log-6 pathogen reduction on porous and non-porous surfaces. Demand concentrates in post-infection residential cleanup and flood damage recovery across Florida and Texas metropolitan markets where insurer documentation requirements mandate professional application.
- UV Sterilization:UV-C LED systems operating at 265-285 nanometer wavelengths disrupt nucleic acid bonds without residual chemical burden. Senior living communities and ambulatory surgery centers in Sun Belt states adopt these systems for daily surface protocols, displacing mercury lamp alternatives through reduced disposal liability and instant-on capability.
- HEPA Vacuuming:Negative air machines with 99.97% filtration efficiency at 0.3 microns capture particulate contaminants during mold remediation and fire damage restoration.
- Fogging:Aerosolized biocide delivery achieves uniform coverage in complex geometries including HVAC ductwork and crawl spaces.
Mature deployment sits with chemical cleaning. Newer deployment is concentrated in UV sterilization.
Technology:
Application method selection hinges on surface material compatibility, dwell time requirements, and re-entry interval constraints. Electrostatic spraying and anti-microbial coatings are gaining share in recurring maintenance contracts.
- Electrostatic Spraying:Charged particle deposition wraps conductive and non-conductive surfaces with uniform biocide film, reducing application time by 60% versus manual methods. Property managers in Phoenix and Atlanta metropolitan areas specify electrostatic protocols for multi-unit turnover cleaning, driven by resident turnover velocity and lease compliance documentation needs.
- Anti-Microbial Surface Coating:Persistent biocide films containing silver ion or quaternary ammonium compounds extend protection intervals to 30-90 days. Dallas-Fort Worth institutional landlords specify coating applications for high-touch surfaces in common areas, reducing emergency remediation frequency and insurance claim exposure.
- Ozone Treatment:Gaseous oxidation penetrates porous materials to neutralize odor compounds and biological contaminants without liquid residue.
- Thermal Fogging:Heated biocide aerosols achieve penetration equivalent to smoke particle distribution for fire damage odor neutralization.
Electrostatic spraying dominates new contract specifications. Thermal fogging remains anchored in fire restoration specialist workflows.
End User:
Residential homeowners generate transaction volume through one-time remediation events. Property managers and cleaning services produce recurring revenue through portfolio-scale contracts.
- Property Managers:Multi-unit residential operators consolidate vendor relationships to three preferred providers per metropolitan market, negotiating capacity commitments and standardized microbial monitoring protocols. Institutional REITs in Sun Belt markets extract volume pricing through dedicated service level agreements covering emergency response and preventive maintenance.
- Residential Homeowners:Individual property owners initiate decontamination services following infectious disease exposure, water intrusion, or insurer mandates, with price sensitivity highest in discretionary disinfection categories.
- Real Estate Agents:Pre-listing certification requirements in competitive housing markets drive mold and odor remediation prior to open house events.
- Cleaning Services:Janitorial contractors extend service portfolios into microbial remediation through sub-contractor relationships or technician cross-training.
Property managers command the steepest expansion trajectory. Residential homeowners anchor absolute transaction count.
Application:
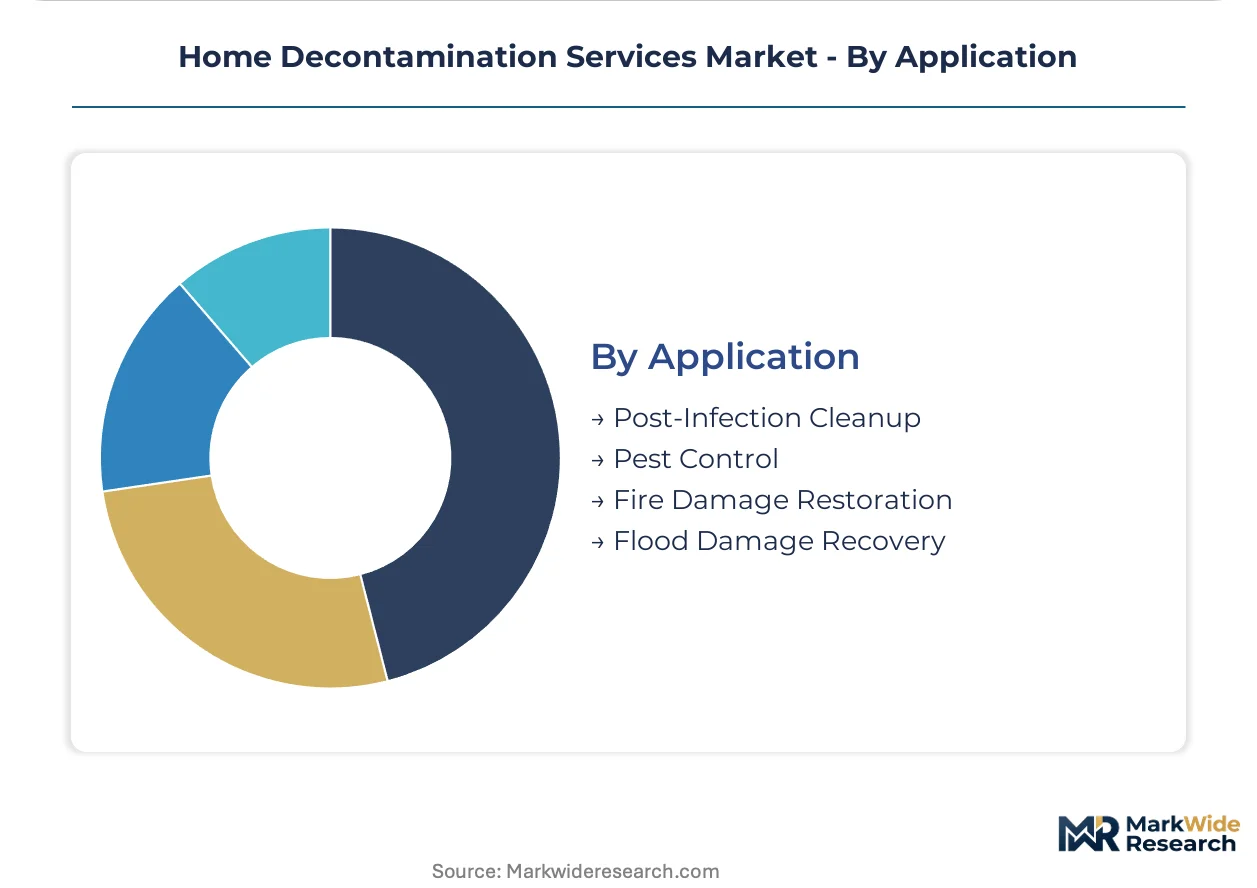
Climate-driven water damage and post-pandemic hygiene protocols are restructuring demand concentration across incident categories. Post-infection cleanup and flood recovery are expanding fastest.
- Post-Infection Cleanup:Professional remediation following confirmed pathogen exposure requires OSHA bloodborne pathogen standard compliance, HEPA containment, and waste stream documentation. Senior living communities and healthcare facilities mandate these services as permanent operational standards, generating recurring contract structures rather than one-time events.
- Flood Damage Recovery:Mold colonization within 24-48 hours of water intrusion drives emergency mobilization requirements in Florida, Louisiana, and Texas coastal markets. Climate intensification is compressing storm intervals and sustaining above-trend decontamination demand in Gulf Coast metropolitan areas.
- Fire Damage Restoration:Thermal degradation byproducts and smoke particulate removal requires combined chemical cleaning and thermal fogging protocols.
- Pest Control:Integrated pest management convergence bundles rodent and insect decontamination with exclusion services.
Fire damage restoration represents the most mature application category. Post-infection cleanup is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provision concentrates in consumption hubs where climate-driven damage and institutional hygiene mandates sustain recurring demand. Production of decontamination equipment and biocide formulations clusters separately from service delivery networks.
United States
Sun Belt metropolitan areas generate sustained demand from hurricane-driven water damage and mold colonization cycles. EPA registration requirements under FIFRA govern biocide selection and application protocols nationwide. Miami, Houston, and Phoenix anchor the largest service provider networks, with institutional landlords in these markets consolidating vendor panels to three preferred providers per metro area.
Germany
REACH antimicrobial substance restrictions are phasing out quaternary ammonium compounds in favor of peracetic acid alternatives. The country's national chemical regulator enforces accelerated retraining requirements for new application protocols. Berlin and Frankfurt service providers face reformulation mandates that reshape product lines for cross-border service provision.
United Kingdom
Healthcare facility privatization drives recurring decontamination contracts in senior living and ambulatory surgery segments. The Health and Safety Executive mandates worker protection standards during biohazard remediation. London and Birmingham concentrate the largest property management portfolios, with institutional REITs negotiating dedicated service level agreements.
Japan
Post-pandemic hygiene protocols in elder care facilities harden into permanent operational standards requiring daily surface disinfection. METI guidelines promote UV-C LED adoption to reduce mercury lamp disposal liabilities. Tokyo and Osaka metropolitan areas lead equipment installation rates for 265-285 nanometer wavelength sterilization systems.
Australia
Flood recovery cycles in eastern coastal states sustain emergency mobilization demand for mold remediation services. The national environmental regulator oversees antimicrobial chemical registration and environmental persistence standards. Sydney and Brisbane service providers maintain rapid-response capacity for compressed storm intervals driven by climate intensification.
Home Decontamination Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented service territories. National franchise networks sustain rapid mobilization capacity after catastrophic events, while integrated pest management providers reduce customer churn through bundled hygiene portfolios. Three strategic archetypes dominate: catastrophe-response mobilizers, preventive maintenance bundlers, and residential channel controllers. M&A activity concentrates on regional service roll-ups, while technology licensing partnerships accelerate UV-C LED deployment.
Within the catastrophe-response tier, Servpro leverages its national franchise infrastructure to anchor rapid mobilization positioning. Rentokil Initial plc exemplifies the integrated bundling archetype through its convergence of pest management and hygiene service lines. Stanley Steemer occupies a position within residential channel control, extending carpet-cleaning customer relationships into microbial remediation contracts.
| Leading Market Players |
|---|
| Servpro |
| Belfor |
| Rentokil Initial plc |
| Stanley Steemer |
| Bio Decontamination Group Ltd. |
| PuroClean |
| ServiceMaster Restore |
| Terminix Global Holdings, Inc. |
| NYC Steam Cleaning, Inc. |
| Others |
Supply & Pricing Matrix
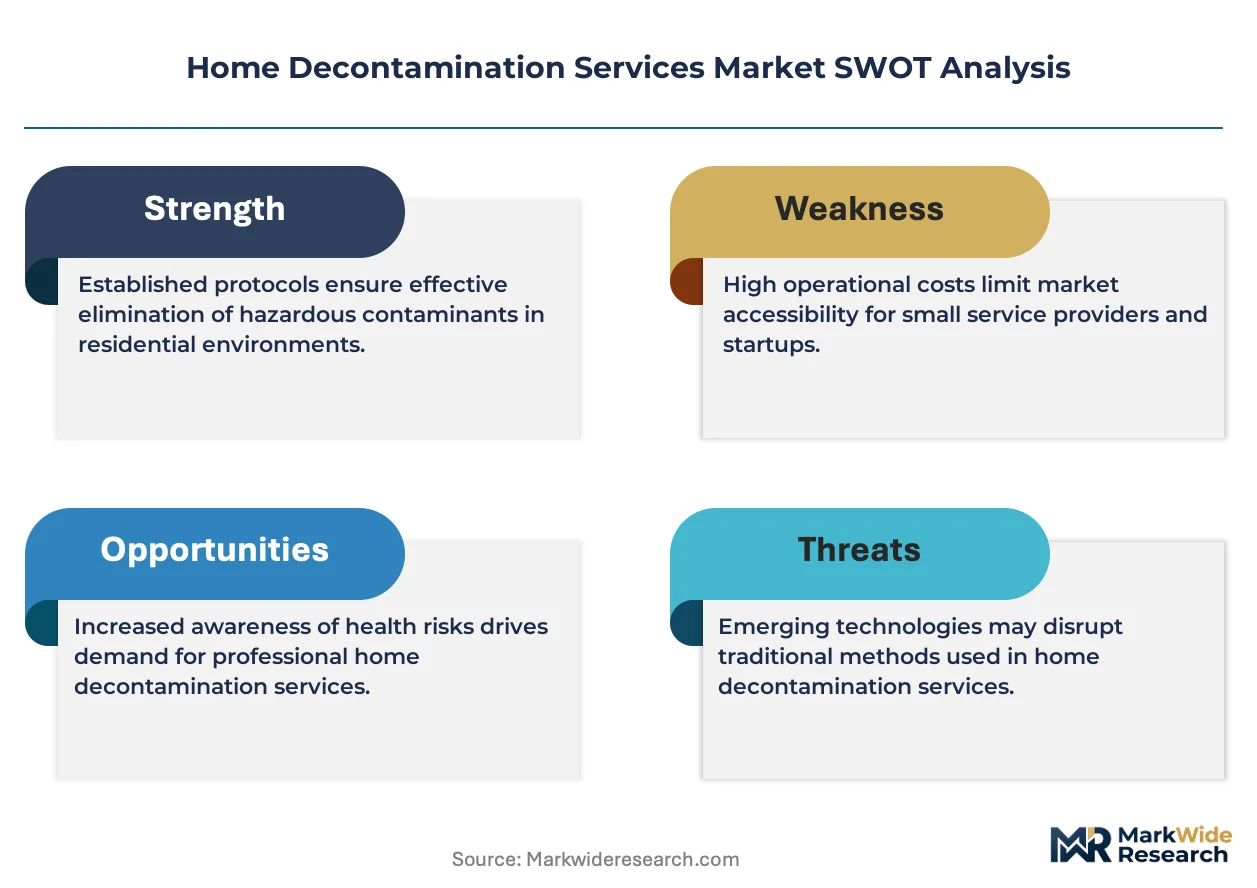
Captive in-house production of HEPA filtration equipment and negative air containment systems anchors pricing power for established providers, while outsourced biocide sourcing exposes smaller operators to petrochemical feedstock volatility that compresses margins during registration renewal cycles.
Pricing Analysis
Margin tightening in standard chemical cleaning reflects EPA registration fee escalations and quaternary ammonium compound reformulation costs. Three-tier pricing structure across premium UV-C LED protocols, standard HEPA remediation, and economy fogging applications separates certification-grade providers from uninsured contractors. Price differentiation hinges on IICRC credential tier and after-sales microbial monitoring bundling. Residential homeowners exhibit acute price sensitivity in discretionary disinfection, whereas institutional REITs absorb premium pricing for documented compliance.
Supply Chain Analysis
Domestic-content mandates in federal facility contracts are reshaping sourcing toward US-manufactured UV-C LED arrays and EPA-registered biocide formulators. Equipment production concentrates in the United States, Germany, and Japan, while antimicrobial chemical feedstocks draw from Chinese and Indian petrochemical bases. Supply chain risk centers on single-source vulnerability for 265-285 nanometer wavelength LED chips. Distribution runs through national franchise networks and direct property manager channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification backlogs and IICRC credential bottlenecks constrain workforce scaling, propping pricing power for incumbents with established training pipelines.
For Market Incumbents: Anchor rapid mobilization capacity through dedicated equipment reserves in hurricane-prone Sun Belt metros. Defend against DIY fogging substitution by bundling preventive maintenance contracts with emergency response SLAs. Deepen backward integration into UV-C LED equipment distribution to capture technology upgrade cycles. For New Entrants and Emerging Players: Small multifamily operators in secondary Sun Belt cities represent an underserved buyer archetype with fragmented vendor relationships. Target Phoenix and Atlanta exurban portfolios with electrostatic spraying protocols priced below national franchise rates. Pursue sub-contractor relationships with institutional cleaning services lacking microbial remediation credentials. For Investors and Strategic Acquirers: Exit pathways concentrate in regional service roll-ups to national franchise networks. Long-term viability favors providers with integrated pest management convergence and recurring revenue share above transactional cleanup. Monitor EPA emerging contaminant designation velocity as inflection indicator for reimbursable service category expansion.| Strategic Initiative | Industry Significance |
|---|---|
| UV-C LED Technology Licensing | Accelerates deployment of mercury-free sterilization systems in senior living facilities. |
| Regional Franchise Acquisition | Consolidates vendor panels in Dallas-Fort Worth and Phoenix metropolitan markets. |
| Integrated Pest Management Convergence | Reduces customer churn through bundled hygiene and exclusion service contracts. |
| Property Manager Channel Partnership | Locks recurring revenue via standardized microbial monitoring protocols. |
| Technician Certification Pipeline Investment | Alleviates IICRC credential bottlenecks constraining workforce scaling. |
Research Methodology
Document review covered EPA FIFRA registration databases, OSHA bloodborne pathogen compliance filings, and state contractor licensing board records, complemented by interviews with restoration firm operations directors, property management procurement leads, biocide formulation technical directors, and IICRC certification administrators. Secondary validation drew from insurer loss data, senior living operator facility spend disclosures, and customs records for decontamination equipment imports. Bottom-up service provider revenue estimates triangulated against top-down end-user expenditure surveys.
Segmented outputs across service type, technology application, end-user category, and geographic market cluster fed into the projection framework. CAGRs derived from historical demand elasticities mapped against climate event frequency trends and regulatory mandate adoption curves. UV-C LED cost decline trajectories and EPA emerging contaminant designation timelines served as technology and policy inputs.
Revisions become necessary when antimicrobial resistance designations alter biocide approval status or when climate intensification compresses storm intervals beyond modeled frequencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Noise Control System Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Industrial Noise Control Market