
 Europe Pest Control Services Market | 2026-2036
Europe Pest Control Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pest Control Services Market Insights
Remote sensor networks and predictive analytics are reshaping how pest control services are delivered across Europe, shifting providers from reactive treatments to continuous digital monitoring. Rentokil Initial leverages its connected pest management platform to sustain recurring revenue streams in commercial food service accounts. Anticimex anchors its Nordic dominance through in-house production of smart trapping hardware. Ecolab differentiates by controlling specialized protocols for pharmaceutical cleanroom environments.
Europe pest control services encompass systematic detection, elimination, and prevention of arthropod and rodent infestations using integrated pest management protocols that combine chemical, biological, and physical interventions calibrated to specific infestation thresholds and facility risk classifications. These services protect public health, preserve food safety chains, and maintain regulatory compliance across commercial, industrial, and residential properties. Commercial service contracts currently lead the service type dimension due to mandated food safety audits and insurance-driven compliance requirements, while biological control technologies within the technology dimension are gaining fastest traction as the EU Biocidal Products Regulation restricts conventional neurotoxic chemistries. Fumigation applications command premium pricing in grain storage and import quarantine segments where zero-tolerance phytosanitary standards apply.
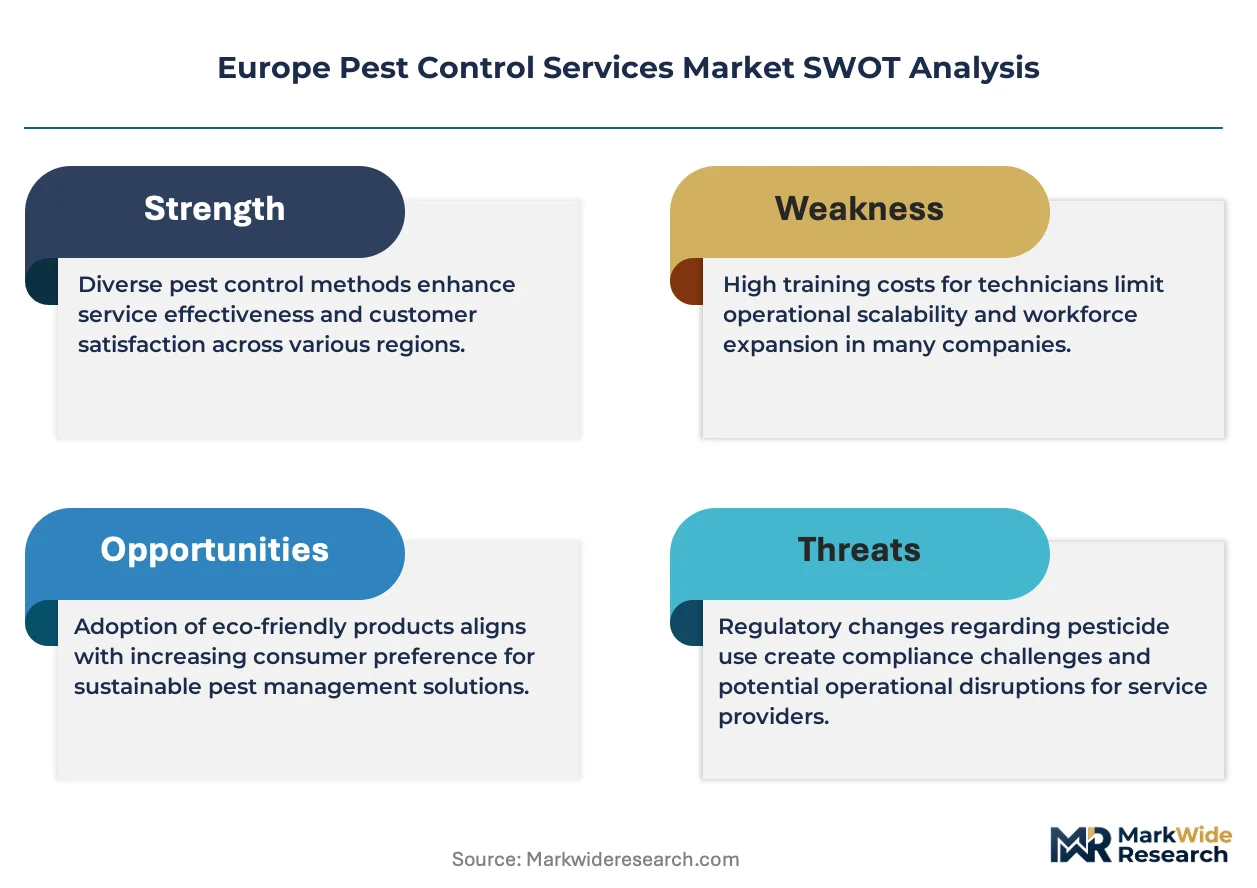
The EU Biocidal Products Regulation and REACH framework govern active substance authorization and worker exposure limits, forcing service providers to reformulate treatment portfolios and retrain field technicians. ECHA substance evaluations and national implementations such as France's ANSM biocide oversight create fragmented compliance obligations across member states. Germany's KBA and BfR contribute transport and food-contact safety standards that shape service protocols in logistics hubs. Stakeholders must monitor the EU Green Deal's chemical sustainability targets and emerging digital reporting mandates under CSRD to anticipate how environmental disclosure requirements will alter client procurement criteria and competitive positioning.
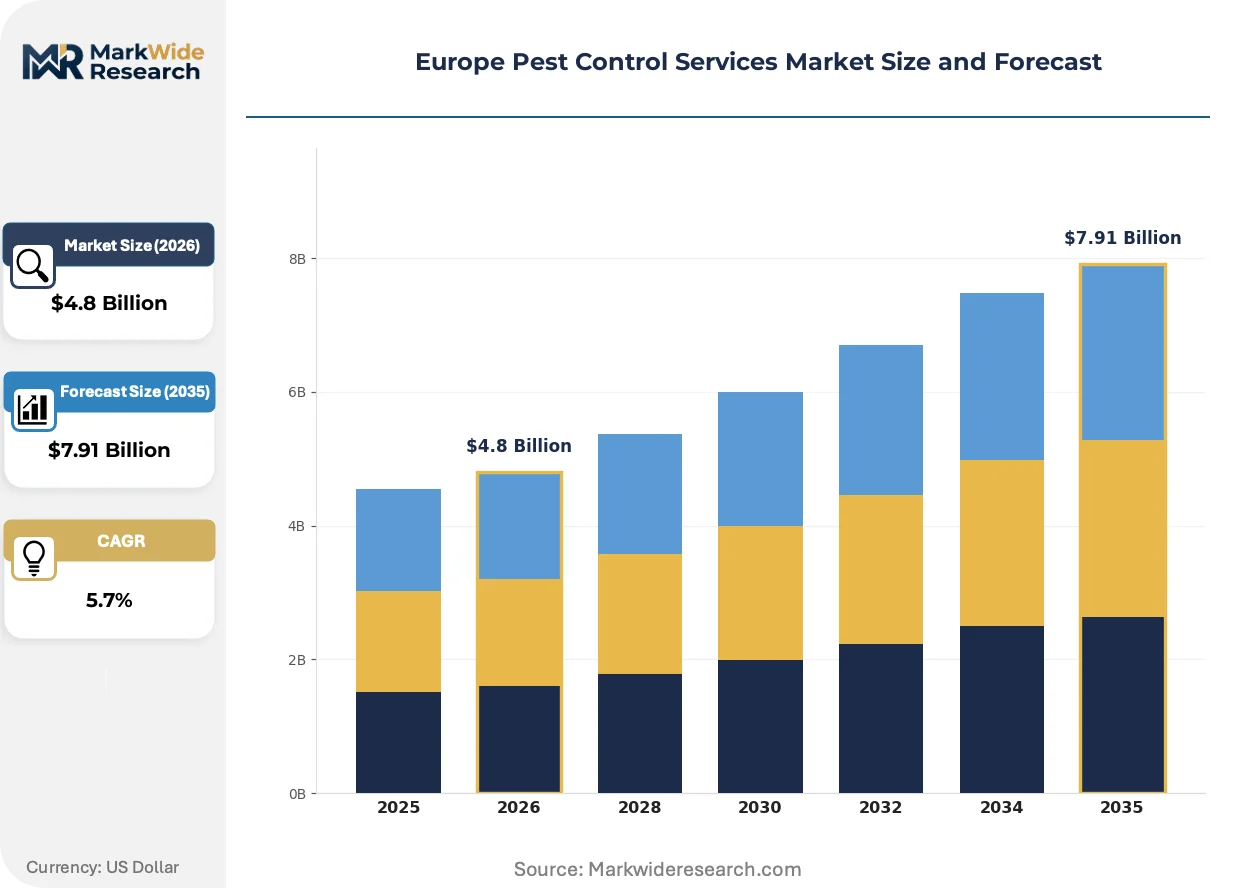
Market Dynamics
The EU Biocidal Products Regulation is systematically eliminating legacy neurotoxic chemistries from service portfolios, forcing providers to rebuild treatment protocols around biological and physical interventions while maintaining efficacy thresholds for food safety and healthcare compliance.
Growth Catalysts
- CSRD disclosure mandates:Large commercial property managers in France and Germany now require documented pest management data for sustainability reporting, creating recurring audit-driven contracts.
- Food processing expansion:Cold chain logistics hubs across the Netherlands and Belgium are mandating continuous monitoring for HACCP compliance, accelerating sensor network deployment.
- Heat treatment protocols:Thermal remediation for bed bug infestations in hospitality is displacing chemical fumigation in urban corridors where residue restrictions tighten.
Market Restraints
- Active substance scarcity:ECHA's staggered substance evaluations under the Biocidal Products Regulation are removing pyrethroid classes faster than replacement chemistries gain approval.
- Technician certification bottlenecks:National implementations of the EU's professional qualification framework create fragmented training requirements across member states.
- Biological control limitations:Entomopathogenic nematodes and parasitoid wasps face temperature and humidity constraints that limit deployment in northern European climates.
Strategic Opportunities
- Pharmaceutical cleanroom protocols:Specialized services for aseptic manufacturing environments command premium pricing as EMA's GMP Annex 1 revisions tighten contamination control.
- Poland and Czech Republic underpenetration:Commercial service contract density in Central European manufacturing corridors remains half Western European levels.
- Sensor-to-ERP integration:Direct data feeds into client enterprise systems is creating vendor stickiness beyond traditional service agreements.
Industry Challenges
- Field technician data literacy:Digital platform operation and predictive alert interpretation now compete with entomological expertise as core competencies.
- Multi-jurisdiction compliance overhead:Service providers operating across France's ANSM, Germany's BfR, and national environmental agencies face divergent reporting formats and inspection rhythms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pest Control Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Industrial, Agricultural Application: Pest Extermination, Termite Control, Rodent Management, Fumigation Technology: Biological Control, Chemical Control, Traps, Baits Customer Type: Homeowners, Businesses, Farmers, Property Managers |
| Companies Covered | Rentokil Initial, Anticimex, Ecolab, Rollins, BASF, Syngenta, Bayer, NBC Environment, Killgerm Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pest Control Services Market Trends and Innovations
Digital infrastructure is displacing scheduled service visits with continuous remote monitoring, compressing response times from days to hours while shifting provider economics toward subscription-based recurring revenue.
Smart trapping hardware is hybridizing pheromone lures with computer vision and cellular connectivity to deliver species-specific identification and population trend analysis. Food retailers in Germany and the Netherlands are deploying these systems across distribution centers to preempt infestation events before threshold breaches trigger regulatory action. The technology is hybridizing chemical and biological interventions by enabling precision targeting that reduces blanket spraying volumes.
REACH authorization timelines for biocidal active substances are extending development cycles and elevating registration costs for formulators. The regulation is compressing available chemistries to a narrower portfolio of approved substances, concentrating supply among providers with dedicated regulatory affairs capabilities. Grain storage and import quarantine segments face acute pressure as fumigant options contract.
Facility managers are consolidating vendor relationships and demanding integrated pest management documentation for insurance underwriting and ESG disclosure. Multi-site hospitality and healthcare operators in the UK and Spain are replacing transactional service calls with multi-year performance contracts tied to audit outcomes. This consolidation favors providers with proprietary digital platforms and cross-border service consistency.
Europe Pest Control Services Market Segmentation
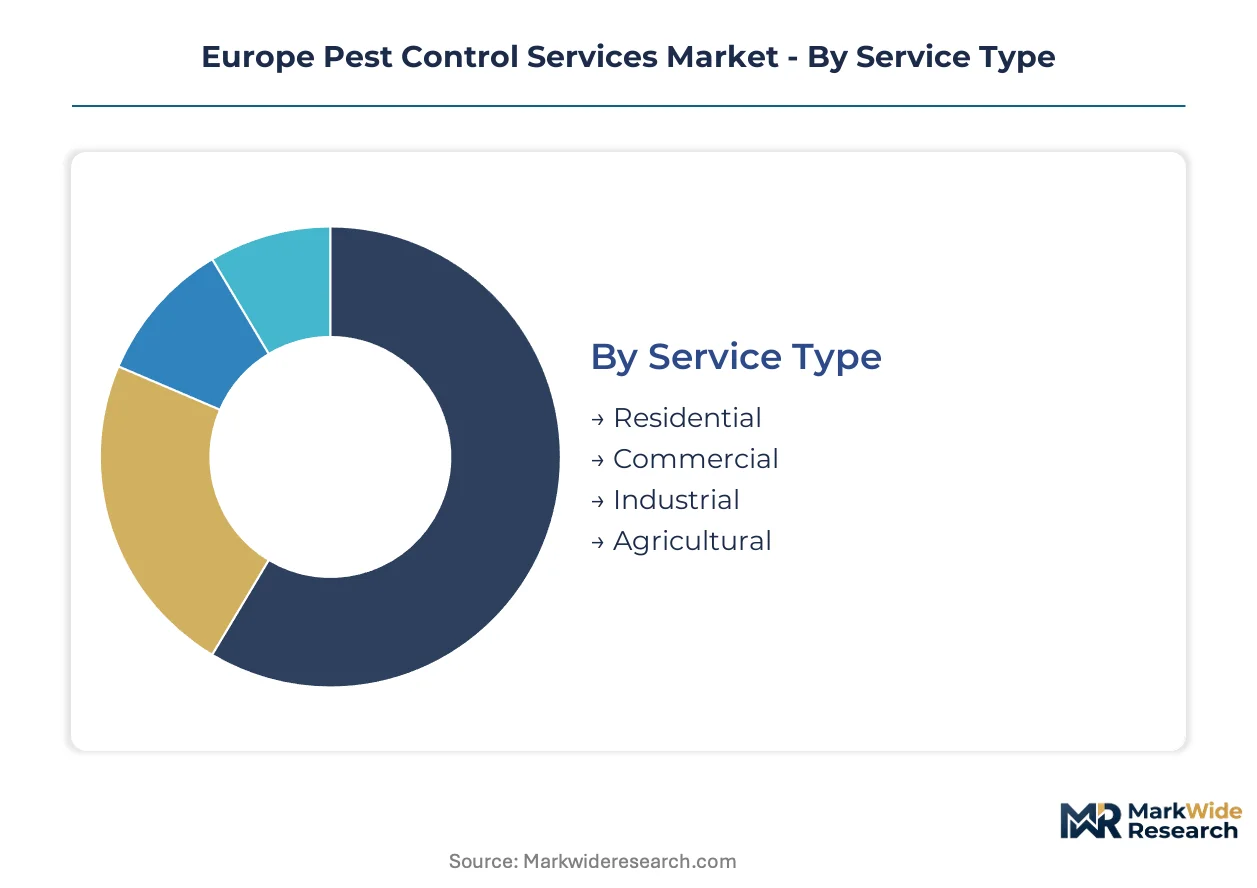
Service providers across Europe calibrate treatment protocols and pricing architectures around four distinct segmentation axes. Each dimension reflects divergent compliance burdens, technology intensity, and contract structures that shape competitive positioning.
Service Type:
Mature contract structures dominate Western European urban corridors while emerging service models penetrate Central European manufacturing zones.
- Residential:Scheduled perimeter treatments and seasonal wasp nest removals constitute the core offering. Demand concentrates in suburban France and southern Germany where detached housing stock and garden culture elevate rodent and wasp service calls.
- Commercial:Continuous monitoring contracts tied to HACCP audits and insurance underwriting requirements anchor revenue stability. Food retailers across the Netherlands and Belgium mandate sensor-integrated service agreements that preempt regulatory threshold breaches.
- Industrial:Heavy manufacturing and logistics facilities require specialized protocols for stored product pests and bird management. German automotive component warehouses and Polish cold chain hubs drive contract density in this segment.
- Agricultural:Seasonal field applications and grain storage fumigation face tightening active substance restrictions under ECHA evaluations. French cereal cooperatives and Danish pork operations represent primary demand centers.
Commercial retains volume leadership; Agricultural holds the steepest expansion curve as biological alternatives displace restricted chemistries.
Application:
Cost tier stratification separates premium protocols for zero-tolerance environments from standard treatment cycles in conventional facilities.
- Pest Extermination:General arthropod elimination using residual sprays and dust formulations addresses cockroach and ant infestations. Urban hospitality operators in Spain and Italy sustain recurring demand amid dense building stock and climate suitability.
- Termite Control:Soil barrier treatments and baiting systems protect structural integrity in Mediterranean climates. French and Portuguese property markets drive specialized contractor certification requirements.
- Rodent Management:Integrated trapping networks and proofing interventions reduce population pressure in food-adjacent environments. UK supermarket distribution centers and German bakery supply chains mandate continuous rodent monitoring.
- Fumigation:Phosphine and sulfuryl fluoride applications for grain silos and import quarantine command premium pricing. Rotterdam port facilities and Black Sea grain transshipment points concentrate specialized service demand.
Fumigation commands the highest price tier per treatment; Rodent Management generates the most recurring contract volume.
Technology:
Application intensity varies from precision biological interventions in organic food production to broad-spectrum chemical treatments in legacy industrial settings.
- Biological Control:Entomopathogenic nematodes and parasitoid wasps target specific pest species without residue accumulation. Dutch greenhouse vegetable operations and Danish organic pork farms adopt these methods ahead of regulatory phase-outs.
- Chemical Control:Synthetic pyrethroids and neonicotinoids face progressive withdrawal under REACH and BPR timelines. Service providers reformulate portfolios around remaining approved actives while retraining field technicians.
- Traps:Mechanical and electronic capture devices enable population monitoring without chemical deployment. German food processing facilities deploy smart traps with computer vision for species-specific identification.
- Baits:Gel and block formulations deliver targeted active doses in sensitive environments. Healthcare facilities across France prefer baiting protocols that minimize airborne residues and ventilation system contamination.
Chemical Control retains installed base dominance; Biological Control gains share fastest as substitution pressures intensify.
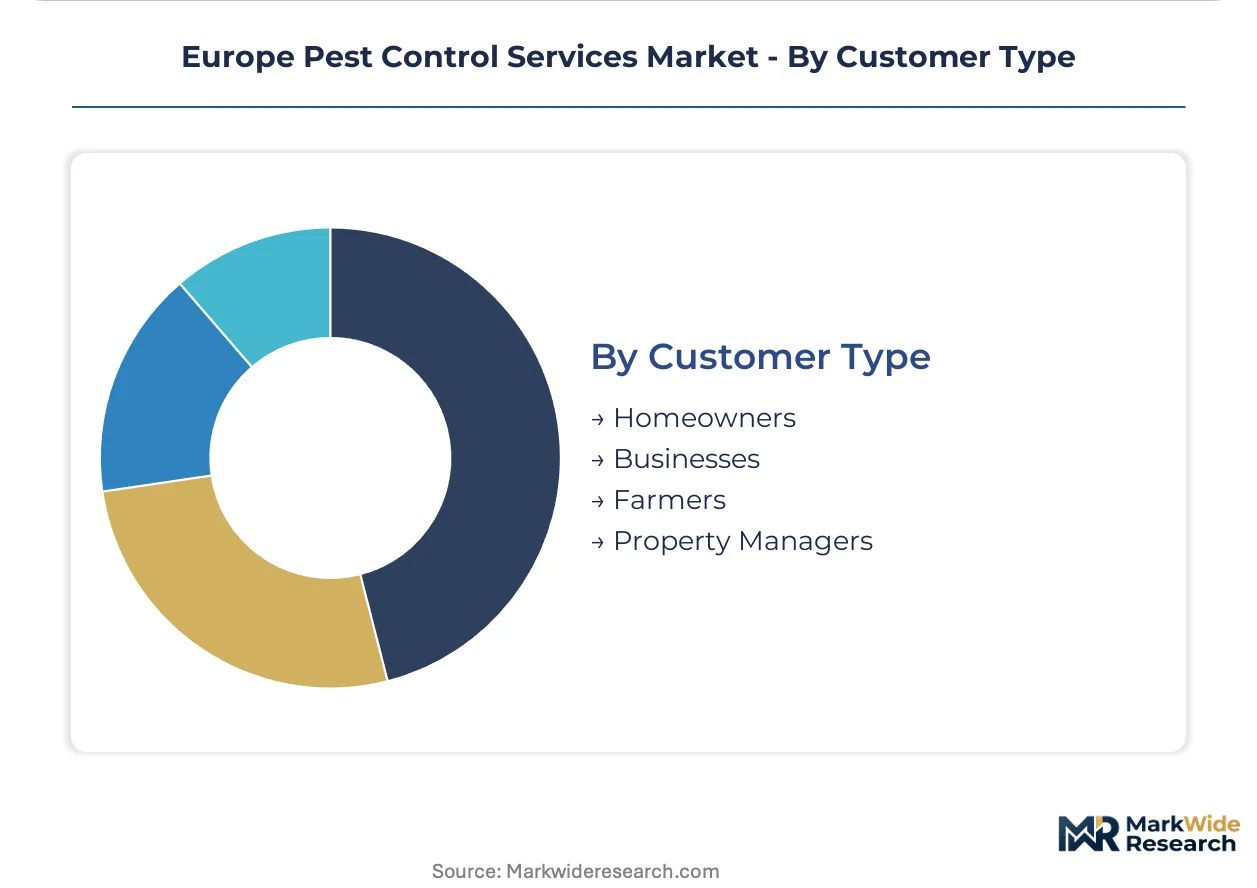
Customer Type:
Procurement sophistication separates enterprise-scale property managers with integrated compliance requirements from transactional residential consumers.
- Homeowners:Reactive service calls for visible infestations dominate this segment with limited contract penetration. Seasonal wasp nest removal and rodent trapping generate intermittent revenue.
- Businesses:Multi-site hospitality and retail operators consolidate vendor relationships and demand audit-ready documentation. French hotel chains and Spanish restaurant groups favor performance-based contracts.
- Farmers:Agricultural producers balance treatment efficacy with harvest interval restrictions and export market residue limits. Polish apple growers and Italian vineyard cooperatives face divergent phytosanitary standards.
- Property Managers:Commercial real estate and social housing portfolios require systematic prevention programs for tenant retention and liability mitigation. German residential property companies embed pest management into facility management contracts.
Businesses concentrate the highest contract value per account; Property Managers deliver the most predictable recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial property managers and food processing operators concentrate demand across Western European urban corridors, while Central European manufacturing zones present underpenetrated expansion opportunities for contracted pest management services.
Germany
Automotive component warehouses and cold chain logistics hubs drive demand for continuous rodent monitoring and HACCP-compliant sensor networks. The BfR and KBA enforce transport and food-contact safety standards that shape service protocols in logistics corridors. Bavaria and North Rhine-Westphalia concentrate contract density around Munich and Düsseldorf industrial zones.
France
Hotel chains and restaurant groups favor performance-based contracts tied to audit outcomes and insurance underwriting. ANSM biocide oversight creates fragmented compliance obligations distinct from neighboring jurisdictions. Île-de-France and Provence-Alpes-Côte d'Azur anchor hospitality-driven demand in Paris and Marseille corridors.
United Kingdom
Supermarket distribution centers mandate continuous rodent monitoring for food safety certification. The Health and Safety Executive and Food Standards Agency govern worker exposure limits and facility inspection rhythms. Greater London and the Midlands concentrate contract value among multi-site retail operators.
Netherlands
Greenhouse vegetable operations adopt biological control methods ahead of regulatory phase-outs for conventional chemistries. The Dutch Food and Consumer Product Safety Authority enforces strict residue limits for export-oriented agriculture. Randstad logistics hubs deploy smart trapping systems for distribution center monitoring.
Poland
Manufacturing corridors and cold chain infrastructure present underpenetrated commercial contract opportunities at half Western European density levels. National implementations of EU professional qualification frameworks create technician certification bottlenecks. Warsaw and Łódź industrial zones drive emerging demand for integrated pest management documentation.
Europe Pest Control Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around digital platform capabilities and cross-border service consistency. Three archetypes dominate: integrated facility service conglomerates with proprietary sensor networks, regional specialists with in-house hardware production, and chemical manufacturers extending into service provision. M&A activity targets sensor-to-ERP integration capabilities, while portfolio diversification accelerates around biological control formulations.
Among UK-based integrated service providers, Rentokil Initial exemplifies the channel-controlling archetype through connected pest management platforms. Swedish specialist Anticimex occupies a position within the smart hardware tier. US conglomerate Ecolab represents the diversified facility services model with pharmaceutical cleanroom protocols. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning across the European market.
| Leading Market Players |
|---|
| Rentokil Initial |
| Anticimex |
| Ecolab |
| Rollins |
| BASF |
| Syngenta |
| Bayer |
| NBC Environment |
| Killgerm Group |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp freight corridor channels biocidal active substances and smart trapping hardware into Western European service networks, where logistics cost differentials between bulk chemical shipments and precision electronics concentrate supplier power among integrated formulators while fragmenting downstream pricing power across regional service providers.
Pricing Analysis
Cost-plus contracts indexed to ECHA substance evaluation timelines dominate commercial service agreements, with price differentiation anchored in certification grade and sensor integration depth. Premium-mid-economy pricing stratification separates pharmaceutical cleanroom protocols from standard perimeter treatments, while pricing pressure stems from pyrethroid phase-outs compressing available chemistries faster than biological alternatives achieve scale. Residential homeowners exhibit highest price sensitivity; multi-site hospitality operators under CSRD mandates show lowest.
Supply Chain Analysis
Supply-chain finance facilities extended by German chemical distributors ease working capital constraints for mid-tier service providers purchasing reformulated actives under REACH authorization delays. Active substance manufacturing concentrates in Germany, the Netherlands, and Belgium; smart trap hardware production centers on Sweden and Denmark. The network draws from pyrethroid precursors, entomopathogenic nematode cultures, and cellular IoT modules, with single-source vulnerability in ECHA-approved active substance suppliers. Distribution runs through national service branches with direct-to-facility technician deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as sensor-to-ERP data interoperability becomes the primary procurement criterion for multi-site commercial operators, with ESG disclosure integration creating winner-take-most dynamics among connected pest management providers.
For Market Incumbents: Build switching-cost moats through proprietary sensor-to-ERP integration that embeds service providers into client enterprise systems beyond traditional contract renewal cycles. Prioritize backward integration into biological control formulation capacity as ECHA pyrethroid withdrawals accelerate substitution demand. Consolidate technician certification capabilities across France's ANSM and Germany's BfR jurisdictions to reduce multi-jurisdiction compliance overhead. For New Entrants and Emerging Players: Mid-market manufacturing facilities in Poland and the Czech Republic represent the most penetrable entry point, where commercial service contract density runs at half Western European levels and integrated pest management documentation demand is emerging. Pharmaceutical cleanroom protocols offer premium positioning for specialists with aseptic environment expertise. Lead with biological control service offerings to bypass conventional chemistry registration barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified facility services conglomerates seeking to divest non-core pest management units lacking digital platform capabilities. Long-term viability hinges on recurring revenue share from subscription-based monitoring versus transactional treatment calls. Watch EMA GMP Annex 1 enforcement intensity as inflection indicator for pharmaceutical cleanroom service premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Control Formulation Investment | Builds regulatory resilience as ECHA pyrethroid withdrawals accelerate under REACH timelines. |
| Sensor-to-ERP Platform Integration | Creates vendor stickiness through direct data feeds into client enterprise resource planning systems. |
| Cross-Border Certification Consolidation | Reduces compliance overhead from fragmented ANSM, BfR, and national environmental agency requirements. |
| Central European Geographic Expansion | Captures underpenetrated manufacturing corridor demand in Poland and Czech Republic industrial zones. |
| Pharmaceutical Cleanroom Protocol Development | Commands premium pricing as EMA GMP Annex 1 revisions tighten aseptic manufacturing contamination controls. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pest control service executives, facility managers at food processing and pharmaceutical manufacturing sites, ECHA regulatory affairs specialists, and smart trap hardware engineers. Secondary validation incorporated EU Biocidal Products Regulation authorization databases, national biocide agency filings from France's ANSM and Germany's BfR, customs trade data for active substance imports, and corporate sustainability reports under CSRD disclosure mandates. Bottom-up service contract value estimates were triangulated against top-down market sizing from regulatory expenditure flows.
Calibration against historical ECHA substance evaluation timelines and sensor network deployment rates anchored projection modeling across the analysis window. Segmentation dimensions included service type, application method, technology platform, and customer procurement sophistication. CAGRs were derived from trend extrapolation of digital monitoring adoption curves and biological control substitution elasticities, with cross-validation against food safety audit frequency data and insurance underwriting requirement evolution.
Practitioners should monitor ECHA authorization delays, CSRD disclosure mandate expansion, and biological control efficacy breakthroughs for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
North America Rockfall Radar Market