
 Noise Control System Market | 2026-2036
Noise Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Noise Control System Market Outlook
EU Environmental Noise Directive amendments is rebalancing the cost-of-entry calculus for European suppliers, forcing acoustic performance certification upgrades across product portfolios. Saint-Gobain S.A. leverages its mineral wool manufacturing scale to dominate industrial insulation specifications. Rockwool International A/S anchors its position through captive basalt sourcing and vertical control over melt-spinning capacity. Kinetics Noise Control, Inc. specializes in vibration isolation systems for precision manufacturing environments.
A noise control system encompasses engineered assemblies of porous absorbers, resonant dampers, barrier materials, and active cancellation electronics designed to attenuate airborne and structure-borne sound transmission across frequencies from 63 Hz to 8 kHz. These systems deploy in HVAC plenums, enclosure walls, and machine bases to maintain occupational exposure below regulatory thresholds and community noise ordinances. Acoustic Panels and Sound Barriers command the largest installed base in commercial and transportation applications, while Active Noise Control represents the fastest-expanding technology segment as digital signal processors drop in cost. Vibration Dampers retain premium margin pools in semiconductor fabrication and precision metrology end uses where displacement tolerances measure in nanometers.
OSHA permissible exposure limits in the United States, the EU Environmental Noise Directive, and China's GB 3096 environmental quality standards collectively shape product certification requirements and market access conditions across major demand centers. Compliance with these frameworks now requires third-party laboratory validation of insertion loss and reverberation time metrics, adding fixed cost layers that favor scaled manufacturers over regional fabricators. Stakeholders must monitor evolving low-frequency regulation in transportation corridors and assess whether active cancellation investments justify the performance premium against passive alternatives in cost-sensitive industrial retrofit projects.
Market Dynamics
EU Environmental Noise Directive amendments are compressing certification timelines for acoustic product suppliers, forcing simultaneous upgrades to laboratory validation protocols across mineral wool, resonant damper, and active cancellation product lines.
Growth Catalysts
- Trackside absorption procurement:Urban rail authorities in Germany and China are scaling purchases of porous absorber arrays as decibel limits tighten under amended EU directives and China's GB 3096 standards.
- Industrial corridor remediation:Factory retrofit cycles across the US Rust Belt are accelerating as OSHA permissible exposure limits trigger mandatory noise control installations in legacy manufacturing facilities.
- Digital signal processor cost compression:Falling semiconductor prices are expanding the addressable market for active noise cancellation electronics in cost-sensitive HVAC and transportation applications.
Market Restraints
- Basalt fiber supply concentration:Captive sourcing of melt-spinning feedstock in volcanic regions creates geographic vulnerability for stone wool insulation manufacturers.
- Third-party validation fixed costs:Mandatory laboratory certification of insertion loss and reverberation time metrics under EU, US, and Chinese frameworks disadvantages regional fabricators against scaled producers.
- Passive barrier performance ceiling:Mass-law limitations on single-layer panels above 500 Hz restrict acoustic performance gains without substantial material thickness penalties.
Strategic Opportunities
- Precision manufacturing verticals:Semiconductor fabrication and metrology equipment installations require nanometer-scale vibration isolation where damper systems command sustained premium positioning.
- Low-frequency transportation regulation:Emerging standards for 63-125 Hz attenuation in rail and aviation corridors favor hybrid active-passive systems over conventional absorption.
- Retrofit service bundling:Industrial facility managers are consolidating acoustic assessment, product specification, and installation oversight into single-contractor arrangements.
Industry Challenges
- Acoustic engineering talent scarcity:Specialized expertise in finite element modeling of multi-physics vibration systems remains concentrated among a limited pool of consultants and OEM engineering groups.
- Legacy infrastructure integration:Active cancellation electronics require signal processing architecture incompatible with existing HVAC control systems in aged commercial buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noise Control System Market |
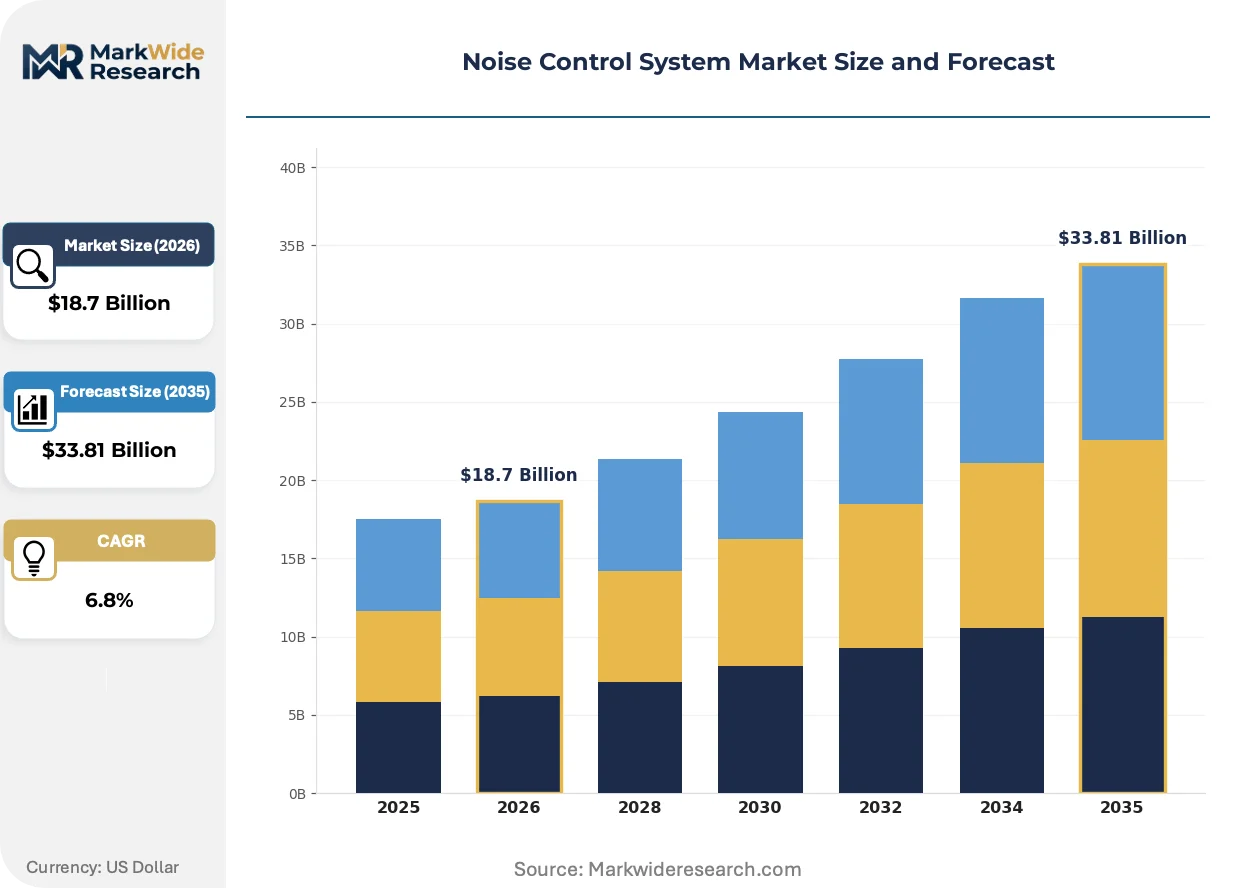
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Panels, Sound Barriers, Noise Barriers, Vibration Dampers Application: Industrial Facilities, Transportation, Commercial Spaces, Residential Areas Technology: Passive Noise Control, Active Noise Control, Acoustic Insulation, Noise Abatement End User: Manufacturing, Construction, Automotive, Healthcare |
| Companies Covered | 3M Company, Saint-Gobain S.A., Honeywell International Inc., Rockwool International A/S, Armstrong World Industries, Owens Corning, Kinetics Noise Control, Inc., Acoustiblok, Inc., IAC Acoustics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noise Control System Market Strategic Shifts
Digital signal processing architectures are compressing the cost-performance frontier for active noise control, while regulatory stringency in transportation and occupational settings tightens material certification requirements across supplier bases.
Machine learning-based adaptive filtering is automating real-time adjustment of anti-noise waveforms in variable-frequency industrial environments. Precision machining facilities and power generation plants are deploying these systems to maintain compliance without manual recalibration. The technology is automating labor-intensive commissioning processes that previously required specialized acoustic consultants on-site for weeks.
Amendments to the EU Environmental Noise Directive now mandate third-party verification of low-frequency insertion loss in rail corridor applications. This regulatory shift forces suppliers to maintain accredited laboratory partnerships or invest in in-house reverberation chambers. Trackside absorption system manufacturers serving German and French markets are prioritizing 63-125 Hz performance data in product specifications.
Facility managers in US industrial corridors are consolidating vendor relationships from fragmented specialty contractors toward integrated acoustic solution providers. This buyer concentration compresses procurement cycles but raises barriers for regional fabricators lacking full-service capabilities. The pattern is most pronounced in Rust Belt states where OSHA enforcement has intensified factory retrofit timelines.
Noise Control System Market Segmentation
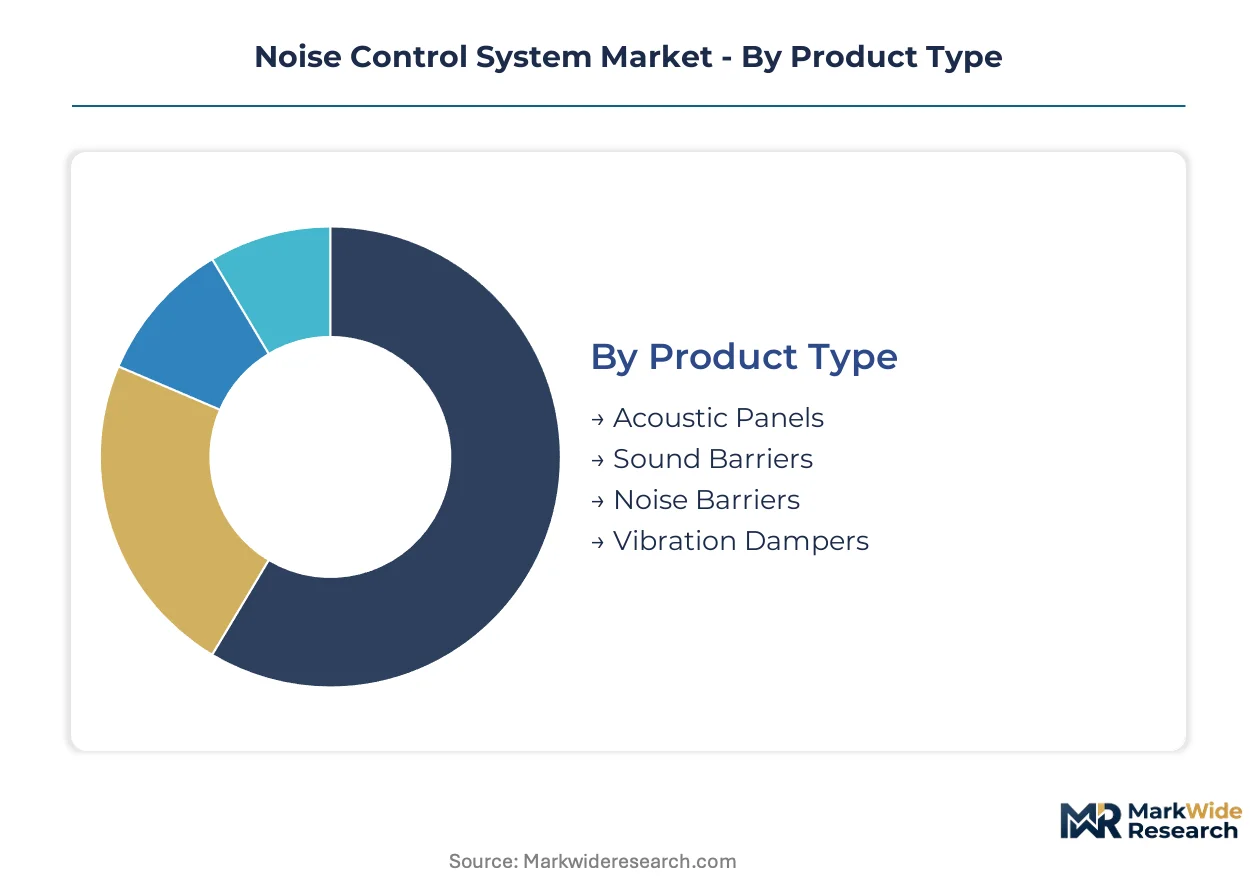
Product specifications in noise control systems diverge sharply across installation environments, with industrial retrofit cycles and transportation infrastructure upgrades driving portfolio rebalancing among manufacturers. Segmentation clarity enables suppliers to align laboratory certification investments with regulatory pressure points.
Product Type:
Upgrade cycles in legacy manufacturing facilities and rail corridor remediation projects are reshaping procurement specifications across absorptive and barrier product lines.
- Acoustic Panels:Porous absorber assemblies of mineral wool or fiberglass face composite substrates, engineered for broadband absorption coefficients above 0.85 in HVAC plenums and machinery enclosures. Demand concentrates in German urban rail stations where EU Environmental Noise Directive amendments mandate reverberation time reductions.
- Sound Barriers:Mass-loaded barrier membranes and composite wall systems designed for transmission loss performance in the 500-4000 Hz range. Procurement accelerates across US Rust Belt industrial corridors as OSHA enforcement intensifies factory perimeter noise mitigation.
- Noise Barriers:Rigid panel systems combining absorptive facing with reflective backing for outdoor transportation applications.
- Vibration Dampers:Resonant mass-spring assemblies and viscoelastic isolators for structure-borne energy dissipation.
Acoustic Panels sits at the top of the volume ranking, with Vibration Dampers climbing the fastest.
Application:
Cost tier differentiation separates specification-grade systems from commodity absorption products across facility types.
- Industrial Facilities:High-performance enclosure systems and ventilation silencers engineered for occupational exposure limits in metalworking and power generation plants. Retrofit demand clusters in Ohio and Pennsylvania where OSHA permissible exposure limits trigger mandatory noise control installations in legacy factories.
- Transportation:Trackside absorption arrays and aircraft engine nacelle treatments designed for 63-125 Hz low-frequency attenuation. German and Chinese rail authorities are scaling procurement as GB 3096 standards and EU directive amendments tighten decibel limits.
- Commercial Spaces:Ceiling baffles and wall treatments for open-plan offices and hospitality environments.
- Residential Areas:Window inserts and facade insulation for community noise ordinance compliance.
Industrial Facilities commands the largest installed base, while Transportation gains share fastest.
Technology:
Application requirements determine the active-passive technology mix, with precision manufacturing environments tolerating premium electronics costs.
- Passive Noise Control:Absorptive, reflective, and damping treatments relying on material properties without powered components. Dominates cost-sensitive HVAC and construction applications where digital signal processor costs remain prohibitive.
- Active Noise Control:Real-time anti-noise generation through microphone-loudspeaker feedback loops with adaptive filtering algorithms. Expanding most quickly in semiconductor fabrication facilities where nanometer-scale vibration tolerances justify electronics premiums.
- Acoustic Insulation:Thermal-acoustic composite materials for building envelope integration.
- Noise Abatement:Engineered source control through mufflers, silencers, and intake treatment systems.
Passive Noise Control maintains volume leadership, with Active Noise Control showing the steepest expansion trajectory.
End User:
Customer type concentration shapes distribution channel configuration and service bundling requirements.
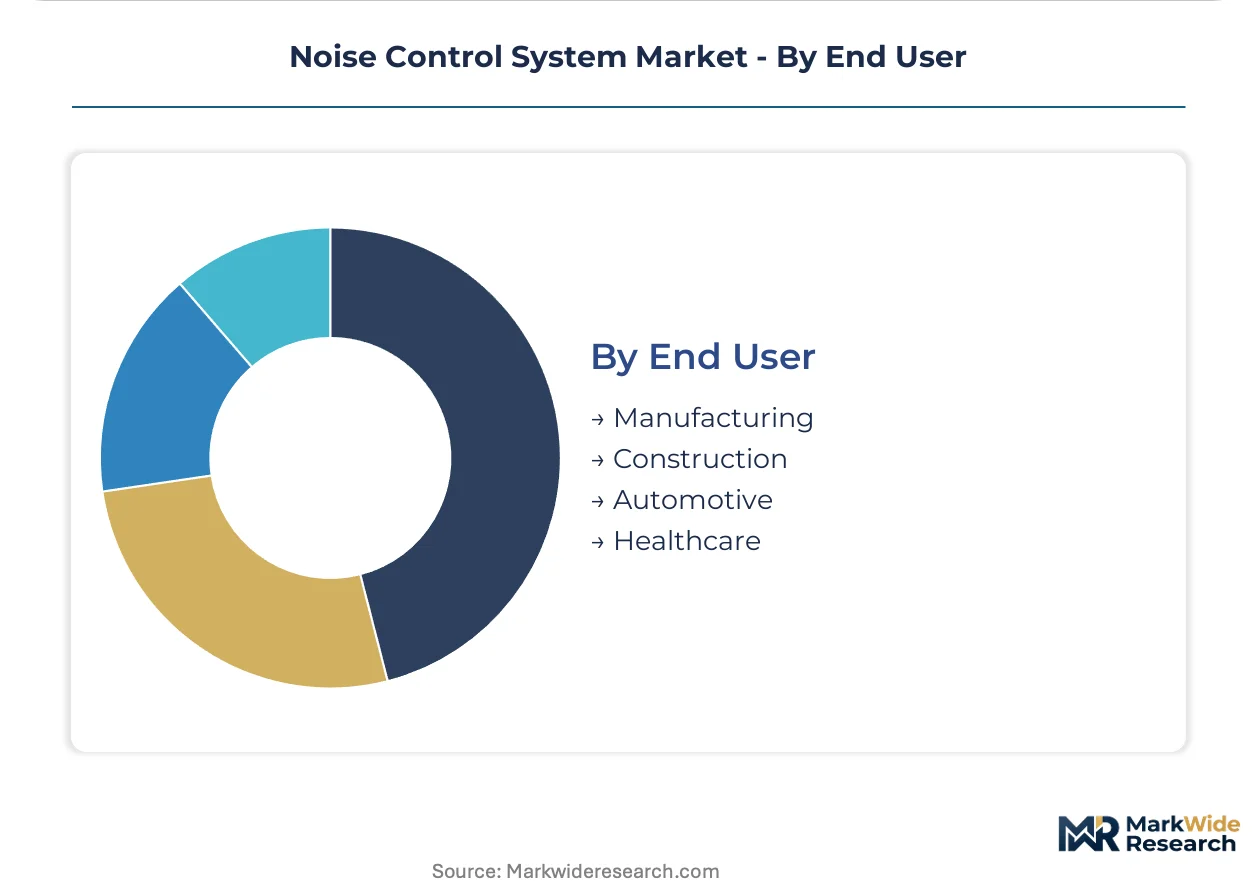
- Manufacturing:Integrated noise control specifications for production line enclosures, material handling systems, and quality control environments. Procurement in automotive stamping plants and electronics assembly facilities drives demand for hybrid active-passive systems.
- Construction:Building-integrated acoustic treatments specified during design phase for LEED and WELL certification compliance.
- Automotive:Powertrain encapsulation and cabin isolation systems for electric vehicle NVH management.
- Healthcare:MRI suite isolation and hospital HVAC silencing for patient recovery environments.
Manufacturing anchors demand volume, with Automotive climbing fastest on electric vehicle production expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic engineering talent clusters in Germany, the United States, and China anchor procurement decisions for noise control infrastructure across rail, industrial, and commercial applications. Regulatory divergence between OSHA enforcement in American factory corridors and EU Environmental Noise Directive amendments in European transit systems fragments certification requirements. Procurement patterns track manufacturing density and transportation infrastructure age.
United States
Industrial corridor remediation drives demand across Ohio and Pennsylvania where legacy metalworking facilities face OSHA permissible exposure limit enforcement. The Department of Labor intensifies factory inspection cycles in Rust Belt states, accelerating retrofit timelines for enclosure systems and ventilation silencers. Cleveland and Pittsburgh manufacturing clusters concentrate procurement of hybrid active-passive systems for automotive stamping plants.
Germany
Urban rail authorities in Berlin and Munich scale trackside absorption procurement as amended EU Environmental Noise Directive mandates tighten decibel thresholds. KBA certification requirements for low-frequency insertion loss reshape supplier laboratory investments. Stuttgart and Hamburg transit corridors prioritize 63-125 Hz performance validation in porous absorber specifications.
China
GB 3096 environmental quality standard revisions compress compliance timelines for industrial and transportation acoustic treatments. Shanghai and Beijing rail authorities deploy trackside barrier systems along elevated corridor expansions. Shenzhen semiconductor fabrication clusters drive precision vibration damper demand for nanometer-scale process equipment isolation.
Japan
METI industrial efficiency guidelines intersect with JIS acoustic standards to mandate noise control upgrades in precision manufacturing facilities. Nagoya automotive production corridors and Osaka electronics assembly clusters specify active cancellation systems for cleanroom environments. Tokyo rail operators test hybrid absorption arrays for underground station reverberation management.
India
BIS certification expansion for building acoustic materials opens procurement channels for mineral wool and fiberglass panel suppliers. Maharashtra and Gujarat industrial zones retrofit textile and chemical processing facilities under state pollution control board enforcement. Delhi-Mumbai freight corridors drive demand for wayside noise barriers along high-density rail segments.
Noise Control System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material, electronic, and engineered system segments. The vendor base stratifies into three tiers: multinational material science conglomerates with captive mineral fiber capacity, mid-scale acoustic engineering specialists with certified laboratory networks, and regional fabricators serving single-country retrofit markets. Two strategic archetypes dominate competitive positioning: backward-integrated mineral wool producers controlling melt-spinning feedstock, and technology-licensed active cancellation integrators leveraging falling digital signal processor costs. Capacity expansion in basalt fiber sourcing and M&A consolidation of regional installation contractors represent the dominant competitive moves.
Within the diversified conglomerate tier, Saint-Gobain S.A. and Owens Corning exemplify mineral wool manufacturing scale applied to industrial insulation specifications. Rockwool International A/S anchors the stone wool specialist archetype through volcanic region basalt sourcing. Kinetics Noise Control, Inc. occupies a position among vibration isolation engineering specialists serving precision manufacturing environments. These three company structures illustrate how geographic origin and corporate form signal strategic positioning: French S.A. conglomerates, Danish A/S specialists, and American Inc. engineering firms each represent distinct capability bundles without claiming specific market share or financial performance.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain S.A. |
| Honeywell International Inc. |
| Rockwool International A/S |
| Armstrong World Industries |
| Owens Corning |
| Kinetics Noise Control, Inc. |
| Acoustiblok, Inc. |
| IAC Acoustics |
| Others |
Value Chain & Pricing Dynamics
Active noise control digital signal processor cost compression is simultaneously collapsing electronics premiums and concentrating procurement power among scaled system integrators capable of absorbing validation overhead. This technology shift forces regional fabricators toward passive material specialization or exit while rewarding conglomerates with captive laboratory networks.
Pricing Analysis
Bundled assessment-specification-installation contracts command 15-25% premiums over unbundled material-only transactions in Rust Belt industrial retrofits. Three-tier pricing structure across certified, pre-qualified, and commodity-grade products reflects EU Environmental Noise Directive laboratory validation tiers. Cost compression in active cancellation electronics is intensifying because semiconductor foundry capacity expansion outpaces acoustic engineering talent growth. Municipal rail authorities exhibit lowest price sensitivity due to regulatory compliance mandates, while commercial HVAC contractors face acute margin pressure from commodity mineral wool substitution.
Supply Chain Analysis
Direct-to-OEM channels handle precision manufacturing damper demand, while distributor networks serve construction and retrofit contractors. Basalt fiber supply concentrates in Iceland, Russia, and China's volcanic provinces, creating geographic vulnerability for stone wool insulation manufacturers. Melt-spinning feedstock, digital signal processors, and certified acoustic laboratory access constitute critical input dependencies. Tariff exposure on Chinese electronic components threatens active cancellation system margins. Distribution runs through specialized acoustic engineering distributors in Germany, integrated building materials suppliers in the United States, and state-owned procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA enforcement intensity in Ohio and Pennsylvania creates 18-24 month retrofit windows that compress supplier qualification timelines versus China's GB 3096 phased implementation, generating geographic-arbitrage opportunities for validated product portfolios.
For Market Incumbents: Hedge against active cancellation commoditization by deepening backward integration into basalt fiber sourcing and acquiring regional installation contractors in Rust Belt corridors. Saint-Gobain S.A. and Rockwool International A/S exemplify mineral wool scale defense against electronics-licensed entrants. Certification investment in EU reverberation chamber partnerships represents the priority capability lever. For New Entrants and Emerging Players: Enter via precision semiconductor fabrication vibration isolation where nanometer-scale tolerances sustain premium positioning against passive alternatives. White-space targets cluster in Shenzhen cleanroom expansions and Nagoya automotive metrology facilities. Licensing adaptive filtering algorithms from audio consumer electronics vendors accelerates go-to-market velocity versus ground-up DSP development. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale acoustic engineering specialists with certified laboratory networks but lacking installation service bundling. Long-term viability hinges on regulatory enforcement persistence in transportation and occupational settings. Watch KBA low-frequency insertion loss mandate expansion into French and Italian rail corridors as inflection signal for hybrid active-passive system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | EU Environmental Noise Directive amendments mandate third-party validation for rail corridor access. |
| Backward Integration into Basalt Sourcing | Captive volcanic region feedstock secures stone wool margin pools against fiber price volatility. |
| Installation Service Bundling | Rust Belt facility managers consolidate vendor relationships toward single-contractor acoustic retrofit arrangements. |
| Adaptive Filtering Algorithm Licensing | Machine learning-based real-time adjustment automates commissioning labor in variable-frequency industrial environments. |
| Regional Installation Contractor Acquisition | OSHA enforcement timelines in Ohio and Pennsylvania compress procurement cycles for qualified local installers. |
Study Parameters
Coverage spans Germany, the United States, China, and Japan, with primary inputs from each manufacturing and transportation corridor. Interviews with acoustic engineering consultants, rail authority procurement officers, industrial facility maintenance directors, and mineral wool plant managers combined with secondary validation from OSHA enforcement records, EU Environmental Noise Directive amendment texts, GB 3096 standard documentation, and KBA certification databases. Bottom-up project pipeline tracking and top-down regulatory impact modeling triangulate volume estimates.
Rate-of-change decomposition separates baseline retrofit replacement cycles from regulatory acceleration effects across the projection horizon. Segmentation dimensions include product type (absorptive, barrier, active, damping), application environment (industrial, transportation, commercial, residential), technology architecture (passive, active, hybrid), and end-user vertical (manufacturing, construction, automotive, healthcare). CAGRs derive from regression against manufacturing density indices, rail infrastructure age profiles, and enforcement intensity proxies. Industry-specific inputs include semiconductor fabrication equipment capital expenditure patterns and electric vehicle platform noise-vibration-harshness engineering budgets.
Inputs from German KBA, US Department of Labor, and China MEE regulatory filings were available through the study window; gaps in real-time enforcement intensity data introduce uncertainty bands around Rust Belt retrofit timing assumptions. Forecasts reflect documented assumptions regarding OSHA inspection cycle frequency, EU directive amendment ratification timelines, and GB 3096 revision implementation pace. Commodity basalt fiber price volatility and digital signal processor foundry capacity allocation shifts constitute primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Industrial Noise Control Market