
 Environmental Health and Safety Market | 2026-2036
Environmental Health and Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Health and Safety Market Intelligence
Platform licensing revenue is reshaping competitive economics in the Environmental Health and Safety sector, pulling margin pools away from one-time implementation fees toward recurring subscription streams. Ecolab Inc leverages its installed base across industrial water treatment to cross-sell integrated EHS modules. WSP Global Inc anchors its positioning through deep engineering relationships with heavy infrastructure clients. ERM differentiates by embedding climate risk analytics into traditional compliance workflows.
Environmental Health and Safety encompasses the systematic identification, assessment, and mitigation of workplace hazards, environmental releases, and regulatory exposures through engineered controls, administrative protocols, and personal protective systems designed to prevent occupational injury, illness, and ecological harm. The discipline relies on continuous monitoring parameters including air quality indices, noise exposure levels, chemical vapor concentrations, and wastewater discharge thresholds to maintain operational permits and workforce protection standards. Cloud-based deployment is expanding fastest among mid-sized manufacturing plants that lack dedicated IT security staff yet require scalable incident reporting. Risk Management solutions command the largest solution offering share as enterprises consolidate fragmented point tools into unified governance platforms. Worker Safety applications within oilfield services and mining operations generate premium pricing due to catastrophic loss potential and stringent MSHA enforcement.
OSHA maintains active enforcement protocols for process safety management in chemical facilities, while EPA oversight of Clean Air Act compliance drives continuous emissions monitoring system investments. The EU Green Deal and CSRD disclosure requirements are extending EHS data collection obligations to supply chain tiers for multinational exporters. Stakeholders must evaluate whether their current compliance architectures can absorb emerging requirements around Scope 3 emissions tracking and biodiversity impact disclosure without wholesale system replacement.
Market Dynamics
Cloud migration is compressing deployment cycles for Environmental Health and Safety platforms as mid-sized industrial facilities abandon on-premises infrastructure for scalable SaaS architectures. This shift is redistributing vendor economics from upfront implementation fees toward recurring subscription revenue pools.
Growth Catalysts
- OSHA Process Safety Management:Chemical processing facilities in the United States are accelerating software procurement to satisfy stricter enforcement protocols for hazardous process documentation and mechanical integrity tracking.
- Worker Safety digitization:Oilfield services and mining operations are deploying connected wearables and real-time gas detection networks to preempt catastrophic incidents under MSHA oversight.
- EU CSRD disclosure mandates:Multinational exporters are extending EHS data collection obligations to supply chain tiers to meet corporate sustainability reporting requirements for Scope 3 emissions transparency.
Market Restraints
- Legacy system stranded costs:Heavy industrial plants face write-down pressures from depreciated on-premises EHS installations that resist cloud API integration without middleware layers.
- Cybersecurity skill scarcity:Mid-sized manufacturing facilities lack dedicated IT security staff to manage cloud platform governance, creating adoption friction for SaaS deployment models.
- Input cost volatility:Sensor hardware and industrial IoT components face pricing instability from semiconductor supply concentration in East Asian fabrication clusters.
Strategic Opportunities
- Biodiversity impact disclosure:Emerging regulatory frameworks in the European Union are creating demand for nature-positive analytics modules that extend beyond carbon and chemical compliance.
- Climate risk convergence:Integration of physical risk modeling with traditional EHS workflows is opening white space for engineering consultancies with deep infrastructure client relationships.
- India industrial expansion:Manufacturing capacity growth under PLI scheme incentives is generating first-time EHS software demand among domestic chemical and pharmaceutical producers.
Industry Challenges
- Interoperability fragmentation:Point solutions for incident reporting, emissions monitoring, and training management resist unified data architecture without expensive custom integration.
- Certification timeline compression:Accelerated OSHA and EPA audit cycles are forcing facilities to compress compliance documentation workflows without proportional staffing increases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Health and Safety Market |
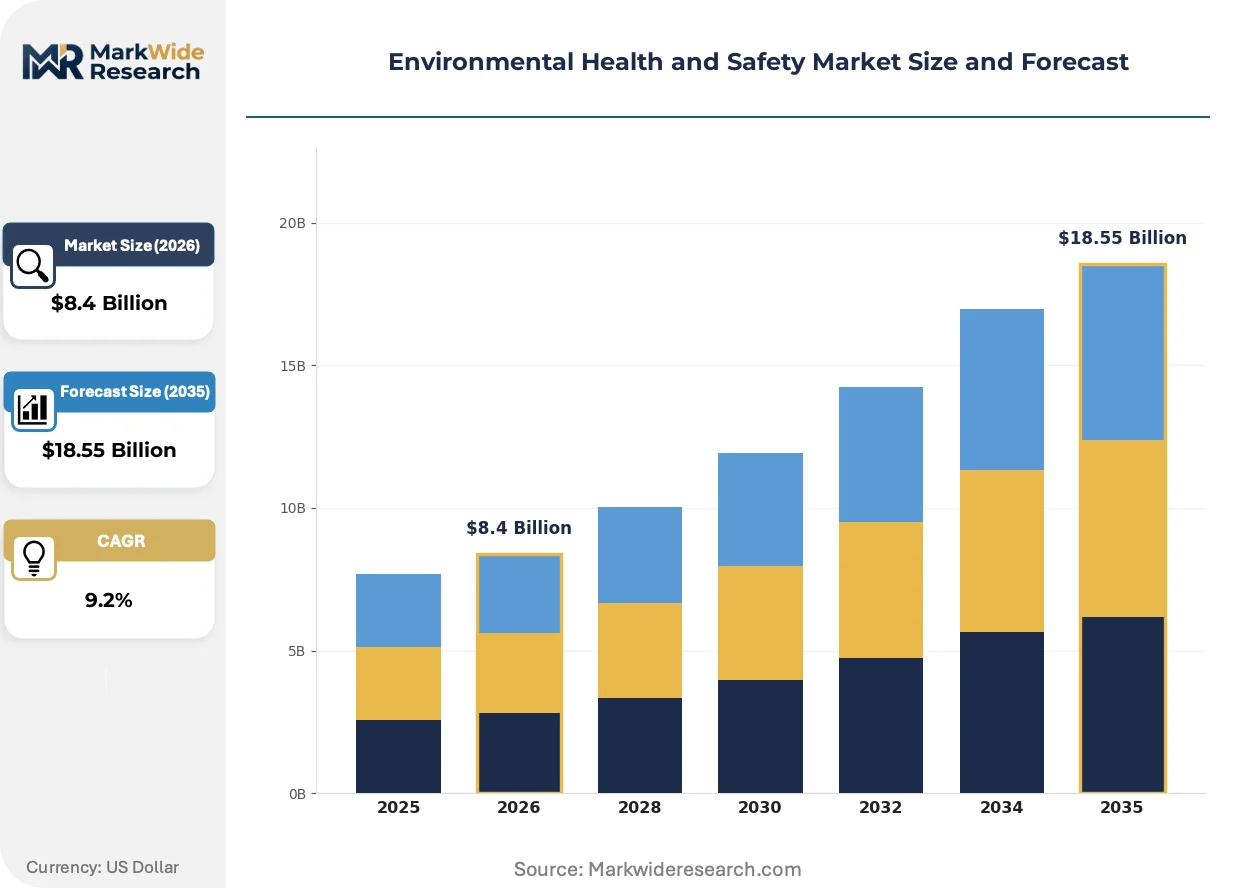
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Risk Management, Compliance Management, Incident Management, Audit Management, Environmental Monitoring, Training & Awareness Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application Area: Worker Safety, Environmental Protection, Regulatory Compliance, Hazardous Material Management, Waste Management End User Industry: Manufacturing Plants, Chemical Processing, Construction Firms, Oilfield Services, Mining Operations, Utilities |
| Companies Covered | Triumvirate Environmental, WSP Global Inc, ERM, Xylem Inc, Ecolab Inc, BSI Group, Inogen Alliance, The Phylmar Group, EHS Momentum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Health and Safety Market Strategic Shifts & Innovations
Environmental Health and Safety technology is pivoting from reactive compliance documentation toward predictive risk intervention. Vendors are embedding machine learning models into operational workflows to anticipate equipment failures and exposure events before regulatory thresholds trigger.
Industrial IoT sensor networks are digitizing environmental monitoring across chemical, utility, and mining operations. Mid-sized manufacturing plants lacking dedicated IT infrastructure are adopting plug-and-play air quality and noise monitoring arrays that feed directly into cloud analytics dashboards. This connectivity is digitizing what were previously manual sampling and paper-based reporting workflows, compressing incident response times from days to minutes.
EPA enforcement of Clean Air Act continuous emissions monitoring requirements is mandating real-time data transmission from stack sensors to federal repositories. Power generation and cement producers are retrofitting optical gas imaging and Fourier-transform infrared systems to satisfy enhanced reporting obligations. Facilities in Texas and California industrial corridors are responding by consolidating fragmented point tools into unified governance platforms that automate permit threshold alerts.
Subscription-based platform licensing is displacing perpetual software ownership across industrial procurement departments. Capital-constrained facilities prefer operational expenditure treatment for EHS technology, shifting vendor relationships toward outcome-aligned service agreements. This preference is most visible among North American chemical processors and European automotive suppliers restructuring technology budgets around cash flow visibility rather than depreciation schedules.
Environmental Health and Safety Market Segmentation
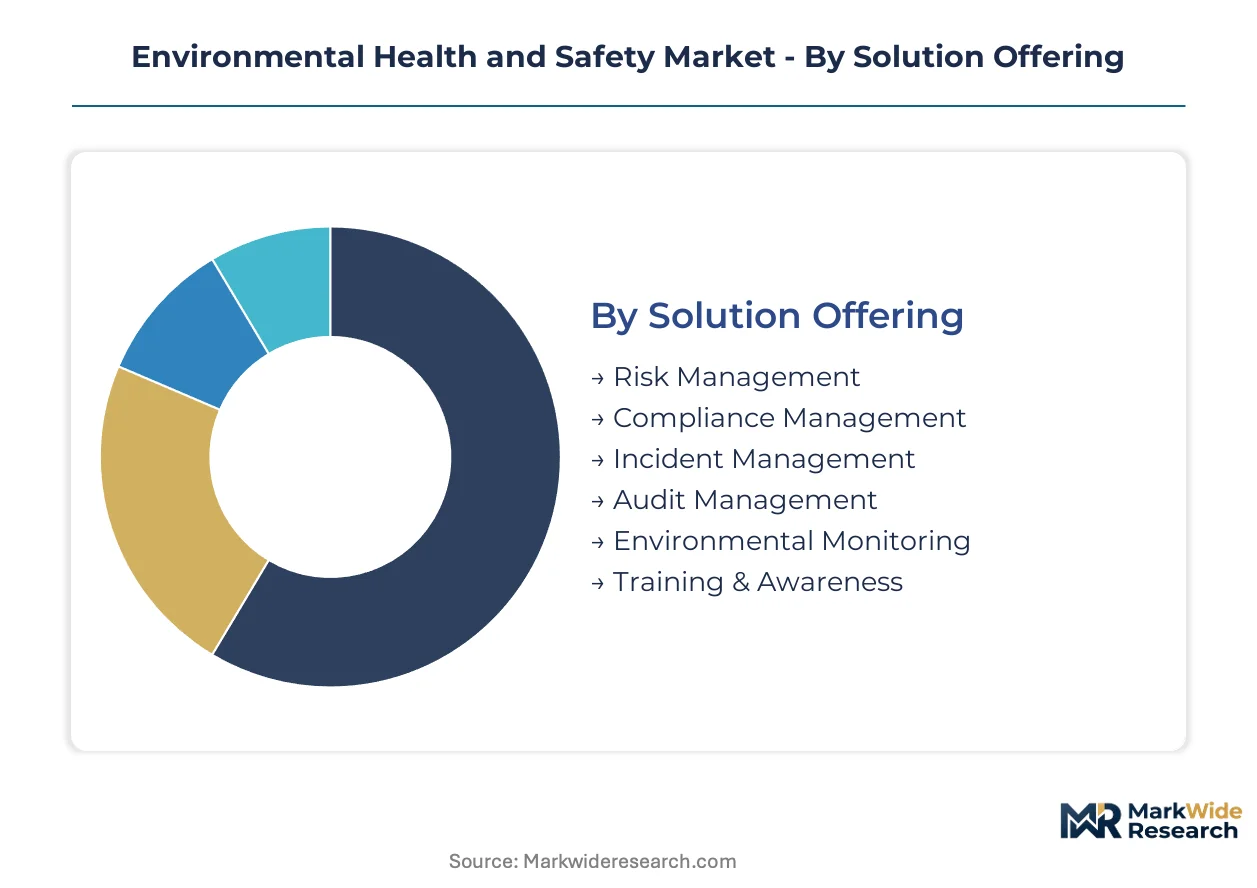
EHS procurement patterns diverge sharply by operational scale and regulatory exposure. Segment-specific buying criteria determine whether facilities prioritize unified platforms or specialized point solutions for targeted compliance domains.
Solution Offering:
Cost tier structures in EHS software separate enterprise-grade governance suites from modular departmental tools.
- Risk Management:Unified governance platforms consolidate fragmented point tools into single data architectures. Demand concentrates among multinational chemical processors navigating overlapping EPA, OSHA, and EU CSRD obligations simultaneously.
- Compliance Management:Automated permit tracking and audit trail documentation for regulatory submissions. Heavy infrastructure clients in Texas and California industrial corridors are upgrading systems to compress documentation cycles under accelerated EPA inspection timelines.
- Incident Management:Real-time reporting workflows with root cause analytics.
- Audit Management:Scheduled inspection protocols with corrective action tracking.
- Environmental Monitoring:Continuous emissions and discharge parameter surveillance.
- Training & Awareness:Certification tracking and competency validation modules.
Risk Management holds installed capacity. Compliance Management is rotating up the share rankings.
Deployment:
Application maturity varies across infrastructure ownership models and IT staffing levels.
- Cloud-Based:Scalable SaaS architectures eliminate capital expenditure treatment and accelerate deployment cycles. Mid-sized manufacturing plants lacking dedicated IT security staff are adopting these platforms fastest for real-time incident reporting capabilities.
- Hybrid:Sensitive operational data remains on-premises while analytics migrate to cloud environments. Chemical processing facilities in the United States favor this model to satisfy OSHA process safety documentation requirements without exposing proprietary process parameters.
- On-Premises:Legacy perpetual licensing with full infrastructure control.
- Managed Services:Outsourced platform administration with outcome-aligned service agreements.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Application Area:
Volume concentration tracks directly to catastrophic loss potential and enforcement intensity by sector.
- Worker Safety:Connected wearables and real-time gas detection networks for occupational hazard prevention. Oilfield services and mining operations generate premium pricing here under MSHA oversight and wrongful death liability exposure.
- Environmental Protection:Air quality, water discharge, and soil contamination monitoring systems. Power generation and cement producers are retrofitting optical gas imaging and Fourier-transform infrared systems to satisfy EPA Clean Air Act continuous emissions monitoring mandates.
- Regulatory Compliance:Permit threshold alerts and automated submission workflows.
- Hazardous Material Management:Chemical inventory tracking and exposure limit enforcement.
- Waste Management:Disposal chain documentation and circular economy metrics.
Worker Safety holds installed capacity. Environmental Protection is rotating up the share rankings.
End User Industry:
Customer type determines whether procurement favors integrated suites or specialized vertical solutions.
- Chemical Processing:Process safety management systems for hazardous reaction documentation and mechanical integrity tracking. United States facilities are accelerating software procurement to satisfy stricter OSHA enforcement protocols.
- Mining Operations:Underground ventilation monitoring and emergency response coordination. Real-time gas detection networks are expanding fastest here due to MSHA fatality prevention mandates and catastrophic loss potential.
- Manufacturing Plants:General occupational health and environmental permit compliance.
- Construction Firms:Site-specific safety protocols and subcontractor certification tracking.
- Oilfield Services:Remote location hazard assessment and blowout prevention systems.
- Utilities:Emissions monitoring and grid infrastructure safety management.
Chemical Processing holds installed capacity. Mining Operations is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity as EPA enforcement actions and state-level climate disclosure laws mandate compliance infrastructure upgrades. Indian chemical and pharmaceutical producers under the PLI scheme show higher sensitivity, prioritizing modular SaaS deployments over enterprise suites. European multinationals face intermediate elasticity as CSRD requirements force system replacements regardless of cost.
United States
OSHA process safety management enforcement drives software procurement at chemical processing facilities along the Texas and Louisiana Gulf Coast. EPA Clean Air Act continuous emissions monitoring mandates require real-time data transmission from stack sensors to federal repositories. Houston and Port Arthur industrial corridors are consolidating fragmented point tools into unified governance platforms that automate permit threshold alerts.
Germany
Heavy infrastructure clients in the Rhine-Ruhr and Bavarian industrial zones anchor demand for integrated EHS modules with climate risk analytics. EU Green Deal and CSRD disclosure requirements extend data collection obligations to supply chain tiers for automotive and chemical exporters. Stuttgart and Munich manufacturing clusters are retrofitting optical gas imaging systems to satisfy enhanced emissions reporting obligations.
China
Dual carbon goals and MEE environmental monitoring mandates accelerate cloud-based deployment adoption among mid-sized manufacturing plants in the Yangtze River Delta. Semiconductor supply concentration in East Asian fabrication clusters creates pricing instability for industrial IoT sensor components. Shanghai and Suzhou industrial parks are digitizing environmental monitoring through plug-and-play air quality arrays feeding cloud analytics dashboards.
India
PLI scheme incentives generate first-time EHS software demand among domestic chemical and pharmaceutical producers in Gujarat and Maharashtra. BIS standards and state-level factory compliance rules compress certification timelines without proportional staffing increases. Ahmedabad and Mumbai manufacturing belts are adopting scalable SaaS architectures to eliminate capital expenditure treatment for compliance technology.
United Kingdom
Post-Brexit regulatory divergence creates demand for hybrid deployment models that satisfy both retained EU environmental standards and emerging UK-specific reporting frameworks. Engineering consultancies with deep infrastructure client relationships leverage climate risk convergence opportunities. London and Midlands industrial regions are embedding nature-positive analytics modules that extend beyond carbon and chemical compliance.
Environmental Health and Safety Market Key Industry Players
Capability concentration sits with engineering consultancies possessing deep infrastructure relationships; scale advantage sits with diversified industrial service conglomerates leveraging installed bases for cross-selling. The market structures around three tiers: unified governance platform providers, specialized risk analytics boutiques, and integrated water-energy-service conglomerates. Dominant competitive moves include portfolio diversification into adjacent climate risk services and strategic partnerships to bridge cloud API integration gaps.
Within the diversified industrial services tier, Ecolab Inc and Xylem Inc exemplify scale-driven positioning through water treatment infrastructure relationships that enable EHS module cross-selling. Among engineering consultancy specialists, WSP Global Inc and ERM occupy positions anchored by heavy infrastructure client access and climate risk analytics embedding. Triumvirate Environmental represents the specialized compliance services archetype focused on hazardous waste and environmental remediation workflows.
| Leading Market Players |
|---|
| Triumvirate Environmental |
| WSP Global Inc |
| ERM |
| Xylem Inc |
| Ecolab Inc |
| BSI Group |
| Inogen Alliance |
| The Phylmar Group |
| EHS Momentum |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta sensor manufacturing clusters anchor global industrial IoT component supply, concentrating pricing power among semiconductor foundries serving EHS platform vendors. Downstream software providers absorb cost volatility through subscription model restructuring that shifts buyer expenditure from capital budgets to operational line items.
Pricing Analysis
After-market service contracts and extended platform support agreements now generate the majority of lifetime customer value in EHS software procurement. Three-tier pricing structure across premium, standard, and economy levels separates enterprise governance suites from departmental point tools and modular SaaS entry packages. Price differentiation hinges on ISO 45001 certification tier and integration complexity with legacy SCADA systems. Cost compression in mid-market SaaS tiers is intensifying because cloud-native entrants compete aggressively on per-seat economics. Chemical processing facilities in Texas and Louisiana exhibit lowest price sensitivity due to OSHA enforcement penalties, while Indian pharmaceutical producers under PLI scheme incentives prioritize lowest total cost of ownership.
Supply Chain Analysis
Contract manufacturing for industrial IoT sensors concentrates among Foxconn Industrial Internet, Jabil, and Flex specialized divisions serving environmental monitoring OEMs. Semiconductor fabrication draws from Taiwan, South Korea, and mainland China foundries, with MEMS gas detection chips and optical gas imaging sensors resting on East Asian wafer capacity. Raw material dependencies span rare earth elements for magnetic sensors, germanium substrates for infrared detectors, and lithium-ion cells for wireless node power. Single-source vulnerability in advanced node semiconductor supply creates procurement risk for real-time emissions monitoring hardware. Distribution runs through authorized industrial automation distributors and direct enterprise sales teams serving Fortune 500 energy and chemical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer consolidation among multinational chemical processors and mining conglomerates is shifting procurement leverage toward unified platform tenders that displace fragmented point solution vendors.
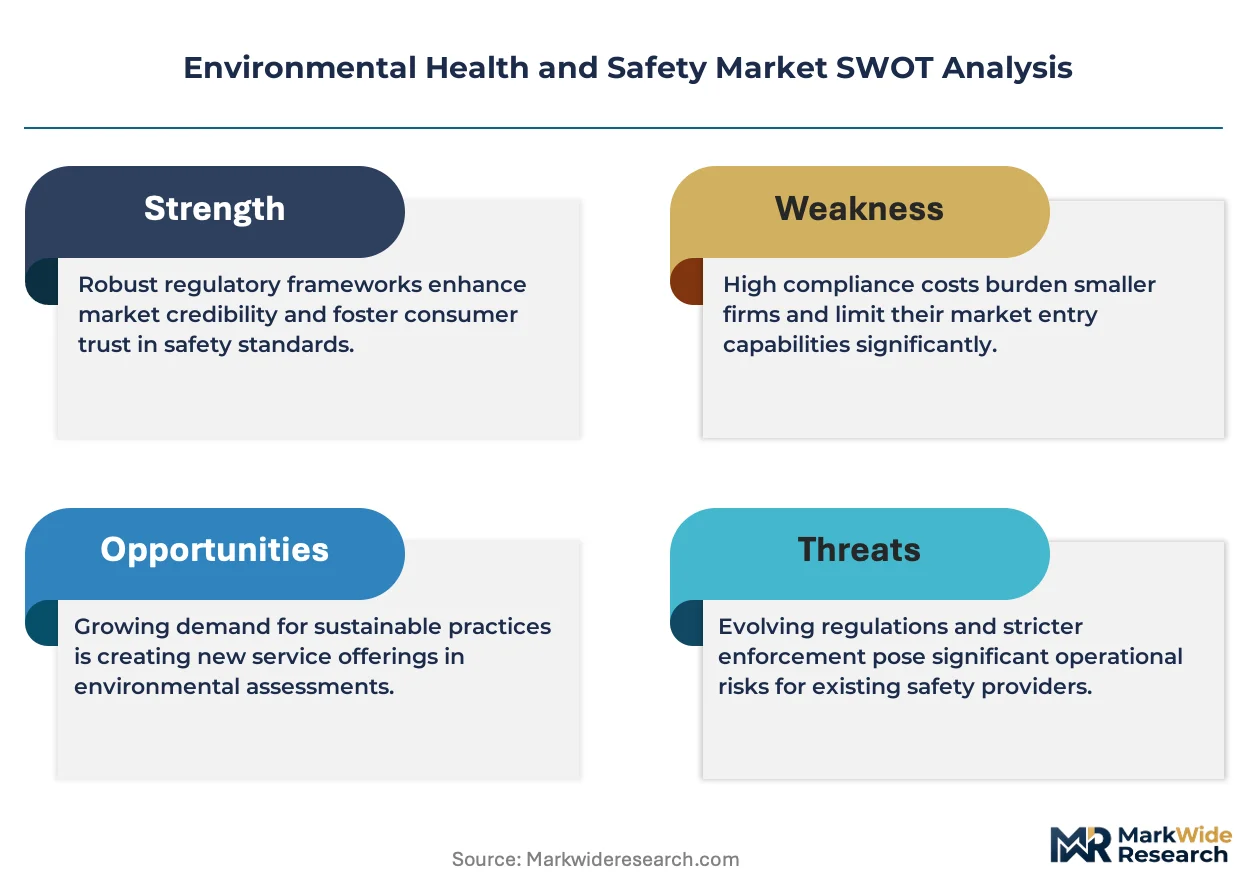
For Market Incumbents: Harden subscription retention through embedded climate risk analytics that increase switching costs for ERM and WSP Global clients. Deepen API integration partnerships with industrial automation leaders to defend against cloud-native entrants. Vertical integration into sensor hardware manufacturing mitigates semiconductor supply concentration exposure threatening delivery timelines. For New Entrants and Emerging Players: Mid-sized manufacturing plants in India's Gujarat and Maharashtra industrial belts represent the most penetrable entry point for first-time EHS software adoption. Biodiversity impact disclosure modules for EU CSRD compliance create immediate product-market fit among automotive exporters. Channel partnerships with industrial engineering consultancies accelerate credibility building without direct enterprise sales investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized risk analytics boutiques with embedded machine learning capabilities over legacy compliance documentation vendors. Long-term viability rests on predictive intervention technology rather than reactive reporting workflows. Acquisition targets should demonstrate proven API architectures enabling rapid integration with incumbent industrial software stacks. The signal to watch is MSHA and EPA enforcement budget allocations as inflection indicator for compliance technology procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified governance platforms consolidate OSHA, EPA, and EU CSRD compliance into single data architectures for chemical processors. |
| Strategic Partnership | Cloud API alliances with industrial automation vendors bridge legacy system integration gaps for mid-sized manufacturing adopters. |
| Acquisition of Specialist Firm | Machine learning boutiques add predictive risk intervention capabilities to reactive compliance documentation portfolios. |
| Geographic Expansion | India PLI scheme incentives generate first-time EHS software demand among domestic chemical and pharmaceutical producers. |
| Product Launch | Biodiversity impact analytics modules address emerging EU nature-positive disclosure requirements beyond carbon compliance. |
Research Approach
The analysis maps cloud deployment platforms, risk management solutions, worker safety applications, and environmental monitoring systems, each validated through EHS software procurement officers, plant safety directors, regulatory compliance managers, and industrial IoT integration specialists. Primary interviews with these stakeholders combine with secondary validation against EPA enforcement databases, OSHA inspection records, EU CSRD regulatory filings, and customs trade data for sensor hardware imports. Bottom-up facility-level demand estimation triangulates against top-down vendor revenue analysis across the projection horizon.
Assumptions around OSHA enforcement intensity, EU Green Deal implementation pace, and cloud migration adoption curves were held fixed while semiconductor supply volatility and MSHA budget allocations were stress-tested. Segmentation dimensions modeled include deployment architecture, solution offering tier, application area, and end-user industry vertical throughout the forecast period. CAGRs derive from regression analysis against historical compliance technology procurement cycles and regulatory deadline clustering. Industry-specific inputs incorporate continuous emissions monitoring system installation mandates and connected wearable device penetration rates in oilfield services.
Practitioners should monitor EPA civil penalty inflation, EU CSRD scope expansion timelines, and East Asian semiconductor export restrictions for early signals requiring forecast revision. Quarterly review of MSHA fatality incident rates and state-level climate disclosure law enactment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
Industrial Noise Control Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Noise Control System Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Global Air Sampling Pumps Market