
 Africa Wheat Protein Market | 2026-2036
Africa Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Wheat Protein Market Outlook
South Africa's Department of Health food fortification regulations is consolidating demand for standardized wheat protein in industrial milling. Cargill Incorporated leverages its grain origination infrastructure across the continent to secure supply chain advantages. Archer Daniels Midland Company sustains processing capabilities that convert regional wheat stocks into protein concentrates. Manildra Group anchors quality-sensitive contracts with Egyptian and Nigerian bakery conglomerates.
Wheat protein comprises gluten fractions extracted from wheat flour through wet-processing separation, yielding products with protein concentrations ranging from 75% to over 90% depending on isolation grade. Its primary commercial purpose centers on providing viscoelastic structure to baked goods and serving as a functional binder in meat alternative formulations. Concentrates dominate volume flows due to cost positioning in mass-market bread applications, while isolates capture premium positioning in nutritional supplements where protein purity thresholds matter. Hydrolyzed variants are gaining traction in beverage sector formulations requiring cold-soluble functionality without turbidity.
Kenya's Bureau of Standards enforces gluten quality parameters that shape import specifications for wheat protein entering East African markets. South Africa's Department of Trade, Industry and Competition applies local content incentives that influence procurement decisions by multinational food manufacturers operating in the region. Egypt's General Organization for Export and Import Control maintains protein content verification protocols for subsidized flour distribution. Stakeholders must monitor how harmonization pressures between national standards bodies and the African Continental Free Trade Area technical committees reshape cross-border product certification requirements.
Market Dynamics
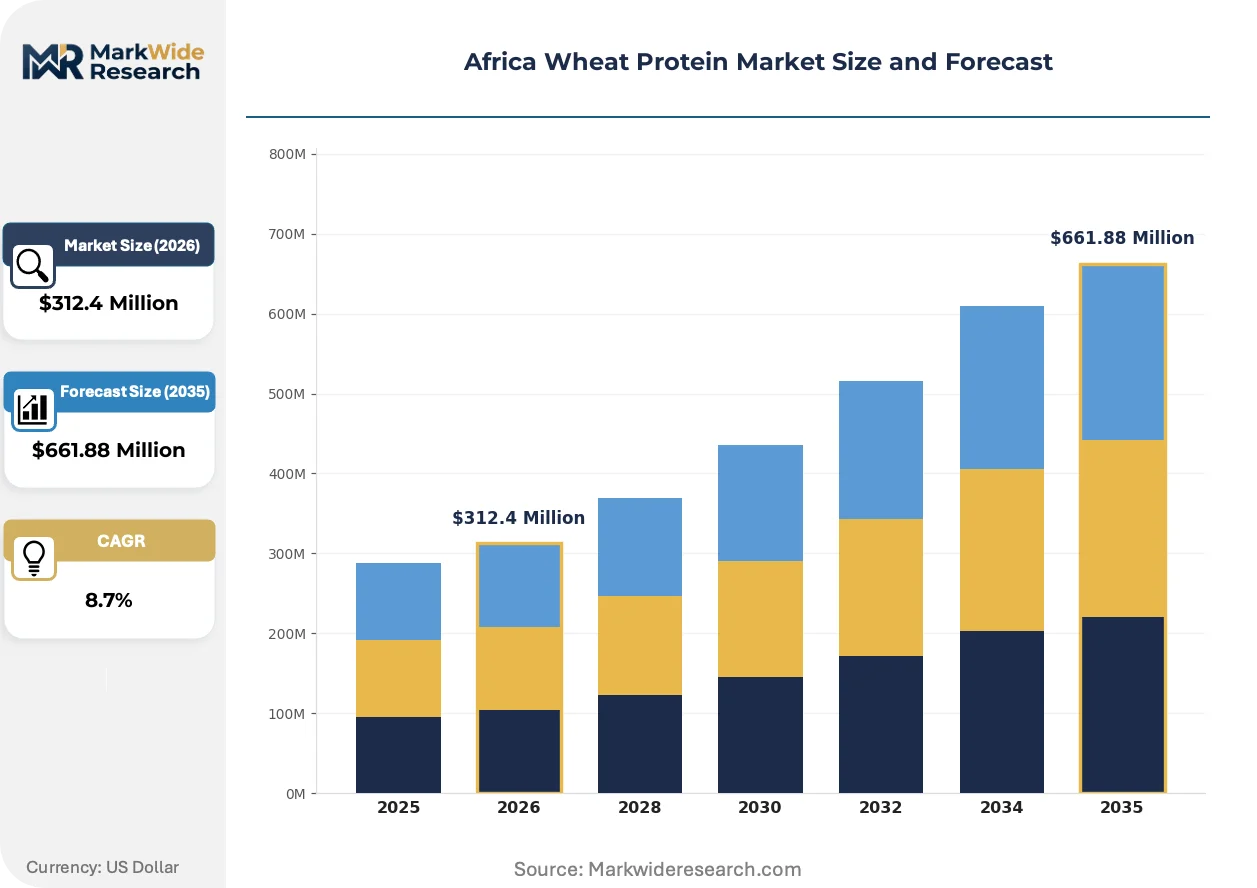
Egypt's subsidized baladi bread program is compressing procurement timelines for industrial wheat protein, forcing suppliers to align with state-controlled flour distribution cycles while Kenya's KEBS gluten mandates and South Africa's fortification rules simultaneously tighten quality thresholds.
Growth Catalysts
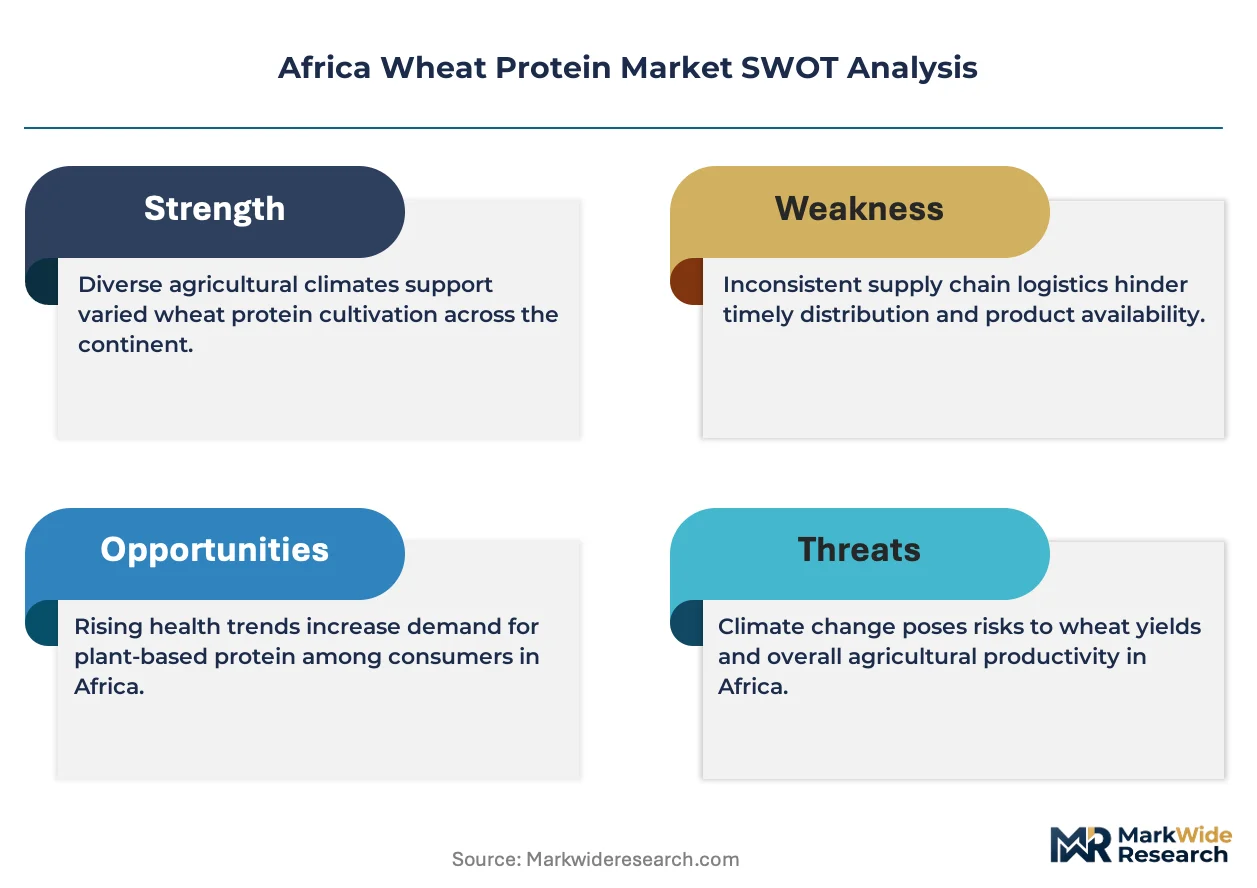
- Clean-label bakery expansion:Nigerian and South African industrial bakers are reformulating bread recipes to eliminate synthetic additives, pulling wheat protein into standard formulations as a natural structuring agent.
- KEBS gluten quality mandates:Kenya's Bureau of Standards enforcement is filtering substandard imports, creating procurement preference for certified protein concentrates meeting specified elasticity parameters.
- Meat alternative R&D pipelines:Food technologists in Egypt and Morocco are testing wheat protein isolates for plant-based sausage and burger applications, opening parallel demand channels beyond traditional baking.
Market Restraints
- Wheat price volatility:Input cost swings tied to Black Sea supply disruptions compress margins for regional protein processors dependent on imported grain stocks.
- Single-origin supply concentration:Wet-processing capacity clusters in Egypt's Nile Delta corridor, exposing buyers to localized production bottlenecks and transport cost spikes.
- Technical substitution threat:Pea and fava bean proteins are gaining traction in South African meat alternative trials, threatening wheat protein's functional positioning in high-hydration applications.
Strategic Opportunities
- Ethiopian milling corridor development:Industrial bakery investment in Addis Ababa and Hawassa is outpacing local protein supply, creating first-mover positioning for external concentrate suppliers.
- Hydrolyzed protein beverages:Cold-soluble wheat protein variants are penetrating Kenyan and Tanzanian sports nutrition channels, displacing whey in lactose-free formulations.
- AfCFTA technical harmonization:African Continental Free Trade Area committee negotiations on food additive standards promise to streamline cross-border certification for compliant suppliers.
Industry Challenges
- Specialized extrusion technician scarcity:Wet-processing plant expansion in Nigeria and Egypt is outpacing trained workforce availability, extending commissioning timelines for new capacity.
- Legacy equipment integration:Retrofitting existing flour mills in Morocco and Algeria with protein separation units requires custom engineering, inflating capex forecasts beyond standardized equipment quotes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Wheat Protein Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Textured, Hydrolyzed Application: Baked Goods, Snacks, Meat Alternatives, Nutritional Supplements End User: Food Industry, Beverage Sector, Nutraceuticals, Animal Feed Form: Powder, Liquid, Granular, Pellet |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Kroener Staerke, Roquette, Manildra Group, Maccallum Pty Ltd, Meelunie BV, Crespel & Deiters GmbH and Co. KG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Wheat Protein Market Strategic Shifts
Processing technology advances and regulatory alignment pressures are restructuring how wheat protein moves from grain origination to finished food applications across African markets.
Enzymatic hydrolysis systems are rewriting the functional range of wheat protein derivatives. Industrial bakeries in Egypt and South Africa are adopting cold-soluble hydrolyzed concentrates for ambient-stable beverage fortification. This enzymatic processing is compressing the traditional divide between baking and beverage-grade protein specifications, allowing single-source suppliers to serve multiple end-use verticals without dedicated production lines.
South Africa's Department of Health food fortification regulations are tightening protein content verification protocols for subsidized flour distribution. Industrial millers must now submit batch-level analytical certificates, increasing testing overhead but filtering informal suppliers from state contract eligibility. Egyptian and Nigerian bakery conglomerates are responding by consolidating procurement around vertically integrated processors capable of in-house laboratory certification.
Direct mill-to-bakery contracting is displacing traditional commodity trading channels in Nigeria's Lagos-Ibadan corridor. Large-scale bread manufacturers are negotiating multi-year protein concentrate supply agreements with Egyptian wet-processors, bypassing Lagos-based distributors. This channel compression is most visible among industrial bakeries serving Nigeria's federal school feeding program, where volume predictability justifies long-term procurement commitments over spot-market flexibility.
Africa Wheat Protein Market Segmentation
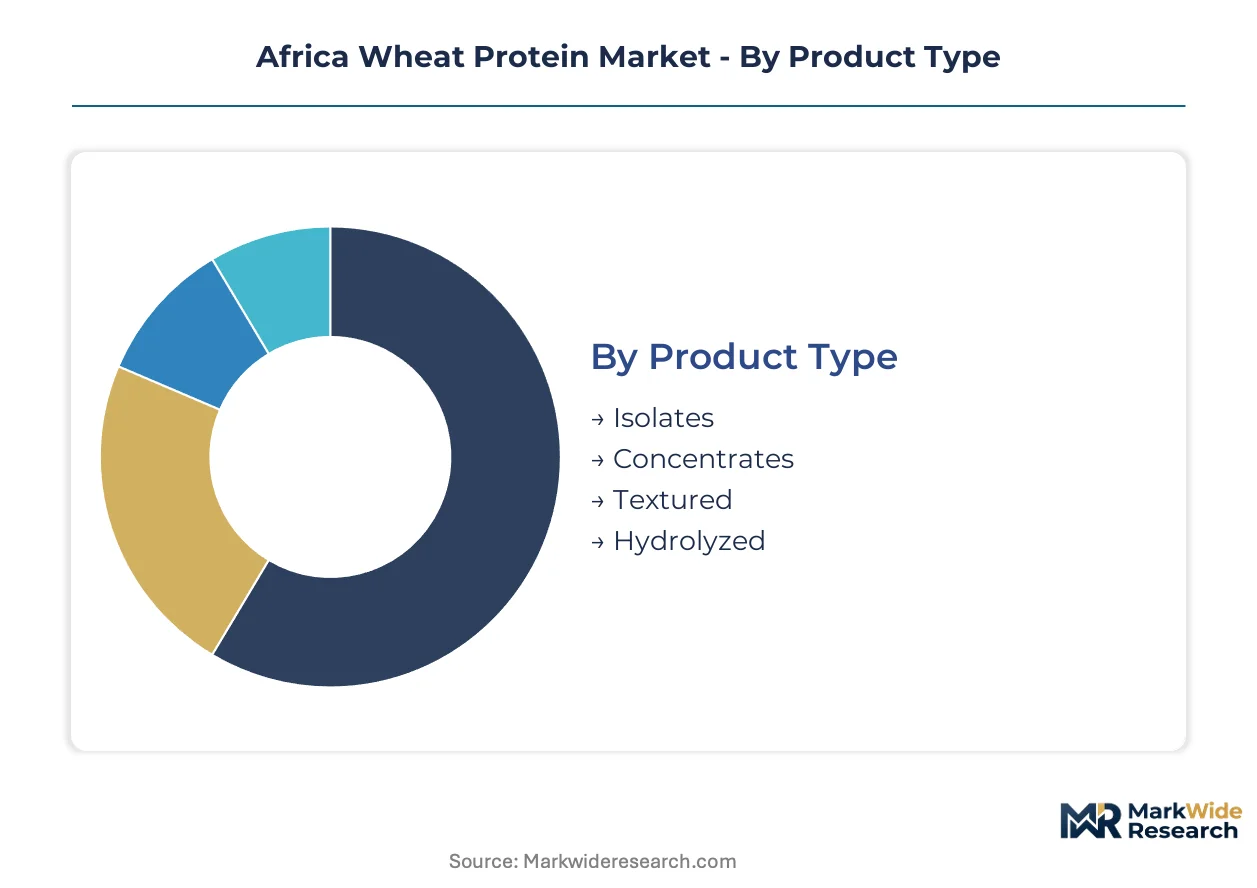
Wheat protein procurement patterns across Africa diverge sharply by processing grade, end-use functionality, and supply chain integration depth. Understanding these splits reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Buyers differentiate primarily by protein purity thresholds and functional performance requirements, with cost tolerance varying dramatically between mass-market bread programs and specialized nutrition formulations.
- Concentrates:Protein fractions ranging from 75% to 85% purity, produced through wet-processing separation of wheat flour. Egyptian baladi bread subsidies and Nigerian industrial bakery contracts absorb the majority of concentrate volumes, with state-controlled flour distribution cycles compressing procurement timelines.
- Isolates:Refined protein exceeding 90% purity through additional purification stages. Moroccan and Egyptian food technologists are testing isolates for plant-based sausage and burger applications, opening parallel demand channels beyond traditional baking with higher margin capture.
- Hydrolyzed:Enzymatically treated for cold-solubility without turbidity. Kenyan and Tanzanian sports nutrition channels are adopting these variants for lactose-free beverage fortification.
- Textured:Extruded forms mimicking meat fiber structure. Limited adoption currently, primarily in South African meat alternative R&D pipelines.
Concentrates lead volumes today; isolates are gaining share fastest.
Application:
End-use segmentation tracks the divergence between heritage wheat consumption patterns and emerging protein diversification trends across North and East Africa.
- Baked Goods:Dominant application spanning subsidized bread programs, industrial bakery chains, and artisanal producers. Egypt's General Organization for Export and Import Control maintains protein content verification protocols that shape procurement specifications for state flour distribution.
- Meat Alternatives:Fastest-expanding vertical as Egyptian and Moroccan manufacturers trial wheat protein for plant-based formulations. Functional requirements center on water-binding capacity and texture retention under thermal processing.
- Snacks:Cracker and biscuit manufacturers in Nigeria and South Africa utilize wheat protein for dough conditioning and shelf-life extension.
- Nutritional Supplements:Premium positioning in sports nutrition and clinical feeding applications, concentrated in South African and Kenyan urban markets.
Baked goods anchor current demand; meat alternatives show the steepest expansion trajectory.
End User:
Customer-type splits reflect the concentration of wheat protein purchasing power among industrial-scale processors versus fragmented downstream channels.
- Food Industry:Encompasses industrial bakeries, confectionery manufacturers, and processed food conglomerates across Nigeria, Egypt, and South Africa. Direct mill-to-bakery contracting is displacing traditional commodity trading channels in Nigeria's Lagos-Ibadan corridor.
- Beverage Sector:Emerging category driven by hydrolyzed protein adoption for ambient-stable fortification. South African health regulations are tightening protein content verification protocols for functional drinks.
- Nutraceuticals:Specialized clinical and sports nutrition segments requiring certified protein grades with batch-level analytical documentation.
- Animal Feed:Residual protein flows from wet-processing operations, primarily consumed by Egyptian and South African livestock operations.
Food industry purchases dominate value capture; beverage sector demand is climbing the fastest.
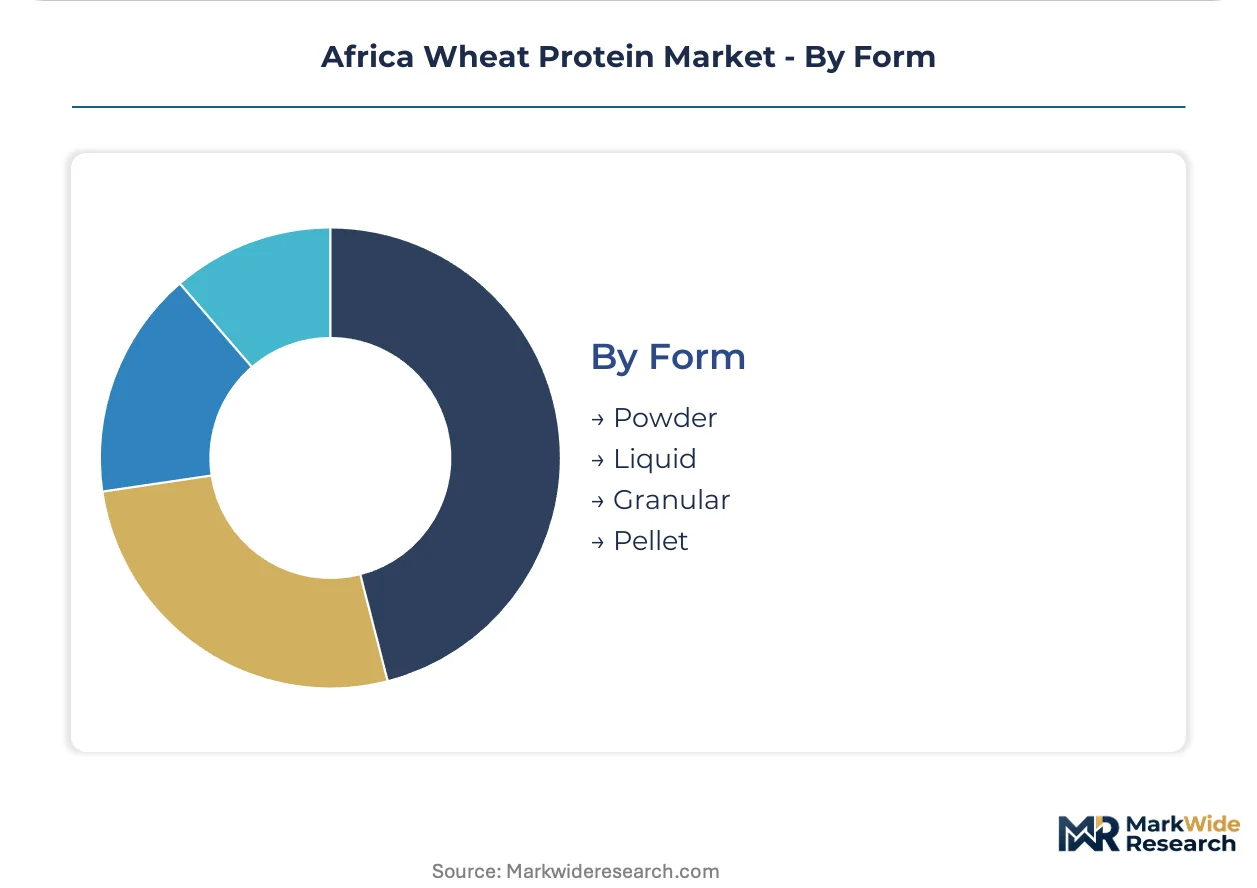
Form:
Physical presentation choices trade off storage economics, handling automation compatibility, and dissolution kinetics for specific manufacturing processes.
- Powder:Standard presentation for bakery and nutritional applications, dominating procurement volumes. Egyptian wet-processors ship bulk powder to Nigerian bakery conglomerates under multi-year supply agreements.
- Liquid:Pre-hydrated forms reducing manufacturing step complexity for beverage and sauce applications. Limited adoption due to shelf stability constraints in ambient African supply chains.
- Granular:Intermediate flowability for automated dosing systems in large-scale milling operations.
- Pellet:Dense form factor for animal feed compounding and select industrial applications requiring reduced dust exposure.
Powder forms command the volume majority; liquid presentations are expanding most quickly in beverage sector trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wheat protein processing first scaled commercially in Egypt's Nile Delta during the 1970s state-led industrialization, establishing wet-processing infrastructure that now supplies protein concentrates across North and East African markets.
Egypt
Egypt's General Organization for Export and Import Control enforces protein content verification for subsidized baladi bread flour distribution. Industrial bakeries in Cairo and Alexandria compress procurement timelines to align with state-controlled distribution cycles. The Nile Delta corridor anchors continental wet-processing capacity, with Egyptian wet-processors shipping bulk concentrates to Nigerian bakery conglomerates.
Nigeria
Federal school feeding program volume predictability justifies multi-year supply agreements between Lagos-Ibadan corridor industrial bakeries and Egyptian protein processors. Direct mill-to-bakery contracting displaces traditional commodity trading channels. Nigeria's federal nutrition initiatives pull wheat protein into standardized bread formulations for institutional procurement.
South Africa
The Department of Health food fortification regulations tighten protein content verification protocols for subsidized flour distribution. Industrial millers submit batch-level analytical certificates, filtering informal suppliers from state contract eligibility. Cape Town and Johannesburg bakery conglomerates consolidate procurement around vertically integrated processors with in-house laboratory certification.
Kenya
KEBS gluten quality mandates filter substandard imports, creating procurement preference for certified protein concentrates meeting specified elasticity parameters. Nairobi and Mombasa industrial bakeries source wheat protein for clean-label bread reformulations. Kenyan sports nutrition channels adopt hydrolyzed variants for lactose-free beverage fortification.
Ethiopia
Industrial bakery investment in Addis Ababa and Hawassa outpaces local protein supply, creating first-mover positioning for external concentrate suppliers. The country's national food regulator develops import specifications as commercial milling capacity expands. Ethiopian milling corridor development attracts regional suppliers seeking volume growth beyond saturated North African markets.
Africa Wheat Protein Market Competitive Environment
Capital-heavy wet-processing operators compete with asset-light trading houses and regional distributors across African wheat protein procurement channels. The vendor base clusters around three tiers: multinational grain processors with origination infrastructure, specialized protein refiners with Egyptian Nile Delta production assets, and regional trading houses facilitating cross-border logistics. Strategic moves center on backward integration into grain origination and multi-year supply contracting with state-linked bakery programs.
Among multinational grain processors, Cargill Incorporated and Archer Daniels Midland Company occupy positions exemplifying integrated origination-to-processing archetypes. Manildra Group anchors quality-sensitive contract relationships with Egyptian and Nigerian bakery conglomerates. These three entities represent distinct competitive vectors: continental grain infrastructure leverage, regional processing scale, and premium-tier customer consolidation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Kroener Staerke |
| Roquette |
| Manildra Group |
| Maccallum Pty Ltd |
| Meelunie BV |
| Crespel & Deiters GmbH and Co. KG |
| Others |
Value Chain & Pricing Dynamics
Kenya's Bureau of Standards gluten quality mandates gate qualified supply for premium-tier wheat protein, compressing procurement options for industrial bakeries while Egyptian Nile Delta wet-processors capture pricing power through certified concentrate exports to Nigerian federal school feeding programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolate-grade protein for Moroccan meat alternative R&D from concentrate flows for Egyptian baladi bread subsidies and residual feed-grade fractions. Price differentiation hinges on KEBS certification status and volume scale under multi-year supply agreements. Cost compression in standard concentrates is intensifying because Black Sea wheat input volatility feeds through to Egyptian wet-processing margins. Federal program contractors in Nigeria show highest price sensitivity; South African sports nutrition formulators purchasing hydrolyzed variants demonstrate lowest.
Supply Chain Analysis
South Africa's Department of Trade, Industry and Competition local content incentives are reshaping sourcing decisions for multinational food manufacturers operating in the region. Wet-processing capacity concentrates in Egypt, with secondary clusters in South Africa and Nigeria. Raw material flows draw from imported Black Sea wheat stocks, enzymatic treatment inputs, and laboratory certification services. Single-origin exposure to Nile Delta production creates vulnerability to localized bottlenecks and transport cost spikes. Distribution runs through direct mill-to-bakery contracting in Nigeria's Lagos-Ibadan corridor and state-linked flour distribution cycles in Egypt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Egyptian wet-processing scale advantages offset Kenyan and Ethiopian logistics premiums for concentrate suppliers targeting East African industrial bakery expansion.
For Market Incumbents: To counter pea and fava bean protein substitution threats in South African meat alternative trials, Cargill and Archer Daniels Midland should deepen backward integration into grain origination infrastructure across the continent while consolidating laboratory certification capabilities to meet tightening South African Department of Health verification protocols.
For New Entrants and Emerging Players: Enter via Ethiopian milling corridor development in Addis Ababa and Hawassa, where industrial bakery investment outpaces local protein supply and first-mover positioning remains available. Target hydrolyzed protein beverage formulations for Kenyan and Tanzanian sports nutrition channels as the most penetrable application. Pursue AfCFTA technical harmonization compliance as the primary go-to-market credential.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale Egyptian wet-processors with Nile Delta production assets because fragmented ownership structures and succession pressures create acquisition opportunities at favorable multiples. Long-term viability centers on captive supply relationships with state-linked bakery programs. Watch AfCFTA committee negotiations on food additive standards as the signal for cross-border certification streamlining.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill leverages continental infrastructure to secure input cost advantages against Black Sea volatility. |
| Multi-Year Supply Agreement Negotiation | Nigerian federal school feeding program contractors lock volume predictability with Egyptian wet-processors. |
| Enzymatic Hydrolysis Capacity Addition | South African processors capture premium positioning in cold-soluble protein for beverage fortification. |
| KEBS Certification Investment | Kenyan industrial bakeries filter substandard imports through compliance with Bureau of Standards mandates. |
| Direct Mill-to-Bakery Channel Development | Lagos-Ibadan corridor manufacturers bypass distributors to compress procurement timelines. |
Study Parameters
Direct dialogue with wet-processing plant managers, procurement leads at Nigerian and Egyptian industrial bakeries, Egyptian General Organization for Export and Import Control officials, and South African Department of Health regulatory affairs specialists grounded qualitative findings. Secondary validation drew from KEBS technical standards documentation, AfCFTA committee negotiation records, Egyptian customs trade data, and SEC filings of multinational grain processors. Bottom-up volume estimates from named production facilities triangulated against top-down demand projections from end-use consumption patterns.
Segment-level outputs across the analysis window reflect modeled splits by protein grade tier, end-use application, customer scale, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy intervention timing and infrastructure commissioning schedules. Forecast inputs incorporated wet-processing capacity expansion timelines, enzymatic hydrolysis technology adoption curves, and state subsidy program budget allocations.
Inputs from production facility operators and regulatory documentation were available through the study window; gaps in real-time Ethiopian import specification development introduce uncertainty bands for East African corridor projections. Forecasts reflect documented assumptions regarding AfCFTA harmonization progress and Black Sea supply stability. A small set of named triggers—KEBS enforcement intensity shifts, Egyptian subsidy program modifications, and South African meat alternative R&D pivot decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
China Rice Market
Grains
Quinoa Flour Market
Grains
United States Rice Market
Grains
Non-Basmati Rice Market
Grains
Egypt Rice Market
Grains
Green Pea Grits Market
Grains
Organic Cereals Market
Grains
Cornmeal Market
Grains
Brown Rice Market
Grains
Asia Pacific Maize Market
Grains
Black Gram Market
Grains
Chickpeas Market
Grains
00 Flour Market
Grains
North America Wheat Market
Grains
Low Fat Rice Market
Grains
Africa Maize Market