
 Mucopolysaccharidosis (MPS) Treatment Market | 2026-2036
Mucopolysaccharidosis (MPS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mucopolysaccharidosis (MPS) Treatment Market Foresight
Aftermarket service revenue for long-term patient monitoring is fragmenting across enzyme infusion management platforms and home care coordination networks. Takeda Pharmaceutical Company Limited anchors the enzyme replacement segment with manufacturing scale across multiple MPS subtypes. BioMarin Pharmaceutical Inc. differentiates through specialized R&D intensity in rare lysosomal storage disorders. Ultragenyx Pharmaceutical Inc. competes by extending geographic reach into underserved markets with novel delivery formulations.
Mucopolysaccharidosis treatment encompasses therapeutic interventions for a group of inherited lysosomal storage disorders characterized by deficient enzymes needed to break down glycosaminoglycans, requiring intravenous or subcutaneous administration of recombinant enzymes or genetic material to halt progressive cellular damage. The primary purpose is to preserve organ function, slow neurodegeneration, and extend life expectancy in pediatric and adult patient populations. Enzyme replacement therapy occupies the dominant revenue position due to established clinical protocols and payer familiarity, while gene therapy represents the fastest-growing segment as one-time curative approaches attract development investment. Subcutaneous delivery modes are gaining traction against intravenous standards because reduced infusion center burden improves adherence and lowers total cost of care.
FDA orphan drug exclusivity provisions and EMA priority medicines designation shape development economics by extending market protection and accelerating review timelines for MPS therapies. The central pharmaceutical regulators in Japan and the United States enforce divergent manufacturing standards that fragment global supply chains for biologics and viral vectors. Stakeholders must monitor how gene therapy durability data reshapes reimbursement negotiations and whether manufacturing scale constraints limit patient access to transformative one-time treatments.
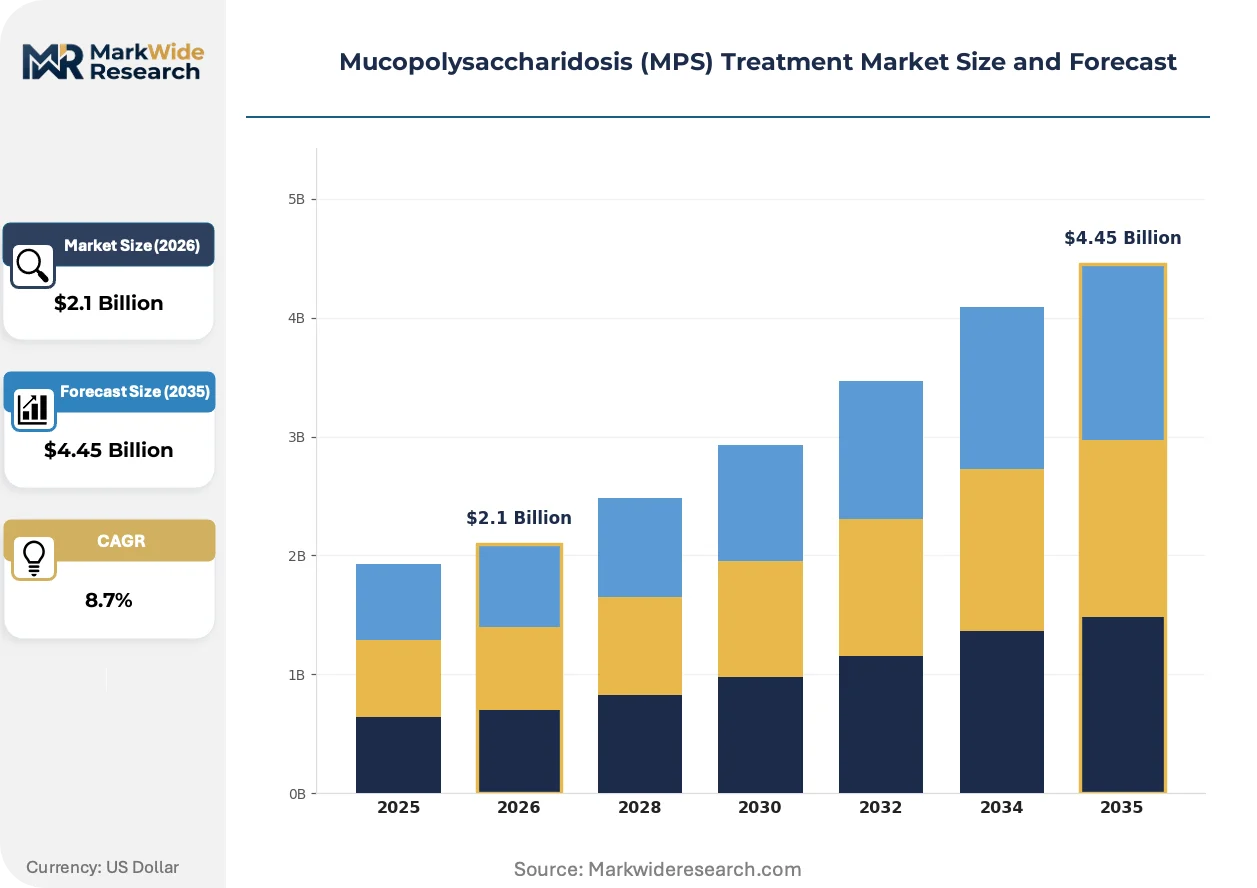
Market Dynamics
The transition from chronic enzyme replacement to one-time gene therapy is restructuring competitive economics, compressing lifetime revenue per patient while demanding massive upfront manufacturing investment and reconfiguring payer negotiation frameworks.
Growth Catalysts
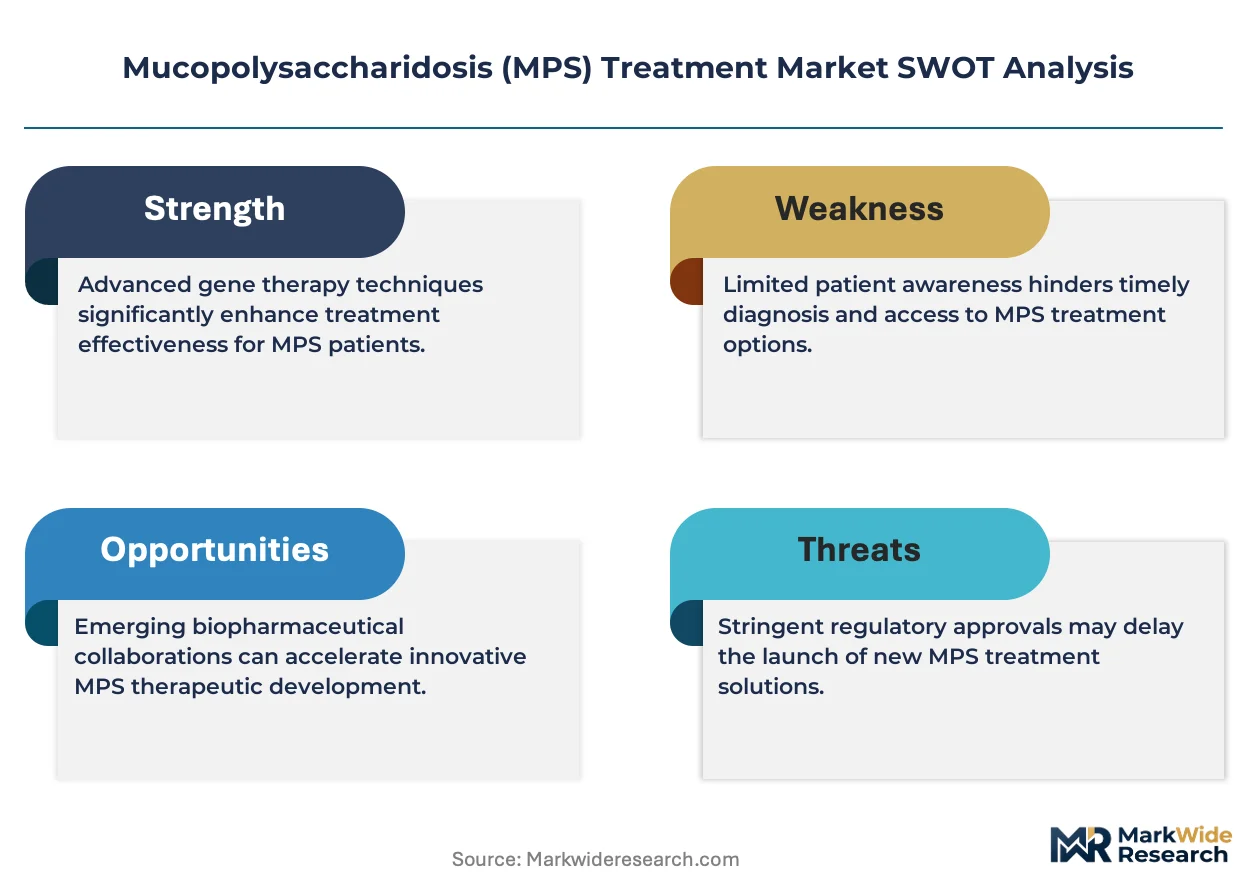
- EMA Priority Medicines Designation:Accelerated review timelines in Europe compress development cycles for novel MPS therapeutics, reducing time-to-market for gene therapy candidates.
- Subcutaneous delivery platforms:Home administration technology eliminates infusion center dependency, expanding addressable patient populations in rural and remote geographies.
- Early diagnosis programs:Newborn screening expansion in the United States identifies pre-symptomatic cases, extending treatment windows and improving therapeutic outcomes.
Market Restraints
- Viral vector manufacturing scarcity:Limited contract development and manufacturing organization capacity for adeno-associated virus production creates multi-year patient access queues for gene therapies.
- FDA orphan drug exclusivity cliffs:Patent protection expiration for established enzyme replacement therapies exposes revenue streams to biosimilar competition without equivalent pipeline depth.
- Reimbursement complexity:Medicaid and private payer divergence on one-time curative therapy valuation methods produces access inequities across state lines.
Strategic Opportunities
- Brazil and Mexico market development:Latin American rare disease networks remain underserved by MPS specialty care, creating first-mover advantages for localized distribution partnerships.
- Neurodegenerative MPS subtypes:Blood-brain barrier penetration technologies open addressable populations previously excluded from peripheral enzyme therapy benefits.
- Japan's regenerative medicine framework:Conditional approval pathways for gene therapies enable earlier commercialization with post-market evidence generation requirements.
Industry Challenges
- Gene therapy durability uncertainty:Long-term expression data gaps complicate payer contracting for single-administration treatments, forcing creative installment-based reimbursement structures.
- Biologics manufacturing talent scarcity:Specialized viral vector production expertise concentrates in Boston and San Diego clusters, constraining geographic diversification of supply networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mucopolysaccharidosis (MPS) Treatment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Gene Therapy, Symptomatic Treatment, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Treatment Stage: Early Intervention, Chronic Management, Advanced Care, Palliative Care |
| Companies Covered | Takeda Pharmaceutical Company Limited, BioMarin Pharmaceutical Inc., Ultragenyx Pharmaceutical Inc., Sanofi, REGENXBIO Inc., Sangamo Therapeutics, Inc., Abeona Therapeutics Inc., JCR Pharmaceuticals Co Ltd., Sarepta Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mucopolysaccharidosis (MPS) Treatment Market Shifts & Advancements
Gene therapy manufacturing scale-up and subcutaneous delivery innovation are converging to transform chronic disease management into acute intervention models, with profound implications for patient adherence economics and healthcare system capacity planning.
Next-generation adeno-associated virus serotypes are collapsing the distinction between peripheral and central nervous system MPS treatment by achieving meaningful brain tissue transduction after intravenous administration. Pediatric neurology centers in the United States are prioritizing these candidates for MPS III and MPS I subtypes with cognitive involvement. The technology is collapsing traditional enrollment barriers for clinical trials by eliminating the need for direct intrathecal delivery.
REACH authorization requirements for viral vector manufacturing in Europe are tightening environmental release controls and supplier qualification standards for gene therapy production facilities. The regulation forces contract manufacturers to invest in closed-system bioreactor technology and enhanced containment infrastructure. Small and mid-cap developers without captive manufacturing are consolidating supplier relationships to secure compliant capacity.
Caregiver burden reduction is driving preference shifts toward home-based subcutaneous enzyme administration over hospital-based intravenous infusion. US commercial payers are embedding home nursing coordination into specialty pharmacy benefit management, displacing traditional site-of-care reimbursement models. The shift is most visible in employer-sponsored insurance plans with high-deductible structures where out-of-pocket cost exposure drives channel selection.
Mucopolysaccharidosis (MPS) Treatment Market Segmentation
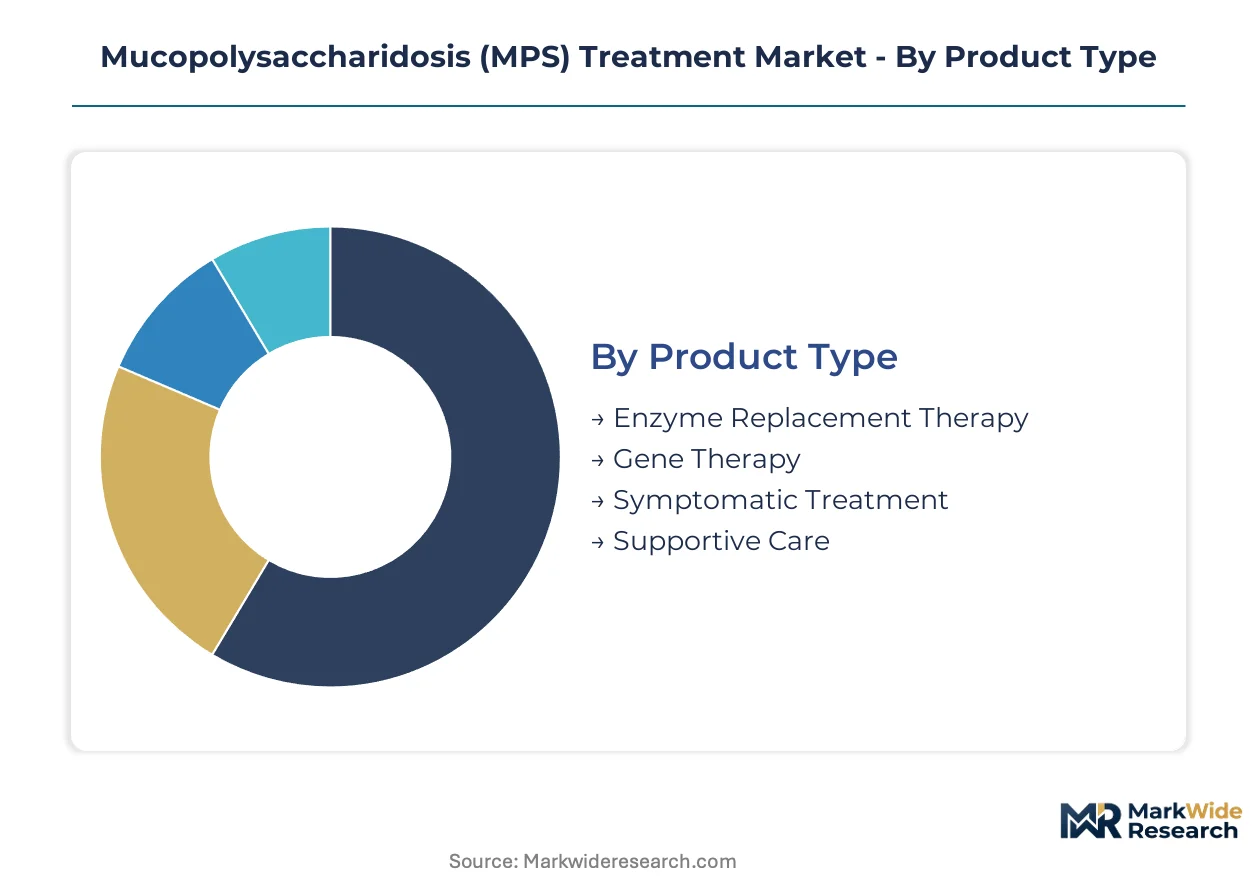
Segmentation in MPS treatment reveals divergent commercial rhythms across therapeutic modalities. Product type cycles span decades for enzyme replacement versus compressed development timelines for gene therapy, while delivery mode turnover reflects shifting site-of-care economics and patient adherence priorities.
Product Type:
Cycle times vary dramatically across therapeutic categories, with chronic administration platforms exhibiting extended revenue stability against one-time intervention models demanding rapid manufacturing scale-up.
- Enzyme Replacement Therapy:Recombinant enzyme formulations delivered via regular infusion protocols constitute the established revenue foundation. Demand concentrates in United States pediatric centers with established infusion infrastructure, constrained by biosimilar exposure as FDA orphan exclusivity periods expire for legacy products.
- Gene Therapy:Single-administration viral vector approaches promise curative outcomes through durable transgene expression. Investment is accelerating in Boston and San Diego bioclusters, limited by multi-year patient access queues stemming from contract manufacturing capacity scarcity for adeno-associated virus production.
- Symptomatic Treatment:Adjunctive therapies addressing pain, mobility, and respiratory complications without modifying disease progression.
- Supportive Care:Multidisciplinary interventions spanning orthopedic surgery, cardiac monitoring, and neurodevelopmental services.
Enzyme Replacement Therapy anchors the volume base while Gene Therapy gains share at the steepest rate.
Delivery Mode:
Cost tier differentiation separates hospital-dependent administration from home-based alternatives, with reimbursement structures determining accessibility across patient populations.
- Intravenous:Infusion center-based delivery remains the clinical standard for enzyme replacement, requiring specialized nursing oversight and facility infrastructure. United States commercial payers increasingly steer volume toward alternative sites through benefit design modifications.
- Subcutaneous:Home administration technology eliminates geographic barriers to treatment access. Employer-sponsored plans with high-deductible structures drive preference shifts through out-of-pocket cost exposure, expanding addressable populations in rural geographies.
- Oral:Investigational small-molecule chaperone therapies targeting specific MPS subtypes with amenable mutations.
- Inhalation:Experimental pulmonary delivery for MPS subtypes with primary respiratory involvement.
Intravenous administration commands the premium reimbursement tier while Subcutaneous delivery is expanding most quickly through payer channel incentives.
End User:
Customer type fragmentation reflects divergent capabilities across the care continuum, from acute intervention to longitudinal disease management.
- Hospitals:Academic medical centers anchor complex case management for MPS I and MPS II subtypes with multi-organ involvement. United States children's hospitals concentrate gene therapy trial enrollment and post-administration monitoring protocols.
- Specialty Clinics:Lysosomal storage disorder centers deliver coordinated care across genetics, orthopedics, and cardiology disciplines. Capacity expansion is visible in metropolitan clusters with established rare disease referral networks.
- Home Care:Nursing coordination and infusion services embedded within specialty pharmacy benefit management.
- Research Institutions:Clinical trial sites driving pipeline advancement for novel modalities.
Hospitals retain the highest-acuity case volume while Specialty Clinics capture expanding chronic management share.
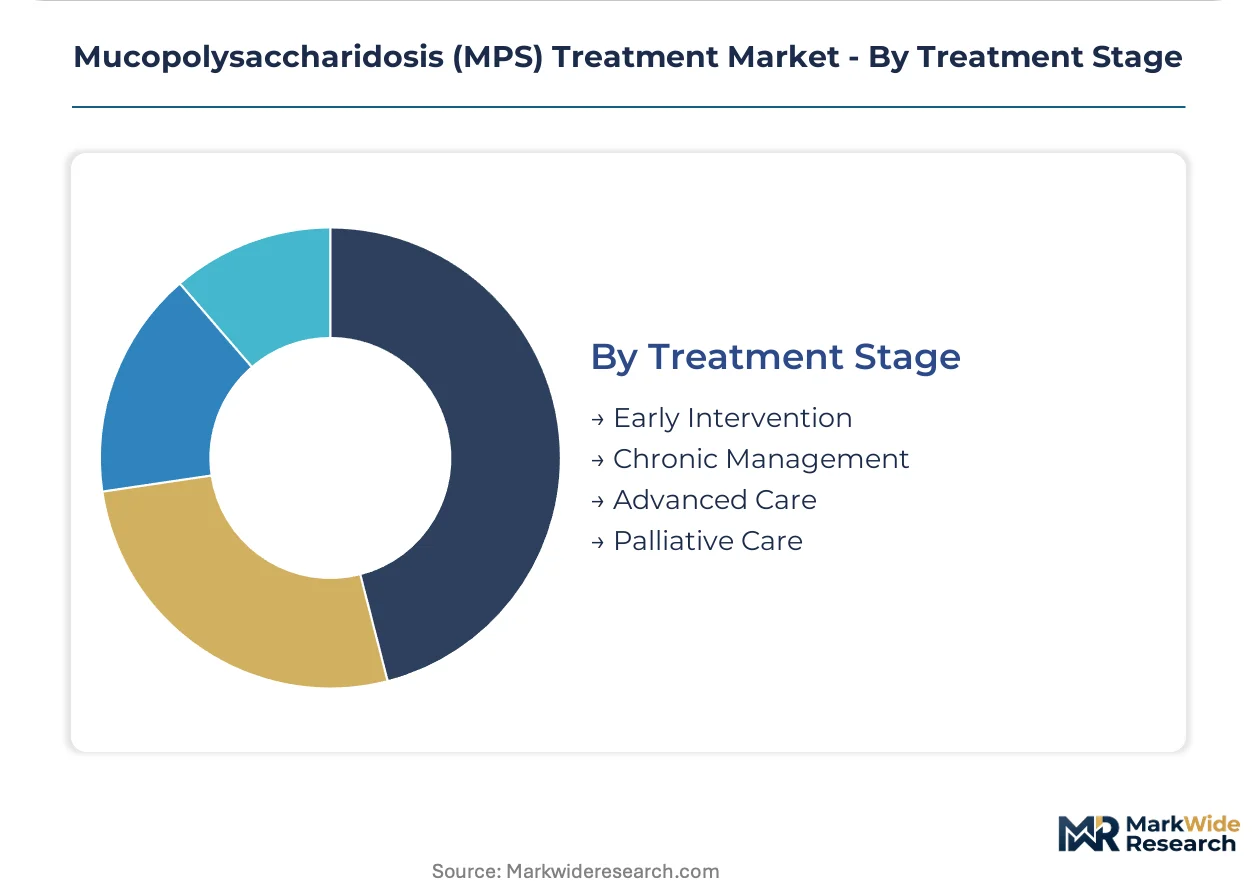
Treatment Stage:
Maturity gradients separate preventive intervention economics from late-stage palliative resource allocation, with newborn screening expansion reshaping stage distribution.
- Early Intervention:Pre-symptomatic or minimally symptomatic initiation following newborn screening identification. United States state-level screening program expansion extends treatment windows and improves therapeutic outcomes for MPS I and MPS II subtypes.
- Chronic Management:Long-term enzyme replacement for established disease with stabilized organ function. Patient volumes concentrate in employer-sponsored insurance plans with mature rare disease benefit structures.
- Advanced Care:Escalated intervention for progressive organ dysfunction despite standard therapy.
- Palliative Care:Symptom-focused support for neurodegenerative MPS subtypes with limited therapeutic options.
Chronic Management represents the largest patient volume today while Early Intervention is climbing the fastest through screening program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity due to entrenched rare disease reimbursement frameworks, while emerging market purchasers face acute cost sensitivity that fragments access patterns across geographies.
United States
Employer-sponsored insurance plans with high-deductible structures drive site-of-care shifts toward home-based administration. FDA orphan drug exclusivity provisions extend market protection for novel therapies, accelerating gene therapy pipeline investment. Boston and San Diego bioclusters concentrate viral vector manufacturing expertise and contract development capacity.
Germany
Statutory health insurance funds maintain comprehensive coverage for enzyme replacement therapies across all MPS subtypes. EMA priority medicines designation enables accelerated review timelines for gene therapy candidates targeting neurodegenerative variants. The Rhine-Main metropolitan region anchors centralized lysosomal storage disorder referral networks with coordinated multidisciplinary care.
Japan
PMDA conditional approval pathways for regenerative medicines enable earlier commercialization of gene therapies with post-market evidence requirements. METI industrial policy supports domestic biologics manufacturing scale-up to reduce import dependency. The Kanto region surrounding Tokyo concentrates pediatric neurology centers and clinical trial enrollment capacity.
Brazil
Price sensitivity in the public health system limits access to high-cost enzyme replacement therapies, creating demand for localized distribution partnerships. ANVISA regulatory harmonization efforts with FDA standards streamline approval pathways for imported biologics. São Paulo state anchors the national rare disease network with specialized lysosomal storage disorder diagnostic capacity.
United Kingdom
NICE technology appraisal processes enforce rigorous cost-effectiveness thresholds that delay access to premium-priced gene therapies. NHS England specialized commissioning frameworks consolidate MPS treatment delivery through designated supraregional centers. The Greater London area concentrates gene therapy trial infrastructure and advanced therapy manufacturing partnerships.
Mucopolysaccharidosis (MPS) Treatment Market Competitive Landscape
Established enzyme replacement specialists and emerging gene therapy developers split the market along modality lines, with manufacturing scale and R&D intensity serving as the primary axes of differentiation. The competitive structure reflects a tiered pattern where large-cap pharmaceutical companies with diversified rare disease portfolios coexist with mid-cap developers focused exclusively on lysosomal storage disorders. Two dominant strategic archetypes prevail: vertically integrated biologics manufacturers with captive production assets, and asset-light developers dependent on contract manufacturing organizations for viral vector supply. Competitive moves concentrate on securing constrained manufacturing capacity through long-term supplier agreements and expanding geographic reach through localized regulatory submissions.
Among the established therapeutic developers, Takeda Pharmaceutical Company Limited and BioMarin Pharmaceutical Inc. occupy positions exemplifying contrasting scale-based archetypes, while Ultragenyx Pharmaceutical Inc. represents the geographic expansion-focused model targeting underserved markets. These three entities anchor the competitive landscape through their respective emphases on manufacturing breadth, R&D specialization, and market access innovation. The remaining competitive set includes Sanofi as a diversified pharmaceutical incumbent, REGENXBIO Inc. and Sangamo Therapeutics, Inc. as gene therapy platform specialists, Abeona Therapeutics Inc. as a clinical-stage developer, JCR Pharmaceuticals Co Ltd. as a Japan-focused regional player, and Sarepta Therapeutics as a neuromuscular and CNS-targeted therapy developer.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| BioMarin Pharmaceutical Inc. |
| Ultragenyx Pharmaceutical Inc. |
| Sanofi |
| REGENXBIO Inc. |
| Sangamo Therapeutics, Inc. |
| Abeona Therapeutics Inc. |
| JCR Pharmaceuticals Co Ltd. |
| Sarepta Therapeutics |
| Others |
Supply & Pricing Matrix
Viral vector manufacturing concentration in Boston and San Diego bioclusters concentrates pricing power with contract development and manufacturing organizations, pushing margin pools downstream toward developers with captive production assets or locked-in supplier agreements.
Pricing Analysis
Aftermarket service revenue from long-term patient monitoring and home care coordination drives lifetime value per MPS patient. Pricing stratifies across premium intravenous infusion protocols, mid-tier subcutaneous home administration, and economy-tier symptomatic management bundles. Cost compression in enzyme replacement stems from biosimilar exposure as FDA orphan exclusivity cliffs approach for legacy products. Medicaid programs exhibit acute price sensitivity due to budget constraints, while United States commercial payers with rare disease carve-outs demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between United States and Chinese biologics equipment suppliers dominates supply chain risk assessment for viral vector production facilities. Adeno-associated virus manufacturing draws from United States, Germany, and Japan for specialized bioreactor systems, purification resins, and quality control instrumentation. Single-source vulnerability concentrates in plasmid DNA supply and cell line banks held by limited contract manufacturers. Distribution runs through specialty pharmacy networks with embedded nursing coordination rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy durability data emergence constitutes a technological inflection reshaping reimbursement negotiations and competitive economics across the MPS treatment landscape.
For Market Incumbents: Harden manufacturing scale advantages through captive viral vector capacity additions in Boston and San Diego bioclusters. Lock in long-term supplier agreements with contract development and manufacturing organizations before queue times extend further. Defend enzyme replacement revenue streams against biosimilar pressure by accelerating subcutaneous formulation transitions that embed patients in home care ecosystems.
For New Entrants and Emerging Players: Brazil and Mexico's underserved rare disease networks offer first-mover positioning through localized distribution partnerships with academic medical centers. Blood-brain barrier penetration technologies for neurodegenerative MPS subtypes represent the most penetrable white space, with pediatric neurology centers actively seeking trial candidates. Pursue Japan's PMDA conditional approval pathway to enable earlier commercialization with post-market evidence generation.
For Investors and Strategic Acquirers: Capital is best deployed toward gene therapy platform specialists with demonstrated brain tissue transduction capabilities and secured manufacturing capacity. Long-term viability in this market hinges on one-time curative durability data that supports installment-based reimbursement structures. Watch for EMA REACH authorization compliance milestones as signals of manufacturing scalability and European market access readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive viral vector capacity secures patient access queues ahead of multi-year contract manufacturing backlogs. |
| Regulatory Approval Pathway | Japan's PMDA conditional approval enables earlier gene therapy commercialization with post-market evidence requirements. |
| Pipeline Diversification | Next-generation adeno-associated virus serotypes collapse peripheral-central nervous system treatment distinctions for MPS III. |
| Strategic Partnership | Localized distribution alliances with São Paulo rare disease networks unlock Latin American market development. |
| Reimbursement Strategy | Installment-based contracting structures address payer uncertainty on single-administration gene therapy durability. |
Research Methodology
The analysis maps enzyme replacement therapies, gene therapy candidates, symptomatic treatments, and supportive care interventions, each validated through drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary interview intelligence triangulates against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient volume estimates and top-down revenue reconciliation anchor segmentation-specific projections.
Fixed assumptions across the analysis window include sustained FDA orphan drug exclusivity provisions, stable EMA priority medicines designation timelines, and continued United States newborn screening expansion. Segmentation dimensions span product type, delivery mode, end user, and treatment stage, with regional regulatory clusters modeled separately. CAGRs derive from patient population growth, pricing trajectory assumptions, and modality shift elasticity. Forecast inputs incorporate viral vector manufacturing capacity constraints and subcutaneous delivery adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing capacity additions by large-cap pharmaceutical companies or breakthrough blood-brain barrier technologies would shift outcomes materially. Gene therapy durability readouts, biosimilar launch timing, and Medicaid reimbursement policy divergence represent specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Dystrophic Epidermolysis Bullosa Treatment Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market