
 North America Printing Machinery Market | 2026-2036
North America Printing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Printing Machinery Market Insights
North American printing press manufacturing is shifting toward digital and hybrid configurations as legacy offset capacity faces retirement waves. HP Inc leverages its PageWide inkjet architecture to anchor high-volume commercial contracts in the United States. Xerox Holdings Corp sustains channel dominance through managed print services that bundle hardware with software workflows. Canon Inc competes aggressively in the label and packaging segment with UV-cured inkjet systems designed for narrow-web converters.
Printing machinery encompasses equipment that transfers ink or toner onto substrates through mechanical impression, digital deposition, or additive layer formation, with systems rated by resolution measured in dots per inch, print speed in impressions per minute, and substrate width compatibility. These machines serve commercial communication, product decoration, and industrial marking across paper, film, textile, and three-dimensional object surfaces. Digital printers now capture the fastest expansion as run lengths shorten and versioned content multiplies, while offset printers retain margin pools in long-run publication work where amortized plate costs preserve unit economics. Flexographic printers occupy a structural middle ground in corrugated and flexible packaging, where water-based ink formulations respond to food-contact compliance pressures.
EPA emissions regulations constrain solvent-based ink systems and drying processes, pushing OEMs toward water-based and UV-cured alternatives that reduce volatile organic compound releases. OSHA machine guarding standards and noise exposure limits shape equipment design, particularly in high-speed web offset and rotogravure installations where operator proximity demands integrated safety interlocks. NIST calibration protocols and ANSI press safety standards further define market access thresholds for new equipment introductions. Stakeholders must monitor how state-level extended producer responsibility laws in California and New York reshape packaging print specifications and equipment upgrade cycles.
Market Dynamics
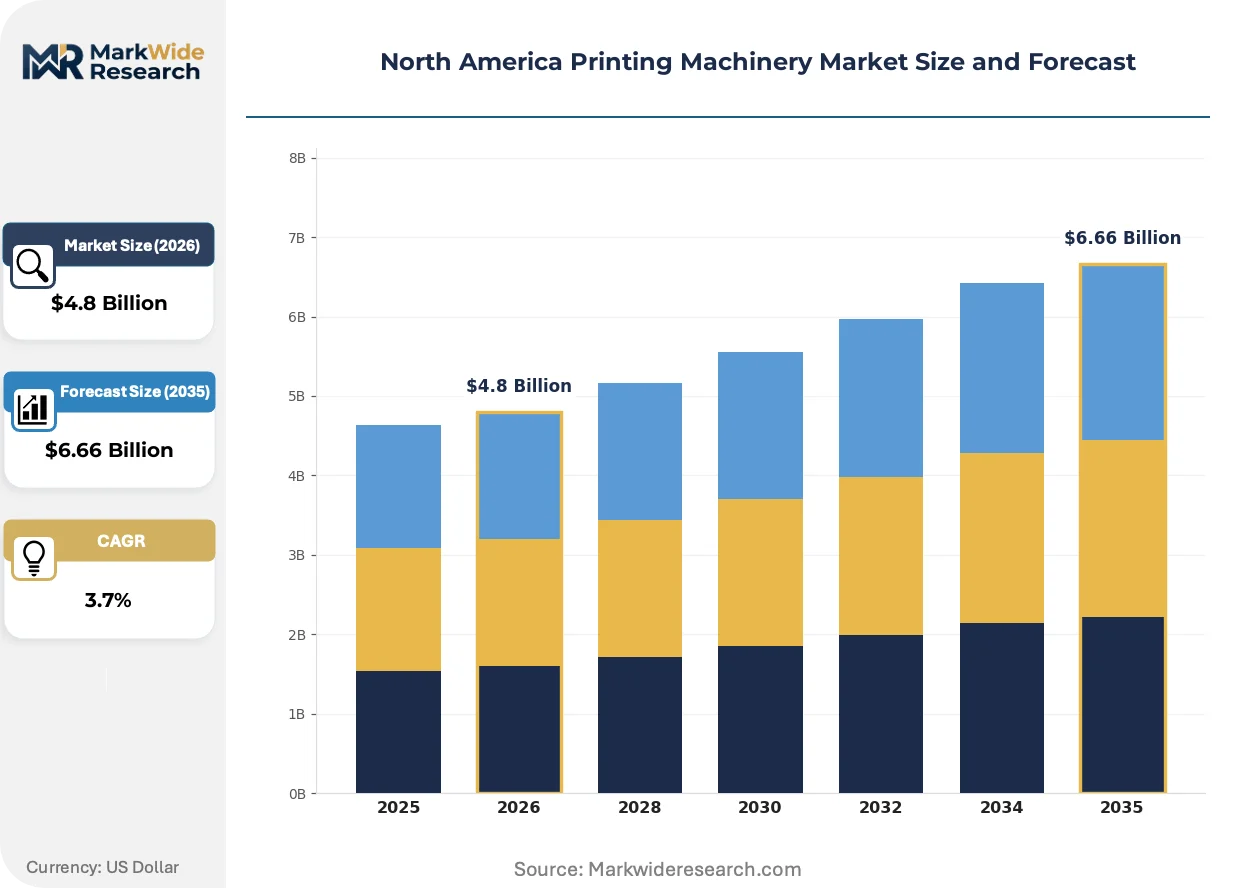
Digital inkjet technology is absorbing run-length compression across North American commercial print, while EPA volatile organic compound regulations force drying-system retrofits that reshape capital allocation timelines for converters.
Growth Catalysts
- EPA Emissions Standards:Federal caps on solvent-based ink volatile organic compounds accelerate water-based and UV-cured system upgrades across corrugated and flexible packaging lines.
- Automotive supply chain labeling:Traceability mandates for parts and components sustain demand for high-resolution variable-data printing in Michigan and Ontario manufacturing clusters.
- Versioned content proliferation:E-commerce packaging personalization requirements pull digital press capacity expansion among contract packagers serving direct-to-consumer brands.
Market Restraints
- Copper and rare-earth magnet supply concentration:Servo motor and precision drive component sourcing from concentrated Asian suppliers creates lead-time vulnerability for domestic press builders.
- Technical limitation in substrate breadth:Digital inkjet systems remain constrained on untreated corrugated and certain synthetic films where offset and flexographic chemistries retain performance advantages.
- OSHA noise exposure compliance:Retrofit costs for acoustic enclosures and vibration damping on legacy high-speed web presses compress upgrade ROI calculations for independent commercial printers.
Strategic Opportunities
- Canadian prairie agricultural packaging:Underpenetrated demand for short-run seed and crop-input bag printing creates white space for narrow-web flexographic and digital hybrid installations.
- California extended producer responsibility laws:State-mandated recycled content thresholds for packaging substrates drive equipment upgrades capable of handling lower-grade, higher-variability paper stocks.
- Industrial IoT convergence:Integration of machine vision inspection with cloud-based predictive maintenance platforms enables outcome-based service contracts that capture recurring revenue streams.
Industry Challenges
- Electromechanical technician scarcity:Retirement waves among skilled press mechanics trained on mechanical cam and gear systems outpace vocational program output for mechatronics-qualified replacements.
- Legacy MIS/ERP integration complexity:Digital press workflow software requires costly middleware development to synchronize with decades-old print shop management systems still prevalent among mid-market commercial printers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Printing Machinery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printers, Offset Printers, Flexographic Printers, Gravure Printers End User: Publishing, Packaging, Commercial Printing, Textiles Technology: Inkjet, Laser, UV, 3D Printing Application: Advertising, Labeling, Signage, Business Cards |
| Companies Covered | HP Inc, Canon Inc, Xerox Holdings Corp, Komori Corp, Heidelberger Druckmaschinen AG, Zebra Technologies Corp, 3D Systems Corp, Manroland Goss Web Systems GmbH, Koenig & Bauer AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Printing Machinery Market Trends and Innovations
Hardware-software bundling is restructuring competitive positioning as OEMs capture margin through recurring workflow subscriptions rather than equipment sales alone.
Single-pass inkjet arrays are absorbing impression-volume that previously flowed to offset perfecting presses. Catalog and direct-mail producers in the Upper Midwest are deploying these systems at replacement-cycle velocity. The technology is absorbing run-length thresholds below ten thousand impressions that previously sustained small-format offset profitability pools.
OSHA machine guarding standards are tightening interlock requirements on web-fed equipment. Press manufacturers must now engineer light-curtain and two-hand control systems into new builds rather than retrofitting field installations. High-speed newspaper and publication gravure facilities in the Great Lakes corridor face the steepest compliance timelines.
Converter procurement patterns are fragmenting as brand owners unbundle specification authority from volume aggregation. Individual plant managers at regional packaging subsidiaries now source presses directly, bypassing corporate capital committees. This disintermediation concentrates in food and beverage contract packaging networks across Texas and the Southeast.
North America Printing Machinery Market Segmentation
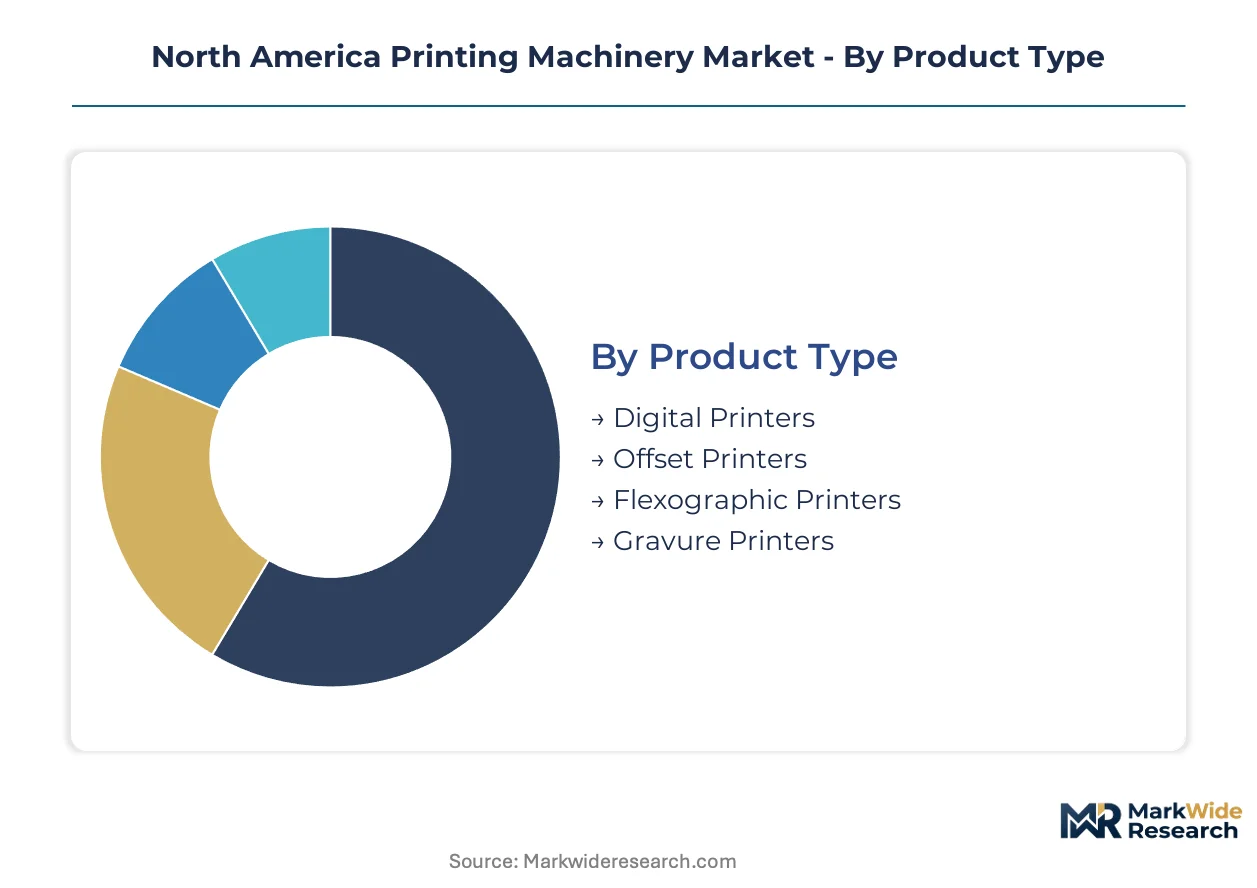
Segmentation reveals how North American converters allocate capital across competing print technologies. Equipment choices reflect run-length economics, substrate versatility, and regulatory compliance pressures that vary sharply by end-use vertical.
Product Type:
Customization intensity spans from configurable digital engines to highly standardized offset platforms engineered for decade-long depreciation cycles.
- Digital Printers:Inkjet and electrophotographic systems deposit toner or liquid ink without mechanical impression cylinders. Demand concentrates among e-commerce contract packagers in Texas and the Southeast, where versioned corrugated and personalized direct-mail requirements compress run lengths below offset breakeven thresholds.
- Offset Printers:Lithographic sheetfed and web-fed systems transfer ink from plate to blanket to substrate with amortized tooling costs. Long-run publication work in the US Great Lakes corridor sustains installed base utilization, though retirement waves are accelerating as commercial printers defer replacement capital.
- Flexographic Printers:Rotary relief printing with photopolymer plates and anilox metering rolls dominates corrugated board and flexible film applications.
- Gravure Printers:Engraved cylinder intaglio systems retain niche dominance in high-volume decorative packaging and security printing where ink laydown consistency justifies cylinder manufacturing lead times.
Most installed capacity flows through Offset Printers. Expansion is steepest in Digital Printers.
End User:
Margin structures diverge across customer types, from consolidated multinational packaging converters to fragmented commercial print shops operating on equipment financing.
- Packaging:Corrugated, flexible film, and label converters serving food, beverage, and pharmaceutical brand owners. California extended producer responsibility mandates and Michigan automotive traceability labeling sustain equipment refresh cycles despite interest rate headwinds.
- Commercial Printing:General communication printers producing marketing collateral, direct mail, and transactional documents. Catalog producers in the Upper Midwest are retiring small-format offset in favor of single-pass inkjet arrays.
- Publishing:Newspaper and book manufacturers facing secular volume decline. EPA volatile organic compound regulations on heatset web offset drying systems accelerate facility consolidation.
- Textiles:Direct-to-garment and roll-to-roll fabric decorators serving fashion and interior design markets.
Revenue concentration sits with Packaging. Technology transition velocity peaks in Commercial Printing.
Technology:
Capital intensity and operating cost structures separate aqueous inkjet platforms from energy-intensive laser and UV curing architectures.
- Inkjet:Piezoelectric and thermal drop-on-demand deposition enables non-contact printing across porous and coated substrates. Narrow-web label converters in Ontario and Quebec are standardizing on UV-cured inkjet for short-run pharmaceutical and nutraceutical packaging.
- Laser:Electrophotographic imaging with dry toner fusing retains speed advantages in monochrome transaction printing and certain security applications.
- UV:Ultraviolet curing systems instantaneously polymerize inks and coatings, eliminating volatile organic compound emissions and enabling direct printing on non-porous synthetics. EPA compliance deadlines are accelerating adoption across flexible packaging lines.
- 3D Printing:Additive layer fabrication for prototyping, tooling, and limited production runs in industrial and medical device markets.
Unit installation volume favors Inkjet. UV technology is climbing the fastest as regulatory pressure compounds with substrate versatility requirements.
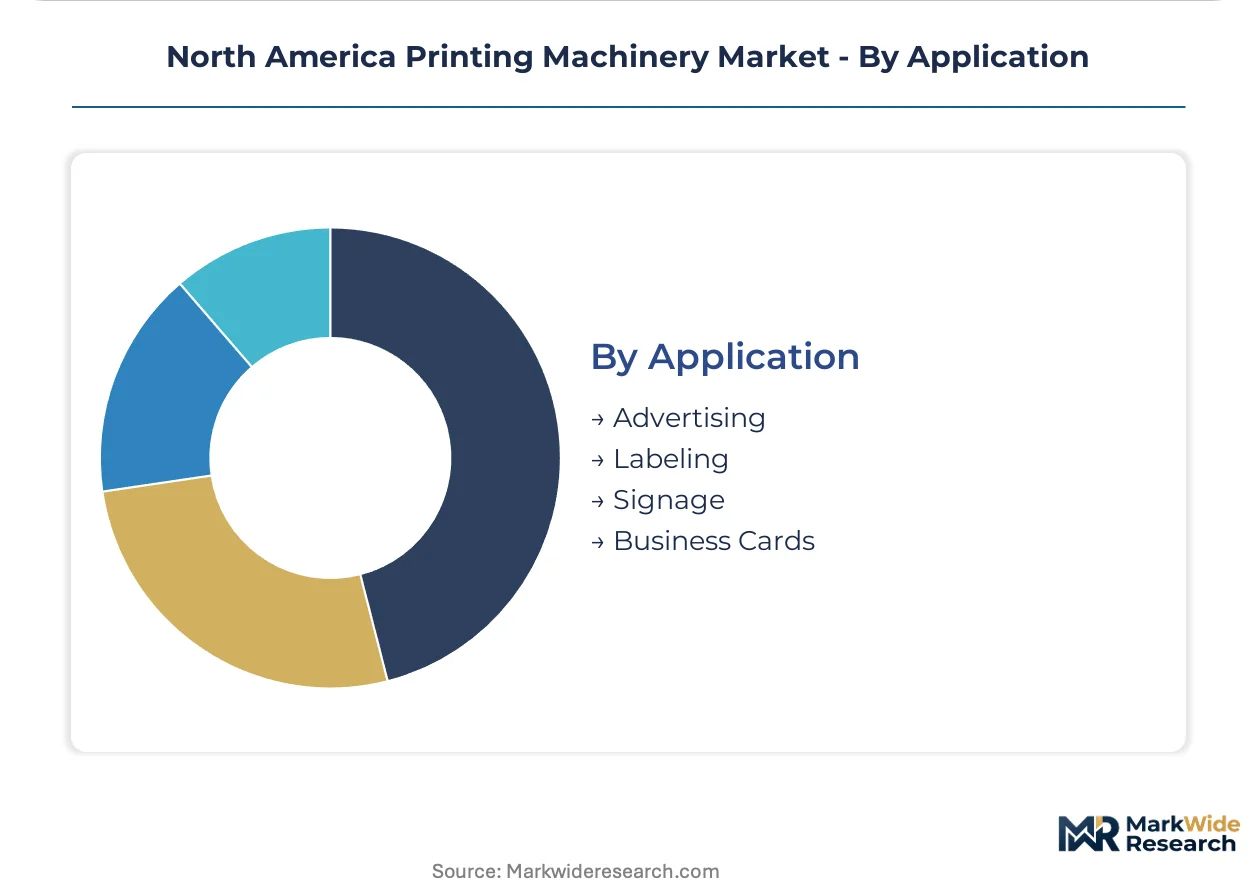
Application:
Specification authority fragmentation reshapes procurement patterns, with brand owners unbundling design standards from volume aggregation decisions.
- Labeling:Pressure-sensitive, shrink-sleeve, and in-mold labels requiring variable-data serialization for supply chain traceability. Automotive parts manufacturers in Michigan and Ontario mandate high-resolution 2D codes driving press specification.
- Advertising:Point-of-sale displays, outdoor signage, and promotional materials. Retail network regionalization demands shorter-run, faster-turnaround production.
- Signage:Wide-format rigid and flexible substrates for retail, construction, and event markets.
- Business Cards:Premium and standard stationery products facing digital substitution pressure.
Specification complexity concentrates in Labeling. Procurement decentralization is most pronounced in Advertising.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's prairie provinces generate specialized packaging demand for agricultural inputs, while the United States concentrates three-quarters of regional installed press capacity across industrial corridors.
United States
Automotive traceability mandates from Michigan manufacturers sustain demand for high-resolution variable-data printing systems. EPA volatile organic compound caps on solvent-based inks accelerate water-based and UV-cured retrofits across Ohio and Illinois corrugated lines. The Great Lakes industrial corridor hosts dense clusters of contract packagers serving direct-to-consumer brands with versioned content requirements.
Canada
Ontario and Quebec label converters standardize on UV-cured inkjet for short-run pharmaceutical packaging serving Health Canada-regulated supply chains. PMRA compliance deadlines for agricultural product labeling drive equipment refresh cycles in Prairie Province seed bag operations. Toronto and Montreal metropolitan areas concentrate narrow-web flexographic and digital hybrid installations for nutraceutical exports.
Mexico
Nearshoring relocation of US consumer goods manufacturing expands demand for corrugated and flexible packaging machinery across Nuevo León and Jalisco. Mexican environmental regulations under SEMARNAT tighten emissions monitoring on solvent-based flexographic lines in the Bajío Region. Mexico City Metro area print service clusters feed automotive component labeling for US-Mexico-Canada Agreement supply chains.
North America Printing Machinery Market Competitive Landscape
United States-based technology conglomerates anchor one tier; German and Japanese precision engineering specialists hold differentiated positions in high-volume web and sheetfed offset configurations. The vendor structure concentrates around three strategic archetypes: diversified electronics manufacturers leveraging hardware-software bundling, pure-play printing equipment builders defending installed base service revenues, and industrial automation integrators capturing workflow software attach rates. Dominant competitive moves include vertical integration into consumables supply and geographic expansion through distributor network acquisition.
Among diversified technology manufacturers, HP Inc and Canon Inc exemplify the hardware-software bundling archetype, while Xerox Holdings Corp occupies a position within managed print services integration. Heidelberger Druckmaschinen AG and Koenig & Bauer AG represent German precision engineering heritage in sheetfed and web offset configurations. Komori Corp and Manroland Goss Web Systems GmbH anchor specialized positions in high-speed publication and packaging gravure systems.
| Leading Market Players |
|---|
| HP Inc |
| Canon Inc |
| Xerox Holdings Corp |
| Komori Corp |
| Heidelberger Druckmaschinen AG |
| Zebra Technologies Corp |
| 3D Systems Corp |
| Manroland Goss Web Systems GmbH |
| Koenig & Bauer AG |
| Others |
Pricing and Supply Chain Analysis
Mechatronics-qualified press mechanics concentrated in the US Great Lakes industrial corridor command wage premiums that widen spreads between premium-tier OEM service contracts and economy-tier independent maintenance arrangements. Labor-cost differentials between unionized technical workforces in Michigan and non-unionized technicians in the Southeast feed directly into three-tier pricing stratification across digital press installations.
Pricing Analysis
Capacity additions in Texas and the Southeast are reshaping price floors for mid-range digital inkjet systems as regional contract packagers expand fleet footprints. Three-tier pricing structure across premium, standard, and economy levels separates HP Inc and Canon Inc bundled workflow subscriptions from independent hardware resellers and gray-market refurbishment operators. Price differentiation hinges on software attach rates and EPA-compliant UV curing certification tiers. Cost compression in economy-tier sheetfed offset is intensifying because retirement-wave asset liquidations flood secondary markets with depreciated presses. Independent commercial printers in the Upper Midwest exhibit highest price sensitivity, while pharmaceutical label converters in Ontario demonstrate lowest sensitivity due to Health Canada validation requirements.
Supply Chain Analysis
Domestic-content mandates under the US-Mexico-Canada Agreement are reshaping sourcing patterns for servo motors and precision drive assemblies. Component supply concentrates in China, Japan, and Germany for rare-earth magnets, piezoelectric printheads, and precision linear motion systems. Raw material dependencies span copper windings, neodymium permanent magnets, and photopolymer plate substrates. Single-source vulnerability in thermal inkjet printhead fabrication creates lead-time exposure for narrow-web label press builders. Distribution runs through authorized dealer networks for capital equipment, with consumables flowing via direct OEM channels and third-party chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American printing machinery functions as a regulatory compounder where EPA volatile organic compound caps and OSHA machine guarding standards perpetually refresh equipment replacement cycles. California extended producer responsibility laws represent the most consequential near-term milestone, mandating recycled-content handling capabilities that obsolete legacy press configurations.
For Market Incumbents: Hedge against single-pass inkjet displacement by anchoring service revenue through predictive maintenance platform subscriptions. Deepen backward integration into UV-cured ink formulations to capture recurring consumables margin. Prioritize certification investment for California and New York extended producer responsibility compliance to lock out non-compliant competitors.
For New Entrants and Emerging Players: Begin with underpenetrated Canadian prairie agricultural packaging, where short-run seed bag printing lacks digital hybrid capacity. Target narrow-web flexographic retrofits in Manitoba and Saskatchewan where PMRA labeling deadlines concentrate demand. Pursue equipment-as-a-service go-to-market models that bundle hardware with regulatory compliance consulting.
For Investors and Strategic Acquirers: Industrial automation conglomerates with existing machine vision capabilities are the most active acquirer in this space, seeking workflow software attach rates. Five-to-ten year viability favors targets with captive consumables supply and installed base service density. Monitor California Air Resources Board enforcement actions as the critical inflection signal for accelerated water-based system adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| UV Curing System Retrofit | EPA compliance deadlines in Ohio and Illinois corrugated lines accelerate capital deployment. |
| Workflow Software Bundling | HP Inc and Xerox Holdings Corp capture recurring revenue through cloud-based print management platforms. |
| Predictive Maintenance Platform | Machine vision integration enables outcome-based service contracts with automotive label converters. |
| Consumables Backward Integration | In-house UV ink production insulates margin from raw material volatility in photoinitiator supply. |
| Prairie Province Distribution Expansion | Dealer network acquisition in Alberta and Saskatchewan captures agricultural packaging refresh cycles. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The research combines structured interviews with OEM product managers, contract packaging procurement directors, and commercial print shop owners with secondary validation. Secondary sources include EPA enforcement databases, OSHA machine guarding standard updates, USITC trade flow records, and SEC 10-K equipment revenue disclosures. Bottom-up press installation counts triangulate against top-down capital expenditure surveys from corrugated and flexible packaging trade associations.
Granularity-level modeling disaggregates volume and value across product type, end user, technology, and application dimensions, with additional segmentation by regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis, regulatory compliance deadline mapping, and run-length compression trajectory modeling. Forecast inputs incorporate EPA volatile organic compound phase-out schedules and extended producer responsibility law implementation timelines across California, New York, and Canadian provinces.
Several conditions sit outside the modeled scope, including hypothetical federal carbon pricing legislation, breakthrough substrate technologies enabling untreated corrugated inkjet printing, and major trade agreement renegotiations. Forecasts reflect documented assumptions regarding interest rate stability and copper price bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Flow Wrapper Market