
 North America Corrugated Board Packaging Market | 2026-2036
North America Corrugated Board Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corrugated Board Packaging Market Outlook
The premium-customer split in North America corrugated board packaging is restructuring around flute precision and print-grade linerboard versus bulk shipping containers. International Paper Company leverages its integrated pulp-to-box network across the southeastern United States to control linerboard supply. Smurfit Westrock anchors its position through high-volume containerboard mills serving the Midwest automotive parts trade. Packaging Corporation of America differentiates via lightweighting R&D that reduces basis weight without sacrificing box compression strength.
Corrugated board packaging consists of fluted paper medium laminated between flat linerboard sheets, typically manufactured through the corrugator process with flute profiles ranging from A-flute to micro-flute configurations, engineered to absorb impact and distribute load for product protection during distribution. Single wall and double wall configurations dominate volume production for Food & Beverage shipping applications, while die-cut formats command margin pools in Electronics retail packaging where precise fitment reduces dimensional weight charges. Triple wall segments occupy a mature position in industrial machinery crating where alternative materials face substitution pressure.
The EPA enforces recycled fiber content thresholds under Comprehensive Procurement Guidelines, while OSHA regulates dust exposure limits in corrugating facilities, and the FTC's Green Guides constrain unsubstantiated recyclability claims on printed boxes. These frameworks elevate capital requirements for compliance and filter market access toward operators with certified environmental management systems. Stakeholders must weigh recycled fiber cost volatility against virgin pulp price hedging strategies when committing to multi-year supply contracts.
Market Dynamics
The North America corrugated board packaging market is restructuring around the EPA's recycled content mandates under the Resource Conservation and Recovery Act, which are compressing virgin fiber demand while concentrating supply among operators with certified recovery infrastructure.
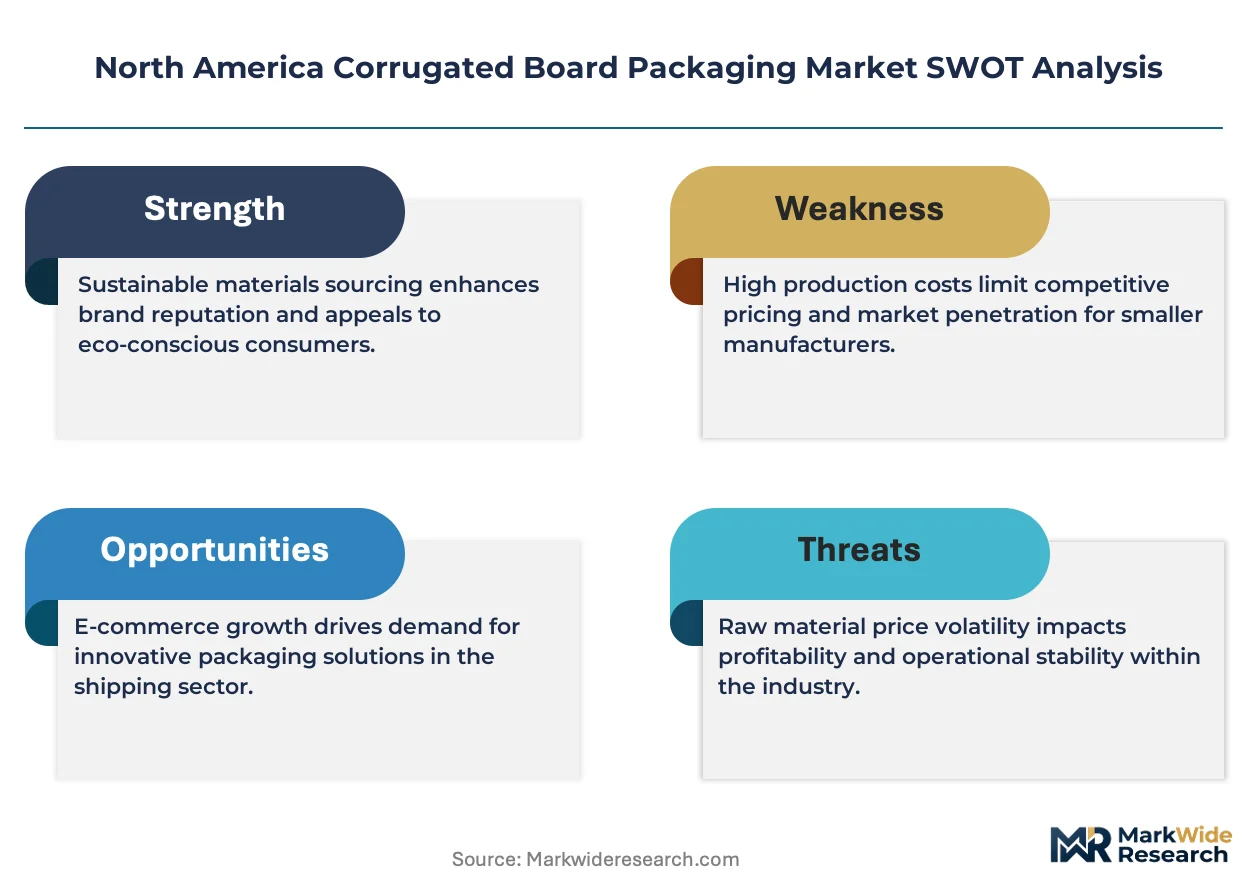
Growth Catalysts
- E-commerce fulfillment specifications:United States retailers are expanding box size matrices for fragile goods, driving demand for precision-engineered flute configurations with enhanced compression strength.
- Resource Conservation and Recovery Act thresholds:EPA mandates for post-consumer recycled content are accelerating investment in recovery and processing infrastructure across the Great Lakes corridor.
- Automotive parts distribution:Just-in-time supply chains serving Michigan, Ohio, and Illinois assembly plants require high-volume containerboard with consistent caliper and print-grade surfaces for bar-code scanning.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container pricing swings create margin compression for mills without captive pulp supply or long-term hedging contracts.
- Great Lakes supply concentration:Production gravity across Michigan, Ohio, and Illinois exposes buyers to regional logistics disruptions and limited alternative sourcing.
- Lightweighting technical ceiling:Basis weight reductions below industry-standard thresholds risk box compression failure under palletized load conditions.
Strategic Opportunities
- Micro-flute electronics packaging:Die-cut formats with F-flute and N-flute profiles are penetrating consumer electronics retail channels where dimensional weight reduction offsets premium substrate costs.
- FTC Green Guides compliance services:Third-party certification of recyclability claims creates margin pools for converters with environmental management systems.
- Triple-wall industrial substitution:Heavy-duty corrugated crating is displacing wooden crates in machinery exports from the southeastern United States to reduce ISPM-15 compliance burden.
Industry Challenges
- Corrugator operator skill gaps:Automated flute-profile changeover systems require technicians with mechatronics training that exceeds traditional paper-machine apprenticeship pipelines.
- Dust exposure compliance timelines:OSHA permissible exposure limit reductions for respirable particulates demand capital-intensive ventilation retrofits with extended facility shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corrugated Board Packaging Market |
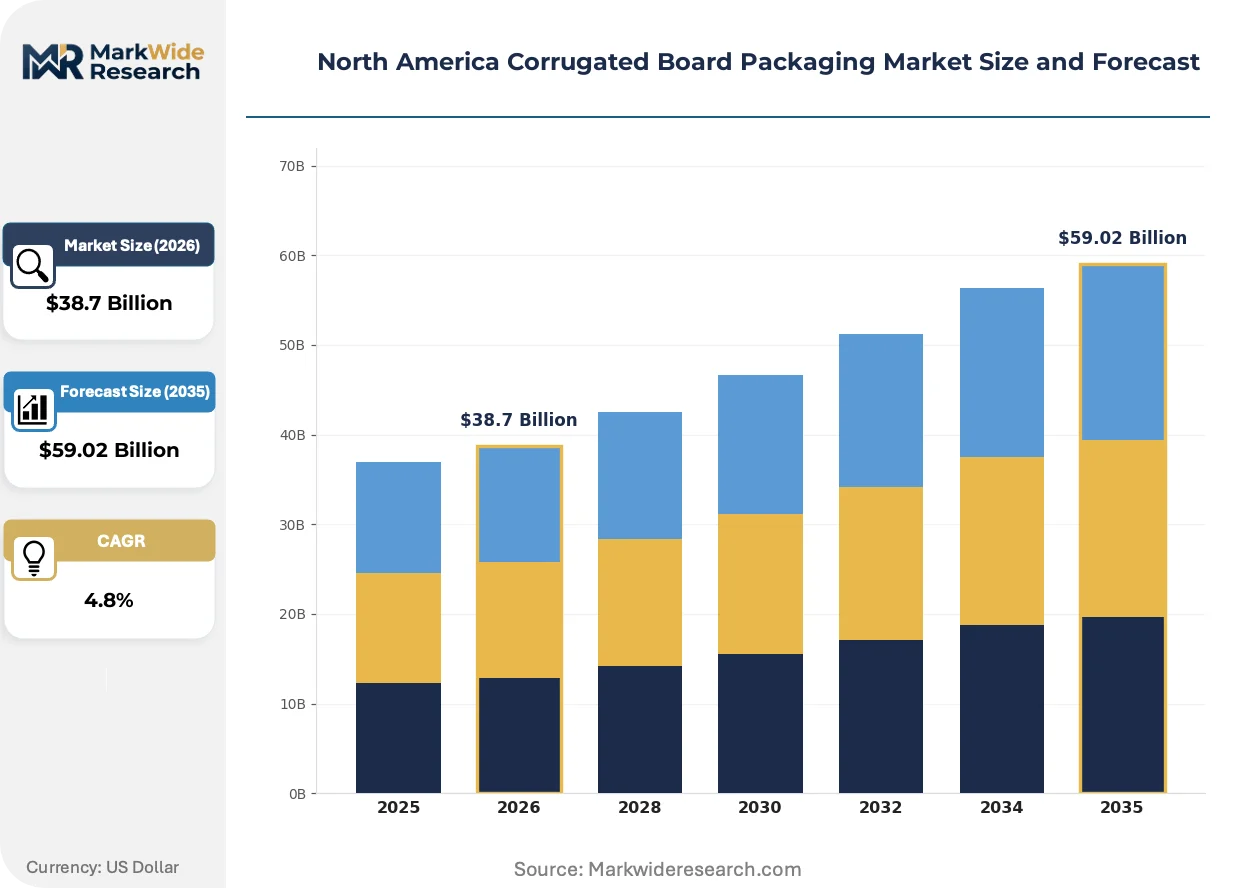
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Die-Cut End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Application: Shipping, Retail Packaging, Storage, Industrial Packaging Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | International Paper Company, Smurfit Westrock, Packaging Corporation of America, Georgia-Pacific LLC, WestRock Company, DS Smith, Smurfit Kappa Group, Cascades Inc., Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corrugated Board Packaging Market Strategic Shifts
Digital printing and automation are converging with substrate science to compress production lead times while expanding customization capabilities for short-run packaging specifications.
Water-based flexographic printing with expanded-gamut ink sets is expanding into food-grade linerboard applications previously reserved for offset lithography. Regional converters serving specialty coffee and craft beverage brands are adopting seven-color process systems to eliminate plate-change downtime. This capability is expanding into micro-batch production runs that previously failed minimum-order thresholds.
OSHA's updated respirable crystalline silica standards are forcing corrugating facilities to accelerate dust collection infrastructure investments. Mills across the United States are retrofitting knife-line exhaust systems and pneumatic conveying enclosures to meet stricter permissible exposure limits. The compliance burden falls heaviest on independent converters without captive engineering resources for ventilation redesign.
Brand owners are consolidating corrugated specifications across regional distribution networks to reduce SKU complexity and improve procurement leverage. National retailers are mandating unified box designs across fulfillment centers in Illinois, Ohio, and Texas, displacing locally optimized formats. This standardization is most visible in consumer packaged goods verticals where marketing consistency overrides regional logistics preferences.
North America Corrugated Board Packaging Market Segmentation
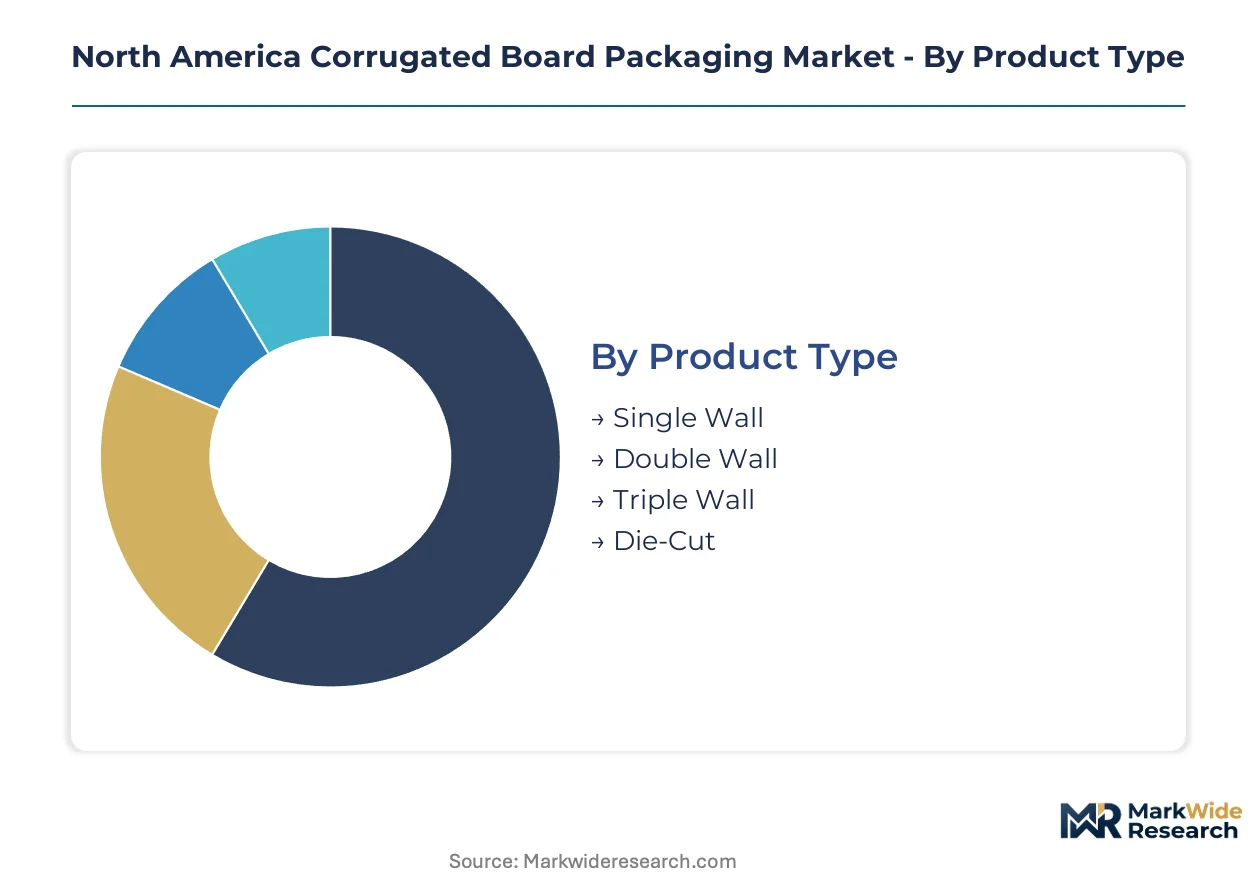
Corrugated board packaging segmentation in North America reflects divergent technical requirements across fulfillment channels. Product wall configurations, end-use durability standards, and distribution velocity demands create distinct procurement tiers with specialized supplier qualifications.
Product Type:
Buyers select wall configurations based on load-bearing requirements and freight optimization targets across their distribution networks.
- Single Wall:One fluted medium between two linerboard sheets provides baseline protection for lightweight consumer goods. Food & Beverage shippers across the Great Lakes corridor specify C-flute profiles for canned goods distribution, balancing compression strength against pallet cube efficiency.
- Double Wall:Two fluted layers separated by three linerboard sheets deliver enhanced stacking performance for heavier payloads. Electronics fulfillment operations in Texas and California mandate BC-flute combinations for fragile device protection during multi-node distribution.
- Triple Wall:Heavy-duty industrial crating for machinery exports from southeastern United States ports.
- Die-Cut:Precision-engineered formats with custom void-fill geometry for retail-ready presentation.
Volume sits with Single Wall; growth tilts toward Die-Cut.
End User:
End-use verticals impose distinct certification and performance specifications that filter supplier eligibility.
- Food & Beverage:FDA-compliant linerboard with grease-resistant coatings for direct food contact applications. Frozen supply chains across the Midwest require moisture-vapor transmission rates below industry thresholds to prevent carton degradation.
- Electronics:Anti-static flute treatments and precise dimensional tolerances for component protection. California and Washington State distribution centers prioritize ESD-safe formats for semiconductor device handling.
- Consumer Goods:Print-grade surfaces for shelf-ready merchandising in big-box retail.
- Pharmaceuticals:Lot-code traceability and temperature-indicator compatibility for cold-chain compliance.
Food & Beverage commands shipment volume; Electronics delivers margin expansion.
Application:
Application context determines flute profile selection and print specification intensity.
- Shipping:Standard RSC boxes with B-flute or C-flute configurations for e-commerce parcel networks. Amazon and Walmart fulfillment centers specify edge crush test ratings above 32 ECT for automated sortation compatibility.
- Retail Packaging:Shelf-ready formats with high-graphic litho-laminated surfaces for point-of-sale presentation.
- Storage:Heavy-duty triple-wall configurations for warehouse racking applications in automotive parts distribution.
- Industrial Packaging:Export-grade crating with ISPM-15 exempt status for machinery shipments.
Shipping dominates unit volume; Retail Packaging captures value-per-ton premiums.
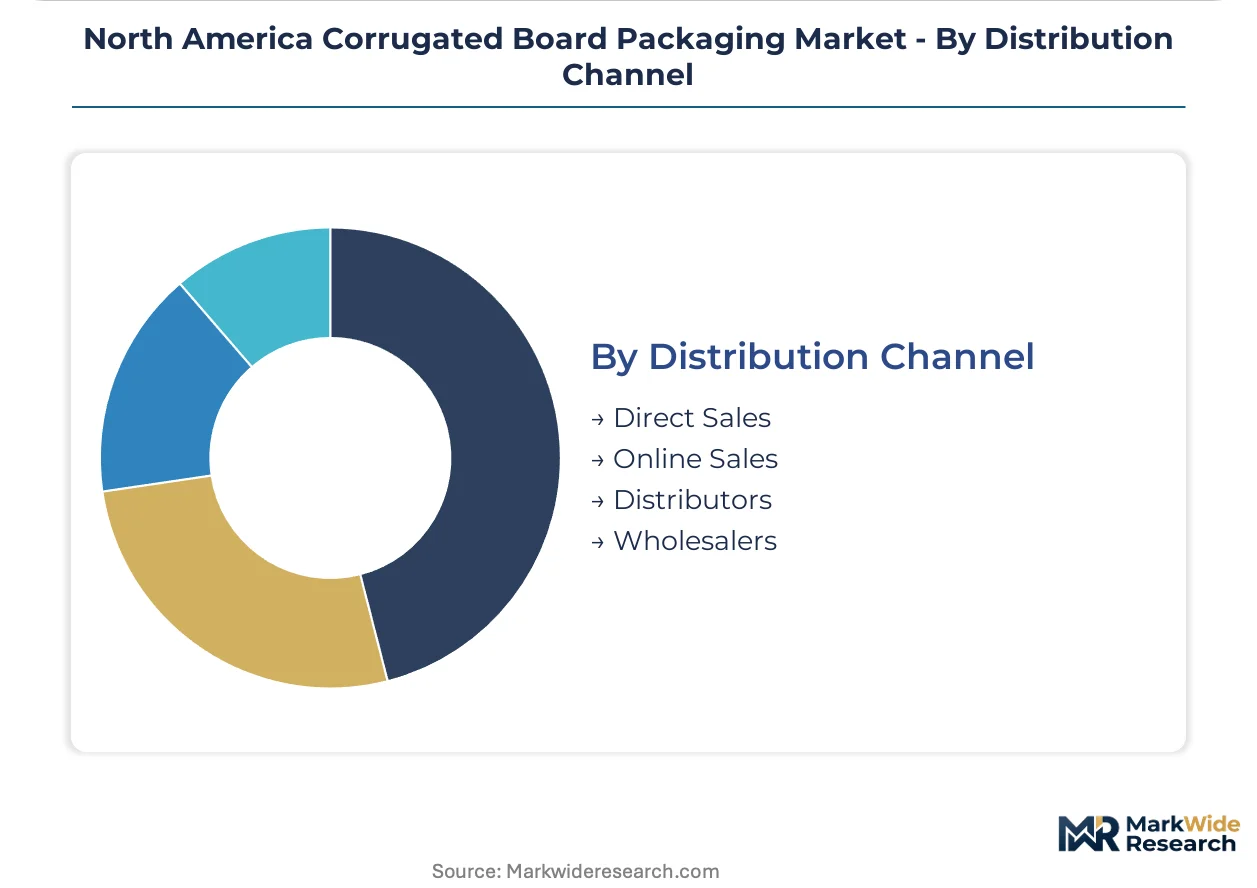
Distribution Channel:
Channel selection reflects order scale, customization requirements, and inventory velocity needs.
- Direct Sales:Mill-direct relationships for high-volume accounts with dedicated corrugator capacity. International Paper and Packaging Corporation of America maintain direct procurement portals for national retailers with annual volume commitments.
- Distributors:Regional inventory buffers for mid-tier converters requiring just-in-time substrate supply.
- Online Sales:Digital specification tools for small-batch custom box orders with short lead times.
- Wholesalers:Consolidated sourcing for independent converters without captive mill relationships.
Direct Sales anchors large-account relationships; Online Sales expands fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois commands the dominant share of North American corrugated board demand, driven by automotive parts distribution and food processing concentration.
United States
E-commerce fulfillment centers in Illinois, Ohio, and Texas are expanding box specification matrices for fragile goods distribution. EPA recycled content mandates under the Resource Conservation and Recovery Act are compressing virgin fiber demand while favoring operators with certified recovery infrastructure. The southeastern United States pulp-to-box network supplies linerboard to national retail accounts with annual volume commitments.
Canada
Ontario and Quebec containerboard mills serve cross-border automotive supply chains with just-in-time delivery requirements. Health Canada and PMRA regulations govern food-contact packaging standards for frozen supply chains exporting into the United States. Cascades Inc. anchors production capacity in Quebec with integrated recycling and manufacturing operations.
Mexico
Nuevo León and the Bajío Region are attracting corrugated packaging investment to serve nearshored manufacturing operations. Mexican environmental regulators are implementing recycled fiber content guidelines aligned with US EPA frameworks. Mexico City Metro distribution centers handle growing e-commerce parcel volumes for cross-border retail fulfillment.
North America Corrugated Board Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across flute precision and print-grade linerboard specialization versus bulk shipping container production. The market structure concentrates supply among integrated pulp-to-box operators with captive fiber supply and regional converters serving mid-tier accounts. Three archetypes dominate: integrated majors with mill networks, regional specialists with automotive sector focus, and lightweighting technology leaders. Capacity consolidation and geographic expansion represent the dominant competitive moves reshaping supply allocation.
Among integrated North American operators, International Paper Company, Smurfit Westrock, and Packaging Corporation of America exemplify the tiered competitive structure. International Paper represents the integrated pulp-to-box archetype with southeastern United States network control. Smurfit Westrock occupies a position serving high-volume Midwest industrial accounts. Packaging Corporation of America sits within the lightweighting R&D tier, reducing basis weight without sacrificing compression performance. These three anchors demonstrate how fiber integration, regional density, and technical differentiation stratify competitive positioning across the North American market.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Westrock |
| Packaging Corporation of America |
| Georgia-Pacific LLC |
| WestRock Company |
| DS Smith |
| Smurfit Kappa Group |
| Cascades Inc. |
| Mondi |
| Others |
Value Chain & Pricing Dynamics
National retailers with annual volume commitments anchor pricing power in the North America corrugated board packaging market, locking in contract-based long-term offtake structures that compress spot-market premiums for independent converters. The EPA's recycled content mandates under the Resource Conservation and Recovery Act are tightening substrate requirements, forcing mills to absorb cost volatility or pass through fiber price swings to tiered account structures.
Pricing Analysis
Edge crush test ratings above 32 ECT for automated sortation compatibility anchor value-based pricing premiums for e-commerce fulfillment specifications. Three-tier pricing structure across premium, standard, and economy levels separates die-cut micro-flute electronics formats from bulk shipping containers and commodity RSC boxes. Cost compression in standard-grade linerboard is intensifying because old corrugated container pricing swings create margin pressure for mills without captive pulp supply. Mid-tier automotive parts distributors exhibit highest price sensitivity due to just-in-time inventory requirements, while semiconductor device handlers in California and Washington State accept premium substrate costs for ESD-safe formats.
Supply Chain Analysis
FDA-compliant linerboard certification for direct food contact applications gates supplier eligibility in frozen supply chains across the Midwest. Production gravity centers on the United States, Canada, and Mexico, with the Great Lakes corridor commanding dominant share for automotive parts distribution. The supply chain draws from virgin pulp, post-consumer recovered fiber, and starch-based adhesives as core inputs. Single-source vulnerability concentrates in the southeastern United States pulp-to-box network, where integrated majors control linerboard supply. Distribution runs through mill-direct procurement portals for high-volume accounts, with regional distributors buffering mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified recovery infrastructure scarcity props pricing power for operators with EPA-compliant post-consumer fiber processing, constraining capacity expansion timelines for uncertified entrants.
For Market Incumbents: Deepen backward integration into captive pulp supply to hedge against old corrugated container price volatility threatening margin stability. Expand certified environmental management systems to capture FTC Green Guides compliance service premiums. Prioritize lightweighting R&D investments that reduce basis weight without sacrificing box compression strength, defending position against substrate substitution in industrial crating applications. For New Entrants and Emerging Players: Specialty coffee and craft beverage brands represent an underserved buyer archetype seeking seven-color process flexographic capabilities for micro-batch production runs. Penetrate the micro-flute electronics packaging segment in Texas and California distribution centers where dimensional weight reduction offsets premium substrate costs. Pursue digital specification tools for small-batch custom box orders with short lead times as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional converters with automotive sector focus in Michigan, Ohio, and Illinois, where just-in-time supply chain requirements create sticky customer relationships. Long-term viability over a multi-year horizon rests on fiber integration depth and EPA compliance certification status. Monitor OSHA permissible exposure limit enforcement timelines as the inflection indicator for capital-intensive ventilation retrofit burdens falling heaviest on independent operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Processing | EPA recycled content mandates favor operators with certified recovery infrastructure in the Great Lakes corridor. |
| Lightweighting R&D Investment | Basis weight reduction without compression strength loss captures premium positioning in e-commerce fulfillment specifications. |
| Micro-Flute Die-Cut Capacity Expansion | F-flute and N-flute profiles penetrate consumer electronics retail channels demanding dimensional weight optimization. |
| FTC Green Guides Certification Services | Third-party recyclability claim verification creates margin pools for converters with environmental management systems. |
| Automotive Sector Geographic Density Buildout | Just-in-time supply chains serving Michigan, Ohio, and Illinois assembly plants require consistent caliper and print-grade surfaces. |
Study Parameters
Independent corroboration across corrugator plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors underwrites the qualitative findings in this study. Primary interviews with industry stakeholders combined with secondary validation from EPA enforcement records, SEC 10-K filings, customs/trade data, and TAPPI technical standards establish demand-side and supply-side triangulation. Bottom-up volume estimates from individual facility capacity and top-down macroeconomic drivers converge in the analytical framework.
Rate-of-change decomposition across the analysis window segments expansion by wall configuration, end-use vertical, flute profile specification, and regional production hub. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology substitution curves. Modeled inputs include e-commerce fulfillment center expansion pipelines, automotive production schedules in the Great Lakes corridor, and EPA recycled content threshold compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to old corrugated container price volatility, OSHA dust exposure compliance timelines, and lightweighting technical ceiling breakthroughs. Forecasts reflect assumptions documented in the segmentation and regional outlook sections without explicit probability weighting. A model refresh is warranted upon material change in EPA enforcement intensity or breakthrough basis weight reduction technologies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Wax Paper Medicine Pots Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Liquid Packaging Board Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market