
 LAMEA Printing Machinery Market | 2026-2036
LAMEA Printing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Printing Machinery Market Insights
High-speed, precision-grade digital press specifications are reorganizing competitive dynamics across LAMEA. HP, Inc. leverages its thermal inkjet architecture to dominate variable-data packaging contracts for Latin American consumer goods brands. Canon, Inc. sustains its position through integrated toner-based systems that anchor commercial print shops in Mexico City and São Paulo. Seiko Epson Corporation specializes in dye-sublimation engines that control textile printing workflows for Turkish and Egyptian apparel exporters.
LAMEA printing machinery encompasses industrial equipment designed to transfer ink onto substrates through mechanical or digital processes, with operating speeds typically ranging from 3,000 to 15,000 impressions per hour and registration tolerances below 0.1 mm for precision applications. These systems serve commercial reproduction, product decoration, and functional coating needs across packaging, publishing, and industrial manufacturing. Digital technology leads value generation as inkjet platforms displace analog workflows in short-run label and packaging segments across the region. Flexographic equipment retains scale dominance in Brazilian corrugated board production, where volume throughput and lower per-unit ink costs preserve margin pools for established converters.
Brazil's national standards body enforces machinery safety protocols aligned with ISO 12643 series requirements, while South Africa's occupational regulator mandates CE-equivalent conformity for imported printing equipment, shaping procurement specifications and supplier qualification processes. Egypt's industrial quality authority applies GB-influenced electromagnetic compatibility testing for digital press imports, creating additional compliance layers for Asian equipment vendors. Stakeholders must monitor how evolving energy-efficiency thresholds and substrate recycling mandates across LAMEA jurisdictions reshape total cost-of-ownership calculations and equipment replacement timelines.
Market Dynamics
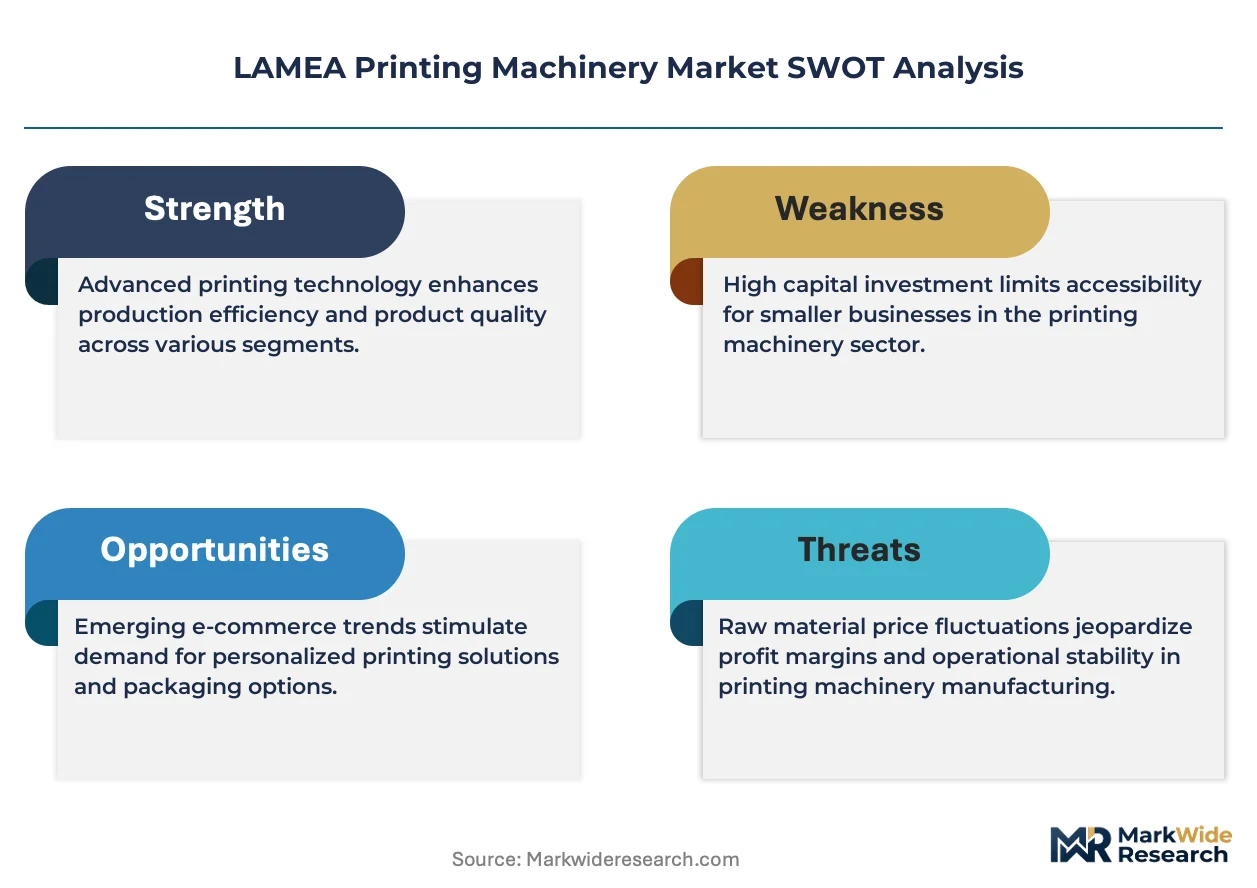
Digital inkjet architectures are compressing replacement cycles across LAMEA packaging converters, forcing analog gravure and flexographic asset owners to accelerate fleet modernization or cede short-run contracts to digitally equipped competitors.
Growth Catalysts
- Short-run flexible packaging demand:Brazilian and Mexican food exporters require variable-data labels for SKU proliferation, pulling digital press installations into São Paulo and Mexico City industrial corridors.
- ISO 12643-aligned safety mandates:Brazil's national standards body enforces updated machinery safety protocols, triggering equipment replacement among legacy gravure operators.
- Electromagnetic compatibility testing:Egypt's industrial quality authority applies GB-influenced standards for digital press imports, filtering supplier pools toward certified Asian and European vendors.
Market Restraints
- Specialized consumables cost volatility:UV-curable and water-based ink formulations for high-speed inkjet systems expose converters to petrochemical input price swings.
- Asian equipment vendor concentration:Digital press supply chains cluster among thermal inkjet and piezoelectric printhead manufacturers in East Asia, creating single-source vulnerability for LAMEA importers.
- Substrate compatibility limitations:Uncoated corrugated and recycled fiber boards resist aqueous ink adhesion, preserving flexographic dominance in Brazilian volume packaging.
Strategic Opportunities
- Textile dye-sublimation expansion:Turkish and Egyptian apparel exporters seek digital textile printing workflows for fast-fashion sampling and micro-batch production.
- South African equipment replacement wave:Occupational safety regulators mandate CE-equivalent conformity, opening procurement windows for certified European and Asian machinery suppliers.
- Energy-efficiency incentive alignment:Emerging substrate recycling mandates and power consumption thresholds across LAMEA jurisdictions favor next-generation digital presses with regenerative drying systems.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven registration systems and closed-loop color management require skilled maintenance labor that São Paulo and Mexico City training pipelines undersupply.
- Legacy analog integration complexity:Hybrid workflows combining existing gravure units with digital front-ends demand custom middleware development that stretches converter IT capabilities.
- Multi-jurisdiction certification timelines:Equipment vendors face sequential ISO 12643, CE-equivalent, and GB-influenced EMC approvals that delay revenue recognition across Brazil, South Africa, and Egypt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Printing Machinery Market |
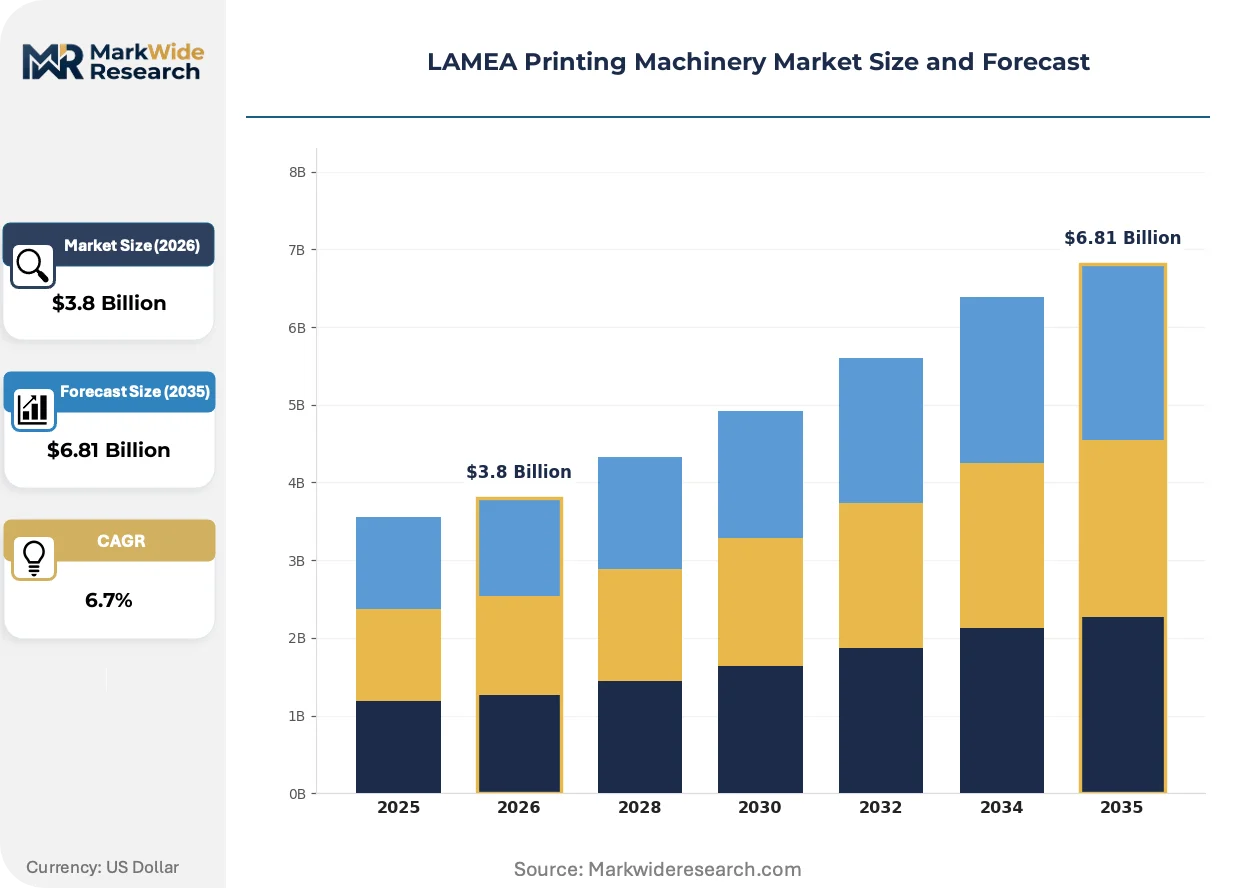
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Offset, Flexographic, Digital, Gravure Application: Packaging, Commercial Printing, Label Printing, Textile Printing Technology: Inkjet, Laser, Thermography, Screen Printing End User: Publishing, Advertising, Textile, Automotive |
| Companies Covered | HP, Inc., Canon, Inc., Seiko Epson Corporation, Xerox Corporation, Ricoh Company, Ltd., Konica Minolta, Inc., Mimaki Engineering Co., Ltd., Agfa-Gevaert Group, Brother Industries, Ltd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Printing Machinery Market Trends and Innovations
Precision-grade inkjet architectures and converging regulatory frameworks are redrawing competitive boundaries across Latin American, Middle Eastern, and African print markets. Three forces now dominate strategic planning.
Single-pass inkjet arrays with fixed printbar configurations are miniaturizing footprint requirements for high-volume packaging production. Brazilian corrugated converters in the São Paulo industrial corridor are piloting these systems for medium-run beverage carton work. The technology is miniaturizing the economic threshold for digital adoption, compressing the run-length crossover point where inkjet matches flexographic unit economics.
South Africa's occupational regulator now mandates CE-equivalent conformity assessment for all imported printing equipment, extending European machinery safety norms to LAMEA procurement specifications. Industrial buyers must document third-party certification before customs release, lengthening supplier qualification timelines. Egyptian packaging converters face the steepest compliance burden as they simultaneously navigate GB-influenced electromagnetic compatibility testing for Asian-sourced digital presses.
Service unbunding now separates hardware acquisition from consumables supply and technical support across major Latin American markets. Mexican commercial print shops in Mexico City increasingly lease digital toner systems while purchasing ink and maintenance contracts from competing vendors. This fragmentation concentrates negotiating leverage with buyers who can arbitrage supply contracts, pressuring OEM margin pools across the region's largest metropolitan print markets.
LAMEA Printing Machinery Market Segmentation
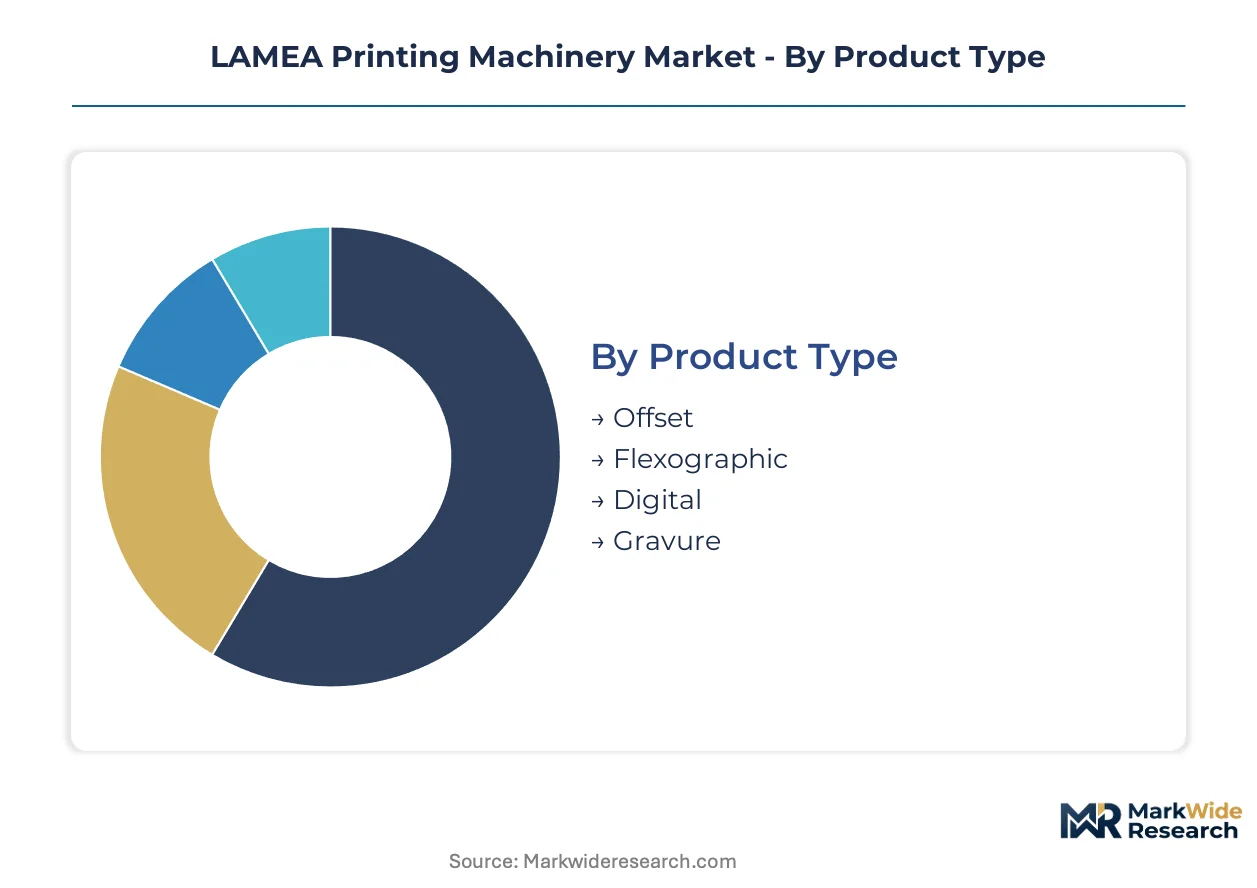
Segmentation in the LAMEA printing machinery market reveals how regulatory frameworks, substrate requirements, and end-use specifications reshape equipment procurement patterns across Brazil, South Africa, and Egypt. Understanding these divisions exposes where compliance costs concentrate and where technology substitution accelerates.
Product Type:
ISO 12643-aligned safety mandates in Brazil and CE-equivalent conformity requirements in South Africa create divergent compliance burdens across analog and digital equipment categories, filtering supplier pools and reshaping replacement timelines.
- Digital:Inkjet and toner-based systems with variable-data capabilities dominate short-run packaging contracts in São Paulo and Mexico City. Brazilian food exporters deploy these presses for SKU-proliferated label production where run lengths fall below flexographic economic thresholds.
- Flexographic:Rotary relief printing with photopolymer plates sustains volume dominance in Brazilian corrugated board production, where uncoated recycled fiber substrates and per-unit ink economics preserve margin pools for established converters serving beverage export supply chains.
- Offset:Lithographic systems with blanket-cylinder transfer mechanisms retain commercial print shop installations in Mexico City for long-run publication work.
- Gravure:Intaglio engraving presses with chrome-plated cylinders serve high-volume flexible packaging in São Paulo's industrial corridor, though replacement cycles accelerate under updated machinery safety enforcement.
Established volume favors Flexographic; emerging adoption favors Digital.
Application:
Cost tier differentiation separates high-compliance packaging investments from lower-threshold commercial and textile segments, with Egyptian electromagnetic compatibility testing adding premium layers to digital press imports for flexible packaging.
- Packaging:Flexible carton, corrugated, and label production systems face the steepest regulatory stacking—Brazil's ISO 12643 safety protocols, South Africa's CE-equivalent mandates, and Egypt's GB-influenced EMC testing converge on this application, extending supplier qualification timelines and concentrating procurement among certified Asian and European vendors.
- Textile Printing:Dye-sublimation and direct-to-fabric inkjet systems serve Turkish and Egyptian apparel exporters for fast-fashion sampling and micro-batch production, where shorter run lengths and rapid design turnover compress equipment payback periods.
- Label Printing:Narrow-web flexographic and digital hybrid systems address variable-data pharmaceutical and food labeling requirements across São Paulo and Mexico City.
- Commercial Printing:Toner-based and offset systems anchor Mexico City print shops for long-run marketing collateral and publication reproduction.
Margin concentration sits with Packaging; steepest expansion trajectory belongs to Textile Printing.
Technology:
Customer type segmentation—packaging converters versus commercial print shops versus textile manufacturers—determines which printhead architectures, drying systems, and color management protocols dominate procurement specifications.
- Inkjet:Piezoelectric and thermal drop-on-demand systems with single-pass printbar configurations are miniaturizing footprint requirements for medium-run beverage carton work in São Paulo, compressing the run-length crossover point where digital matches flexographic unit economics.
- Laser:Electrophotographic imaging with organic photoconductor drums sustains high-volume commercial print operations in Mexico City where toner adhesion and substrate flexibility requirements favor dry-toner workflows.
- Screen Printing:Stencil-based ink transfer with mesh tensioning systems serves automotive and industrial decorative applications across South Africa's manufacturing belt.
- Thermography:Heat-activated powder adhesion systems retain niche presence for raised-print stationery and security document applications.
Technology maturity favors Laser; capability expansion concentrates in Inkjet.
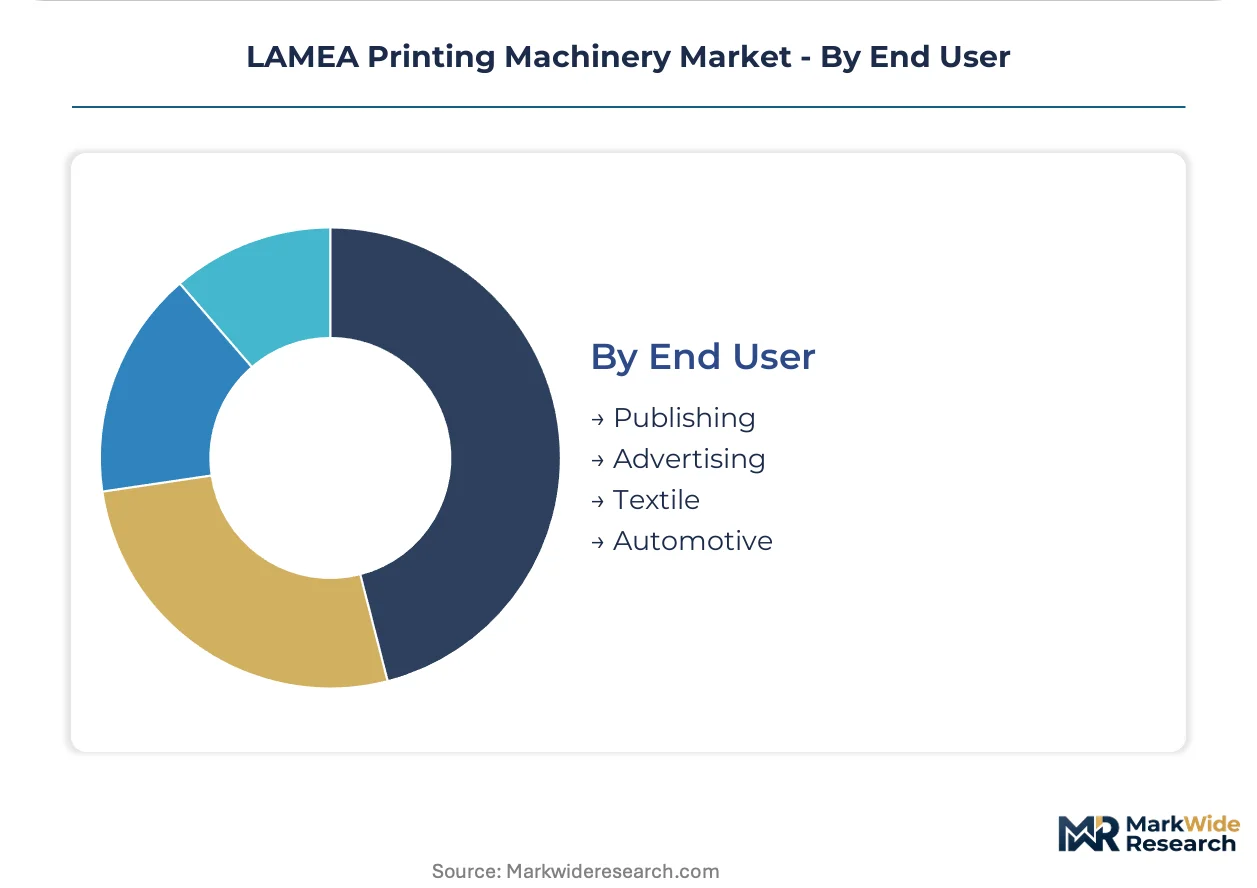
End User:
Geographic clustering within LAMEA jurisdictions—São Paulo's industrial corridor, Mexico City's commercial print district, Cairo's textile zone, Johannesburg's automotive belt—shapes which machinery specifications dominate regional demand.
- Textile:Apparel manufacturers in Egypt and Turkey deploy dye-sublimation and direct-to-garment systems for fast-fashion sampling, where micro-batch production requirements and rapid design turnover pull digital textile printing into Cairo and Istanbul production zones.
- Advertising:Commercial print shops and wide-format display producers in Mexico City and São Paulo combine toner-based systems with UV-curable inkjet for point-of-sale and outdoor advertising substrates.
- Publishing:Newspaper and book production facilities in São Paulo retain offset and gravure capacity for long-run educational and periodical work, though digital front-ends increasingly penetrate short-run academic and specialty title production.
- Automotive:Interior trim and component decorators in South Africa's manufacturing corridor apply screen printing and pad printing systems for dashboard graphics and control panel markings.
Volume stability anchors Publishing; share gains concentrate in Textile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment supply chains concentrate among thermal inkjet and piezoelectric printhead manufacturers in East Asia, creating distribution bottlenecks that LAMEA importers navigate through certified vendor relationships. Brazil, Mexico, South Africa, Turkey, and Egypt constitute the primary demand nodes, each shaped by distinct regulatory frameworks and industrial clustering patterns.
Brazil
Food and beverage exporters in São Paulo's industrial corridor drive gravure and flexographic press installations for high-volume flexible packaging. ANVISA, the national health regulator, enforces strict labeling requirements that pull digital inkjet systems into short-run SKU proliferation workflows. The São Paulo state industrial belt hosts the densest concentration of corrugated board converters serving Mercosur export supply chains.
Mexico
Commercial print shops in Mexico City anchor toner-based and offset capacity for long-run publication and marketing collateral production. The national standards body applies machinery safety protocols aligned with ISO 12643 series requirements, extending equipment replacement timelines for legacy installations. Nuevo León's manufacturing corridor is emerging as a secondary node for automotive component decorators utilizing pad printing systems.
South Africa
The occupational safety regulator mandates CE-equivalent conformity assessment for all imported printing equipment, filtering procurement toward certified European and Asian vendors. Johannesburg's automotive manufacturing belt sustains demand for screen printing and industrial decorative applications. The Western Cape packaging cluster is piloting single-pass inkjet arrays for medium-run beverage carton production.
Turkey
Apparel exporters in Istanbul and Bursa deploy dye-sublimation and direct-to-fabric inkjet systems for fast-fashion sampling and micro-batch production. The national quality infrastructure applies electromagnetic compatibility testing protocols that extend supplier qualification timelines for Asian-sourced digital presses. The Istanbul textile zone concentrates the region's highest density of digital textile printing workflows.
Egypt
Cairo's textile manufacturing district is absorbing direct-to-garment systems as apparel producers pivot toward rapid design turnover and reduced minimum order quantities. The industrial quality authority applies GB-influenced electromagnetic compatibility standards for digital press imports, creating additional compliance layers for equipment vendors. The Suez Canal Economic Zone is attracting packaging converters seeking duty-advantaged access to African and Middle Eastern markets.
LAMEA Printing Machinery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LAMEA printing machinery market. Japanese and American vendors anchor the premium tier through proprietary printhead architectures and integrated color management systems, while Chinese and Korean fabricators compete on equipment acquisition cost and regional service density. Three archetypes dominate: full-stack OEMs controlling hardware-consumables-service bundles; specialized subsystem suppliers licensing printhead technology to regional integrators; and aftermarket service providers unbundling maintenance from original equipment contracts. Competitive moves concentrate on geographic expansion through certified distributor networks and portfolio diversification into textile and packaging-specific configurations.
Within the full-stack OEM tier, HP, Inc. and Canon, Inc. occupy positions that exemplify divergent technology bets—thermal inkjet versus electrophotographic architectures—while Seiko Epson Corporation represents the specialized subsystem path through piezoelectric printhead dominance. These three Japanese and American anchors illustrate how vendor origin shapes regulatory compliance capabilities across Brazil's ISO 12643 enforcement, South Africa's CE-equivalent mandates, and Egypt's GB-influenced testing regimes.
| Leading Market Players |
|---|
| HP, Inc. |
| Canon, Inc. |
| Seiko Epson Corporation |
| Xerox Corporation |
| Ricoh Company, Ltd. |
| Konica Minolta, Inc. |
| Mimaki Engineering Co., Ltd. |
| Agfa-Gevaert Group |
| Brother Industries, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term consumables bundling contracts lock in supply access and price visibility for LAMEA packaging converters negotiating digital press acquisitions. Brazilian gravure operators facing ISO 12643 replacement mandates secure ink and service commitments alongside hardware procurement to stabilize total cost-of-ownership calculations across extended depreciation cycles.
Pricing Analysis
ISO 12643-aligned safety mandates dictate the pricing tier structure across Brazil and South Africa, separating certified premium equipment from uncertified economy imports. Three-tier pricing stratifies across CE-equivalent certified, ISO-aligned, and non-compliant machinery levels, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the economy tier intensifies because Asian vendors compete on acquisition price alone. Commercial print shops in Mexico City exhibit highest price sensitivity, while ANVISA-regulated food exporters accept premium positioning for compliance assurance.
Supply Chain Analysis
Japan and South Korea anchor piezoelectric and thermal printhead fabrication for LAMEA digital press imports. Taiwan and China feed precision mechatronics components and control systems. Supply chains draw from petrochemical-derived UV-curable ink formulations and specialty substrate coatings. Single-source vulnerability concentrates in East Asian printhead architecture licensing. Distribution runs through certified dealer networks with mandatory technical certification for pre-installation validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inkjet substitution threatens analog gravure and flexographic incumbents across short-run packaging segments, forcing defensive repositioning or fleet modernization commitments.
For Market Incumbents: Compound service revenue streams through unbundled maintenance contracts and consumables arbitrage to offset hardware margin erosion. Deepen backward integration into ink formulation captive supply to reduce petrochemical input exposure. Prioritize CE-equivalent certification investment for South African and Egyptian procurement qualification. For New Entrants and Emerging Players: Anchor in Turkish and Egyptian textile dye-sublimation workflows where fast-fashion sampling demand outpaces established vendor service density. Target Cairo's direct-to-garment micro-batch producers with lease-based equipment models and rapid technician deployment. Lead with design-to-delivery speed guarantees rather than unit cost positioning. For Investors and Strategic Acquirers: The market sits at a substitution acceleration phase that favors subsystem specialists with printhead licensing leverage over full-stack OEMs facing margin compression. Long-term viability hinges on regulatory compliance capabilities across multiple LAMEA jurisdictions rather than single-country dominance. Monitor Egyptian GB-influenced EMC testing enforcement as signal for Asian vendor filtering intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | CE-equivalent and ISO 12643 alignment opens procurement windows in South Africa and Brazil. |
| Consumables Supply Agreement | Long-term ink and service contracts stabilize revenue streams amid hardware price erosion. |
| Textile Configuration Development | Dye-sublimation and direct-to-fabric variants capture Turkish and Egyptian apparel exporter demand. |
| Regional Service Center Buildout | Certified technician presence in São Paulo and Cairo reduces buyer qualification timelines. |
| Regulatory Compliance Partnership | Third-party certification pre-negotiation accelerates customs release across Egypt's EMC testing regime. |
Research Methodology
Operator-level perspectives from packaging converter plant managers, commercial print shop owners, textile production directors, and aftermarket service technicians anchored the qualitative base. Primary interviews combined with secondary validation from customs import records, ANVISA regulatory filings, and ISO certification databases. Bottom-up equipment installation tracking and top-down trade flow analysis provided triangulation across market sizing dimensions.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity and petrochemical input cost scenarios. Segmentation modeling spanned product type, application, technology, and end-user dimensions alongside jurisdiction-specific compliance tier. CAGRs derived from equipment replacement cycle analysis and digital adoption curve penetration rates. Inkjet printhead shipment data and flexographic press order backlogs informed volume projections across the analysis window.
Material uncertainties — regulatory timeline delays, currency volatility affecting import costs, and substrate compatibility breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement consistency and technology substitution elasticity. Recalibration cycles align with material shifts in ANVISA labeling mandates and South African occupational safety regulator pronouncements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Automatic Banding Machine Market