
 Shrink Label Machine Market | 2026-2036
Shrink Label Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shrink Label Machine Market Analytics
Polyethylene terephthalate glycol (PET-G) shrink films are displacing traditional PVC substrates and is realigning material economics across the value chain. Krones AG leverages its integrated bottling-line architecture to anchor premium positioning in European beverage installations. Fuji Seal International sustains geographic dominance across Asia-Pacific through specialized film-to-machine bundling contracts. PDC International competes on thermal-tunnel precision, differentiating its systems for high-speed pharmaceutical lines.
A shrink label machine applies heat-activated sleeve labels to containers using thermal, steam, or infrared energy, typically operating at speeds from 100 to 800 containers per minute with shrink-tunnel temperatures between 150°C and 300°C depending on substrate gauge. The equipment serves primary industrial functions in bottling, capping, and final packaging stages where 360-degree decorative or tamper-evident coverage is required. Automatic systems command the largest installed base due to throughput requirements in Food & Beverage end-use, though semi-automatic units are gaining traction among craft distillers and regional dairy processors seeking flexible batch sizes. Thermal technology leads technology segmentation for energy efficiency, while steam-based systems retain preference in personal care applications where surface finish quality dictates brand shelf impact.
The U.S. Food and Drug Administration regulates direct-contact sleeve materials under food additive provisions, while the EPA governs volatile organic compound emissions from solvent-based adhesives in label printing. The EU REACH framework restricts phthalate plasticizers in PVC films, redirecting procurement toward compliant PET-G and oriented polystyrene alternatives. Stakeholders must monitor evolving extended producer responsibility schemes and substrate recyclability certifications, as these criteria will determine machine specification requirements and retrofit demand.
Market Dynamics
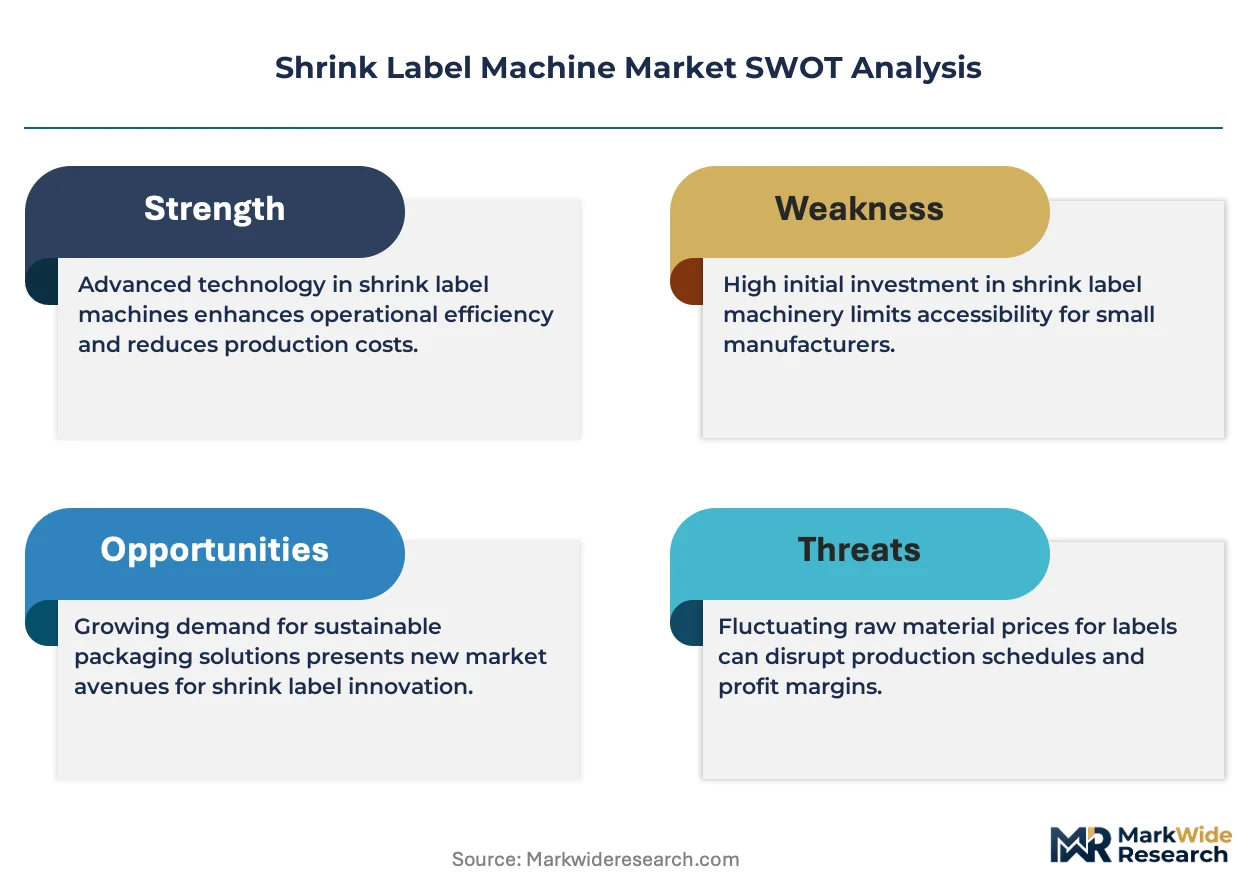
EU REACH restrictions on phthalate plasticizers are redirecting film procurement toward compliant substrates, forcing machine OEMs to retool thermal-tunnel specifications and validate new shrink-curve parameters for PET-G and oriented polystyrene alternatives.
Growth Catalysts
- EU Green Deal packaging directives:Mandatory recyclability targets are accelerating substrate transitions to PET-G and PLA films, requiring compatible machine retrofits across European bottling lines.
- Beverage premiumization in North America:Bottlers are adopting 360-degree shrink-sleeve decoration for craft spirits and functional drinks, expanding installed base requirements for high-speed applicator systems.
- Steam-based surface finishing:Personal care brands in Japan and South Korea specify steam-tunnel systems for gloss-critical cosmetics packaging, sustaining technology diversification despite thermal efficiency advantages elsewhere.
Market Restraints
- Resin supply concentration:PET-G film substrate production clusters in Germany and South Korea, exposing converters to freight-cost volatility and currency-hedging complexity.
- Legacy PVC replacement capex:Converters must replace or rebuild thermal tunnels calibrated for PVC shrink curves, compressing margins during the transition window.
- Pharmaceutical validation timelines:FDA 21 CFR Part 11 compliance for tamper-evident sleeve applications extends qualification periods by 12-18 months versus food-grade deployments.
Strategic Opportunities
- Extended producer responsibility schemes:France and Italy are implementing advanced recycling fee structures that reward mono-material sleeve compatibility, creating specification advantages for machine lines handling PET-G exclusively.
- Pharmaceutical serialization convergence:Integration of shrink-sleeve application with track-and-trace aggregation stations opens dual-function system sales to vaccine and biologics packagers.
- Craft distillery semi-automatic demand:Batch-flexible units below 200 containers per minute address underpenetrated regional spirits producers in Scotland, Kentucky, and Tasmania.
Industry Challenges
- Shrink-curve calibration expertise:Technicians trained on PVC thermal profiles require re-certification for PET-G and PLA substrate behavior, constraining field-service capacity during substrate transitions.
- Legacy line integration complexity:Retrofitting inspection systems from Cognex or Keyence into existing Krones or Sidel architectures demands custom mechanical interfaces and extended commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shrink Label Machine Market |
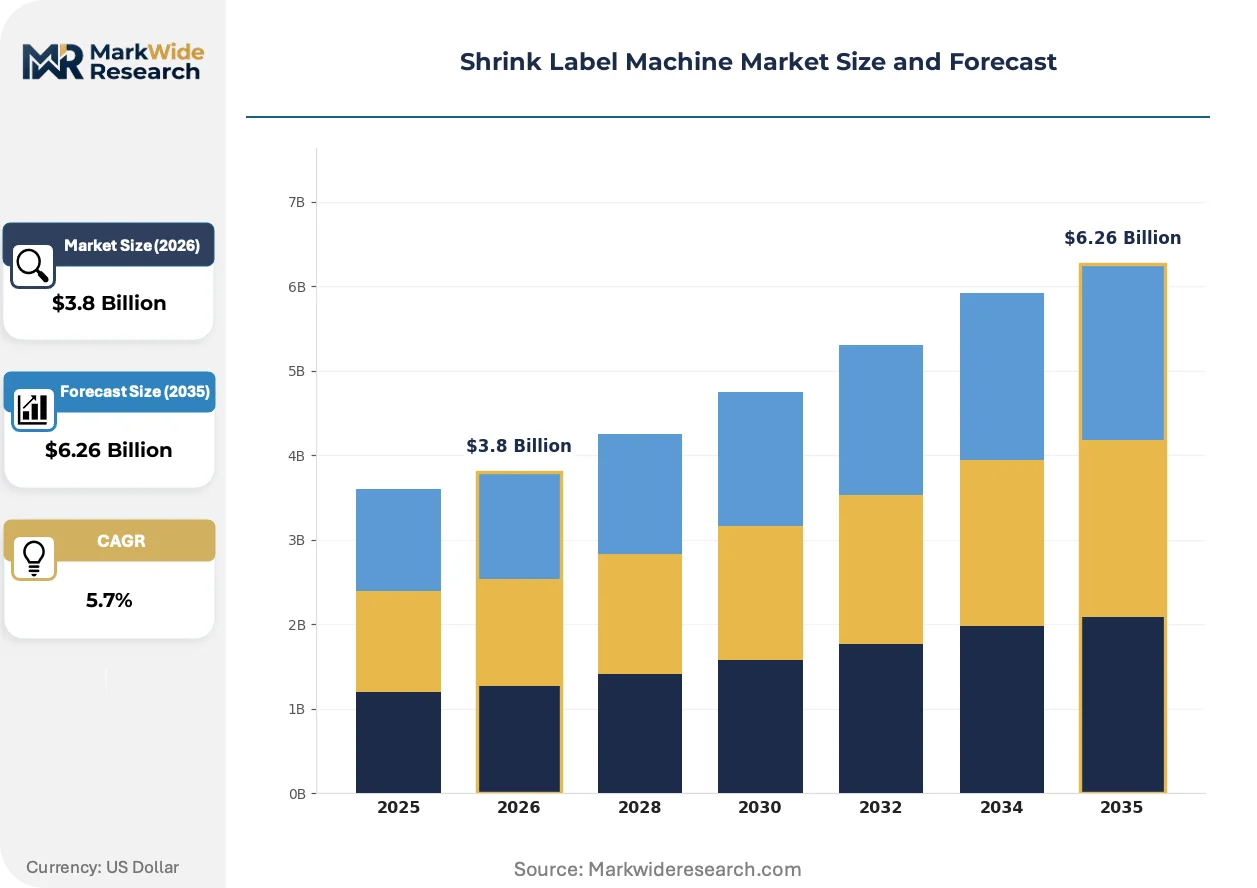
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Electric End User: Food & Beverage, Pharmaceuticals, Personal Care, Consumer Goods Technology: Thermal, Steam, Infrared, Electronic Application: Bottling, Capping, Packaging, Labeling |
| Companies Covered | Krones AG, Fuji Seal International, Accraply, PDC International, Pack Leader Machinery, Axon, BW Integrated Systems, Accutek Packaging Equipment, Karlville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shrink Label Machine Market Evolving Landscape
Digital shrink-sleeve printing and substrate material science are compressing design-to-production cycles while thermal-tunnel engineering advances reduce energy intensity per container.
Infrared pre-heating modules with zone-specific temperature profiling are overtaking conventional single-zone thermal tunnels in high-speed beverage installations. European bottlers operating above 600 containers per minute specify these systems to reduce film-wrinkle rejection rates. The technology is overtaking standard convection designs by enabling real-time curve adjustment without mechanical tunnel reconfiguration.
EU REACH Annex XVII restrictions on phthalate plasticizers in PVC films are compelling substrate conversions across German and Italian packaging converters. The regulation forces thermal-tunnel OEMs to validate new shrink-curve parameters for PET-G alternatives and publish revised energy-consumption specifications. Pharmaceutical and personal care segments in Switzerland and Austria are responding fastest due to existing sustainability procurement mandates.
Service-unbundling from capital-equipment contracts is fragmenting vendor-customer relationships in the North American installed base. Regional dairy processors and craft distillers now procure shrink-label applicators through independent distributors while sourcing maintenance separately from third-party field-service networks. This pattern is most visible in Wisconsin and Vermont dairy cooperatives and Kentucky bourbon distilleries seeking operational flexibility over single-source accountability.
Shrink Label Machine Market Segmentation
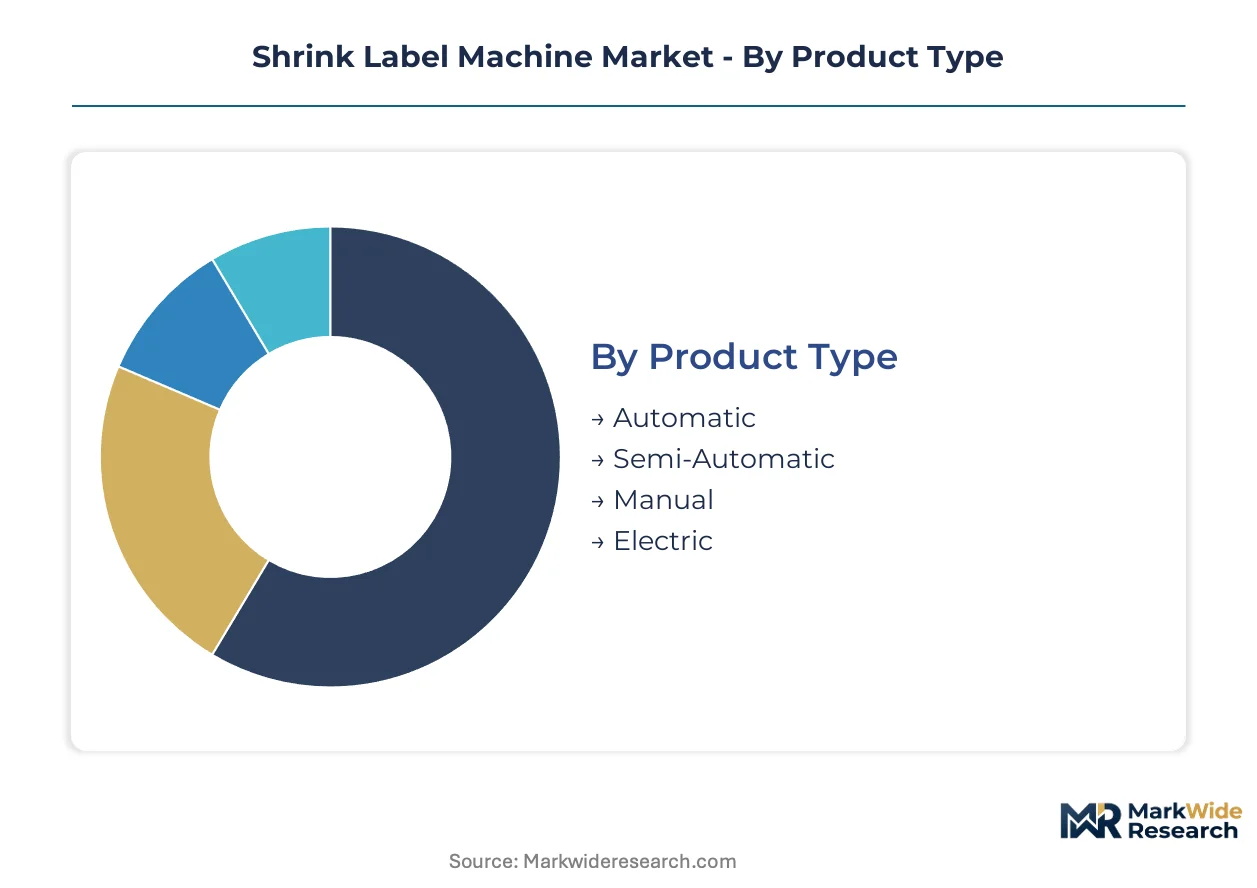
Shrink label machine procurement decisions hinge on throughput requirements, substrate compatibility, and downstream integration complexity. Segment-specific certification burdens—FDA validation for pharmaceutical lines, EU food-contact compliance for beverage installations—directly shape specification requirements and vendor selection criteria.
Product Type:
FDA 21 CFR Part 11 compliance timelines stretch longest for fully automatic systems, while semi-automatic units face abbreviated validation cycles. Electric configurations trigger additional electrical safety certifications under IEC standards.
- Automatic:Systems operate between 400 and 800 containers per minute with integrated programmable logic controllers and servo-driven applicator heads. Beverage bottlers in Germany and the United States anchor demand for these configurations, driven by line-speed requirements in high-volume carbonated soft drink and bottled water facilities. FDA and EU food-contact material validations represent the primary certification burden.
- Semi-Automatic:Batch-flexible units accommodate 50 to 200 containers per minute with operator-assisted container loading and manual changeover protocols. Craft distillers in Kentucky and Scotland favor these systems for seasonal SKU rotation and limited-run premium spirits packaging. Shorter commissioning timelines and reduced electrical safety documentation accelerate deployment.
- Manual:Hand-fed applicators serve prototype laboratories and regional dairy trial runs with minimal capital outlay.
- Electric:All-electric architectures eliminate pneumatic dependencies and reduce energy consumption in sustainability-focused European installations.
Automatic systems sit at the top of the volume ranking, with semi-automatic climbing the fastest.
End User:
Margin structures diverge sharply across end-use segments, with pharmaceutical applications commanding premium pricing for validation-intensive deployments.
- Food & Beverage:Bottlers require 360-degree sleeve coverage for carbonated drinks, functional beverages, and craft spirits, with thermal tunnel specifications calibrated for PET-G substrate migration. North American craft distilleries and German mineral water producers drive replacement demand as PVC phase-outs accelerate.
- Pharmaceuticals:Tamper-evident sleeve applications for vaccines and biologics mandate FDA 21 CFR Part 11 compliance, extending qualification periods substantially. Swiss and Austrian packagers lead European adoption due to pre-existing sustainability procurement mandates.
- Personal Care:Steam-based surface finishing specifications from Japanese and South Korean cosmetics brands prioritize gloss-critical shelf presentation over thermal efficiency.
- Consumer Goods:Household chemical and automotive product lines utilize shrink sleeves for chemical resistance and label durability in high-moisture environments.
Food & Beverage captures the largest installed base, though pharmaceuticals demonstrate the steepest expansion trajectory.
Technology:
Energy intensity per container varies threefold across thermal modalities, with infrared pre-heating modules commanding capital premiums for high-speed lines.
- Thermal:Convection and radiant heat systems dominate beverage installations for energy efficiency and operational simplicity. European bottlers above 600 containers per minute increasingly specify zone-specific temperature profiling to reduce film-wrinkle rejection rates.
- Steam:Saturated steam tunnels deliver superior surface gloss for personal care applications in Japan and South Korea, sustaining technology diversification despite higher energy consumption.
- Infrared:Pre-heating modules with real-time curve adjustment enable rapid substrate transitions without mechanical tunnel reconfiguration.
- Electronic:Induction and radio-frequency systems serve niche applications in moisture-sensitive pharmaceutical packaging.
Thermal technology holds the dominant share, with infrared gaining share fastest among high-speed European bottlers.
Application:
Downstream inspection integration complexity concentrates in bottling and labeling stages, where 360-degree coverage demands precise shrink-curve calibration.
- Bottling:Primary container decoration for carbonated soft drinks, bottled water, and alcoholic beverages requires applicator-tunnel synchronization at line speeds exceeding 600 containers per minute. German OEMs integrate shrink-label stations with downstream vision systems from Cognex and Keyence.
- Capping:Tamper-evident band application demands precise heat distribution to avoid cap seal compromise.
- Packaging:Multi-pack collation and promotional bundling utilize shrink sleeves for unitization.
- Labeling:Standalone sleeve application for pre-formed containers serves contract packaging and seasonal promotional runs.
Bottling commands the highest equipment value per line, with labeling expanding most quickly in contract packaging segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial machinery corridor concentrates shrink-label line integration with downstream inspection systems, driving European equipment specification standards across beverage and pharmaceutical installations.
United States
Craft distilleries in Kentucky and Tennessee deploy semi-automatic units for seasonal SKU rotation, while Wisconsin dairy cooperatives pursue service-unbundled procurement models. FDA food additive provisions govern direct-contact sleeve materials for beverage applications. Greater Chicago packaging machinery distributors anchor Midwest retrofit demand as PVC phase-outs accelerate.
Germany
Mineral water producers and carbonated soft drink bottlers specify zone-specific infrared pre-heating modules above 600 containers per minute. EU REACH Annex XVII restrictions on phthalate plasticizers compel thermal-tunnel OEMs to validate PET-G shrink-curve parameters. Bavaria's automation corridor hosts integrated bottling-line architecture development with vision-system synchronization.
Japan
Cosmetics brands specify steam-tunnel systems for gloss-critical shelf presentation in personal care applications. METI industrial efficiency guidelines influence thermal-tunnel energy consumption specifications. Osaka-Kobe packaging machinery clusters sustain technology diversification despite thermal efficiency advantages elsewhere.
South Korea
PET-G film substrate production clusters expose converters to freight-cost volatility and currency-hedging complexity. MFDS pharmaceutical packaging regulations extend validation timelines for tamper-evident sleeve applications. Busan-Ulsan chemical processing corridors supply film substrates to regional converters and export markets.
Switzerland
Pharmaceutical and biologics packagers lead European adoption of sustainability-mandated substrate transitions. Swissmedic regulatory frameworks govern vaccine packaging validation requirements. Basel's pharmaceutical packaging cluster integrates shrink-sleeve application with track-and-trace aggregation stations.
Shrink Label Machine Market Competitive Landscape
Strategic partnerships dominate the current landscape as OEMs align thermal-tunnel specifications with substrate transitions. The vendor base organizes around three tiers: integrated bottling-line architects, specialized shrink-label machinery fabricators, and regional distributors with third-party service networks. Two competitive moves define positioning: technology licensing for infrared pre-heating modules and geographic expansion through film-to-machine bundling contracts.
Within the integrated-system tier, Krones AG exemplifies European bottling-line architecture, while Fuji Seal International occupies a position across Asia-Pacific through specialized bundling arrangements. PDC International represents precision thermal-tunnel differentiation for high-speed pharmaceutical lines. These three anchors illustrate how competitive positioning fragments across substrate compatibility, line-speed specification, and end-use certification requirements.
| Leading Market Players |
|---|
| Krones AG |
| Fuji Seal International |
| Accraply |
| PDC International |
| Pack Leader Machinery |
| Axon |
| BW Integrated Systems |
| Accutek Packaging Equipment |
| Karlville |
| Others |
Value Network & Pricing Analysis
EU REACH Annex XVII mandates on phthalate-free substrates are compelling beverage converters to absorb retrofit costs for PET-G-compatible thermal tunnels, compressing procurement budgets and forcing OEMs to unbundle service contracts to preserve deal flow. This specification-driven demand shift concentrates price negotiation leverage with buyers operating multi-line facilities in Germany and the United States.
Pricing Analysis
Input-cost pass-through from PET-G resin premiums and energy-intensive infrared module fabrication sustains three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on line-speed certification and FDA validation tier, with pharmaceutical-grade systems commanding substantial premiums over food-contact configurations. Cost compression in the semi-automatic tier is intensifying because regional dairy processors and craft distillers now source maintenance independently. Craft spirits producers exhibit highest price sensitivity due to batch-volume volatility, while pharmaceutical packagers demonstrate lowest sensitivity given 21 CFR Part 11 compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and South Korean PET-G film substrate production, exposing converters to freight-cost volatility and currency-hedging complexity. Machine fabrication draws from precision servo motor suppliers in Japan, control system integrators in Germany, and stainless steel framing sourced from Chinese and Italian metalwork clusters. Tariff exposure on Chinese electrical components constitutes the dominant structural risk. Distribution runs through OEM-direct channels for integrated bottling lines and independent machinery distributors for semi-automatic units in North American dairy and spirits segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal packaging waste directives and FDA substrate contact rules continuously refreshing equipment replacement cycles across beverage and pharmaceutical installations.
For Market Incumbents: Cement substrate-transition service capabilities to lock replacement demand as PVC phase-outs accelerate across European bottling corridors. Backward integration into PET-G film supply partnerships insulates margin pressure from resin cost volatility. Prioritize infrared pre-heating module R&D to defend positioning against emerging thermal-tunnel specialists targeting high-speed beverage lines above 600 containers per minute. For New Entrants and Emerging Players: Capture semi-automatic demand fragmentation in Kentucky bourbon distilleries and Wisconsin dairy cooperatives where service-unbundling procurement patterns create vendor-switching opportunities. The craft spirits segment presents the most penetrable white space due to seasonal SKU rotation requirements and abbreviated validation cycles. A rental-plus-maintenance subscription model addresses capital-constrained regional processors seeking operational flexibility without single-source accountability. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized thermal-tunnel fabricators possessing validated PET-G shrink-curve expertise and established pharmaceutical validation track records. Long-term viability rests on regulatory tailwinds persisting across substrate transitions and serialization integration requirements. The signal to watch is extended producer responsibility fee structures in France and Italy rewarding mono-material sleeve compatibility, which would accelerate specification advantages for PET-G-exclusive machine lines.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Compatibility Certification | EU REACH compliance validates PET-G thermal profiles, unlocking European beverage retrofit demand. |
| Infrared Pre-heating Module Development | Zone-specific temperature profiling reduces film-wrinkle rejection rates above 600 containers per minute. |
| Service Contract Unbundling | Independent maintenance networks address craft distillery and dairy processor flexibility requirements. |
| Pharmaceutical Serialization Integration | FDA 21 CFR Part 11 convergence with track-and-trace aggregation opens vaccine packaging demand. |
| Film-to-Machine Bundling Contracts | Captive substrate supply agreements lock converter loyalty across Asia-Pacific bottling installations. |
Research Methodology
Bottom-up beverage and pharmaceutical end-use modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with bottling line engineers, aftermarket service directors, PET-G film procurement leads, and regulatory compliance officers at packaging converters were validated against secondary sources including EU ECHA regulatory filings, FDA 21 CFR guidance documents, SEC equipment manufacturer disclosures, and German mechanical engineering association production statistics. This dual-layer approach ensures installed base estimates align with substrate transition timelines across European and North American facilities.
Input-output matrices mapping PET-G resin supply constraints, thermal-tunnel energy specifications, and line-speed certification tiers generate volume and value projections across the analysis window. Segmentation dimensions encompass product type, end-use industry, thermal technology modality, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating replacement cycle acceleration from PVC phase-out mandates and pharmaceutical serialization adoption rates.
Resin supply disruptions, regulatory timeline delays, and technician re-certification bottlenecks are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding substrate transition velocity and OEM capacity expansion plans. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Straw Machine Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Shrink Wrapping Machines Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Global Tissue Paper Converting Machines Market
Packaging Machinery
Tray Packing Machine Market