
 Pallet Strapping Machines Market | 2026-2036
Pallet Strapping Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Strapping Machines Market Analytics
Preventive maintenance contracts and software-defined tension control is decoupling hardware margins from lifetime revenue in pallet strapping. Signode Industrial Group leverages its captive service network to lock in multi-year aftermarket streams. Mosca GmbH anchors its position through R&D intensity in electronic strapping heads. FROMM Packaging Systems competes on geographic dominance across European distribution channels.
Pallet strapping machines apply polymer or steel bands around unitized loads at tensions typically ranging from 150 to 2,500 Newtons to secure goods for transport and storage. Automatic strapping systems lead the product type dimension where labor cost arbitrage justifies capital deployment in high-throughput environments. Electronic technology segments are expanding fastest as programmable logic controllers enable real-time tension adjustment and remote diagnostics. Pallet strapping as an application category commands the deepest margin pools due to load-weight specifications and cycle-time requirements that favor premium equipment configurations.
OSHA workplace safety standards in the United States and CE machinery directives in Europe shape guard design, emergency stop placement, and operator training requirements for strapping equipment manufacturers. ISO 9001 quality management certification and EU Green Deal circular-economy provisions on plastic waste are tightening material traceability obligations across the supply base. Stakeholders must monitor how strapping material regulations in target geographies constrain machine compatibility and retrofit economics.
Market Dynamics
Electronic tension control systems and predictive maintenance software are decoupling equipment revenue from lifetime value capture, forcing manufacturers to restructure pricing around throughput guarantees rather than hardware margins.
Growth Catalysts
- E-commerce fulfillment velocity:Third-party logistics operators in Germany and the Netherlands are specifying sub-15-second cycle times for automated strapping lines, pulling demand toward high-speed arch-type machines.
- REACH compliance on plastic strapping:European ECHA restrictions on virgin polypropylene content are accelerating converter investment in polyester-compatible strapping heads with adjustable heat-seal parameters.
- Steel strap substitution:Heavy-gauge polyester developments are displacing metal banding in construction materials and metal coil applications, expanding addressable unit volume for polymer-focused equipment suppliers.
Market Restraints
- Raw material volatility:Petrochemical feedstock fluctuations for polypropylene and PET resins compress converter margins and delay capital replacement cycles for downstream strapping equipment.
- Supply concentration in electronic controls:German and Japanese PLC and servo motor suppliers dominate motion control subsystems, creating single-source vulnerability for mid-tier machine builders.
- Technical ceiling on lightweight loads:Current ultrasonic welding heads struggle to maintain seal integrity on stretch-wrapped pallet loads below 200 kilograms, limiting penetration in fresh produce and pharmaceutical distribution.
Strategic Opportunities
- Underpenetrated Indian warehousing:Cold chain expansion and GST-driven logistics consolidation are creating first-mover openings for semi-automatic strapping systems in Mumbai and Bangalore distribution hubs.
- Remanufacturing and retrofit services:EU Green Deal circular economy provisions on extended producer responsibility are creating compliant revenue streams for hardware refurbishment and control system upgrades.
- Integration with warehouse execution systems:Convergence of IoT-enabled strapping heads with WES platforms enables real-time throughput verification and predictive consumables replenishment.
Industry Challenges
- Electromechanical technician scarcity:Maintenance of servo-driven strapping heads requires hybrid mechanical-electrical competencies that vocational training pipelines in Eastern Europe and Southeast Asia have not scaled to match installed base growth.
- CE machinery directive certification timelines:Validation of safety PLC configurations and guard interlock systems for automatic arch machines extends product launch cycles by eight to fourteen months.
- Legacy pneumatic system integration:Retrofit of electronic tension control onto existing compressed-air strapping lines demands custom mechanical adapters that fragment engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Strapping Machines Market |
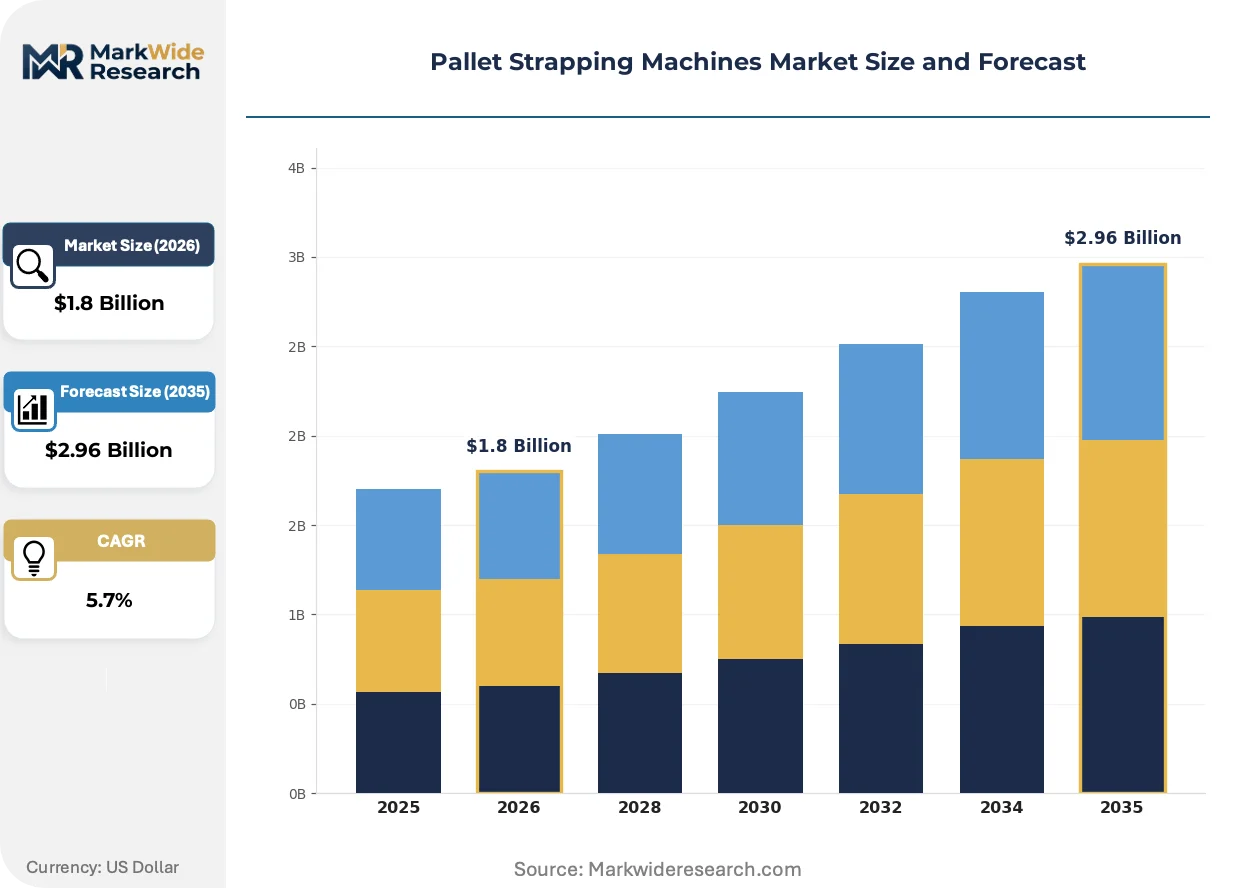
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Electric End User: Manufacturing, Logistics, Packaging, Warehouse Technology: Pneumatic, Mechanical, Electronic, Hydraulic Application: Box Strapping, Pallet Strapping, Carton Strapping, Bundle Strapping |
| Companies Covered | Signode Industrial Group LLC, Mosca GmbH, FROMM Packaging Systems, Polychem Corporation, StraPack Inc., Dynaric Inc., Cyklop International, Samuel Strapping Systems, Fromm Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Strapping Machines Market Evolving Landscape
Software-defined functionality and material science advances are compressing the traditional hardware replacement cycle while opening service-based revenue architectures that favor integrated solution providers over component specialists.
Ultrasonic welding technology for polyester strapping is rewriting the competitive boundary between steel and polymer systems. Food and beverage distributors with high-moisture environments are specifying sealed-band units at triple the rate of conventional heat-seal alternatives. This shift is compressing the addressable market for metal banding equipment while expanding margin pools for precision welding head manufacturers.
EU Green Deal circular-economy provisions on plastic waste traceability are mandating recycled-content verification across strapping supply chains. Equipment manufacturers must now certify compatibility with variable-density regrind materials that exhibit inconsistent melt behavior. German converters are responding by specifying strapping heads with real-time temperature compensation algorithms.
Buyer preference for outcome-based throughput contracts is displacing traditional equipment purchase models in high-volume fulfillment operations. Third-party logistics operators in the Netherlands and Belgium are unbundling hardware ownership from maintenance and consumables supply. This reconfiguration concentrates vendor selection power with service-integrated suppliers capable of guaranteeing line availability metrics.
Pallet Strapping Machines Market Segmentation
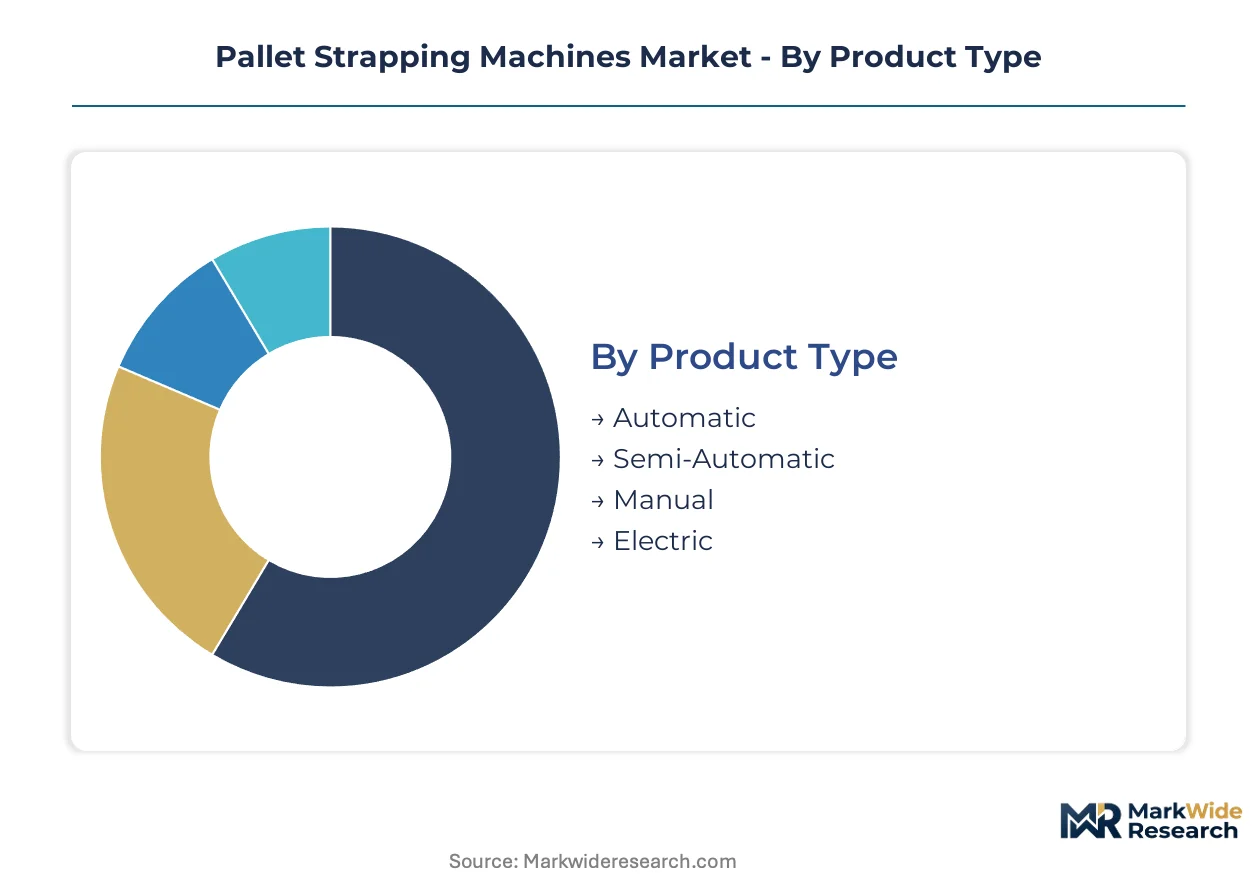
Pallet strapping machines serve distinct operational profiles across fulfillment density tiers, with equipment selection governed by throughput requirements, labor availability, and integration depth with upstream conveying systems. Segmentation reveals where hardware margins concentrate versus where service-based revenue models are displacing traditional capital sales.
Product Type:
Automatic systems operate as embedded components within continuous conveyor lines, while semi-automatic and manual units function in standalone configurations with operator-dependent cycle initiation.
- Automatic:Arch-type machines with programmable logic controllers execute strapping cycles without operator intervention at tensions up to 2,500 Newtons. Demand clusters in German and Dutch e-commerce fulfillment centers where sub-15-second cycle specifications justify capital deployment.
- Semi-Automatic:Operator-fed systems bridge low-volume manufacturing and mid-tier distribution, requiring manual load positioning while automating tensioning and sealing. Indian cold chain expansion in Mumbai and Bangalore distribution hubs is pulling first-mover procurement toward this tier.
- Manual:Hand-held tensioning tools serve field applications and micro-fulfillment operations with minimal capital budgets.
- Electric:Battery-powered portable units address mobile warehousing and construction material yards without compressed air infrastructure.
Volume placements concentrate in Automatic; the faster expansion belongs to Semi-Automatic.
End User:
Cost tier differentiation separates capital-intensive integrated lines from standalone equipment, with procurement authority residing in operations teams versus maintenance departments.
- Manufacturing:Heavy-gauge polyester developments are displacing steel banding in metal coil and construction material applications. OSHA workplace safety standards in the United States mandate guard interlock configurations that extend equipment validation timelines.
- Logistics:Third-party operators in Belgium and the Netherlands are unbundling hardware ownership from maintenance contracts, concentrating vendor power with service-integrated suppliers.
- Packaging:Converters face REACH compliance pressures on virgin polypropylene content, accelerating investment in polyester-compatible strapping heads.
- Warehouse:GST-driven consolidation in Indian distribution networks is creating procurement scale for standardized semi-automatic deployments.
Manufacturing commands the deepest margin pools; Logistics exhibits the steepest shift toward outcome-based contracting.
Technology:
Control architecture maturity determines maintenance technician requirements and predictive maintenance software compatibility, with electronic systems enabling remote diagnostics that pneumatic and mechanical alternatives cannot support.
- Pneumatic:Legacy compressed-air systems dominate installed bases in Eastern European manufacturing, though retrofit demand for electronic tension control fragments engineering resources.
- Mechanical:Cam-driven tensioning heads persist in cost-sensitive applications with minimal cycle variability requirements.
- Electronic:Servo-driven strapping heads with real-time tension adjustment require hybrid mechanical-electrical competencies that vocational training pipelines have not scaled to match installed base growth.
- Hydraulic:High-force applications in metal processing and heavy construction materials rely on fluid power for extreme tension specifications beyond electromechanical limits.
Pneumatic retains the largest installed base; Electronic is climbing the fastest as programmable logic controllers enable throughput guarantees.
Application:
Load-weight specifications and cycle-time requirements create margin stratification, with pallet-level unitization commanding premium equipment configurations versus lighter bundle applications.
- Pallet Strapping:Unitized load securing at 150-2,500 Newtons spans polymer and steel banding, with ultrasonic welding heads gaining specification in high-moisture food and beverage distribution.
- Box Strapping:Corrugated container reinforcement in manufacturing shipping departments favors semi-automatic systems with quick strap width changeover.
- Carton Strapping:Retail-ready packaging lines specify heat-seal or friction-weld heads compatible with recycled-content strapping materials under EU Green Deal traceability mandates.
- Bundle Strapping:Newspaper, printing, and textile aggregation applications utilize lightweight pneumatic tools with minimal tension precision requirements.
Pallet Strapping captures the highest average selling prices; Carton Strapping faces the tightest material compatibility constraints from circular-economy regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of high-end electronic strapping heads consumed across Europe and Asia, while the United States and China absorb disproportionate shares of automatic system installations in e-commerce fulfillment infrastructure.
United States
Third-party logistics operators in California and Texas are specifying sub-15-second cycle times for automated strapping lines, pulling procurement toward high-speed arch-type machines. OSHA workplace safety standards mandate guard interlock configurations and emergency stop placement that extend equipment validation timelines. The Chicago-Milwaukee corridor hosts dense clusters of food and beverage distribution centers where ultrasonic welding heads are displacing conventional heat-seal systems.
Germany
REACH compliance pressures on virgin polypropylene content are accelerating converter investment in polyester-compatible strapping heads with adjustable heat-seal parameters. The EU Green Deal circular-economy provisions mandate recycled-content verification across strapping supply chains. Mosca GmbH and FROMM Packaging Systems anchor a machinery cluster in Baden-Württemberg that supplies electronic tension control systems throughout European distribution networks.
China
Domestic e-commerce fulfillment expansion in the Yangtze River Delta and Pearl River Delta is driving procurement of semi-automatic systems for mid-tier warehousing operations. MIIT industrial equipment standards and GB machinery safety certifications shape guard design and control system architecture. Shenzhen and Shanghai distribution hubs are integrating IoT-enabled strapping heads with warehouse execution systems for real-time throughput verification.
India
Cold chain expansion and GST-driven logistics consolidation in Mumbai and Bangalore distribution hubs are creating first-mover openings for semi-automatic strapping systems. BIS certification requirements for industrial machinery and DGFT import regulations influence equipment sourcing patterns. The Delhi-NCR corridor is emerging as a procurement concentration point for standardized deployments across third-party logistics networks.
Netherlands
Rotterdam and Amsterdam fulfillment operators are unbundling hardware ownership from maintenance and consumables supply, concentrating vendor selection power with service-integrated suppliers. CE machinery directives govern safety PLC configurations and guard interlock systems for automatic arch machines. The Randstad logistics cluster is pioneering outcome-based throughput contracts that guarantee line availability metrics rather than traditional capital purchase arrangements.
Pallet Strapping Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the pallet strapping machines market, with integrated manufacturers maintaining captive control over electronic strapping head production while specialized assemblers source motion control subsystems from German and Japanese PLC suppliers. The vendor base stratifies into three tiers: premium-tier specialists with proprietary tension control algorithms, mid-tier regional fabricators serving price-sensitive distribution networks, and economy-tier assemblers focused on pneumatic legacy system replacement. Consolidation pressure is intensifying through strategic partnerships between equipment manufacturers and consumables suppliers, alongside geographic expansion into underpenetrated Indian and Southeast Asian warehousing markets.
Within the premium-tier electronic systems segment, Mosca GmbH and Signode Industrial Group occupy positions that exemplify divergent approaches to aftermarket value capture. Mosca GmbH anchors its market presence through Baden-Württemberg-based R&D intensity in electronic strapping heads. Signode Industrial Group leverages its captive service network to structure multi-year preventive maintenance contracts. FROMM Packaging Systems represents the geographic dominance archetype across European distribution channels.
| Leading Market Players |
|---|
| Signode Industrial Group LLC |
| Mosca GmbH |
| FROMM Packaging Systems |
| Polychem Corporation |
| StraPack Inc. |
| Dynaric Inc. |
| Cyklop International |
| Samuel Strapping Systems |
| Fromm Holding AG |
| Others |
Value Network & Pricing Analysis
Captive production of electronic strapping heads by German specialists anchors both supply security and premium pricing power across European distribution networks. This backward integration into precision motion control subsystems insulates tier-one manufacturers from PLC sourcing volatility while supporting multi-year service contract premiums.
Pricing Analysis
Margin tightening in mid-tier pneumatic equipment reflects petrochemical feedstock volatility and delayed replacement cycles among Eastern European converters. Three-tier pricing structure across premium electronic, standard semi-automatic, and economy manual tiers separates vendors by certification grade and after-sales bundling intensity. Cost-down pressure on standard-tier systems accelerates as Indian warehousing consolidation drives volume procurement of semi-automatic units. Logistics operators in the Netherlands and Belgium exhibit lowest price sensitivity, having unbundled hardware ownership from outcome-based throughput guarantees.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for strapping consumables and spare parts across European fulfillment networks. Manufacturing concentration in Germany, China, and Japan feeds from specialized servo motor production, precision steel fabrication, and polymer resin compounding. Single-source vulnerability in German and Japanese PLC suppliers creates structural risk for mid-tier machine builders lacking captive electronic control production. Distribution runs through authorized service networks that lock in aftermarket revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid electromechanical technician scarcity props pricing for preventive maintenance contracts, concentrating vendor power with integrated service providers capable of guaranteeing line availability.
For Market Incumbents: Lock in multi-year aftermarket streams through predictive maintenance software deployment and captive consumables supply. Counter emerging entrants from Chinese automation specialists by deepening backward integration into electronic tension control algorithms. Prioritize CE machinery directive certification investment to extend launch cycle moats against faster-moving competitors. For New Entrants and Emerging Players: Enter via semi-automatic system deployment in Indian cold chain expansion around Mumbai and Bangalore distribution hubs. Target GST-consolidated third-party logistics networks seeking standardized equipment procurement at scale. Lead with IoT-enabled strapping head integration for warehouse execution system compatibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated packaging equipment conglomerates seeking geographic footprint expansion. Long-term viability favors vendors with captive electronic strapping head production and service network density rather than pure-play assemblers. Monitor ultrasonic welding head adoption rates in food and beverage distribution as the inflection indicator for polymer substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electronic Controls | Captive PLC and servo motor production insulates margin from German and Japanese supplier concentration. |
| Predictive Maintenance Software Deployment | Real-time diagnostics enable outcome-based contracting with Dutch and Belgian logistics operators. |
| Geographic Expansion into Indian Warehousing | Cold chain infrastructure buildout in Mumbai and Bangalore creates first-mover procurement scale. |
| Ultrasonic Welding Head Development | Sealed-band technology captures specification shifts in high-moisture food and beverage distribution. |
| Remanufacturing and Retrofit Services | EU Green Deal extended producer responsibility mandates create compliant revenue from hardware refurbishment. |
Research Methodology
Multi-period observation of strapping equipment procurement cycles, maintenance contract structures, and consumables pricing anchored the trend analysis, supplemented by interviews with plant engineers, aftermarket service heads, OEM procurement teams, and logistics operations directors. Secondary validation drew from customs trade data, SEC filings of listed packaging equipment manufacturers, EU ECHA regulatory databases, and industrial machinery certification records. Bottom-up equipment shipment tallies and top-down end-use industry demand estimates were triangulated to constrain forecast variance.
Segment-weighting across product type, technology architecture, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from modeled adoption curves for electronic versus pneumatic systems, projected e-commerce fulfillment center buildouts, and REACH compliance-driven material substitution timelines. Industry-specific inputs included warehouse automation capital expenditure patterns and third-party logistics operator consolidation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material volatility spikes or accelerated steel-to-polymer substitution in construction materials. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Chocolate Wrapping Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market