
 Garlic Market | 2026-2036
Garlic Market Size, Share, and Industry Trends Forecast 2026-2036
Garlic Market Analysis
EU Green Deal agricultural sustainability criteria is restructuring the cost-of-entry calculus for European garlic importers, forcing traceability investments and carbon-footprint documentation across supply chains. McCormick And Company Inc. leverages its spice portfolio scale to secure long-term contracts with certified organic growers across multiple continents. Christopher Ranch anchors California's fresh garlic production through integrated farming and processing operations that control quality from field to package. Daesang Corporation competes in Asian markets through fermented garlic derivatives and specialized food-service formulations.
Garlic comprises sulfur-containing organosulfur compounds, principally alliin and its enzymatic derivative allicin, with dried products typically standardized to moisture content below 6% for shelf stability. The bulb serves as both culinary staple and source of nutraceutical extracts targeting cardiovascular and antimicrobial applications. Fresh Garlic occupies the largest volume share in retail and food-service channels, though Dehydrated Garlic commands premium margins from industrial buyers seeking consistent year-round supply. Pharmaceutical-grade Garlic Oil extracts represent the fastest-expanding revenue pool, driven by contract manufacturers demanding certified allicin potency for supplement formulations.
FDA dietary supplement Good Manufacturing Practices and USDA National Organic Program standards govern product claims and certification pathways in the United States, while EFSA novel food assessments shape European market access for innovative garlic-derived ingredients. China's SAMR and GB standards for pesticide residues directly constrain export eligibility for major producing regions. Stakeholders must monitor evolving allicin measurement methodologies and jurisdiction-specific maximum residue limits to sustain competitive positioning.
Market Dynamics
China's SAMR residue threshold tightening is forcing export-oriented garlic processors to rebuild compliance infrastructure from farm-level traceability through finished-product certification, compressing margins for non-integrated suppliers.
Growth Catalysts
- Allicin standardization protocols:Pharmaceutical contract manufacturers now require certified potency documentation for cardiovascular supplement formulations, pulling volume toward extraction-grade bulb supply.
- India:Ayurvedic medicine corridors and processed food manufacturing clusters are expanding domestic processing capacity to reduce import dependency.
- EU Green Deal:Agricultural sustainability criteria are mandating carbon-footprint documentation and regenerative farming verification for import eligibility.
Market Restraints
- Input cost volatility:Sulfur-based fertilizer prices fluctuate with energy markets, directly pressuring farm-level production economics in major growing belts.
- Supply concentration:China's Shandong and Henan provinces control disproportionate fresh bulb export volume, creating single-origin vulnerability for international buyers.
- Technical limitation:Allicin degradation during thermal processing constrains shelf-stable product potency claims, limiting functional food applications.
Strategic Opportunities
- Brazil:ANVISA's expanding dietary supplement registration pathways are opening formal market access for standardized garlic extract imports.
- Fermented derivatives:Black garlic and aged extract formulations command premium positioning in functional food and cosmetic applications.
- Direct-to-manufacturer channels:Food-service and industrial buyers are bypassing traditional spice traders to secure long-term contracted supply with quality guarantees.
Industry Challenges
- Allicin measurement standardization:Jurisdiction-specific assay methodologies create certification friction for multi-market suppliers.
- Organic certification timelines:USDA National Organic Program and EU organic transition periods extend 24-36 months, locking up working capital.
- Legacy dehydration infrastructure:Energy-intensive drying equipment faces carbon accounting pressure under emerging supply chain disclosure rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garlic Market |
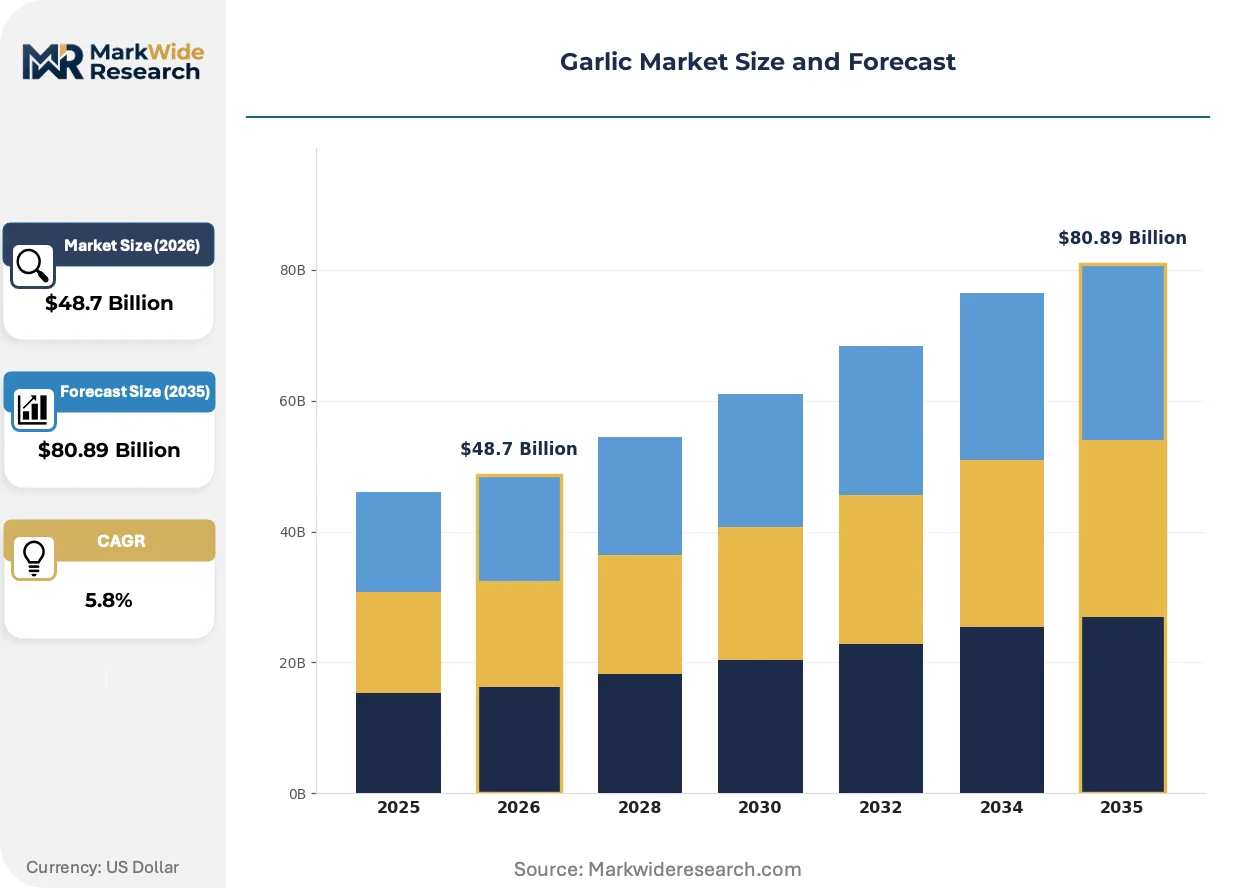
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Garlic, Dehydrated Garlic, Garlic Powder, Garlic Oil End User: Food Service, Retail, Pharmaceutical, Cosmetics Distribution Channel: Supermarket, Online Store, Wholesale, Specialty Stores Form: Whole Bulbs, Cloves, Minced, Granulated |
| Companies Covered | Daesang Corporation, The Spice Hunter Inc., McCormick And Company Inc., California Garlic Company, Jining Forich Fruits and Vegetables Co. Ltd., Ajinomoto Co. Inc., Dabur India Ltd., Christopher Ranch, The Hain Celestial Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garlic Market Emerging Trajectories
Processing technology and regulatory measurement protocols are converging to redefine quality verification and supply chain transparency across garlic-derived ingredient categories.
Near-infrared spectroscopy is absorbing quality control functions previously handled by chromatography labs, enabling real-time allicin potency verification at processing facilities. Mid-sized extract manufacturers in Spain and Argentina are adopting inline sensors to reduce batch rejection rates. The technology is absorbing capital investment that would otherwise flow to centralized laboratory infrastructure.
REACH and EU Green Deal agricultural sustainability criteria are mandating farm-level carbon accounting and pesticide residue documentation for import eligibility. European importers now require supplier data spanning cultivation inputs, irrigation energy sources, and post-harvest handling. Fresh and dehydrated garlic shipments to Germany, France, and the Netherlands face the most stringent verification timelines.
Food-service operators are consolidating spice procurement through integrated supply agreements that bundle garlic with complementary ingredients. Industrial buyers in North American and European prepared food manufacturing are displacing spot-market purchasing with 12-24 month contracts specifying origin, certification grade, and volume flexibility terms. This concentration is most visible in contract manufacturing for private-label retail brands.
Garlic Market Segmentation
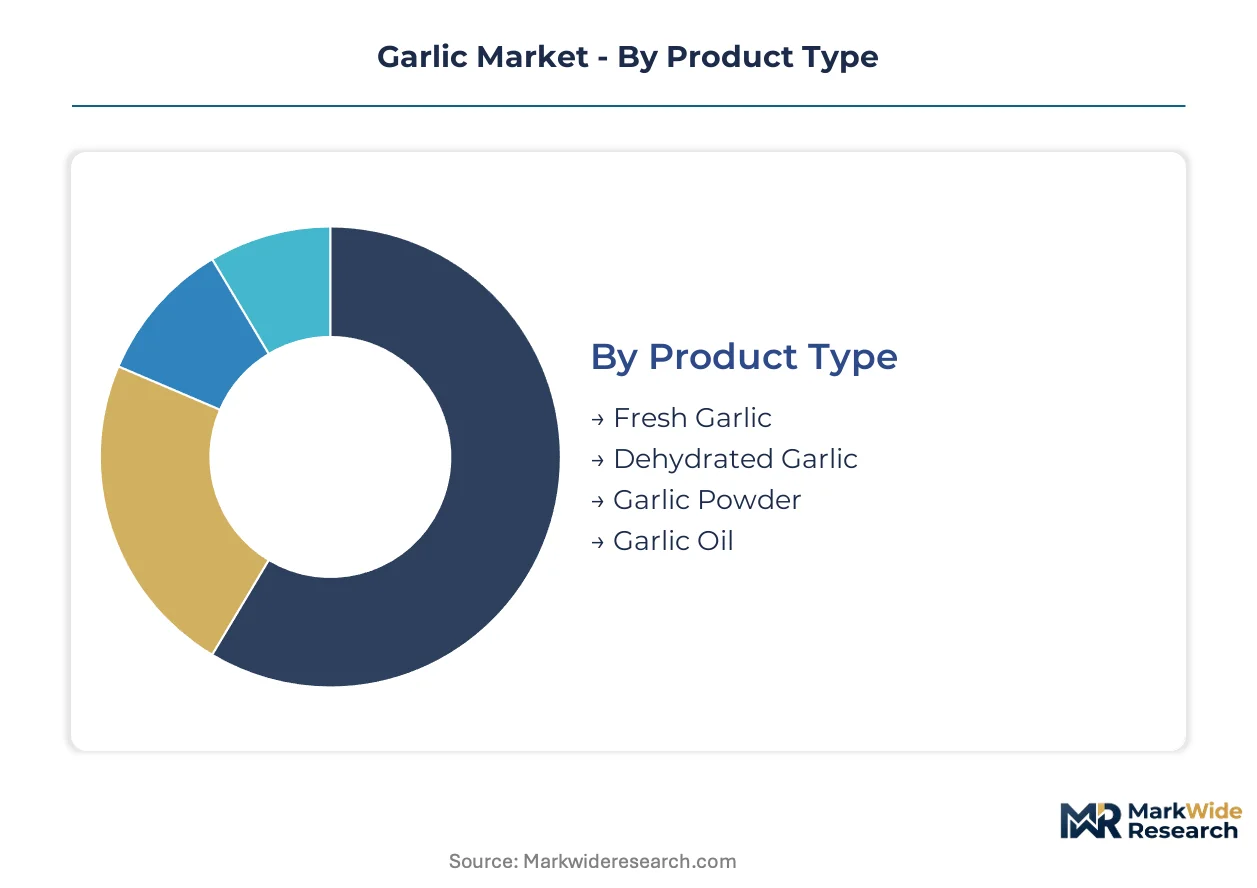
Garlic market segmentation reflects divergent supply chain requirements between perishable fresh channels and shelf-stable processed formats. Pharmaceutical and cosmetic end-uses are pulling standardized extract demand toward certified potency specifications, while food-service consolidation favors bulk dehydrated supply with year-round availability guarantees.
Product Type:
Volume leadership sits with fresh bulb supply, yet margin capture concentrates in extraction-grade and dehydrated categories where processing adds measurable value.
- Fresh Garlic:Field-harvested bulbs with typical moisture content above 60% require cold-chain logistics and rapid turnover through retail and food-service channels. India's domestic processing corridors and European wholesale markets absorb the largest shipment volumes, constrained by seasonal availability windows and perishability limits.
- Dehydrated Garlic:Sliced or diced bulbs dried to below 6% moisture content deliver shelf-stable supply for industrial food manufacturing and seasoning blends. Food-service operators in North America and European prepared-food manufacturers contract for consistent year-round availability, paying premiums over fresh spot markets during off-season periods.
- Garlic Powder:Finely milled dehydrated product standardized to specific mesh sizes for uniform dispersion in dry seasoning applications.
- Garlic Oil:Steam-distilled or solvent-extracted concentrate containing sulfur compounds for pharmaceutical and cosmetic formulations.
Mature deployment sits with Fresh Garlic. Newer deployment is concentrated in Garlic Oil.
End User:
Application concentration spans commodity food preparation through high-margin functional ingredient supply, with regulatory intensity escalating toward pharmaceutical endpoints.
- Food Service:Restaurant chains, institutional catering, and prepared-meal manufacturers purchase peeled cloves, minced preparations, and dehydrated forms in bulk tote quantities. India's Ayurvedic medicine corridors and North American quick-service chains represent divergent demand poles, both seeking supply security through contracted procurement rather than spot purchasing.
- Retail:Supermarkets and specialty grocers stock whole bulbs, pre-peeled cloves, and jarred minced preparations for household consumption. China's updated SAMR food safety protocols for agricultural exports are tightening residue thresholds and reshaping supplier compliance costs for packaged retail goods.
- Pharmaceutical:Contract manufacturers demand certified allicin potency for cardiovascular and antimicrobial supplement formulations.
- Cosmetics:Fermented black garlic and aged extract derivatives command premium positioning in skincare applications.
Volume concentration remains with Food Service. Value expansion is accelerating fastest in Pharmaceutical.
Distribution Channel:
Channel selection reflects buyer scale and certification requirements, with industrial procurement bypassing traditional retail intermediaries.
- Supermarket:Branded fresh and packaged garlic products reach household consumers through conventional grocery retail. European importers now require carbon-footprint documentation and regenerative farming verification under EU Green Deal agricultural sustainability criteria.
- Wholesale:Food-service distributors and industrial ingredient suppliers aggregate bulk volumes for restaurant chains and manufacturing clients.
- Online Store:Direct-to-consumer platforms and B2B marketplaces connect specialty organic growers with niche buyers.
- Specialty Stores:Ethnic grocers and health-food retailers curate specific origin claims and organic certifications.
Established volume flows through Wholesale. Emerging channel investment targets Online Store infrastructure.
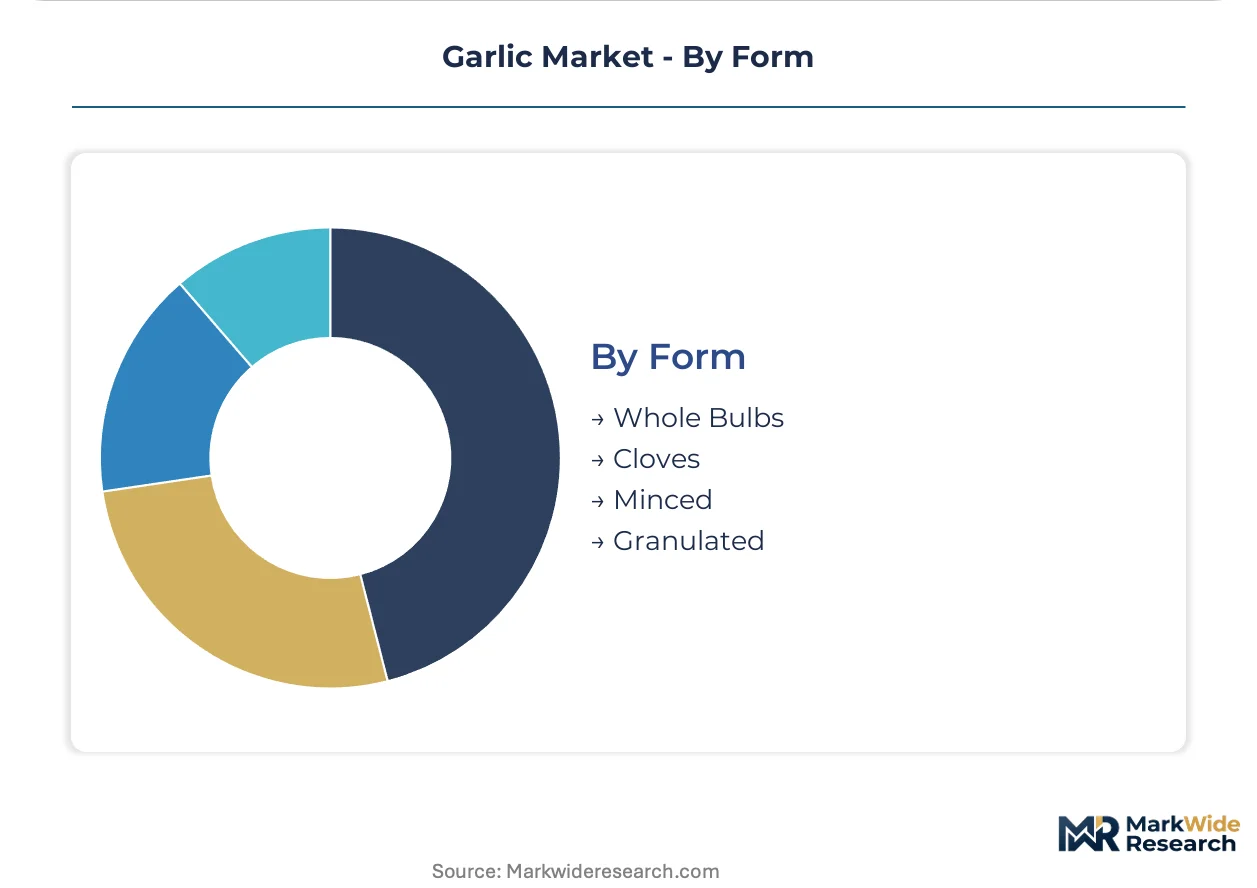
Form:
Physical preparation state determines processing economics and end-use suitability across industrial and consumer applications.
- Whole Bulbs:Unprocessed field-harvested units retain maximum shelf life under proper storage and serve retail display and food-service peeling operations.
- Cloves:Separated and often pre-peeled units reduce labor input for commercial kitchens and ready-meal manufacturing.
- Minced:Finely chopped fresh or rehydrated product delivers immediate usability for sauce and seasoning applications.
- Granulated:Coarse dehydrated particles provide texture and controlled release in dry rubs and seasoning blends.
Primary supply concentration rests with Whole Bulbs. Processing value-add is expanding fastest in Granulated formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong Free Trade Zone concentrates export-oriented processing infrastructure, pulling investment toward integrated cold-chain and dehydration facilities. India's National Food Processing Mission subsidizes garlic value-addition clusters in Madhya Pradesh and Gujarat. Brazil's Manaus Free Trade Zone incentivizes import substitution for pharmaceutical-grade extracts.
China
Shandong and Henan provinces control disproportionate fresh bulb export volume through integrated farming cooperatives. SAMR residue threshold tightening forces processors to rebuild compliance infrastructure from farm-level traceability through finished-product certification. Jining municipality anchors dehydrated garlic processing with expanded capacity targeting pharmaceutical extraction grades.
India
Ayurvedic medicine corridors in Kerala and Karnataka absorb rising volumes of allicin-standardized extracts for cardiovascular formulations. FSSAI's updated food safety protocols for agricultural exports tighten residue thresholds and reshape supplier compliance costs. Madhya Pradesh's Indore-Dewas belt expands domestic processing capacity to reduce import dependency for dehydrated industrial supply.
United States
California's Central Valley anchors fresh garlic production through integrated farming and processing operations controlling quality from field to package. FDA dietary supplement Good Manufacturing Practices govern product claims and certification pathways for pharmaceutical-grade extracts. Gilroy city clusters represent the densest concentration of organic certification infrastructure serving North American retail channels.
Germany
European wholesale markets in Hamburg and Frankfurt absorb the largest fresh and dehydrated shipment volumes for redistribution across EU member states. EU Green Deal agricultural sustainability criteria mandate carbon-footprint documentation and regenerative farming verification for import eligibility. Bavaria's ingredient processing corridor specializes in pharmaceutical-grade garlic oil extraction for supplement contract manufacturers.
Brazil
ANVISA's expanding dietary supplement registration pathways open formal market access for standardized garlic extract imports targeting cardiovascular health positioning. The country's national pharmaceutical regulator tightens documentation requirements for allicin potency claims in functional food applications. São Paulo state's food manufacturing belt consolidates procurement through integrated supply agreements bundling garlic with complementary seasoning ingredients.
Garlic Market Vendor Landscape
Chinese producers anchor one tier; Californian specialists hold premium positioning through organic certification infrastructure. The vendor base splits between scale-driven commodity processors and integrated farm-to-package operators controlling traceability documentation. Three archetypes dominate: multinational spice portfolio companies, regional fermentation specialists, and captive agricultural processors. Competitive moves concentrate on long-term contracted supply agreements and backward integration into certified organic growing operations.
Within the integrated agricultural processor tier, Christopher Ranch and California Garlic Company exemplify field-to-package control structures. McCormick And Company Inc. occupies a position representing multinational spice portfolio scale. Daesang Corporation sits within the Asian fermentation specialist archetype. These three company structures illustrate how geographic origin and corporate form factor into competitive positioning across fresh, dehydrated, and extract-grade supply segments.
| Leading Market Players |
|---|
| Daesang Corporation |
| The Spice Hunter Inc. |
| McCormick And Company Inc. |
| California Garlic Company |
| Jining Forich Fruits and Vegetables Co. Ltd. |
| Ajinomoto Co. Inc. |
| Dabur India Ltd. |
| Christopher Ranch |
| The Hain Celestial Group Inc. |
| Others |
Supply Flow & Price Mechanics
Industrial food-service buyers in North America and Europe now consolidate procurement through 12-24 month contracted supply agreements, displacing spot-market purchasing and compressing margin capture for non-integrated traders. This buyer concentration feeds directly into contract-based pricing structures that reward traceability documentation and penalize origin opacity.
Pricing Analysis
Short lead-time premiums dominate fresh bulb procurement, with food-service operators paying substantial markups for rapid-turnover cold-chain delivery during off-season windows. Three-tier pricing structure across premium organic, standard certified, and economy conventional grades separates Christopher Ranch's integrated California supply from Shandong commodity exports. Cost compression in economy-tier dehydrated products is intensifying because of sulfur-based fertilizer price volatility tied to energy markets. Small-scale spice traders exhibit highest price sensitivity, while pharmaceutical contract manufacturers demonstrate lowest sensitivity due to certified potency requirements.
Supply Chain Analysis
Single-source vulnerability sits with China's Shandong and Henan provinces, which control disproportionate fresh bulb export volume through integrated farming cooperatives. Farm-level production draws from sulfur-based fertilizers, irrigation energy, and post-harvest cold-chain infrastructure. Tariff exposure runs through evolving EU Green Deal agricultural sustainability criteria mandating carbon-footprint documentation. Distribution runs through Hamburg and Frankfurt wholesale hubs for European redistribution, with Jining municipality anchoring dehydrated processing for pharmaceutical extraction grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic growing capacity operates as the binding constraint across major supply corridors, with 24-36 month certification timelines locking up working capital and propping pricing for qualified supply. This capacity bottleneck justifies premium positioning for verified origin documentation.
For Market Incumbents: Lock in long-term contracted supply with certified organic growers across multiple continents to secure traceability documentation required by EU Green Deal criteria. Backward integration into farm-level carbon accounting infrastructure defends against emerging disclosure mandates. McCormick And Company Inc.'s spice portfolio scale exemplifies the channel control lever that blocks trader intermediation.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium organic extracts and economy conventional dehydrated products offers white-space entry for fermentation specialists targeting functional food applications. Brazil's ANVISA registration pathways represent the most penetrable geography for standardized extract imports. A direct-to-manufacturer channel strategy bypasses consolidated spice traders and captures margin through quality guarantees.
For Investors and Strategic Acquirers: The window for entry favors integrated agricultural processors with captive organic certification infrastructure and pharmaceutical-grade extraction capabilities. Mid-sized extract manufacturers in Spain and Argentina adopting near-infrared spectroscopy for real-time allicin verification represent the acquisition target archetype. Watch allicin measurement standardization harmonization across FDA, EFSA, and SAMR jurisdictions as the inflection signal indicating regulatory clarity and margin compression for multi-market suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Growing | Captures 24-36 month certification timelines and locks traceability documentation required by EU Green Deal criteria. |
| Near-Infrared Spectroscopy Adoption | Enables real-time allicin potency verification at processing facilities, reducing batch rejection rates for pharmaceutical contract manufacturers. |
| Long-term Supply Agreement with Food-Service Operators | Displaces spot-market purchasing and secures volume commitments from North American quick-service chains and European prepared-food manufacturers. |
| Fermented Derivatives Capacity Expansion | Commands premium positioning in functional food and cosmetic applications through black garlic and aged extract formulations. |
| Direct-to-Manufacturer Channel Development | Bypasses traditional spice traders and captures margin through integrated supply agreements bundling garlic with complementary seasoning ingredients. |
Methodological Framework
Multi-period observation of allicin standardization protocols, residue threshold tightening, and food-service procurement consolidation anchored the trend analysis, supplemented by interviews with garlic processing facility managers, pharmaceutical contract manufacturing procurement leads, organic certification auditors, and EU import compliance officers. Secondary validation drew from SAMR GB standards documentation, EFSA novel food assessment registers, FDA dietary supplement GMP guidance, USDA National Organic Program certification databases, and customs trade data for dehydrated garlic shipments. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, and distribution channel segmentation.
Segment-weighting approaches distributed value projections across fresh bulb, dehydrated, powder, and oil categories with pharmaceutical-grade extraction carrying highest weighting coefficients. Modeled dimensions spanned product type, end-use application, certification grade, and regional regulatory cluster throughout the forecast period. CAGRs were derived from regression analysis of historical shipment volumes and price realization data, with allicin degradation constraints during thermal processing and organic certification transition timelines incorporated as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pharmaceutical-grade extracts with certified potency documentation carry tighter precision than commodity fresh bulb spot markets. Forecasts reflect documented assumptions regarding SAMR enforcement intensity, EU Green Deal implementation timelines, and allicin assay methodology harmonization. Deviation in China's residue threshold enforcement or EFSA carbon-footprint verification requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Dehydrated Vegetables Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Sweet Potatoes Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Vegetable Chutney Market
Vegetables
North America Peas Market
Vegetables
Sprouts Market
Vegetables
Squash Market
Vegetables
Asparagus Market
Vegetables
Fresh Vegetables Market
Vegetables
Yams Market
Vegetables
Zimbabwe Fruits and Vegetables Market