
 Acorn Squash Market | 2026-2036
Acorn Squash Market Size, Share, and Industry Trends Forecast 2026-2036
Acorn Squash Market Analytics
The gap between premium heirloom acorn squash and commodity hybrid production is expanding as buyer specifications diverge. Stahlbush Island Farms leverages its vertically integrated processing infrastructure to sustain consistent supply to retail frozen channels. Sakata Vegetables dominates proprietary hybrid seed development, while Harris Seeds competes through extensive distribution networks targeting home gardeners and small-scale commercial growers.
Acorn squash (Cucurbita pepo var. turbinata) is a winter squash distinguished by its distinctive ribbed, acorn-shaped fruit with hard rind and sweet, nutty yellow-orange flesh typically weighing 1-2 pounds, primarily cultivated for fresh consumption and seasonal food manufacturing. The organic product type segment anchors premium pricing through certified supply chains with strict input controls, while the food service end use segment leads volume throughput as restaurant chains standardize roasted squash preparations; distribution through farmers' markets occupies the highest margin tier by eliminating intermediary handling costs.
USDA organic standards, FDA Food Safety Modernization Act provisions, and state department of agriculture grading protocols collectively shape grower compliance burdens and market access eligibility across interstate commerce. Stakeholders must monitor evolving consumer preference signals between convenience-oriented pre-cut retail formats and whole-squash heritage variety demand to align cultivation and processing capacity decisions.
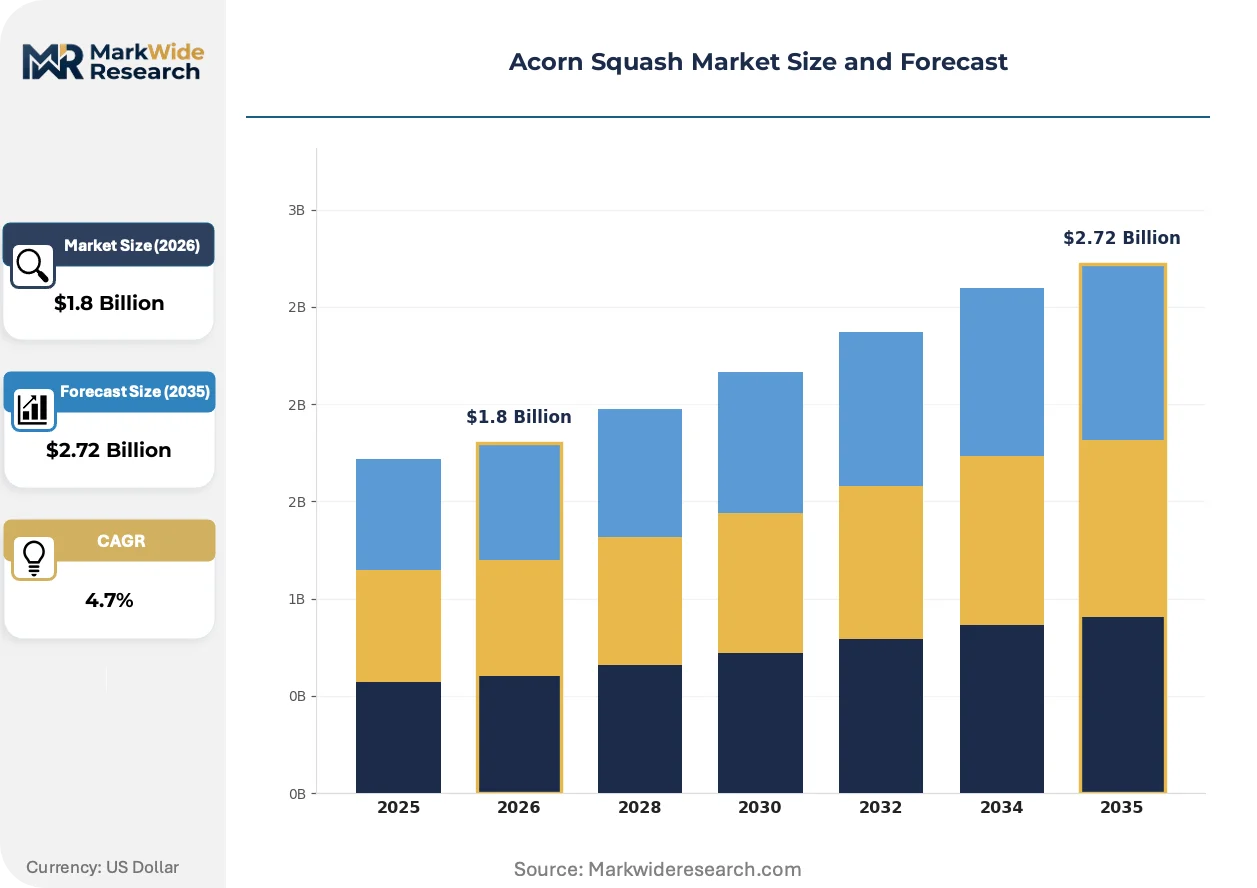
Market Dynamics
USDA organic certification requirements and FDA Food Safety Modernization Act provisions are reshaping grower compliance investments, forcing capital reallocation from acreage expansion to traceability infrastructure and input documentation systems across the supply base.
Growth Catalysts
- California Central Valley production cluster:Concentrated acreage under integrated pest management protocols supplies consistent volume to West Coast processors and national retail chains, reducing per-unit logistics costs through proximity to port infrastructure.
- Farm-to-table restaurant procurement:Specialty food service channels deepen heirloom variety sourcing, creating price premiums for differentiated cultivars that bypass commodity pricing pressure.
- Organic certification standards:USDA organic protocols anchor certified supply chains with strict input controls, enabling three-tier pricing stratification across premium, standard, and economy levels that captures value from health-conscious consumer segments.
Market Restraints
- Input cost volatility:Fertilizer and irrigation energy costs fluctuate with natural gas pricing, compressing margins for open-field growers lacking renewable energy infrastructure or water rights security.
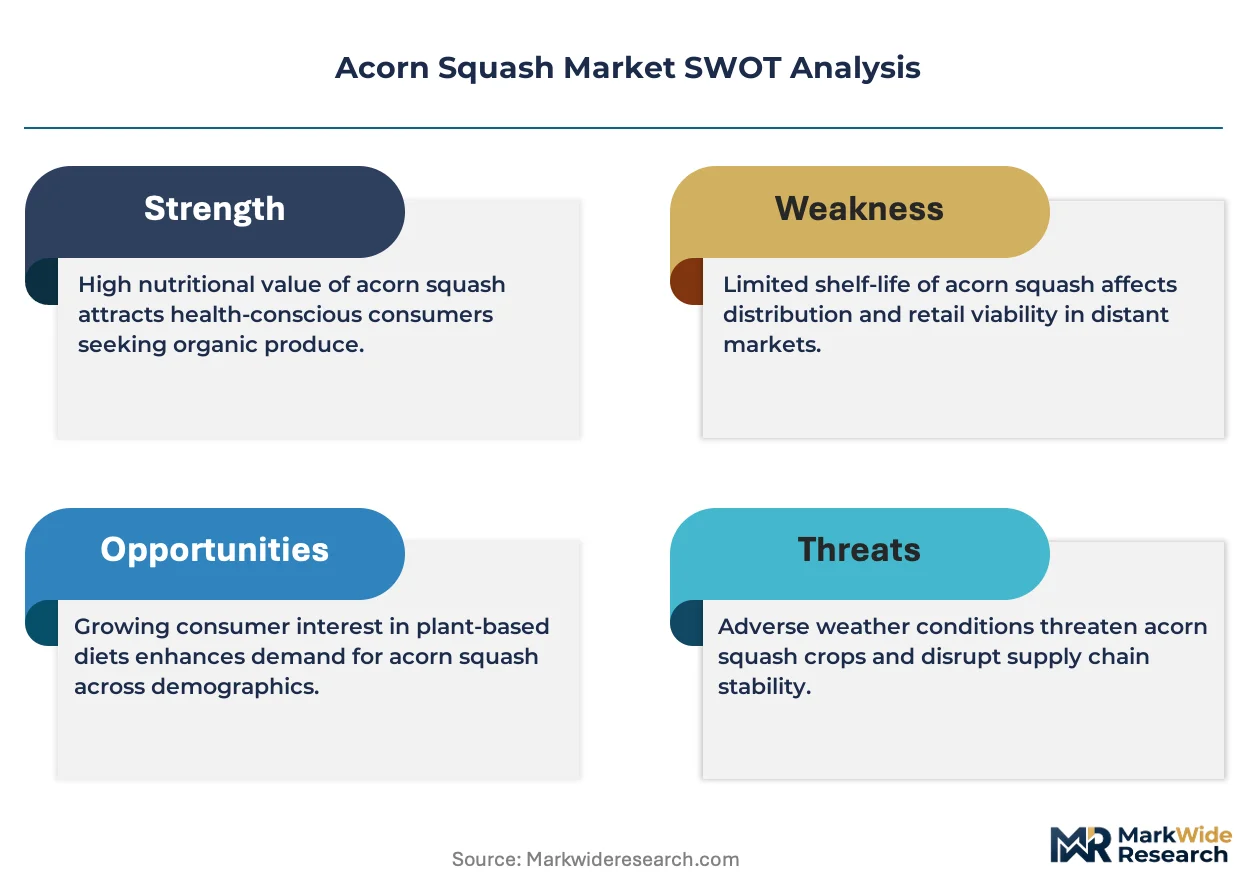
- Geographic supply concentration:California's drought susceptibility and Pacific Northwest frost timing variability create single-region risk exposure that disrupts national availability during adverse weather events.
- Perishability constraints:Hard-rind winter squash storage durability masks post-harvest decay risks in pre-cut retail formats, limiting processor investment in value-added product lines.
Strategic Opportunities
- Controlled environment agriculture:Greenhouse and vertical farming systems enable year-round heirloom production outside California's seasonal constraints, targeting Northeast and Midwest metropolitan markets with local-source claims.
- Direct-to-consumer subscription channels:Community-supported agriculture aggregators and meal-kit platforms bypass intermediary handling costs, capturing farmers' market margin tiers through digital fulfillment infrastructure.
- State-level food safety protocol harmonization:Interstate commerce simplification under unified grading standards reduces compliance duplication costs for multi-state shippers, accelerating market access expansion.
Industry Challenges
- Certification timeline compression:USDA organic transition period requirements and state department of agriculture inspection backlogs delay premium market entry for converting growers, straining working capital during the three-year certification window.
- Heritage variety IP complexity:Open-pollinated seed saving practices conflict with proprietary hybrid development investments, creating licensing friction between independent breeders and commercial seed houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acorn Squash Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Heirloom, Hybrid End Use: Food Service, Retail, Canning, Fresh Market Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Wholesalers Packaging Type: Cartons, Bags, Bulk, Loose |
| Companies Covered | JDM Food Group, Stahlbush Island Farms, Harris Seeds, ALDI, Mackenzie, Stonehill Produce, Tozer Seeds Ltd, Sakata Vegetables, Seminis Vegetable Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acorn Squash Market Evolving Landscape
Processing technology and distribution infrastructure are converging to reshape how acorn squash moves from field to plate, with implications for variety selection, harvest timing, and buyer relationship structures across the value chain.
Precision agriculture sensor networks are expanding into field monitoring for soil moisture, canopy temperature, and pest pressure in real-time. Mid-scale growers in California's Central Valley deploy drone-mounted multispectral imaging to optimize irrigation scheduling and reduce water consumption. This capability is expanding into predictive harvest timing models that align field maturity with processor capacity windows, compressing post-harvest loss rates.
FDA Food Safety Modernization Act traceability mandates require lot-level documentation from seed source through retail shelf. Growers and packers invest in blockchain-enabled record systems to satisfy buyer audit requirements and expedite contamination response protocols. Small-scale direct-market operators face disproportionate compliance burden relative to integrated processors with captive IT infrastructure, accelerating consolidation pressure.
Pre-cut retail formats displace whole-squash volume in conventional grocery channels as convenience-oriented meal preparation dominates urban consumer behavior. Food service chains standardize roasted squash preparations across seasonal menu rotations, creating specification pressure for uniform size grading and consistent sugar content. This shift concentrates in Pacific Northwest metropolitan markets where dual-income households prioritize time-saving ingredients over heritage variety provenance claims.
Acorn Squash Market Segmentation
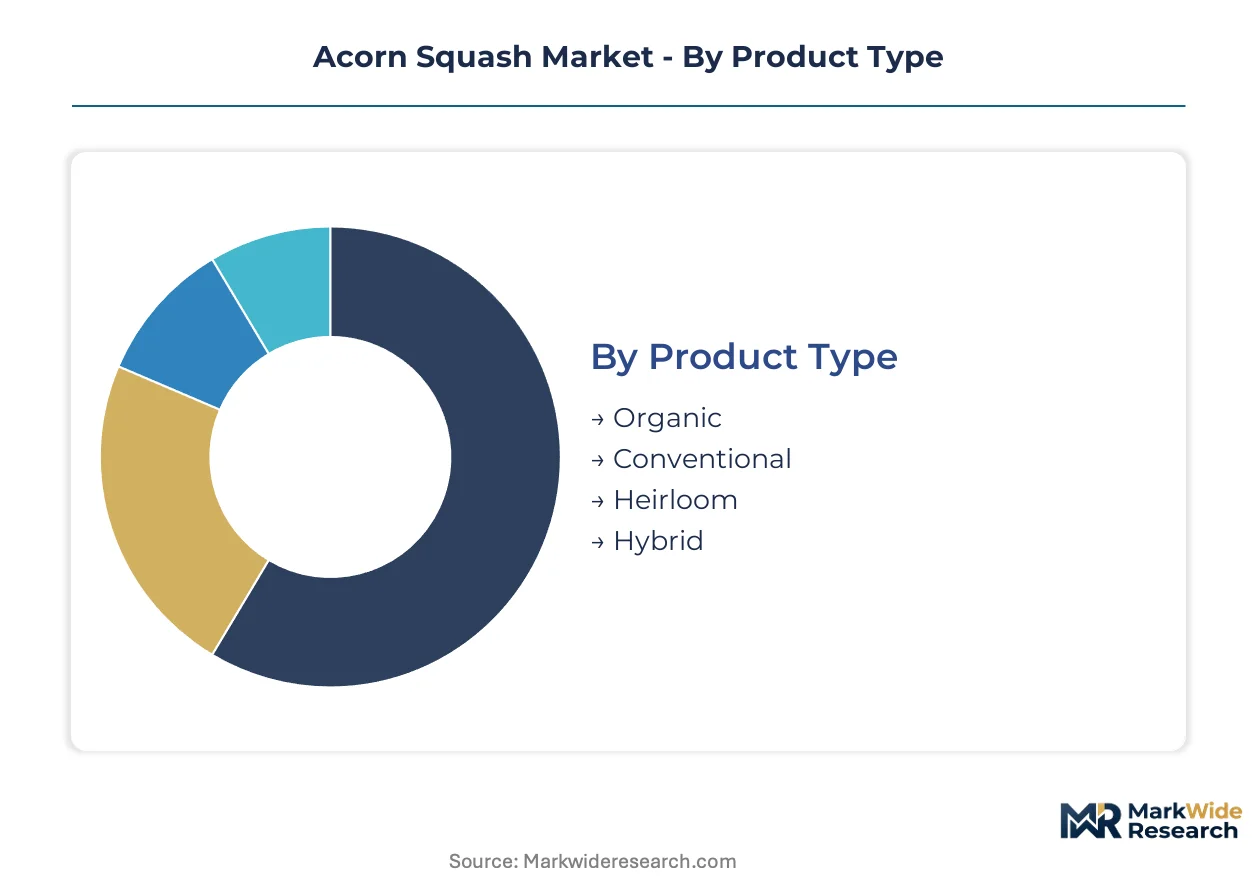
Acorn squash segmentation reflects diverging buyer specifications between convenience-oriented mass retail and provenance-focused premium channels. Cultivation method and distribution pathway determine margin capture more than variety genetics alone.
Product Type:
Customization spans from certified organic protocols with three-year transition requirements to standardized hybrid seed systems optimized for yield uniformity and shipping durability.
- Organic:USDA-certified production with strict input documentation and traceability infrastructure commands premium positioning through health-conscious consumer segments. Demand concentrates in Pacific Northwest direct-market networks and California Central Valley clusters supplying national retail chains, anchored by FDA Food Safety Modernization Act compliance investments that lock in buyer relationships.
- Conventional:Open-field cultivation under integrated pest management protocols supplies volume throughput to food service chains and conventional retail with lower unit costs. California's production cluster dominates supply, though drought susceptibility creates intermittent availability pressure that processors manage through inventory carry strategies.
- Heirloom:Open-pollinated varieties with provenance claims target farm-to-table restaurant procurement and farmers' market premium tiers.
- Hybrid:Proprietary seed development delivers uniform size grading and consistent sugar content for standardized food service specifications.
Leading the category by volume: Conventional. Growing fastest: Organic.
End Use:
Application concentration runs from high-throughput institutional food service to margin-optimized direct-to-consumer channels with divergent specification requirements.
- Food Service:Restaurant chains and institutional buyers standardize roasted squash preparations across seasonal menu rotations, demanding consistent sugar content and uniform size grading. Volume concentrates in Pacific Northwest metropolitan markets where dual-income households drive convenience-oriented dining demand.
- Retail:Pre-cut formats displace whole-squash volume in conventional grocery channels as urban consumers prioritize time-saving ingredients. California Central Valley processors supply frozen and fresh-cut lines to national chains, with perishability constraints limiting value-added investment.
- Canning:Seasonal processing windows align with harvest timing for shelf-stable product lines targeting institutional buyers.
- Fresh Market:Whole-squash sales persist in heritage-focused channels where provenance claims support price premiums.
Dominating volume throughput: Food Service. Expanding most quickly: Retail pre-cut formats.
Distribution Channel:
Channel selection determines margin capture through intermediary elimination versus scale efficiency trade-offs across the value chain.
- Supermarkets:National retail chains source through centralized procurement systems that demand volume consistency and lot-level traceability documentation. California Central Valley integrated processors supply private-label and branded lines, with blockchain-enabled record systems satisfying audit requirements.
- Online Retailers:Digital fulfillment infrastructure enables subscription-based community-supported agriculture models and meal-kit platforms to capture farmers' market margin tiers. Northeast and Midwest metropolitan markets show strongest adoption for direct-to-door heirloom delivery.
- Farmers' Markets:Direct producer-consumer contact eliminates intermediary handling costs, anchoring the highest margin tier for certified organic and heirloom varieties.
- Wholesalers:Consolidated distribution serves independent grocers and regional food service operators with mixed variety lots.
Capturing highest volume: Supermarkets. Gaining share fastest: Online Retailers.
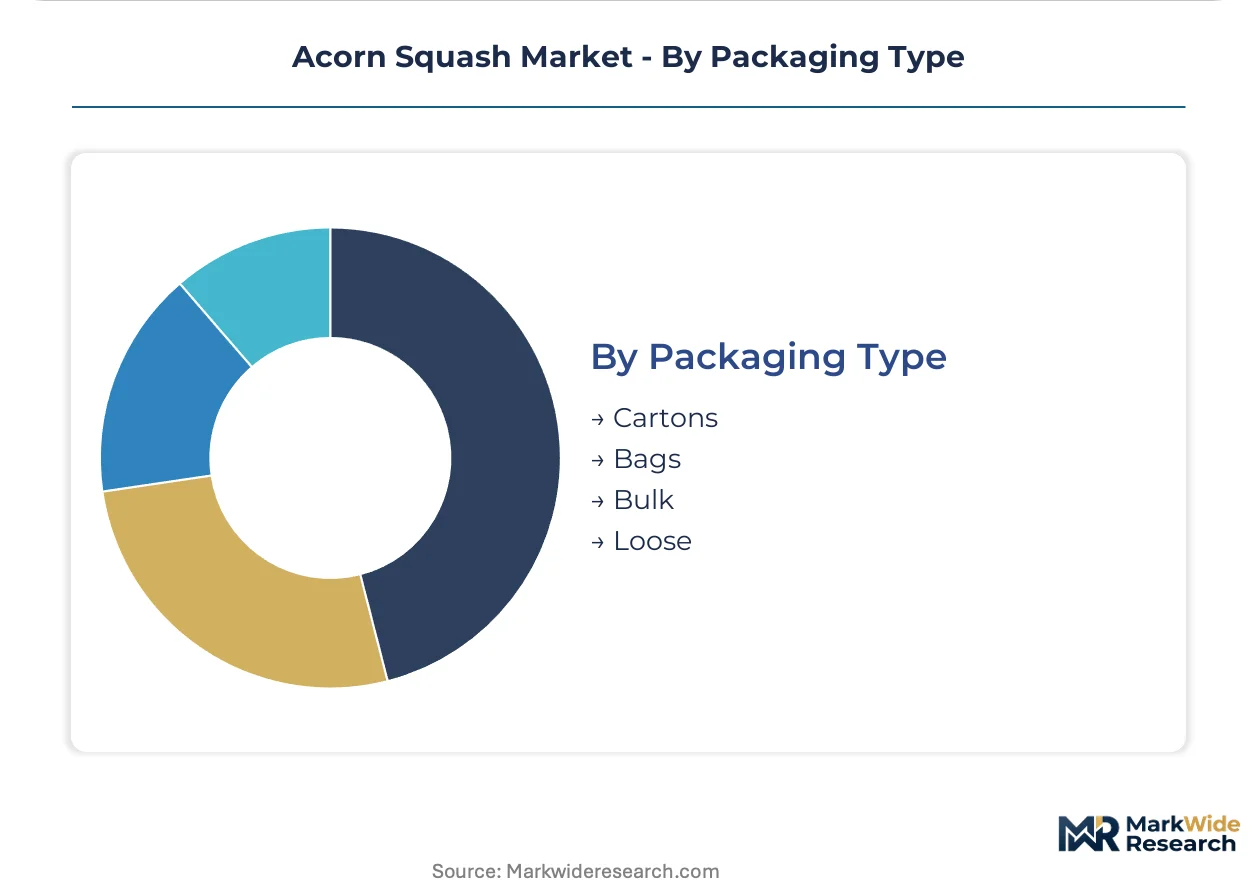
Packaging Type:
Packaging configuration aligns with channel requirements from bulk institutional shipment to consumer-facing portion control.
- Cartons:Corrugated containers protect whole squash during long-haul shipment from California Central Valley to national distribution centers, with stack-optimized dimensions reducing per-unit logistics costs.
- Bags:Modified atmosphere packaging extends shelf life for pre-cut retail formats in convenience-oriented urban markets.
- Bulk:Bin shipments serve processors and canning operations with minimal handling overhead.
- Loose:Unpackaged display dominates farmers' markets and select fresh market channels where visual inspection drives purchase decisions.
Leading volume: Cartons. Steepest expansion trajectory: Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley production cluster anchors North American acorn squash supply, with Fresno County and Kern County growers shipping volume through West Coast port infrastructure to national retail chains and food service distributors.
United States
Pacific Northwest direct-market networks in Oregon and Washington deepen heirloom variety procurement for farm-to-table restaurants. USDA organic certification requirements reshape grower compliance investments across the three-year transition window. California Central Valley integrated processors supply frozen and fresh-cut lines to national supermarket chains.
Canada
Ontario greenhouse operators deploy controlled environment agriculture for year-round heirloom production targeting Toronto and Montreal metropolitan markets. Health Canada and the Canadian Food Inspection Agency administer the Safe Food for Canadians Regulations governing interstate shipment documentation. British Columbia's Fraser Valley clusters supply organic-certified volume to Vancouver's restaurant and retail channels.
Mexico
Baja California and Sinaloa open-field growers supply conventional hybrid squash to US food service chains during California's off-season windows. Mexico's national agricultural regulator SENASICA enforces phytosanitary protocols for cross-border shipment eligibility. Guanajuato's Bajío Region processors invest in pre-cut retail format capacity for US supermarket private-label programs.
United Kingdom
East Anglia glasshouse producers target London's premium restaurant and meal-kit subscription channels with heritage variety claims. Food Standards Agency hygiene regulations and DEFRA agricultural standards shape grower audit requirements. Kent's direct-market networks capture farmers' market margin tiers through producer-consumer contact elimination.
Netherlands
Westland greenhouse clusters export pre-cut acorn squash formats to German and Belgian retail chains under EU organic certification protocols. The Netherlands Food and Consumer Product Safety Authority enforces EU Food Safety Modernization Act-aligned traceability mandates. Wageningen University research partnerships accelerate precision agriculture sensor deployment for irrigation optimization.
Acorn Squash Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and distribution pathway dimensions, with organic-certified and direct-market operators capturing price tiers that bypass conventional grocery pricing pressure. The vendor base arranges into three strategic archetypes: vertically integrated processors controlling captive supply, proprietary seed developers licensing hybrid genetics, and direct-market aggregators eliminating intermediary handling costs. Dominant competitive moves include backward integration into seed development and upstream control over processing infrastructure.
Within the integrated processor tier, Stahlbush Island Farms exemplifies captive supply chain architecture, while Sakata Vegetables occupies a position representing proprietary hybrid seed development specialization. Harris Seeds sits within the distribution-focused archetype targeting home gardeners and small-scale commercial growers through extensive catalog networks. These three anchors illustrate how competitive positioning stratifies across upstream genetic control, midstream processing scale, and downstream channel reach.
| Leading Market Players |
|---|
| JDM Food Group |
| Stahlbush Island Farms |
| Harris Seeds |
| ALDI |
| Mackenzie |
| Stonehill Produce |
| Tozer Seeds Ltd |
| Sakata Vegetables |
| Seminis Vegetable Seeds |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap growers across California's Central Valley and Pacific Northwest direct-market networks anchor supply discipline through patient capital allocation, enabling multi-year organic certification investments that commodity-oriented operators cannot replicate. Their ownership structure sustains pricing power during input cost volatility while limiting acreage expansion in favor of traceability infrastructure.
Pricing Analysis
Value-based pricing anchored to USDA organic certification tiers separates premium certified supply from conventional hybrid production. Price differentiation rests on certification grade and volume scale, with organic heirloom varieties commanding the highest tier and commodity hybrids facing the sharpest compression. Cost compression in conventional tiers is intensifying because fertilizer and irrigation energy costs fluctuate with natural gas pricing. Food service chains demonstrate the lowest price sensitivity due to standardized menu specifications, while conventional retail channels exhibit the highest sensitivity to per-unit cost fluctuations.
Supply Chain Analysis
Seasonal labor availability in California's Central Valley, Mexico's Sinaloa corridor, and Ontario's greenhouse belt constrains harvest timing flexibility and processing capacity utilization. Raw material dependencies center on proprietary hybrid seed stock, organic compost inputs, and modified atmosphere packaging films. Single-source vulnerability concentrates in California's drought-exposed production cluster, where water rights insecurity disrupts national availability. Distribution runs through vertically integrated processors supplying frozen and fresh-cut lines to supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: the three-year USDA organic certification window creates a structural capacity bottleneck that props premium-tier pricing regardless of near-term demand fluctuations.
For Market Incumbents: Anticipate consolidation pressure from integrated processors with captive IT infrastructure by securing backward integration into seed development and upstream control over cold storage capacity. Defensive positioning requires locking in multi-year supply agreements with farm-to-table restaurant chains before traceability mandate compliance costs escalate further. For New Entrants and Emerging Players: The price-point gap between Pacific Northwest heirloom premiums and Mexico-sourced conventional hybrids offers white-space entry through controlled environment agriculture in Northeast metropolitan markets. Target community-supported agriculture subscription channels with digital fulfillment infrastructure to capture farmers' market margin tiers without brick-and-market presence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale organic converters in California's drought-stressed Kern County facing working capital strain during certification transition. Long-term viability hinges on water rights security and renewable energy infrastructure deployment. Monitor FDA Food Safety Modernization Act enforcement intensity as the inflection signal for compliance cost acceleration and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Development | Sakata Vegetables' proprietary hybrid genetics lock in specification control for food service standardization. |
| Controlled Environment Agriculture Expansion | Ontario greenhouse operators bypass California seasonal constraints to supply Toronto's meal-kit channels. |
| Blockchain-Enabled Traceability Deployment | Stahlbush Island Farms satisfies FDA audit requirements while expediting contamination response protocols. |
| Direct-to-Consumer Subscription Launch | Pacific Northwest aggregators eliminate intermediary handling costs through digital CSA fulfillment. |
| Organic Certification Fast-Track Investment | California growers compress three-year transition timelines through accelerated input documentation systems. |
Research Methodology
Independent corroboration across grower cooperative managers, produce procurement directors at national retail chains, food service specification writers, and seed house technical sales representatives underwrites the qualitative findings. Primary fieldwork combined with secondary validation from USDA organic certification databases, FDA Food Safety Modernization Act guidance documents, state department of agriculture inspection records, and customs trade data establishes baseline supply estimates. Bottom-up acreage and yield modeling triangulates against top-down channel volume assessments.
Comparable-period anchoring to historical production cycles across California's Central Valley, Pacific Northwest, and Mexican import windows structures the projection horizon. Segmentation dimensions span cultivation method, end-use application, distribution pathway, and packaging configuration. CAGRs derive from trend-line extrapolation moderated by input cost elasticity and regulatory compliance trajectory. Forecast inputs incorporate irrigation water availability indices and organic certification conversion rates.
Inputs from grower cooperative financial disclosures and seed house sales data were available through the study window; gaps in real-time inventory positioning at food service distributors introduce uncertainty bands around quarterly volume estimates. Forecasts reflect documented assumptions regarding drought recurrence frequency and labor availability in harvest windows. Material deviation in California water allocation adjudication or FDA traceability enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
North America Microgreens Market
Vegetables
Fresh Vegetables Market
Vegetables
Spain Avocado Market
Vegetables
UAE Tomato Market
Vegetables
Roselle Market
Vegetables
Yams Market
Vegetables
Fresh Mushroom Market
Vegetables
Garden Cress Market
Vegetables
Sprouts Market
Vegetables
Vegetable Grader Market
Vegetables
South America Peas Market
Vegetables
Butternut Squash Market
Vegetables
Microgreens Market
Vegetables
Dehydrated Vegetables Market
Vegetables
Squash Market
Vegetables
Asparagus Market