
 Squash Market | 2026-2036
Squash Market Size, Share, and Industry Trends Forecast 2026-2036
Squash Market Intelligence
A divergence in capital intensity between large-scale agribusinesses and smaller specialty farms is redrawing the competitive landscape. Large commercial growers leverage economies of scale in cultivation and logistics to supply major supermarket chains. In contrast, specialty organic producers focus on high-margin niche varieties sold through direct-to-consumer channels and organic stores. This creates a bifurcated market with distinct supply chain and pricing models.
Squash refers to several species of herbaceous vine plants in the genus Cucurbita, cultivated for their edible fruit. The fruit's high water content and rich concentration of vitamins A and C determine its primary use in culinary applications. Winter squash varieties, including butternut and acorn, dominate the food processing end-use segment due to their longer shelf life and dense flesh. Supermarkets remain the primary distribution channel, although online retailers are expanding their share with pre-packaged and organic offerings.
Food safety and pesticide residue regulations from bodies like the US Department of Agriculture (USDA) and the European Food Safety Authority (EFSA) govern market access for producers. In India, the Food Safety and Standards Authority of India (FSSAI) sets parallel standards for labeling and quality. Navigating these varied international phytosanitary requirements and quality standards is critical for producers seeking to access high-value export markets.
Market Dynamics
Production is concentrating in agricultural regions like Mexico and Spain, which are optimized for year-round cultivation. This geographic consolidation allows for a consistent supply to meet demand from major consumer markets in North America and Europe.
Growth Catalysts
- Food Processing Demand:The food processing industry's increasing use of squash purees, powders, and concentrates in soups, baby food, and baked goods drives volume growth for specific varieties like butternut.
- Organic Certification:Consumer demand for certified organic produce, verified by standards such as the USDA Organic seal, creates a high-margin segment for specialty growers able to meet stringent cultivation requirements.
- Supply Chain Efficiency:Advanced logistics and cold chain management enable year-round availability of fresh squash, connecting distant production zones in Spain and Mexico with end-markets across the globe.
Market Restraints
- Perishability and Spoilage:The high water content of squash makes it susceptible to damage and decay during transport and storage, leading to product loss and increased costs within the supply chain.
- Phytosanitary Regulations:Navigating the complex and divergent pesticide residue limits and import standards set by the EFSA in Europe and the USDA in the United States creates significant compliance hurdles for exporters.
- Variety Substitution:High substitutability among different winter squash varieties, such as acorn and butternut, limits producers' pricing power and brand differentiation for non-specialty types.
Strategic Opportunities
- Value-Added Products:Developing shelf-stable, value-added products like squash flour for the gluten-free market or ready-to-eat frozen squash meals opens new consumer and food service segments.
- Emerging Market Entry:Targeting markets in the Middle East and Southeast Asia, where rising incomes and dietary diversification are creating new demand for imported fresh vegetables.
- Precision Agriculture:Implementing drip irrigation and sensor technologies can optimize water usage and nutrient delivery, improving yields and sustainability, particularly in arid growing regions.
Industry Challenges
- Cold Chain Management:Maintaining an unbroken cold chain from harvest to retail is a critical operational challenge, especially for long-haul shipments from primary growing regions to international consumer markets.
- Organic Certification Costs:The financial investment and administrative burden associated with obtaining and maintaining organic certifications can be prohibitive for smaller, independent farms.
- Labor Availability:Seasonal labor shortages in key agricultural zones of Mexico and Spain pose a risk to harvesting capacity, potentially leading to crop losses and supply disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squash Market |
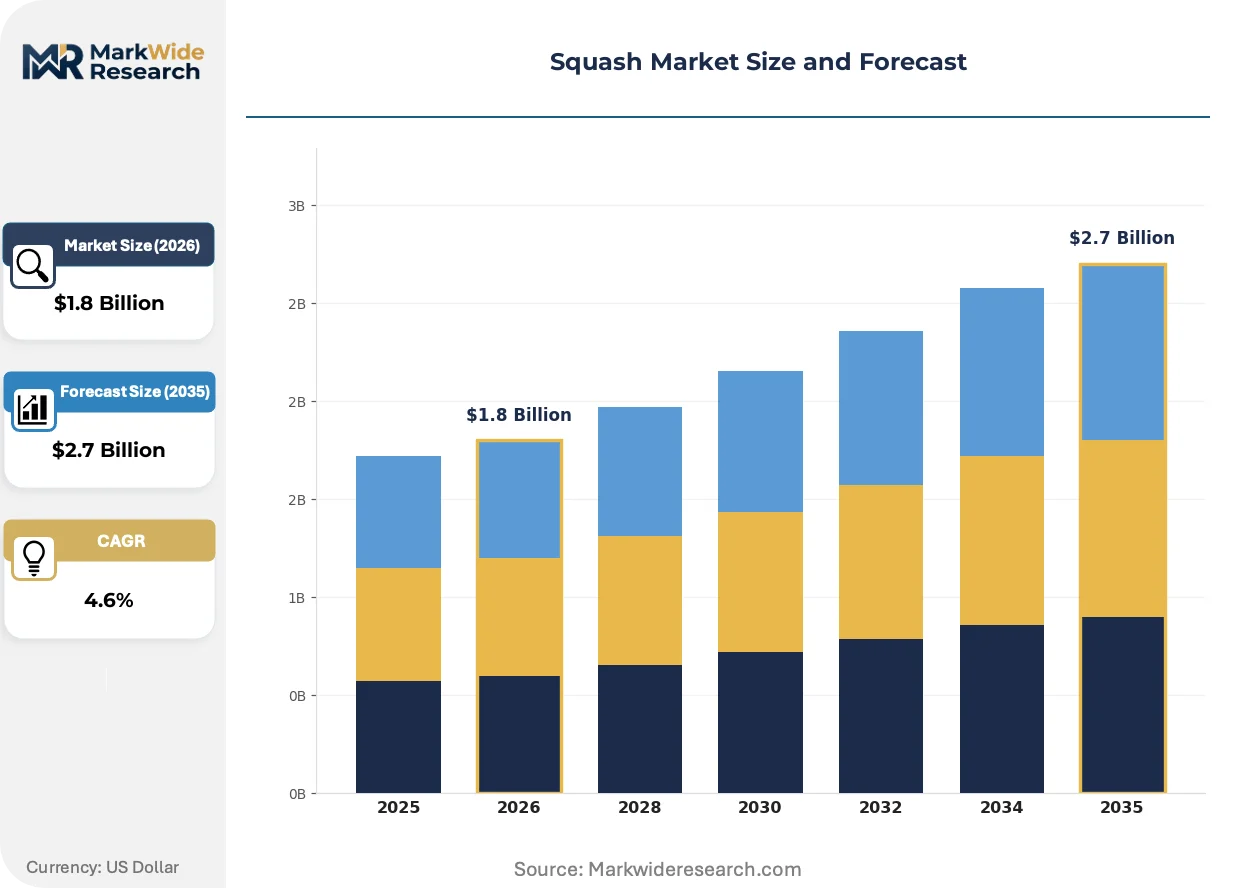
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winter Squash, Summer Squash, Acorn Squash, Butternut Squash End Use: Culinary, Food Processing, Juice Production, Dietary Supplements Distribution Channel: Supermarkets, Organic Stores, Online Retailers, Farm Stands Packaging Type: Boxes, Baskets, Shrink Wrap, Bulk Containers |
| Companies Covered | HEAD Sport, Dunlop Sports, Prince Tennis, Ektelon, Harrow Sports, Black Knight, Tecnifibre, Asics Corporation, Wilson Sporting Goods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squash Market Strategic Shifts & Innovations
Agricultural biotechnology and evolving consumer health standards are converging to redefine product development and cultivation. This dynamic creates pathways for differentiation beyond price, focusing on intrinsic product qualities and production transparency.
Advanced gene-editing techniques like CRISPR are being used to develop squash varieties with enhanced disease resistance and longer shelf life. Large agricultural firms and research institutions are leading the adoption of these tools. This technology is displacing traditional breeding methods by enabling faster development of cultivars with specific, desirable traits like higher vitamin content.
Regulatory mandates, particularly the European Union's Farm to Fork Strategy, are establishing ambitious targets for reducing pesticide use and expanding organic agriculture. This policy directly impacts cultivation practices for all producers supplying the EU market. Growers are now compelled to adopt integrated pest management and seek certification to maintain market access, particularly affecting large-scale exporters from outside the bloc.
A notable behavioral shift is the rise of direct-to-consumer (DTC) sales channels, including community-supported agriculture (CSA) boxes and online farm stores. These models disrupt the traditional dominance of large supermarkets for fresh produce distribution. This trend is most pronounced in North American and European metropolitan areas, where consumers prioritize food provenance and direct relationships with producers.
Squash Market Segmentation
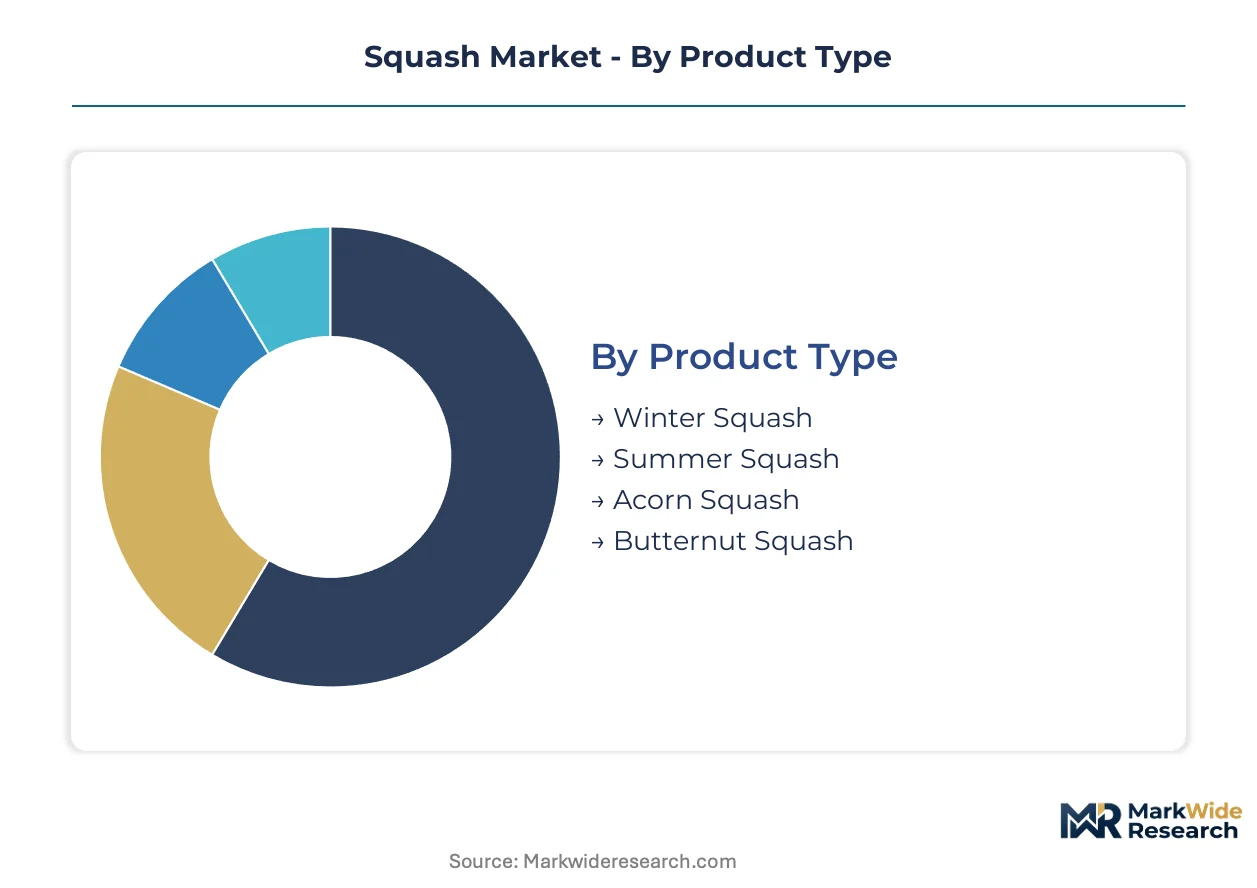
Understanding the varied segments within the squash market provides clarity on specific demand drivers and supply chain configurations. This granular view allows producers and distributors to tailor cultivation strategies and market approaches, addressing distinct consumer preferences and industrial requirements. Analyzing these segments helps identify areas of concentrated value and emerging growth pockets across the supply chain.
Product Type:
The geographic spread of cultivation influences the prevalence of certain squash product types, with regional climates often favoring either winter or summer varieties for commercial scale. Year-round supply from regions like Mexico and Spain supports consistent availability across categories.
- Winter Squash:These varieties, including butternut and acorn, possess dense flesh and a longer shelf life, making them ideal for long-distance transport and industrial processing applications. Demand for winter squash concentrates within the food processing sector, especially for purees and concentrates used in soups and baby food.
- Butternut Squash:Characterized by its sweet, nutty flavor and smooth texture, butternut squash is highly valued for its versatility in culinary and food processing contexts. Consumer demand for this specific variety is robust in North American and European markets, driven by its nutritional profile and suitability for diverse recipes.
- Summer Squash:Varieties like zucchini and yellow squash have a higher water content and shorter shelf life, primarily catering to fresh consumption markets.
- Acorn Squash:This smaller, dark-green winter squash offers a distinct flavor and is often marketed for direct culinary use in household consumption.
Winter Squash commands the established base. The steepest expansion runs through Butternut Squash.
End Use:
The application of squash varies significantly, with industrial uses often dictating large-volume procurement, while specialized dietary applications command premium pricing. Different end uses require specific processing and quality standards.
- Food Processing:This segment utilizes squash, particularly winter varieties, for producing purees, powders, and concentrates for baby food, soups, and baked goods. The food processing industry drives significant volume demand, especially for varieties optimized for industrial yields and consistent quality.
- Culinary:Fresh squash is sold directly to consumers and restaurants for home cooking and foodservice applications. This end use prioritizes appearance, freshness, and variety, with supermarkets serving as the primary distribution channel.
- Juice Production:Squash is processed into juices and juice blends, often combined with other fruits or vegetables for nutritional beverages. This segment requires varieties with high liquid yield and a desirable flavor profile.
- Dietary Supplements:Extracts and powders from squash are incorporated into dietary supplements, valued for their vitamin and antioxidant content. This niche segment demands high-quality, often organically certified, raw materials.
Food Processing represents the largest consumption volume. Dietary Supplements are gaining share fastest.
Distribution Channel:
The channels through which squash reaches consumers are diverse, ranging from traditional retail to emerging direct-to-consumer models, each serving different customer types and market segments. Supply chain efficiency and cold chain management are critical for all channels.
- Supermarkets:Large retail chains serve as the dominant distribution channel, offering a wide array of fresh and sometimes pre-packaged squash varieties to a broad consumer base. Supermarkets prioritize consistent supply, competitive pricing, and adherence to food safety standards like those from the USDA and EFSA.
- Online Retailers:E-commerce platforms and grocery delivery services provide convenience for consumers, expanding access to fresh and organic squash offerings. This channel often features pre-packaged and specialty organic products, capitalizing on consumer demand for home delivery.
- Organic Stores:Specialty retailers focus on certified organic produce, catering to consumers who prioritize sustainable and pesticide-free cultivation practices. Organic stores typically offer niche varieties and emphasize product provenance, aligning with USDA Organic standards.
- Farm Stands:Local farm stands and farmers' markets connect producers directly with consumers, often featuring seasonal and heirloom squash varieties. This channel emphasizes freshness and local sourcing, bypassing larger distribution networks.
Supermarkets maintain the foundational distribution. Online Retailers exhibit rapid expansion.
Packaging Type:
The choice of packaging type directly impacts product preservation, logistics efficiency, and market presentation, catering to different stages of the supply chain and end-user requirements. Packaging innovations aim to reduce perishability and extend shelf life.
- Bulk Containers:Large crates, bins, or sacks are used for high-volume transport of squash from farms to processing plants or distribution centers. This packaging minimizes individual handling and optimizes space utilization during long-haul shipments from Mexico and Spain.
- Shrink Wrap:Individual or small clusters of squash are often shrink-wrapped to protect them from physical damage and extend their freshness by reducing moisture loss. This method is common for retail display in supermarkets, improving product longevity.
- Boxes:Cardboard or plastic boxes provide protection and ease of stacking for smaller quantities of squash, particularly for specialty varieties or direct-to-consumer shipments. Boxes are frequently used for organized storage and transport to organic stores.
- Baskets:Traditional baskets are sometimes employed for local farm-to-market sales, offering a rustic aesthetic and breathability for short-term transport. This packaging type is less common for international trade due to durability concerns.
Bulk Containers form the primary logistics backbone. Shrink Wrap shows significant growth in retail presentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global squash market exhibits a complex export-import dynamic, with agricultural powerhouses like Mexico and Spain supplying major consumer markets in North America and Europe. This geographic specialization ensures consistent year-round availability for fresh consumption and industrial processing. Regional demand patterns are influenced by local culinary traditions, dietary trends, and regulatory frameworks governing food safety and organic certification.
United States
Consumer demand for diverse squash varieties, particularly organic and pre-cut options, drives significant market activity in the United States. The USDA Organic seal provides a crucial certification standard, influencing purchasing decisions for a premium segment. California's vast agricultural regions, especially the Central Valley, concentrate specialty organic squash production to meet these discerning consumer preferences.
Germany
German consumers show strong demand for fresh and processed squash, with a notable preference for organic and sustainably sourced produce. The European Food Safety Authority (EFSA) sets stringent pesticide residue limits, directly impacting import strategies for producers. Major import hubs like Hamburg facilitate the distribution of imported squash across Germany and other European Union member states.
Mexico
Mexico's optimized agricultural conditions position it as a primary year-round supplier of squash to the North American market. Phytosanitary requirements from the US Department of Agriculture (USDA) dictate export protocols, ensuring product safety and quality. Agricultural zones in Sinaloa and Sonora are central to large-scale squash cultivation, leveraging favorable climates for consistent yields.
Spain
Spain's advanced agricultural sector, particularly in Andalusia, serves as a significant source of winter squash for European markets. The EU's Farm to Fork Strategy encourages sustainable cultivation practices, influencing growers' adoption of integrated pest management. Intensive greenhouse farming in regions like Almería ensures consistent supply, despite varying seasonal conditions across the continent.
India
India's squash market is expanding due to dietary diversification and increasing integration into culinary and food processing applications. The Food Safety and Standards Authority of India (FSSAI) establishes national standards for labeling and quality, guiding domestic production and imports. States like Maharashtra and Uttar Pradesh are developing localized supply chains to support growing urban demand for fresh and processed vegetables.
Squash Market Key Industry Players
Concentration sits with large commercial growers who leverage economies of scale in cultivation and logistics, primarily supplying major supermarket chains. The market structure is bifurcated, with specialty organic producers carving out high-margin niches through direct-to-consumer channels. Key archetypes include large-scale agribusinesses, specialty organic farms, and food processing integrators. Competitive moves focus on optimizing supply chain efficiency and developing value-added products.
Within the broader market for squash-related products, companies like HEAD Sport, Dunlop Sports, and Wilson Sporting Goods represent established brands. These entities occupy positions as premium brand manufacturers, offering a range of products associated with the squash industry. Their market presence often extends across global distribution networks, anchoring various segments of the market for squash-related equipment and accessories. These companies exemplify a focus on product innovation and brand recognition within their respective segments.
| Leading Market Players |
|---|
| HEAD Sport |
| Dunlop Sports |
| Prince Tennis |
| Ektelon |
| Harrow Sports |
| Black Knight |
| Tecnifibre |
| Asics Corporation |
| Wilson Sporting Goods |
| Others |
Cost & Logistics Intelligence
Average days of inventory for fresh squash, often less than two weeks, directly influences pricing power for perishable varieties and impacts supply chain velocity.
Pricing Analysis
Price differentiation between bulk commodity squash and specialty organic varieties creates a significant premium spread. Per-unit transactional pricing dominates for fresh market sales, while long-term contracts secure volumes for food processors. Certification levels, such as the USDA Organic seal, and geographic delivery costs drive price differentiation. Pricing softness runs through non-specialty types due to high variety substitution, making food processing buyers highly price-sensitive compared to organic store consumers.
Supply Chain Analysis
Just-in-time inventory management is critical for fresh squash, minimizing spoilage risks inherent in its high water content. Geographic supply concentrates in Mexico and Spain, leveraging optimized agricultural conditions for year-round production. The industry relies on quality Cucurbita seeds, consistent water access, and specialized packaging materials. Phytosanitary regulations from EFSA and USDA present a structural risk for exporters, while distribution runs through major supermarket chains and large-scale food processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A fragmentation opportunity exists in the squash market, driven by consumer demand for certified organic varieties.
For Market Incumbents: Fortify supply chain resilience through diversified sourcing agreements beyond Mexico and Spain to mitigate geopolitical or climate-related disruptions. Invest in precision agriculture technologies to optimize yields and reduce input costs, countering margin pressure from commodity price volatility. Enhance cold chain management capabilities to extend shelf life and reduce spoilage during long-haul transport. Pursue backward integration into proprietary seed development to control genetic traits like disease resistance.
For New Entrants and Emerging Players: Lead with specialized, high-margin niche varieties, such as heirloom or unique winter squash types, targeting direct-to-consumer channels. Focus on emerging metropolitan areas in Southeast Asia where dietary diversification is creating demand for imported fresh vegetables. Develop value-added products like squash flour for the gluten-free market, offering a distinct go-to-market angle. Emphasize transparent sourcing and organic certifications to appeal to discerning consumers.
For Investors and Strategic Acquirers: Carve-out targets emerge from large agribusinesses seeking to divest non-core specialty organic operations. The long-term viability of the squash market remains strong, supported by sustained demand for healthy food options. Identify mid-sized food processing integrators with established distribution networks for value-added squash products. A signal to watch is the increasing investment in advanced gene-editing techniques for disease-resistant cultivars.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Precision Agriculture | Optimizes water usage and nutrient delivery, improving yields for growers in arid regions. |
| Develop Value-Added Products | Creates new revenue streams in segments like gluten-free flours or ready-to-eat meals. |
| Expand Organic Certification | Secures access to premium consumer segments in North American and European markets. |
| Diversify Sourcing Geographies | Reduces reliance on single-origin supply, mitigating risks from climate events or labor shortages. |
| Enhance Cold Chain Logistics | Extends product shelf life and reduces spoilage during international transport to consumer markets. |
Research Approach
A spread of perspectives from commercial growers, food processors, retail buyers, and organic certifiers converged on the working assumptions for this analysis. Primary interviews with industry stakeholders provided qualitative insights, validated through extensive secondary research. This included reviewing USDA reports, EFSA publications, FSSAI standards, and global trade statistics. A bottom-up and top-down triangulation approach ensured comprehensive data validation.
The segmentation dimensions modeled included product type, end use, distribution channel, packaging type, and regional demand patterns across the analysis window. Quantitative forecasts were derived using a multi-variate regression model, informed by historical market trends and projected economic indicators. Compound Annual Growth Rates (CAGRs) reflect anticipated shifts in consumer preferences. Key forecast inputs included agricultural yield data and consumer spending on organic produce.
The analysis sits within stated boundaries; outcomes outside significant climate change impacts or new trade barriers would require recalibration. Forecasts reflect assumptions regarding stable regulatory environments and consistent agricultural labor availability. Revision becomes warranted when major phytosanitary policy changes or significant pest outbreaks cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Global Mushroom Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Dried Vegetable Market
Vegetables
Dried Mushroom Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Dry Onion Market
Vegetables
Spain Avocado Market
Vegetables
Vegetable Grader Market
Vegetables
Artichokes Market
Vegetables
Garlic Market
Vegetables
Qatar Greenhouse Market
Vegetables
Canada Microgreens Market
Vegetables
UAE Tomato Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Greenhouse Produce Market
Vegetables
Garden Cress Market