
 Australia Compound Feed Market | 2026-2036
Australia Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Compound Feed Market Outlook
Commercial farms is rotating toward precision-formulated compound feed as backyard producers retreat from bulk purchasing. Ridley Corporation Limited anchors grain-based manufacturing across southeastern Australia. Cargill Inc. leverages its port terminal network to secure imported protein ingredient flows. Alltech Inc. differentiates through yeast-based additive portfolios that target rumen efficiency.
Compound feed refers to nutritionally complete mixtures of cereals, oilseed meals, vitamins, and minerals processed through steam pelleting or extrusion to deliver standardized metabolizable energy and crude protein levels for livestock production. Poultry feed dominates volume due to vertical integration among broiler processors, while aquaculture feed records the fastest expansion as salmon and prawn farms scale ocean-based operations. Pellet form commands premium positioning because mechanical durability reduces feed waste in automated delivery systems, whereas mash retains cost-sensitive ruminant segments.
The Australian Pesticides and Veterinary Medicines Authority enforces maximum residue limits that dictate additive inclusion rates, while Food Standards Australia New Zealand governs label claims for nutritional guarantees. Biosecurity regulations administered by the Department of Agriculture, Fisheries and Forestry restrict certain imported ingredients, redirecting sourcing toward domestic canola and lupin processors. Stakeholders must monitor feedstock price volatility and regulatory tightening on antibiotic growth promoters to calibrate procurement and formulation strategies.
Market Dynamics
Feedlot operators in Queensland and New South Wales are intensifying metabolizable energy precision programs as grain price volatility forces rapid reformulation cycles. This pressure cascades through ingredient sourcing networks and additive procurement decisions.
Growth Catalysts
- APVMA residue limit enforcement:The Australian Pesticides and Veterinary Medicines Authority tightens maximum residue thresholds, compelling feed mills to invest in certified premix capabilities that lock in premium pricing.
- Dairy herd expansion:Victorian and Tasmanian dairy operations scale total mixed ration adoption, driving demand for steam-pelleted concentrates with standardized crude protein profiles.
- Precision fermentation:Novel single-cell protein ingredients from domestic bioreactors reduce reliance on imported soybean meal, shortening supply chains for aquaculture feed producers.
Market Restraints
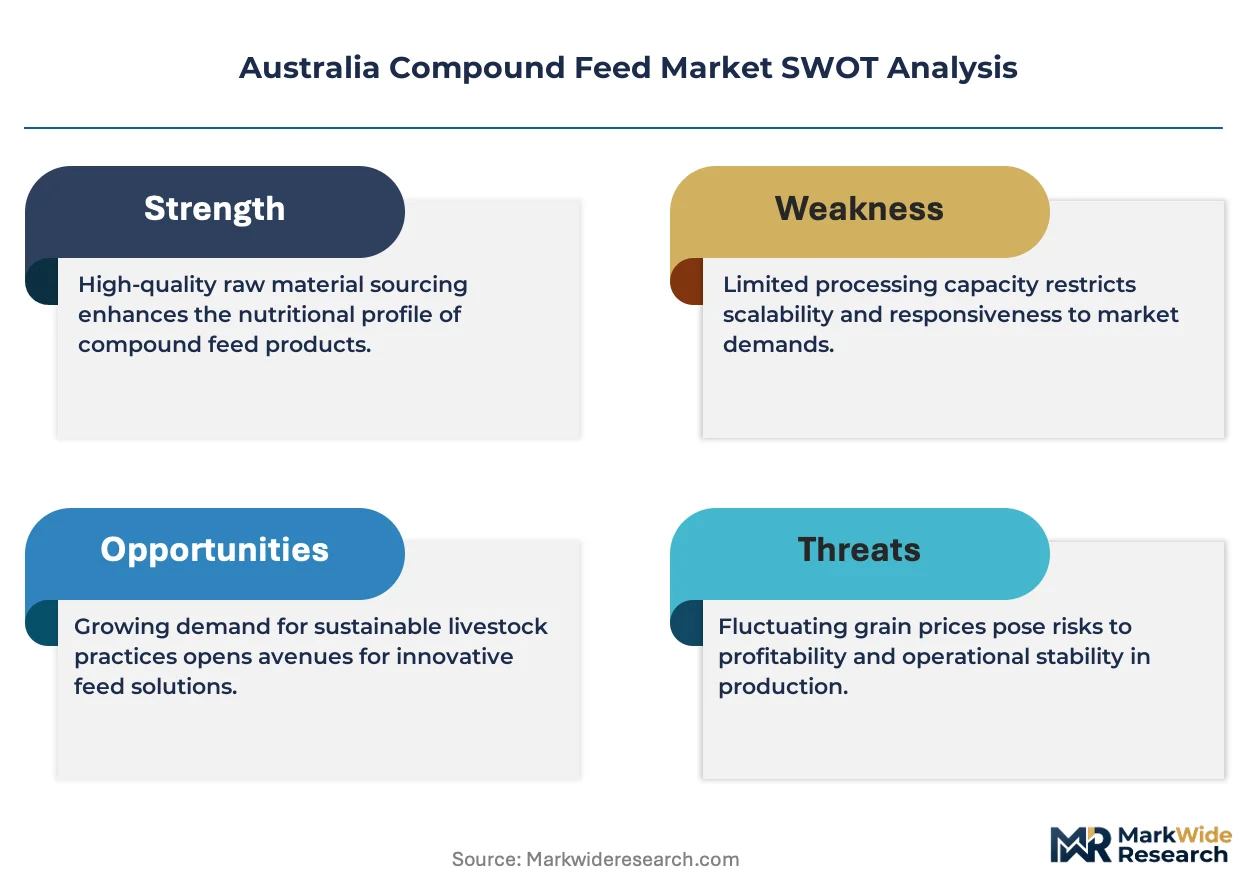
- Wheat and barley price volatility:Eastern Australian grain belts face climate-driven yield uncertainty, compressing margin buffers for ruminant feed compounders locked into long-term supply contracts.
- Port terminal concentration:Bulk protein meal imports funnel through limited southeastern deepwater facilities, creating bottleneck exposure during vessel scheduling disruptions.
- Antibiotic growth promoter phase-out:APVMA restrictions on sub-therapeutic usage force reformulation investments without immediate compensatory price recovery mechanisms.
Strategic Opportunities
- Tasmanian salmon aquaculture:Ocean-based pen expansion creates demand for high-fat extruded feeds with specialized amino acid matrices currently under-supplied by domestic manufacturers.
- Biosecurity-aligned domestic sourcing:Department of Agriculture, Fisheries and Forestry import restrictions on certain rendered proteins redirect procurement toward Australian canola and lupin processors.
- Automated feed delivery integration:Poultry integrators in the Hunter Valley adopt mechanical durability specifications that pellet mills can monetize through performance-based pricing tiers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rumen-protected amino acid balancing remains concentrated among retiring practitioners, constraining product development timelines.
- Extrusion equipment lead times:Twin-screw extruder procurement for aquaculture feed expansion faces eighteen-month manufacturer backlogs, delaying capacity additions.
- Multi-site certification complexity:Feed mills supplying both ruminant and monogastric segments must maintain parallel Hazard Analysis Critical Control Point systems, duplicating audit overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Compound Feed Market |
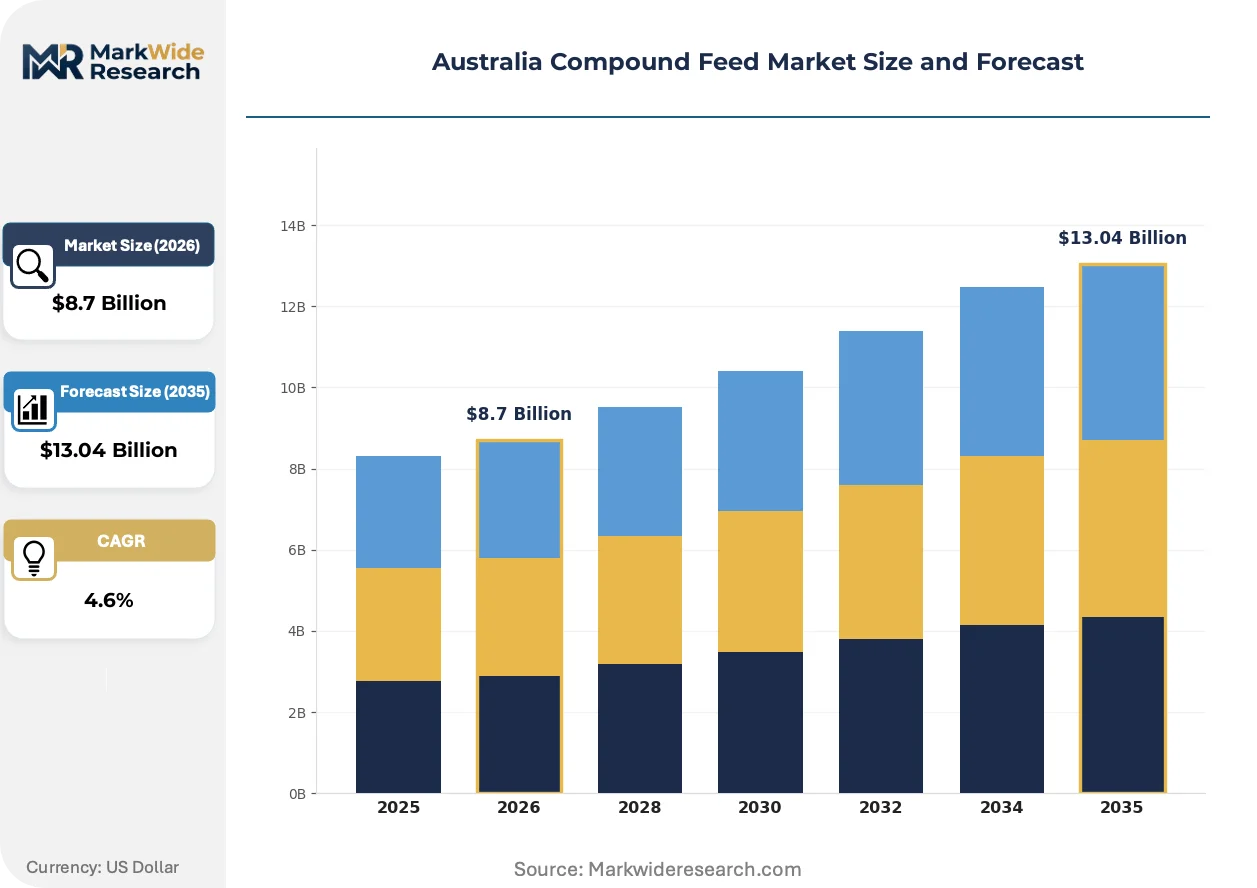
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Ruminant Feed, Swine Feed, Aquaculture Feed Form: Pellets, Crumbles, Mash, Liquid End User: Commercial Farms, Backyard Producers, Feed Manufacturers, Distributors Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale |
| Companies Covered | Archer Daniels Midland, Alltech Inc., Ridley Corporation Limited, Nutreco N.V., Land O'Lakes (Purina), Cargill Inc., Charoen Pokphand Foods, ForFarmers, Inghams Group Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Compound Feed Market Strategic Shifts
Digital feed formulation platforms and novel protein ingredients are compressing development cycles while regulatory tightening on medication residues forces additive portfolio restructuring across Australian manufacturing.
Near-infrared spectroscopy integration is bifurcating quality control protocols. Large feedlot operators deploy real-time ingredient analysis for load-by-load reformulation. Smaller compounders rely on third-party laboratory verification, creating a capability gap that equipment suppliers are exploiting through leasing models.
The Australian Pesticides and Veterinary Medicines Authority is expanding maximum residue limit surveillance for ionophore coccidiostats. Poultry integrators must now document withdrawal periods with batch-level traceability. This compliance burden favors vertically integrated processors with captive laboratory infrastructure over independent feed mills.
Broiler processors in the Darling Downs are consolidating procurement through direct-to-farm delivery contracts. Traditional distributor networks lose volume to logistics platforms that synchronize feed arrival with barn emptying schedules. This disintermediation concentrates purchasing power among three major poultry groups, compressing compounder margins.
Australia Compound Feed Market Segmentation
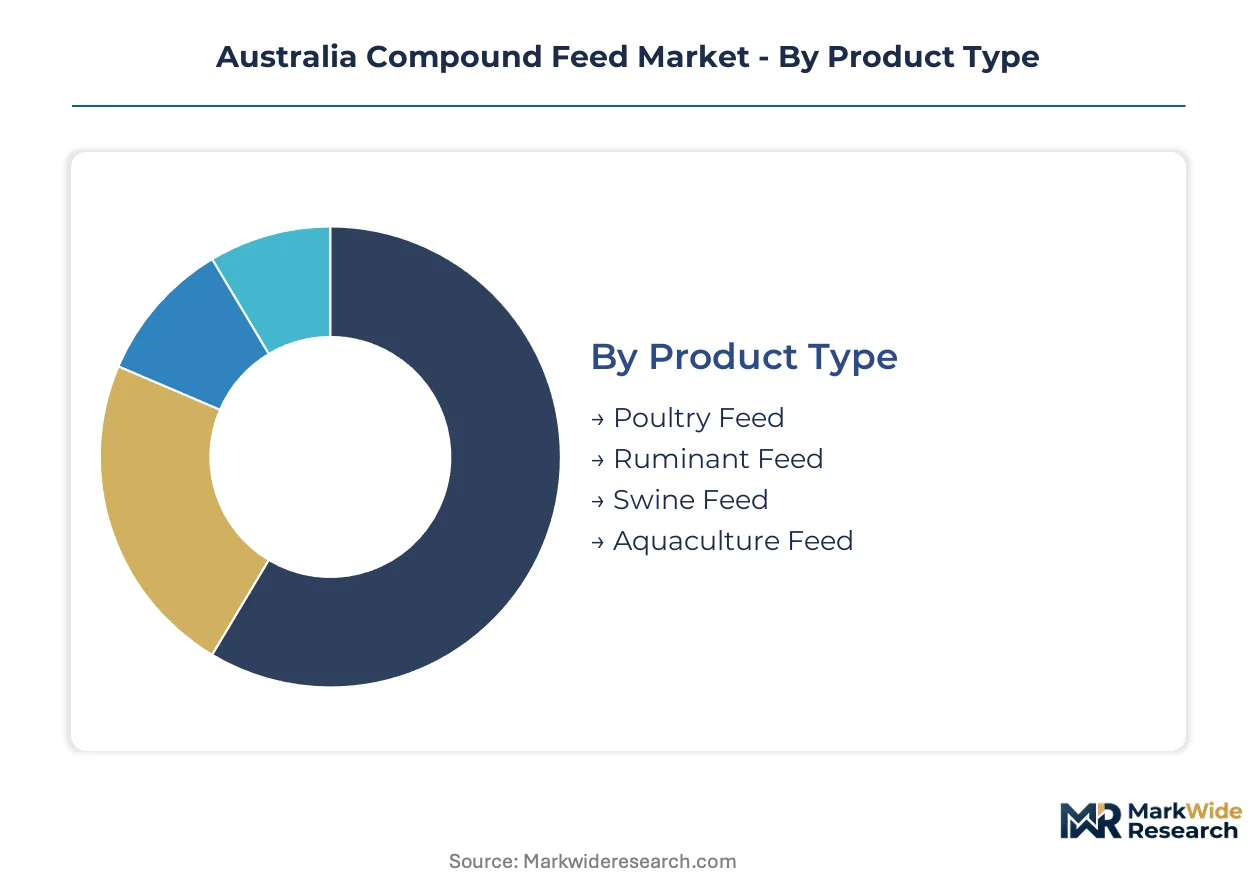
Channel configuration in Australian compound feed varies sharply by buyer scale and species requirements. Commercial poultry integrators bypass traditional distribution entirely, while ruminant feedlot operators in Queensland rely on bulk wholesale networks for grain-based formulations.
Product Type:
Poultry feed moves almost exclusively through direct-to-farm contracts with major processors, whereas ruminant and aquaculture feeds split between manufacturer-direct and wholesale channels depending on farm scale.
- Poultry Feed:Steam-pelleted formulations with standardized metabolizable energy and crude protein profiles dominate. Demand concentrates among vertically integrated broiler processors in the Darling Downs and Hunter Valley, where barn automation requires mechanical durability specifications that only specialized mills can meet.
- Aquaculture Feed:High-fat extruded formulations with specialized amino acid matrices serve ocean-based salmon and prawn operations. Tasmanian pen expansion drives the steepest expansion trajectory as domestic manufacturers struggle to match imported product specifications.
- Ruminant Feed:Total mixed ration concentrates and feedlot finishing rations rely on Victorian and Queensland grain supply corridors.
- Swine Feed:Smaller volume segment concentrated in integrated pork operations with limited independent feed mill penetration.
By volume, poultry feed leads. By growth pace, aquaculture feed is ahead.
Form:
Cost tier stratification separates automated delivery systems from manual feeding operations, with pellet premiums reflecting mechanical durability investments.
- Pellets:Steam-pelleted or extruded forms with calibrated hardness specifications reduce waste in automated auger systems. Poultry integrators in New South Wales specify durability indices above 95 percent, locking in supplier relationships with capital-intensive pelleting lines.
- Mash:Unprocessed grain-meal-vitamin mixtures serve cost-sensitive ruminant segments where on-farm mixing equipment remains common. Queensland feedlot operators accept mash for backgrounding phases before transitioning to pellets for finishing.
- Crumbles:Intermediate particle size targets starter-phase poultry and young swine with beak and palate development requirements.
- Liquid:Molasses-based supplements and fat emulsions deliver precision nutrient dosing in large dairy operations.
Pellet form commands margin premiums. Mash retains the largest volume footprint.
End User:
Customer type determines procurement sophistication, with commercial farms driving specification standards that backyard producers cannot access.
- Commercial Farms:Large-scale operations with captive nutritionists specify custom premixes and audit supplier manufacturing facilities. Victorian dairy cooperatives and Queensland cattle feedlots negotiate long-term contracts with volume-tier pricing.
- Feed Manufacturers:Toll-compounding facilities and private-label producers purchase base mixes for regional branding. These intermediaries concentrate in southeastern grain belts with access to Ridley Corporation and Cargill terminal networks.
- Backyard Producers:Small-scale poultry and hobby farmers purchase retail-packaged products through rural supply stores with limited formulation control.
- Distributors:Independent logistics providers aggregate orders for regional delivery, though their role diminishes as direct contracting expands.
Commercial farms set quality benchmarks. Feed manufacturers intermediate the largest tonnage flows.
Distribution Channel:
Supply concentration in southeastern port terminals shapes channel viability, with direct sales feasible only where grain and protein meal stocks cluster.
- Direct Sales:Manufacturer-to-farm contracts eliminate margin layers for poultry integrators and large feedlot operators. Cargill leverages its port terminal network to synchronize imported soybean meal arrival with compound production schedules.
- Wholesale:Bulk tonnage moves through grain merchant aggregators serving mid-scale ruminant operations without volume to justify direct contracts.
- Retail Outlets:Rural supply stores and agricultural cooperatives serve backyard producers with bagged products and technical advice.
- Online Sales:Emerging channel for specialty additives and small-lot purchases, constrained by freight economics for bulk feed.
Direct sales capture the highest-value tonnage. Wholesale channels move the largest aggregate volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Brisbane grain terminal anchors Queensland's compound feed distribution network, funneling wheat and barley from the Darling Downs to feedlot clusters while Cargill's Newcastle terminal network secures protein meal flows for New South Wales poultry integrators.
New South Wales
The Hunter Valley poultry corridor drives specification-grade pellet demand as Inghams Group and Baiada Poultry scale automated barn complexes. APVMA residue surveillance programs force batch-level traceability investments across processing facilities. Newcastle port terminals concentrate imported soybean meal handling, synchronizing arrival schedules with compound production cycles at Cargill and Ridley Corporation facilities.
Queensland
Feedlot operators in the Darling Downs intensify metabolizable energy precision programs as grain price volatility forces rapid reformulation. Biosecurity regulations administered by the Department of Agriculture, Fisheries and Forestry restrict certain rendered protein imports, redirecting sourcing toward domestic canola processors. Toowoomba and Roma serve as logistics hubs connecting grain belts to coastal export terminals.
Victoria
Dairy cooperatives in Gippsland and the Murray River irrigation districts scale total mixed ration adoption, driving demand for steam-pelleted concentrates with standardized crude protein profiles. Food Standards Australia New Zealand governs label claims for nutritional guarantees across manufacturing facilities. Geelong and Melbourne port infrastructure supports both grain export and specialty additive import flows.
Tasmania
Salmon aquaculture pen expansion in Macquarie Harbour and the D'Entrecasteaux Channel creates demand for high-fat extruded feeds with specialized amino acid matrices. Precision fermentation startups in Hobart develop novel single-cell protein ingredients to reduce reliance on imported soybean meal. The state's biosecurity isolation reinforces domestic sourcing preferences among feed manufacturers.
Western Australia
Grain surplus regions in the Wheatbelt supply eastern states through rail and road corridors while local feed manufacturing remains limited by dispersed livestock operations. CBH Group terminal networks at Albany and Kwinana handle bulk export flows with residual domestic allocation. Perth-based distributors serve small-scale poultry and hobby farm segments through retail supply stores.
Australia Compound Feed Market Competitive Environment
Listed leaders compete with private specialists across formulation capability and terminal access, producing a tiered structure where scale-driven multinationals anchor protein ingredient flows while regional compounders retain ruminant feed relationships. Three archetypes dominate: integrated grain handlers with captive port infrastructure, premix specialists with certified additive portfolios, and toll-compounding facilities serving private-label brands. Competitive moves concentrate on direct-to-farm contracting disintermediation and automated delivery system integration.
Within the multinational grain-handler tier, Archer Daniels Midland and Cargill Inc. occupy positions anchored by port terminal networks that synchronize imported protein flows with compound production schedules. Among domestic specialists, Ridley Corporation Limited exemplifies the integrated manufacturer archetype with southeastern manufacturing density, while Alltech Inc. represents the additive-focused positioning through yeast-based portfolio development. Nutreco N.V. and Land O'Lakes sit within the premix and nutrition solutions segment, serving toll-compounding intermediaries and direct farm contracts respectively.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Alltech Inc. |
| Ridley Corporation Limited |
| Nutreco N.V. |
| Land O'Lakes (Purina) |
| Cargill Inc. |
| Charoen Pokphand Foods |
| ForFarmers |
| Inghams Group Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Queensland feedlot operators and grain merchants lock in supply access while capping price volatility exposure across the Darling Downs supply corridor. These arrangements tether compounder margins to APVMA-certified premix premiums and port-terminal handling fees at Newcastle and Brisbane.
Pricing Analysis
Volume-discount tiering structures separate poultry integrators securing direct-to-farm contracts from ruminant operators purchasing through wholesale aggregators. Premium-mid-economy pricing differentiation tracks mechanical durability specifications and batch-level traceability investments demanded by Hunter Valley broiler processors. Cost compression in mash formulations is intensifying because backyard producers retreat from bulk purchasing. Commercial farms exhibit the lowest price sensitivity due to captive nutritionist staffing, while hobby farmers purchasing retail-packaged products face the highest per-unit costs.
Supply Chain Analysis
Eighteen-month lead times for twin-screw extruder procurement expose aquaculture feed expansion timelines to manufacturer backlog risk. Supply concentrates in southeastern Australia, with Newcastle and Melbourne port terminals anchoring imported soybean meal flows while Victorian grain belts feed domestic canola and lupin processing. Raw material dependencies center on wheat, barley, and oilseed meals subject to climate-driven yield fluctuation. Single-source vulnerability concentrates at limited deepwater protein meal facilities. Distribution runs through direct-sales channels for integrated poultry processors and wholesale networks for mid-scale ruminant operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian compound feed is cycling through a recovery phase as grain price volatility forces rapid reformulation investments and consolidates procurement power among vertically integrated livestock processors.
For Market Incumbents: Consolidate formulation chemist expertise through targeted hiring before practitioner retirement accelerates, and deepen backward integration into domestic canola crushing to offset biosecurity-restricted rendered protein imports. Ridley Corporation and Cargill anchor positions through terminal infrastructure control, but emerging precision fermentation startups threaten additive portfolio relevance. For New Entrants and Emerging Players: Lead with Tasmanian salmon aquaculture feed specifications currently under-supplied by domestic manufacturers, targeting high-fat extruded formulations with specialized amino acid matrices. White-space concentration sits with automated delivery system integration for poultry integrators seeking mechanical durability performance guarantees. A toll-compounding model serving private-label regional brands minimizes capital intensity. For Investors and Strategic Acquirers: Capital is best deployed toward premix specialists with certified additive portfolios and captive laboratory infrastructure capable of absorbing APVMA residue surveillance compliance burdens. Long-term viability hinges on formulation platform scalability across ruminant and monogastric segments. The signal to watch is precision fermentation startup commercialization timelines disrupting imported soybean meal dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Domestic canola crushing reduces biosecurity-restricted import exposure for Queensland feedlot operators. |
| Precision Fermentation Scale-Up | Single-cell protein production in Hobart bioreactors shortens aquaculture feed supply chains. |
| Direct-to-Farm Contract Expansion | Poultry integrators in the Hunter Valley bypass distributor margins through synchronized delivery logistics. |
| Certified Premix Capability Investment | APVMA residue limit enforcement locks in premium pricing for compliant feed mills. |
| Automated Feed Delivery Integration | Mechanical durability specifications above 95 percent create supplier switching costs for pellet mills. |
Study Parameters
The analysis maps poultry, ruminant, aquaculture, and swine feed sub-sectors, each validated through compounder procurement managers, feedlot nutritionists, and grain merchant trading desks. Primary interviews with Victorian dairy cooperative technical directors, Queensland cattle feedlot operators, and Tasmanian salmon aquaculture procurement leads combined with secondary validation from APVMA regulatory filings, Department of Agriculture biosecurity directives, and grain terminal throughput disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs against Ridley Corporation and Cargill terminal network capacity data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled species segmentation, form factor differentiation, and end-user scale tiering alongside regional production cluster dynamics. CAGRs derived from historical trajectory analysis and forward-looking input cost assumptions incorporated wheat and barley price volatility indices, extrusion equipment lead time trends, and precision fermentation commercialization timelines without year-specific anchoring.
Forecasts assume regulatory continuity in APVMA residue limit enforcement and Department of Agriculture biosecurity administration; material policy shifts on antibiotic growth promoters or rendered protein import restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Africa Olive Market