
 Plant Antifreeze Market | 2026-2036
Plant Antifreeze Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Antifreeze Market Analytics
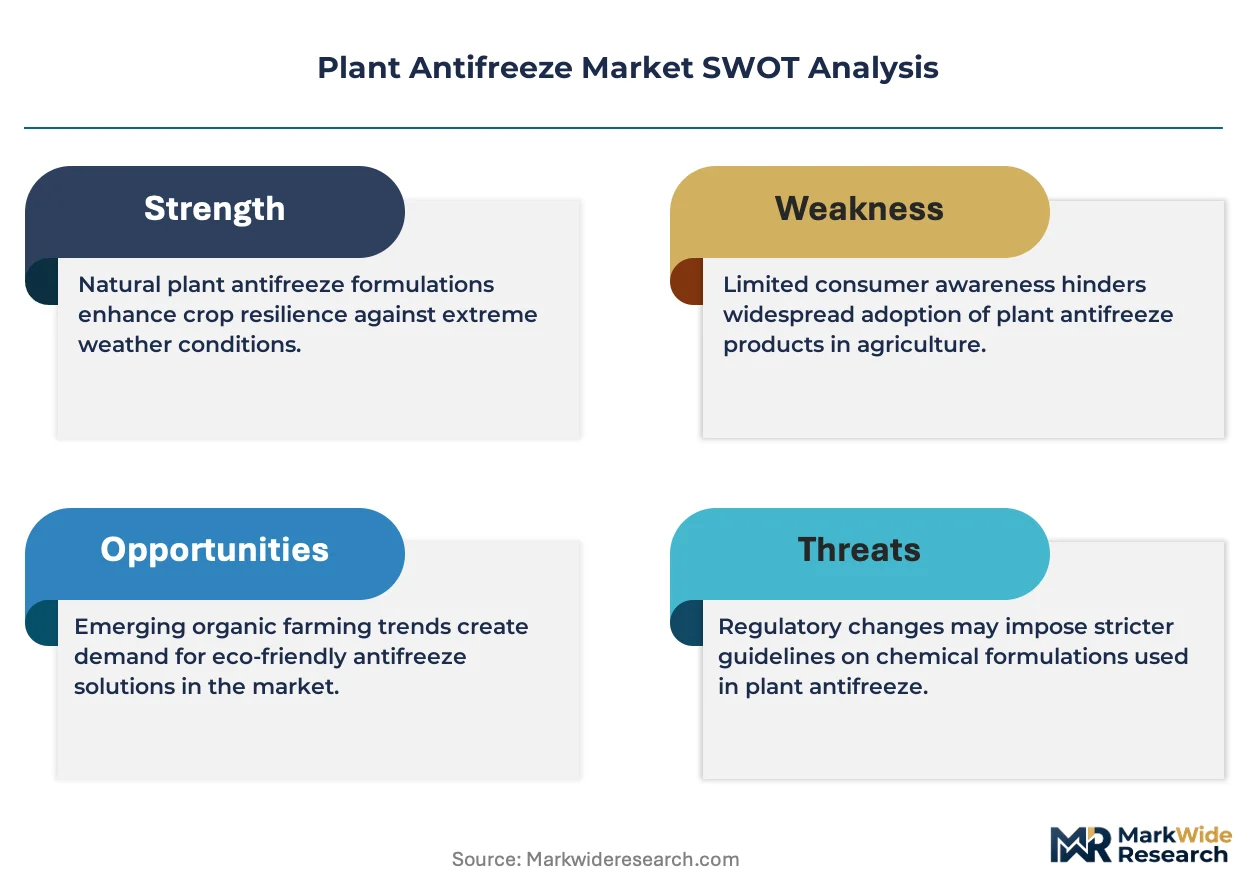
Greenhouse and nursery operations is consolidating as the fastest-expanding end-use channel for plant antifreeze products, displacing traditional open-field commodity applications. BASF SE leverages its synthetic chemistry heritage to sustain formulation leadership across European horticulture markets. Syngenta anchors its position through integrated crop protection portfolios that bundle antifreeze agents with stress-management protocols. Nufarm competes aggressively in biobased development pipelines targeting regulatory-sensitive export zones.
Plant antifreeze comprises chemical or biological agents that depress the freezing point of intracellular and extracellular plant fluids, typically functioning through cryoprotectant mechanisms involving glycoproteins, polyols, or ethylene glycol derivatives at application rates calibrated to crop species and frost severity. Synthetic antifreezes still dominate volume shipments, though biobased antifreezes are capturing margin pools as sustainability premiums widen across contract agriculture. Liquid formulations lead in commercial farming due to spray application compatibility, while granular formulations occupy niche positions in pre-plant soil incorporation for perennial stock.
EPA registration requirements under FIFRA govern active ingredient approval and label claims for plant antifreeze products distributed in the United States, creating multi-year barriers to market entry. EU REACH compliance and the F-Gas Regulation constrain synthetic formulation chemistries, redirecting R&D investment toward biodegradable alternatives. The EU Green Deal and associated Farm-to-Fork strategy intensify scrutiny of persistent chemical residues in food-chain crops. Stakeholders must monitor evolving residue tolerance thresholds and biocidal product reclassification proceedings that could force reformulation cycles across major export jurisdictions.
Market Dynamics
The EU F-Gas Regulation and REACH compliance deadlines are compressing synthetic chemistry margins while redirecting R&D budgets toward biodegradable cryoprotectant platforms. This regulatory pivot is fragmenting formulation leadership between established synthetic suppliers and emerging bioprocess developers.
Growth Catalysts
- EU Green Deal residue thresholds:Farm-to-Fork strategy mandates are accelerating grower migration from persistent synthetic chemistries toward glycoprotein-based formulations that bypass maximum residue limit scrutiny in export markets.
- California almond orchard density:Perennial crop expansion across the Central Valley generates concentrated seasonal demand spikes that justify dedicated antifreeze distribution infrastructure and technical service investments.
- Liquid spray application compatibility:Precision agriculture equipment integration enables calibrated droplet deposition that reduces active ingredient waste compared to legacy blanket application methods.
Market Restraints
- Petrochemical feedstock volatility:Ethylene glycol derivative costs fluctuate with natural gas pricing, compressing margin stability for synthetic formulation manufacturers serving price-sensitive commodity crop segments.
- EPA FIFRA registration timelines:Multi-year active ingredient approval processes create barrier-to-entry effects that favor incumbents with established label portfolios and regulatory affairs capabilities.
- Biobased production scale constraints:Fermentation-derived cryoprotectant output remains limited by bioreactor capacity and downstream purification bottlenecks at commercial manufacturing sites.
Strategic Opportunities
- Florida citrus grove rehabilitation:Hurricane recovery and HLB disease management programs are expanding replanting activity that requires frost protection for young tree establishment phases.
- Greenhouse hydroponic vegetable expansion:Controlled-environment agriculture operators in the Netherlands and Spain are adopting closed-loop irrigation systems compatible with precision antifreeze dosing protocols.
- USDA conservation program incentives:Environmental Quality Incentives Program cost-sharing supports sustainable crop protection adoption, reducing net investment barriers for biobased formulation trials.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiology and fermentation scale-up expertise concentrates at a limited number of agricultural biotechnology hubs, constraining rapid capacity expansion.
- Residue analytical method standardization:Inconsistent detection protocols across EU member state reference laboratories create uncertainty in compliance verification and label claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Antifreeze Market |
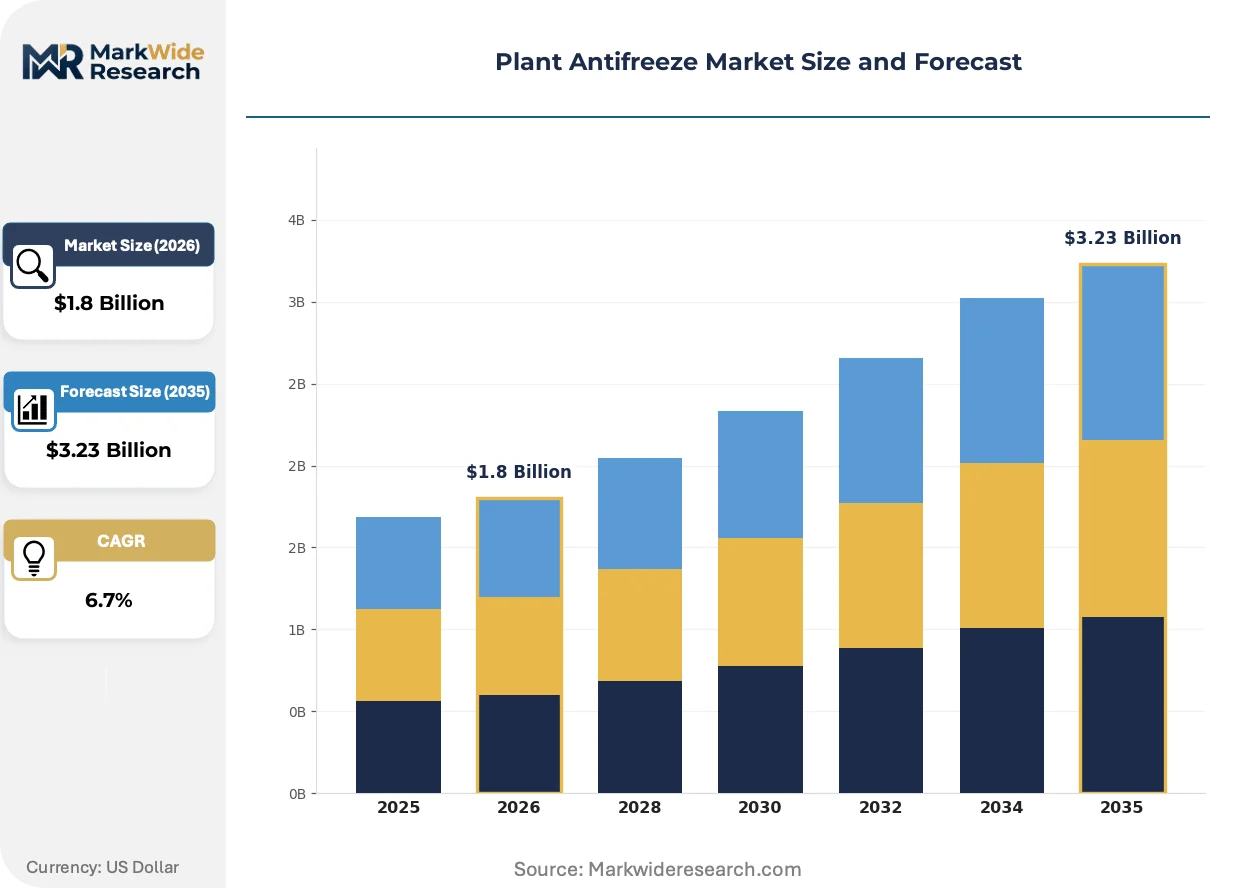
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Antifreezes, Synthetic Antifreezes, Biobased Antifreezes, Chemical Antifreezes Formulation: Liquid Formulations, Granular Formulations, Powder Formulations, Gel Formulations Application Type: Horticulture, Agriculture, Forestry, Landscaping End Use: Commercial Farming, Residential Gardening, Greenhouses, Nurseries |
| Companies Covered | BASF SE, Syngenta, Bayer AG, DuPont, ADAMA, Corteva Agriscience, Nufarm, Sumitomo Chemical Co., Ltd., Gharda Chemicals Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Antifreeze Market Evolving Landscape
Formulation chemistry is bifurcating between synthetic optimization for cost-sensitive commodity applications and bioprocess innovation for premium export-oriented crops. This divergence is reshaping competitive positioning and partnership strategies across the value chain.
Recombinant antifreeze protein production is expanding into commercial agriculture through microbial expression systems that yield glycoprotein cryoprotectants at cost parity with refined polyol formulations. Greenhouse operators in the Netherlands are piloting these proteins for ornamental propagation, enabling precise freezing point depression without glycol residue accumulation that complicates wastewater discharge permits.
EU REACH authorization requirements for persistent organic pollutants are forcing reformulation of ethylene glycol derivatives used in perennial crop protection. Manufacturers serving German and French horticulture markets are submitting substitution plans that prioritize biodegradable polyol alternatives, compressing the commercial viability window for legacy synthetic chemistries in export-oriented production zones.
California almond processors are consolidating procurement decisions through cooperative purchasing arrangements that bypass traditional distribution intermediaries. This channel compression concentrates volume commitments with formulation suppliers capable of integrated technical support and residue testing documentation, marginalizing smaller distributors lacking laboratory partnerships or field agronomy capabilities.
Plant Antifreeze Market Segmentation
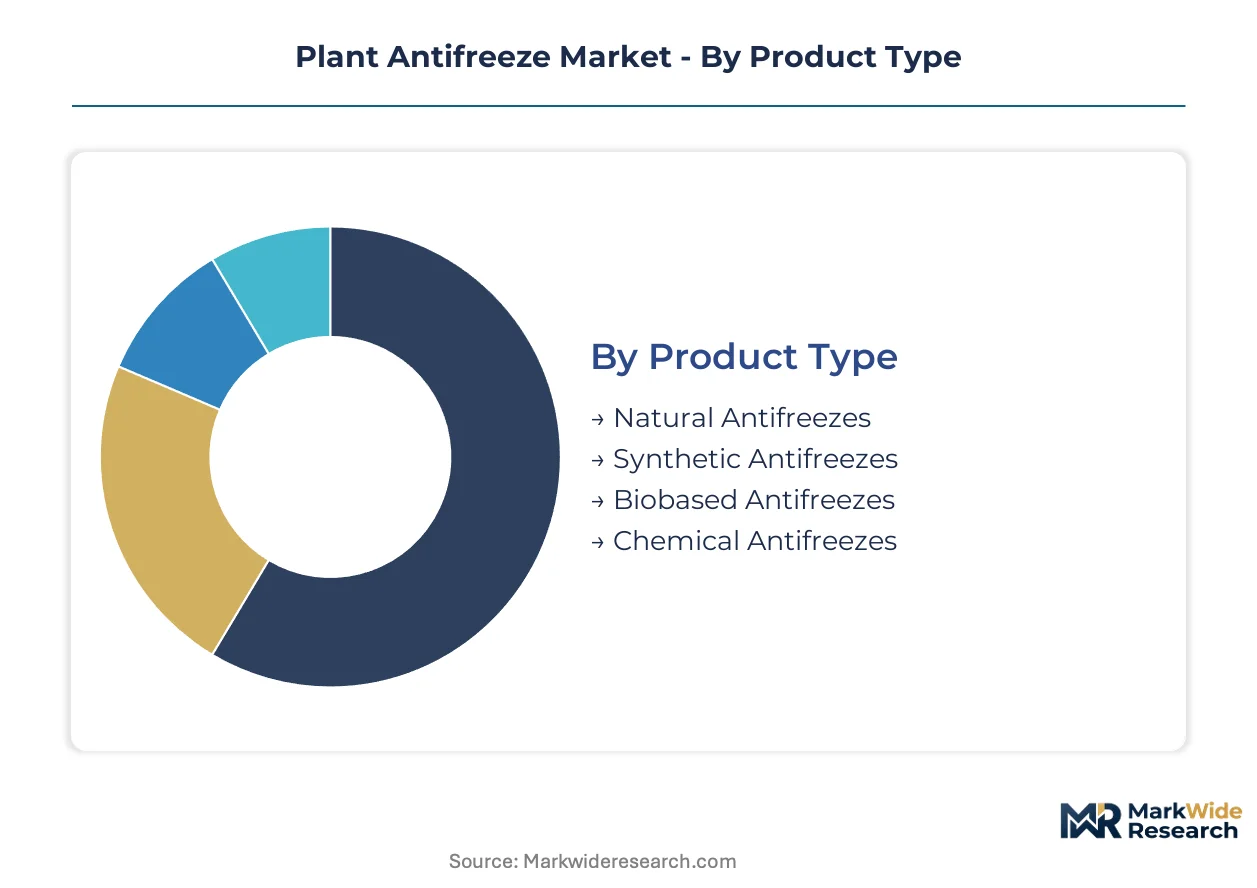
Capital deployment patterns across the plant antifreeze market diverge sharply by segment. Formulation chemistry and application infrastructure requirements determine which categories attract concentrated investment versus fragmented participation.
Product Type:
Capital intensity peaks with bioprocess manufacturing platforms requiring dedicated fermentation capacity and downstream purification infrastructure.
- Natural Antifreezes:Derived from cold-adapted organisms including fish glycoproteins and plant cryoprotectants. Demand concentrates in Dutch ornamental propagation facilities where wastewater discharge restrictions favor residue-free alternatives.
- Synthetic Antifreezes:Ethylene glycol and propylene glycol derivatives manufactured through established petrochemical pathways. California almond cooperatives drive volume procurement through centralized purchasing arrangements that favor suppliers with integrated technical service capabilities.
- Biobased Antifreezes:Fermentation-derived polyols and recombinant proteins. Limited commercial scale due to bioreactor capacity constraints and purification bottlenecks at manufacturing sites.
- Chemical Antifreezes:Inorganic salt formulations and methanol-based solutions. Price-sensitive commodity crop applications in regions with less stringent residue regulation.
Synthetic antifreezes absorb the bulk of installed capacity; biobased antifreezes are expanding most quickly.
Formulation:
Application equipment compatibility determines distribution economics and customer switching costs across formulation categories.
- Liquid Formulations:Ready-to-spray solutions compatible with precision agriculture equipment. California Central Valley almond orchards and Florida citrus groves generate concentrated seasonal demand that justifies dedicated distribution infrastructure.
- Granular Formulations:Slow-release crystals for pre-plant soil incorporation. Perennial stock establishment phases in nursery operations favor this application method.
- Powder Formulations:Concentrated active ingredients requiring on-site reconstitution. Limited adoption due to mixing labor requirements and calibration complexity.
- Gel Formulations:Viscous preparations for targeted stem and bud application. Niche positioning in high-value ornamental propagation where precision deposition justifies premium pricing.
Liquid formulations dominate commercial farming procurement; gel formulations are climbing the fastest as controlled-environment agriculture expands.
Application Type:
Revenue stability varies by application cycle predictability and crop replacement frequency.
- Horticulture:Protected cultivation of fruits, vegetables, and ornamental species. Netherlands greenhouse operators pilot recombinant antifreeze proteins for year-round production cycles.
- Agriculture:Open-field row crops and perennial orchards. California almond orchard density generates the largest absolute volume requirements.
- Forestry:Seedling establishment and plantation management. Cyclical demand tied to reforestation program funding and timber price cycles.
- Landscaping:Turf management and ornamental plantings in municipal and commercial properties. Fragmented customer base with seasonal purchasing patterns.
Agriculture commands the majority of formulation volume; horticulture is gaining share fastest through greenhouse expansion.
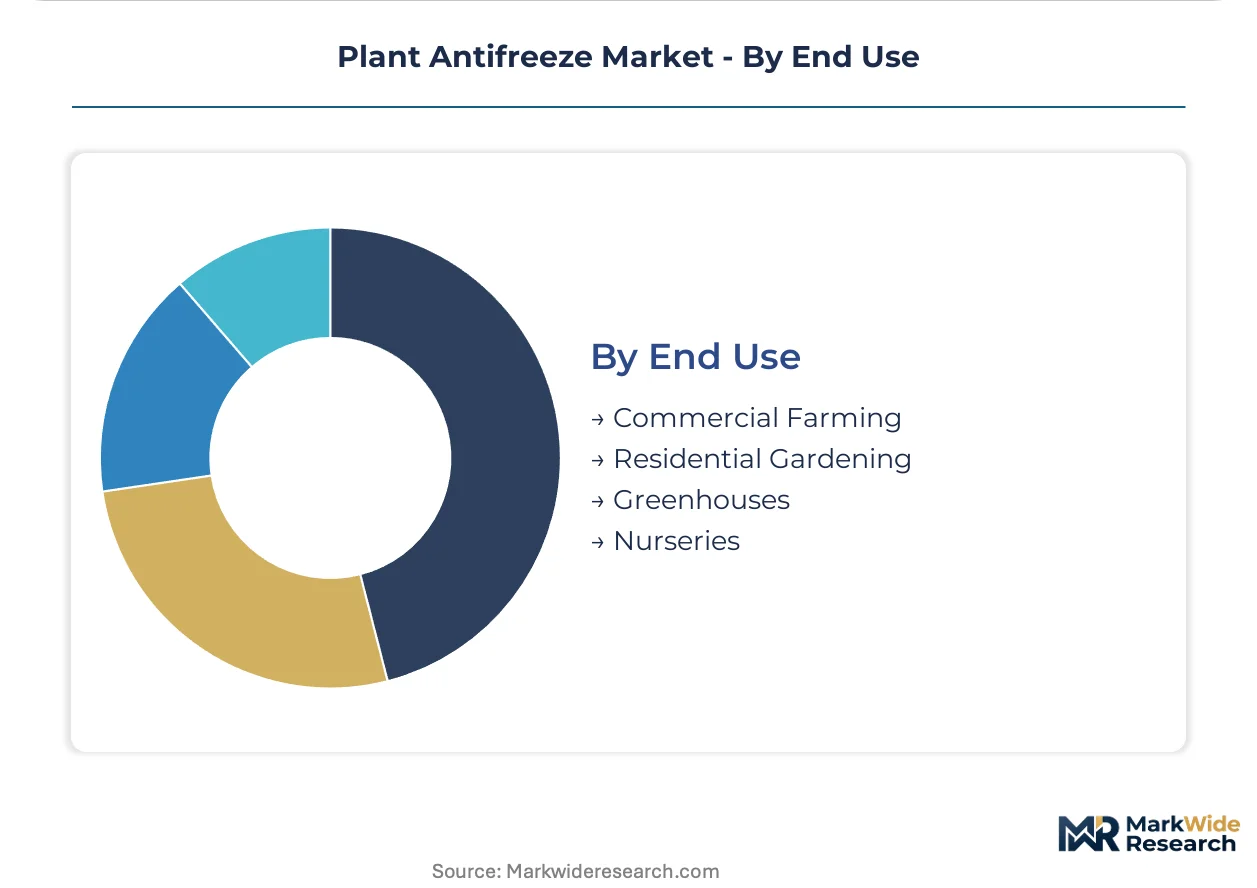
End Use:
Customer scale determines technical service requirements and procurement channel structure.
- Commercial Farming:Large-scale operations with integrated crop protection decision-making. Cooperative purchasing in California bypasses traditional distribution intermediaries.
- Residential Gardening:Consumer retail channels with price-sensitive, low-volume transactions. Limited penetration due to frost protection awareness gaps.
- Greenhouses:Controlled-environment agriculture with closed-loop irrigation compatibility. Netherlands and Spain operators adopt precision dosing protocols.
- Nurseries:Perennial stock propagation requiring establishment-phase protection. Hurricane recovery programs in Florida expand replanting activity.
Commercial farming absorbs the bulk of manufacturer technical service investment; greenhouses are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley Agricultural Enterprise Zones concentrate perennial crop protection procurement, while Dutch greenhouse clusters drive biobased formulation demand through wastewater discharge restrictions.
United States
California almond cooperatives generate concentrated seasonal volume through centralized purchasing arrangements that bypass traditional distribution intermediaries. EPA FIFRA registration timelines create multi-year barriers favoring incumbents with established label portfolios. Florida citrus grove rehabilitation programs expand replanting activity requiring frost protection for young tree establishment phases.
Germany
REACH authorization requirements for persistent organic pollutants force reformulation of ethylene glycol derivatives used in perennial crop protection. Manufacturers serving German horticulture markets submit substitution plans prioritizing biodegradable polyol alternatives. The Rhine-Ruhr industrial corridor hosts fermentation-derived cryoprotectant pilot facilities targeting EU Green Deal compliance.
Netherlands
Greenhouse operators in Westland pilot recombinant antifreeze proteins for ornamental propagation through closed-loop irrigation systems. EU F-Gas Regulation and REACH compliance deadlines compress synthetic chemistry margins while redirecting R&D budgets. Wageningen University clusters anchor bioprocess engineering talent pipelines for microbial expression system scale-up.
Spain
Controlled-environment agriculture operators in Almería adopt precision antifreeze dosing protocols compatible with hydroponic vegetable expansion. EU Farm-to-Fork strategy mandates accelerate grower migration from persistent synthetic chemistries. The Murcia region concentrates biobased formulation trials supported by conservation program incentives.
Australia
Viticulture operations in South Australia and Victoria deploy frost protection for high-value wine grape production during episodic cold events. The country's national agricultural chemical regulator enforces residue tolerance thresholds aligned with export market requirements. Riverland irrigation districts concentrate liquid formulation demand through spray application infrastructure.
Plant Antifreeze Market Competitive Landscape
Top-tier vendors anchor synthetic chemistry heritage, while emerging bioprocess developers occupy specialty niches. The market structure bifurcates between established petrochemical formulation leaders and fermentation-based innovators. Three archetypes dominate: integrated agrochemical conglomerates with bundled crop protection portfolios, dedicated antifreeze specialists pursuing biobased differentiation, and regional distributors with technical service capabilities. Competitive moves concentrate on strategic partnerships for bioreactor capacity access and geographic expansion through cooperative purchasing channel penetration.
Within the integrated agrochemical tier, BASF SE and Syngenta occupy positions exemplifying synthetic formulation leadership across European horticulture markets. Nufarm represents the biobased development archetype, anchoring regulatory-sensitive export zone strategies. These three companies illustrate the competitive divergence between petrochemical heritage and fermentation innovation pathways reshaping procurement patterns.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta |
| Bayer AG |
| DuPont |
| ADAMA |
| Corteva Agriscience |
| Nufarm |
| Sumitomo Chemical Co., Ltd. |
| Gharda Chemicals Ltd |
| Others |
Value Network & Pricing Analysis
Ethylene glycol spot price volatility cascades through formulation tiers, compressing margins for synthetic antifreeze manufacturers while biobased alternatives capture sustainability premiums in export-oriented procurement channels.
Pricing Analysis
Short lead-time premiums apply to California almond cooperative orders during frost emergency windows, while spot inventory discounts emerge in off-season procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates glycoprotein formulations from refined polyol derivatives from commodity ethylene glycol blends. Cost compression in synthetic tiers is intensifying because petrochemical feedstock volatility feeds through contract renegotiation clauses. Commodity crop operators in price-sensitive segments exhibit highest price sensitivity; greenhouse operators in the Netherlands show least sensitivity due to wastewater compliance cost avoidance.
Supply Chain Analysis
Bioreactor capacity for fermentation-derived cryoprotectants rests on German and Dutch pilot facility investments, while ethylene glycol derivative production draws from established petrochemical complexes in the United States and Belgium. Key inputs include cold-adapted fish glycoproteins, microbial expression systems, and refined polyol feedstocks. Single-source vulnerability concentrates in bioprocess engineering talent pools anchored at Wageningen University clusters. Distribution runs through cooperative purchasing arrangements in California that bypass traditional agricultural chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up bottlenecks constrain biobased antifreeze output, propping pricing premiums for suppliers with secured bioreactor access across the analysis window.
For Market Incumbents: Hedge synthetic chemistry margin exposure by accelerating biodegradable polyol substitution plans ahead of EU REACH authorization deadlines. Prioritize capacity addition in the Rhine-Ruhr corridor to capture German horticulture demand shifting from persistent organic pollutants. Channel control through integrated technical service partnerships with California almond cooperatives defends against emerging bioprocess developers. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for glycoprotein-based formulation penetration in Dutch ornamental propagation facilities facing wastewater discharge restrictions. Target greenhouse hydroponic vegetable expansion in Spain and the Netherlands as the most penetrable segment. Pursue USDA Environmental Quality Incentives Program cost-sharing qualification as the primary go-to-market angle for biobased trials. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-based specialists with secured bioreactor partnerships in the Netherlands during synthetic chemistry margin compression phases. Long-term viability hinges on regulatory tailwinds persisting across the Farm-to-Fork strategy implementation horizon. Watch EU member state residue analytical method standardization proceedings as the inflection indicator for compliance verification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Secures fermentation output for glycoprotein cryoprotectants serving Dutch greenhouse wastewater compliance requirements. |
| Backward Integration into Cold-Adapted Organism Sourcing | Captures proprietary glycoprotein libraries from Arctic fish species for recombinant protein expression platforms. |
| EU Green Deal Certification Program | Unlocks premium pricing in German and French horticulture markets with verified biodegradable formulation credentials. |
| Long-term Supply Agreement with California Almond Cooperatives | Locks in seasonal volume commitments through centralized purchasing arrangements bypassing distributor intermediaries. |
| Joint Venture with Wageningen University Bioprocess Hub | Accesses industrial microbiology talent pipelines constrained across European agricultural biotechnology clusters. |
Research Methodology
Multi-period observation of EPA FIFRA registration timelines, EU REACH substitution plan submissions, and California almond acreage expansion anchored the trend analysis, supplemented by interviews with formulation R&D directors, agricultural cooperative procurement managers, greenhouse operations executives, and bioprocess engineering specialists. Secondary validation drew from EPA registration databases, ECHA authorization lists, USDA acreage reports, and EU Farm-to-Fork strategy implementation documents. Bottom-up volume modeling triangulated against top-down market sizing across synthetic and biobased chemistry segments.
Input-output matrices mapped ethylene glycol derivative cost structures, fermentation-derived cryoprotectant yield curves, and precision agriculture equipment penetration rates across the projection horizon. Segmentation dimensions included formulation chemistry type, application method, crop category, and end-use customer scale. CAGRs derived from regression analysis of historical volume shipments against acreage expansion and regulatory compliance deadline schedules. Industry-specific inputs incorporated almond orchard density patterns and greenhouse hydroponic adoption trajectories.
The model assumes a particular technology adoption path for recombinant antifreeze protein expression; alternative pathways for microbial glycoprotein production would alter the outlook if bioreactor capacity constraints resolve faster than baseline assumptions. Forecasts reflect these documented assumptions, with revision triggers including EU residue tolerance threshold adjustments, California water restriction policy shifts, and petrochemical feedstock price regime changes. A small set of regulatory and capacity triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Alfalfa Pellets Market