
 Non GMO Soybean Market | 2026-2036
Non GMO Soybean Market Size, Share, and Industry Trends Forecast 2026-2036
Non GMO Soybean Market Intelligence
Identity-preserved handling protocols for high-protein soybean varieties are unwinding the commodity-centric model of soybean trade. Global agri-business giants like Archer-Daniels-Midland Company leverage extensive logistics networks to segregate non-GMO crops from farm to processor. Cargill competes by offering a broad portfolio of verified non-GMO ingredients to multinational food manufacturers. Specialists such as Clarkson Grain Company differentiate on certified organic and transitional non-GMO soybean supply for niche markets.
Non-GMO soybeans are cultivars developed through conventional plant breeding methods, explicitly excluding genetic engineering or modification. These soybeans must have a genetic identity purity of 99.1% or higher to meet stringent food and feed labeling standards. Soy protein isolate represents a high-value product, commanding premium pricing in the nutraceuticals and specialized food sectors. While the animal feed industry remains a volume driver, margin growth is concentrated in food and beverage applications.
Market access is shaped by national labeling laws and verification bodies, from the USDA's National Bioengineered Food Disclosure Standard to the European Food Safety Authority's (EFSA) strict GMO traceability requirements. In Brazil, the CTNBio's oversight of genetically modified organisms defines the segregation protocols necessary for export. Navigating the patchwork of international regulations and certification costs remains the central challenge for supply chain participants.
Market Dynamics
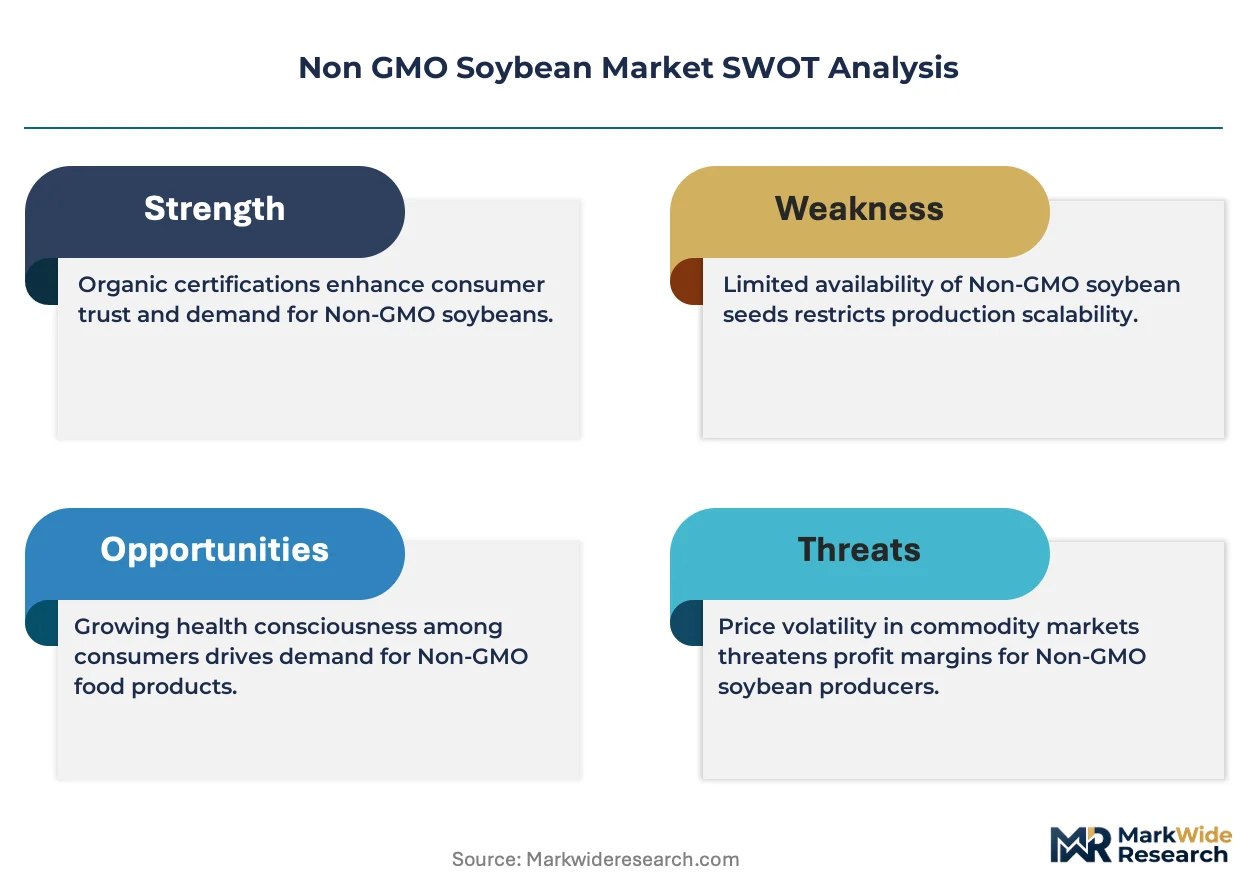
The fundamental dynamic shaping the Non GMO Soybean market is the operational friction between the scale-driven commodity system and the stringent identity-preservation protocols required for non-GMO segregation. This creates a bifurcated supply chain with distinct cost structures and logistics models.
Growth Catalysts
- Plant-Based Protein Demand:The food and beverage industry's escalating need for plant-based ingredients to formulate meat and dairy alternatives is a primary catalyst, with products often seeking Non-GMO Project Verification to appeal to health-conscious consumers.
- Premium Product Formulation:High-value applications, including soy protein isolates for the nutraceutical and specialized infant formula sectors, depend on certified non-GMO supply to meet quality specifications and command higher price points.
- Stringent Labeling Regimes:Regulations such as the European Food Safety Authority's (EFSA) mandatory traceability and labeling for GMOs effectively create protected, premium markets for verified non-GMO soybeans within the European Union.
Market Restraints
- Elevated Production Costs:Identity-preserved handling protocols, including separate storage, dedicated transportation, and frequent testing, impose significant costs that are not present in the conventional commodity soybean supply chain.
- Co-mingling Contamination Risk:The pervasive cultivation of genetically modified soybeans creates a constant risk of cross-contamination during planting, harvesting, transport, and storage, which can lead to rejection of entire shipments.
- Purity Standard Adherence:Consistently achieving the 99.1% genetic identity purity threshold required by many certification bodies and international buyers presents a significant technical and logistical barrier for producers and handlers.
Strategic Opportunities
- Aquaculture Feed Development:Formulating specialized non-GMO soy-based feeds for the aquaculture industry represents a significant volume opportunity, replacing fishmeal with a sustainable, protein-rich alternative.
- Transitional Organic Programs:Supporting farms through the multi-year transition to certified organic by creating a market for their transitional non-GMO soybeans offers a way to build future certified organic supply.
- Blockchain-Enabled Traceability:Deploying blockchain platforms to provide immutable, farm-to-fork traceability can enhance consumer trust and justify premium pricing, creating a new layer of value for certified supply chains.
Industry Challenges
- Regulatory Patchwork Navigation:Supply chain participants face the operational challenge of complying with a disparate array of national regulations, from the USDA's bioengineered food disclosure to Brazil's CTNBio oversight.
- Testing and Certification Bottlenecks:Delays in laboratory testing for genetic purity and the administrative timelines for securing non-GMO certifications can disrupt supply flows and impede market access for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non GMO Soybean Market |
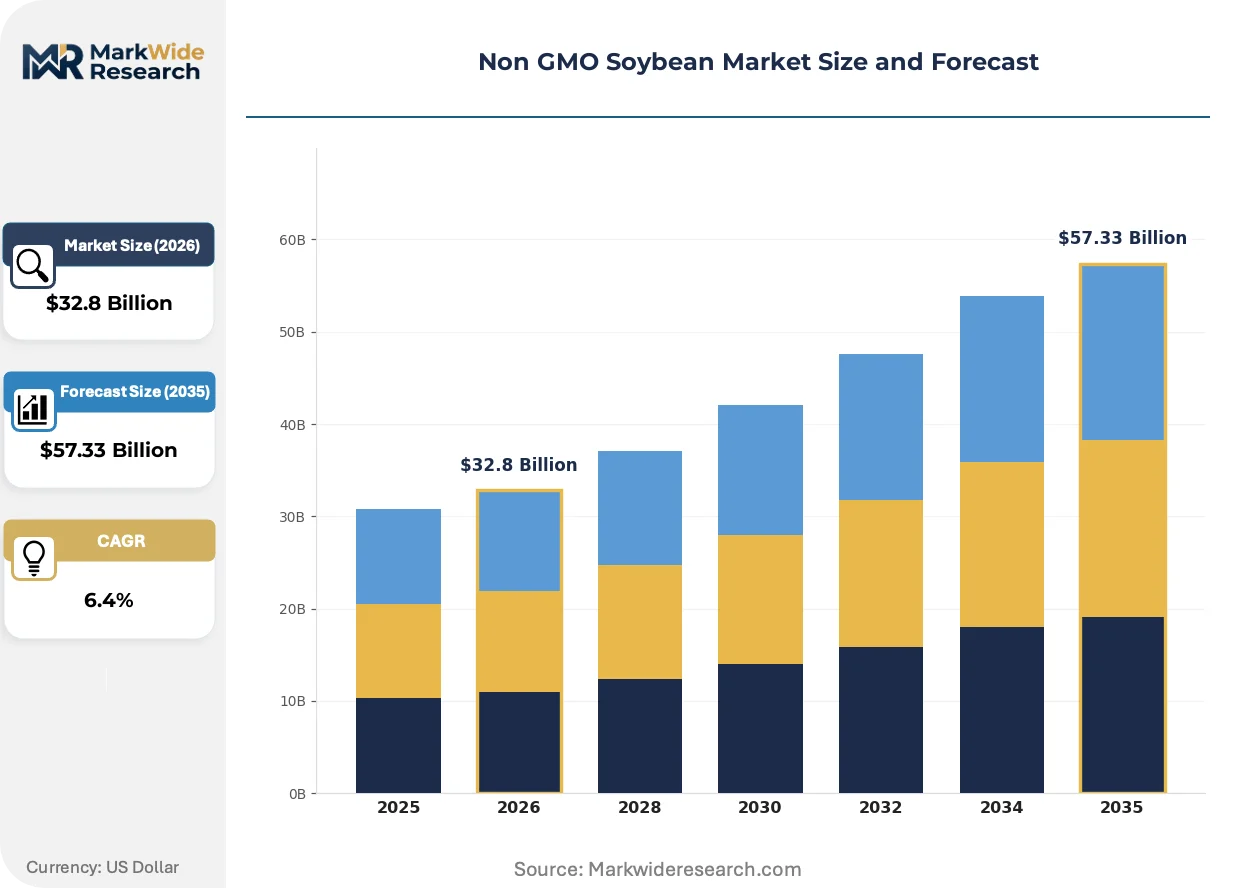
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Soy Flour, Soy Protein Isolate, Soy Oil End Use Industry: Food & Beverages, Animal Feed, Nutraceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Form: Whole, Powdered, Liquid, Granulated |
| Companies Covered | Archer-Daniels-Midland Company, Cargill, Grain Millers, Zeeland Farm Services, World Food Processing, Laura Soybeans, Sans, Divine Soya & Agro Food, Clarkson Grain Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non GMO Soybean Market Strategic Shifts & Innovations
Technological advancements in genetic testing and data management are transforming the market's ability to enforce purity and traceability. These tools are becoming essential for managing risk and validating premium claims in a complex global supply chain where non-GMO and GM crops coexist.
Advanced molecular diagnostics like digital PCR (dPCR) provide ultra-sensitive detection and quantification of genetic modifications. Food manufacturers and grain aggregators are increasingly adopting this technology at intake points to verify supplier declarations. The use of dPCR is decomposing the industry's historical reliance on paper certificates, replacing them with data-driven, quantifiable proof of genetic purity.
The USDA's National Bioengineered Food Disclosure Standard (NBFDS) has formalized labeling requirements in the United States. This regulation compels food manufacturers to disclose the presence of bioengineered ingredients, creating a clear incentive to source non-GMO alternatives. The food processing sector, particularly consumer-facing brands, is responding by reformulating products to avoid the "Bioengineered" label and instead leverage a "Non-GMO" claim.
A notable behavioral shift is the move beyond single-attribute claims toward demand for multi-certified products. Buyers in the natural and organic food sectors are disrupting traditional procurement by seeking soybeans that are not only non-GMO but also certified organic or grown under regenerative agriculture protocols. This bundling of certifications is most prominent in premium food segments in North America and Germany, reflecting a deeper consumer push for holistic transparency.
Non GMO Soybean Market Segmentation
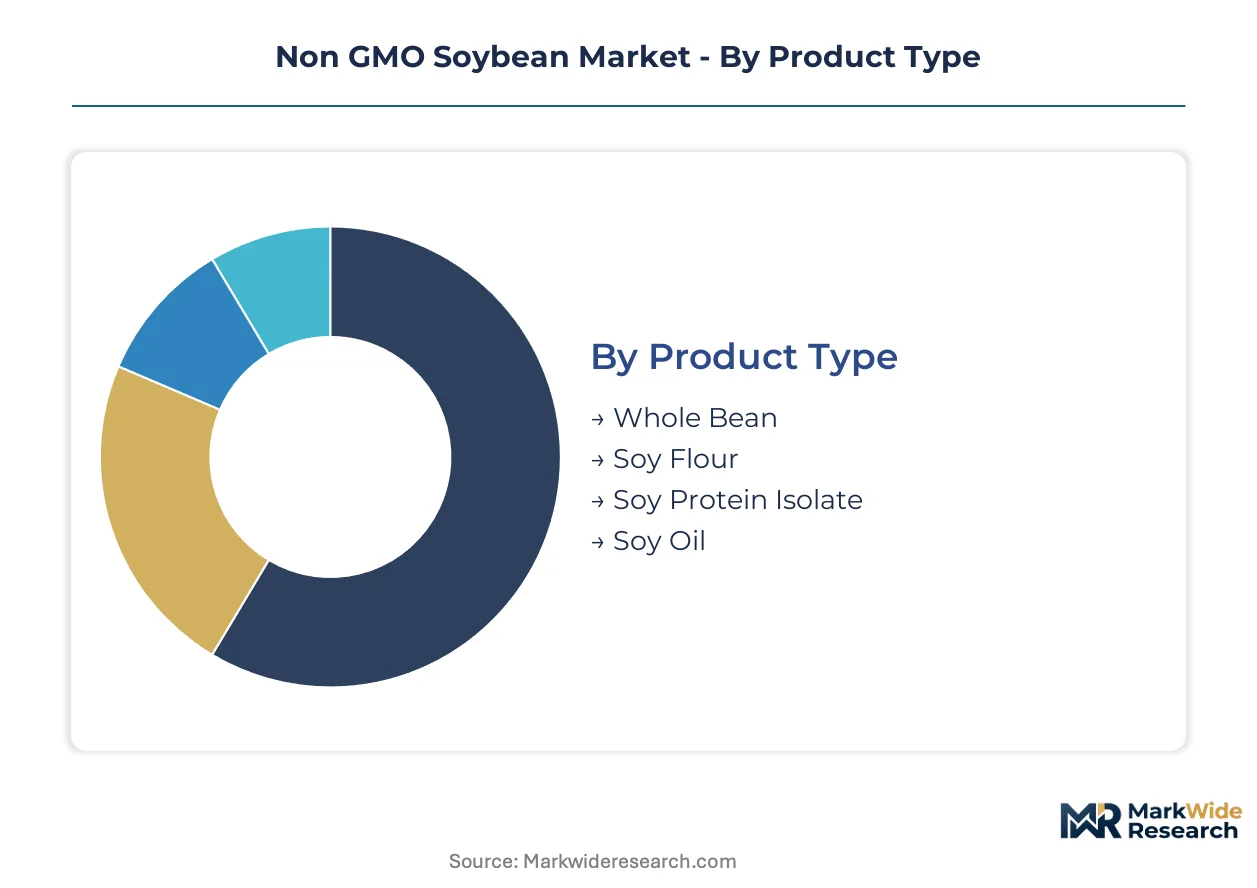
The Non GMO Soybean Market is meticulously segmented to reflect the diverse applications and consumer preferences driving its expansion. Understanding these distinct segments provides clarity on where value creation and demand concentration are most pronounced across the global supply chain.
Product Type:
The distribution of product types varies significantly across global markets, with some forms primarily serving domestic food processing and others dominating export-oriented trade flows.
- Soy Protein Isolate:Soy protein isolate is a highly refined form of soy protein, typically containing over 90% protein on a moisture-free basis, with minimal fat and carbohydrates. Demand concentrates in developed economies like the United States and Germany, driven by the need for high-purity protein in nutraceuticals and specialized infant formula.
- Whole Bean:Whole beans are raw, unprocessed non-GMO soybeans, harvested and cleaned, serving as the foundational input for further processing into various soy products. Global demand for whole beans is substantial, particularly for export to regions like Europe and Asia, where they are processed into food-grade ingredients and animal feed.
- Soy Flour:Soy flour is produced by grinding roasted non-GMO soybeans into a fine powder, enhancing protein content in baked goods and processed foods.
- Soy Oil:Non-GMO soy oil is extracted from whole beans, primarily used as a cooking oil and an ingredient in food manufacturing, valued for its neutral flavor profile.
Whole Bean holds the largest share; momentum sits with Soy Protein Isolate.
End Use Industry:
The end-use industries for non-GMO soybeans exhibit varied cost sensitivities and application focuses across the value chain.
- Food & Beverages:This segment encompasses the use of non-GMO soy in plant-based proteins, meat and dairy alternatives, and clean-label food formulations. Demand is intense in North America and Europe, driven by health-conscious consumers seeking verified non-GMO ingredients and sustainable food options.
- Animal Feed:Non-GMO soybeans and their derivatives, such as soy meal, are incorporated into feed formulations for livestock, poultry, and aquaculture. This industry remains a significant volume consumer globally, with increasing interest in non-GMO feed to meet specific consumer preferences in markets like Germany.
- Nutraceuticals:Non-GMO soy components, including isoflavones and protein isolates, are used in dietary supplements and functional foods for their health benefits.
- Personal Care:Soy-derived ingredients appear in personal care products like cosmetics and skincare, valued for their emollient and protein-rich properties.
This category is defined by the high-volume requirements of Animal Feed, contrasted with the premiumization opportunities in Nutraceuticals.
Distribution Channel:
The distribution channels for non-GMO soybeans reflect varying customer types and margin structures, from direct bulk sales to consumer-facing retail.
- Wholesale:Wholesale channels involve bulk sales of non-GMO soybeans and ingredients to large-scale food manufacturers, animal feed producers, and international traders. This channel is critical for economies of scale, particularly for agri-business giants like Archer-Daniels-Midland Company, ensuring efficient supply to industrial clients globally.
- Supermarkets:Supermarkets offer a range of non-GMO soy-based food products directly to consumers, including plant-based milks, tofu, and packaged meat alternatives. Consumer purchasing in developed economies, especially the United States and Germany, drives demand through this channel, emphasizing clean-label and wellness trends.
- Online Retail:E-commerce platforms provide direct-to-consumer access for niche non-GMO soy products and specialized ingredients, catering to specific dietary needs.
- Specialty Stores:These outlets, including health food stores, focus on premium, often multi-certified non-GMO soy products, appealing to discerning consumers.
The efficiency of Wholesale underpins market volume, while Supermarkets capture consumer-level value.
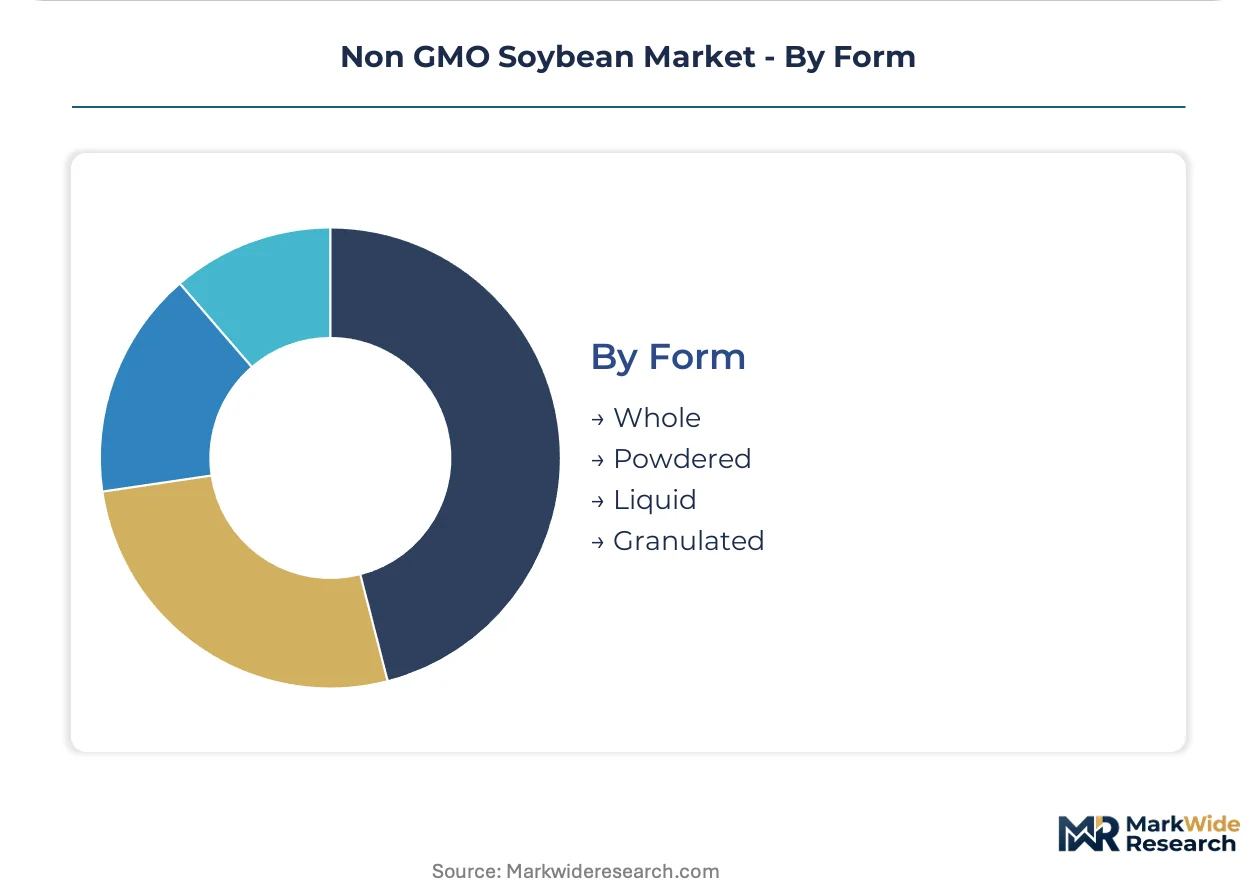
Form:
The various forms of non-GMO soybeans dictate their application versatility and processing requirements across diverse industries.
- Whole:Whole non-GMO soybeans are the unprocessed, intact beans used as raw material for crushing, milling, or direct culinary applications. This form is fundamental for initial processing into oil and meal, with significant demand from food manufacturers in Europe and Asia for plant-based ingredient production.
- Powdered:Powdered forms encompass products like soy flour, soy protein concentrates, and isolates, created through drying and milling processes. High demand exists in the nutraceuticals and sports nutrition sectors in North America, where these powders serve as essential protein sources and functional ingredients.
- Liquid:Liquid forms include soy milk and soy sauces, providing versatile dairy alternatives and savory flavor bases for global cuisine.
- Granulated:Granulated soy products, often textured soy protein, serve as meat extenders or substitutes in processed foods due to their fibrous texture.
The market exhibits a clear preference for Whole as a raw material, with significant growth in value-added Powdered applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the non-GMO soybean market, with some regions prioritizing cost efficiency while others readily pay premiums for verified purity. Developed economies demonstrate lower price sensitivity for specialized applications. Conversely, volume-driven markets often seek competitive pricing for feed and basic food ingredients.
United States
United States demand for non-GMO soybeans centers on plant-based proteins and clean-label food formulations. The USDA's National Bioengineered Food Disclosure Standard creates a clear incentive for non-GMO sourcing. Food processing hubs across the Midwest and California actively integrate these ingredients into consumer products.
Germany
German consumers drive demand for premium non-GMO soybeans, particularly in organic and health-focused food segments. The European Food Safety Authority's (EFSA) strict traceability requirements ensure market integrity. Major port cities like Hamburg serve as critical entry points for imported non-GMO feed and food ingredients.
Brazil
Brazilian producers are crucial for global non-GMO soybean supply, focusing on export markets with stringent purity standards. CTNBio's oversight defines the segregation protocols necessary for international trade. Agricultural regions in states like Mato Grosso and Paraná implement specialized cultivation practices for non-GMO varieties.
China
Chinese demand for non-GMO soybeans is growing, driven by food processing for traditional soy products and an expanding middle class. National food safety standards and import regulations influence sourcing decisions. Eastern coastal cities like Shanghai and Guangzhou are key centers for processing and consumption of non-GMO soy ingredients.
Japan
Japanese consumers value non-GMO soybeans for traditional foods such as tofu, miso, and soy sauce. The Ministry of Health, Labour and Welfare (MHLW) enforces specific food labeling standards. Urban centers like Tokyo and Osaka concentrate specialized food manufacturers and health-conscious consumers seeking verified non-GMO products.
Non GMO Soybean Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the non-GMO soybean market. The industry structure features a tiered landscape, encompassing large-scale agri-business corporations and specialized niche suppliers. Strategic archetypes include global commodity traders and boutique organic certifiers. Companies are increasingly pursuing portfolio diversification and expanding their logistics networks to capture market share.
Global agri-business giants, such as Archer-Daniels-Midland Company and Cargill, exemplify the scale-driven end of the supply chain, leveraging extensive logistics networks for non-GMO crop segregation and distribution. These corporations manage vast agricultural procurement and processing operations, serving multinational food manufacturers. In contrast, Clarkson Grain Company represents the specialized segment, differentiating through certified organic and transitional non-GMO soybean supply for niche markets. This company occupies a position focused on high-purity, often multi-certified, products catering to discerning buyers. These distinct player archetypes address varied market needs across the non-GMO soybean value chain.
| Leading Market Players |
|---|
| Archer-Daniels-Midland Company |
| Cargill |
| Grain Millers |
| Zeeland Farm Services |
| World Food Processing |
| Laura Soybeans |
| Sans |
| Divine Soya & Agro Food |
| Clarkson Grain Company |
| Others |
Cost & Logistics Intelligence
The European Food Safety Authority's (EFSA) strict GMO traceability requirements simultaneously gate non-GMO soybean supply qualification and drive price differentiation within the European market. This regulatory framework necessitates rigorous identity-preservation protocols throughout the entire supply chain.
Pricing Analysis
Extended contracts for verified non-GMO soybean supply, ensuring long-term ingredient consistency, represent a crucial value-add for food manufacturers. The dominant pricing model incorporates commodity spot prices for bulk volumes alongside contract-based long-term offtake agreements for specialized grades. Price differentiation stems from the stringent certification level, such as Non-GMO Project Verified status, and the high protein content required for nutraceutical applications. Pricing pressure originates from elevated identity-preservation costs and specialized logistics. Nutraceuticals and specialized infant formula sectors exhibit the lowest price sensitivity, while the animal feed industry remains highly cost-sensitive.
Supply Chain Analysis
Strategic stockpiles of identity-preserved non-GMO soybeans are essential for mitigating contamination risks and ensuring consistent supply to processors. Geographic supply concentration for non-GMO varieties centers on Brazil and the United States, with Europe serving as a key import and processing hub. The supply chain relies on high-purity non-GMO soybean seeds and specialized processing equipment. Co-mingling contamination risk during transport and storage presents a significant structural vulnerability. Distribution runs primarily through wholesale channels for large-scale food manufacturers and feed producers, complemented by specialty stores for consumer-facing products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non GMO Soybean Market is in an early-cycle expansion phase, driven by escalating plant-based protein demand across global food and beverage sectors.
For Market Incumbents:Fortify existing identity-preserved supply chains against co-mingling contamination risks, which threaten market integrity and premium claims. Invest in advanced genetic testing technologies like digital PCR to enhance purity verification at intake points. Expand dedicated logistics networks in key export regions like Brazil to ensure compliant segregation. Leverage certification investment to maintain competitive positioning against emerging specialized suppliers.
For New Entrants and Emerging Players:A service-layer gap exists in transparent, verifiable sourcing for multi-certified non-GMO soybeans. Target niche markets in Europe and North America that prioritize both non-GMO and organic or regenerative agriculture certifications. Penetrate the specialized infant formula and nutraceutical segments with high-purity soy protein isolates. Implement blockchain-enabled traceability solutions as a go-to-market differentiator, justifying premium pricing and building consumer trust.
For Investors and Strategic Acquirers:The USDA's National Bioengineered Food Disclosure Standard reshapes the acquisition landscape for non-GMO soybean assets, creating clear incentives for non-GMO sourcing. This market offers long-term viability as a sustainable protein source for a health-conscious consumer base. Target specialized processors or logistics providers with proven identity-preservation capabilities and established certification pathways. A significant signal to watch is the expansion of mandatory non-GMO labeling regimes into new, high-volume consumer markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Identity-Preserved Logistics | This ensures physical segregation of non-GMO crops from farm to processor, critical for purity standards. |
| Invest in dPCR Testing Technology | Advanced molecular diagnostics provide ultra-sensitive detection of GM presence, validating supplier declarations. |
| Develop Non-GMO Aquaculture Feed | Formulating specialized soy-based feeds offers a sustainable, protein-rich alternative to traditional fishmeal. |
| Integrate Blockchain Traceability | Immutable, farm-to-fork data enhances consumer trust and justifies premium pricing for certified supply. |
| Pursue Multi-Certification Bundling | Offering non-GMO, organic, and regenerative certifications appeals to discerning buyers in premium food segments. |
Research Approach
A spread of perspectives from agri-business executives, food manufacturers, and certification bodies converged on the working assumptions for the Non GMO Soybean Market. This involved combining primary interviews with industry stakeholders and secondary validation through USDA reports, EFSA publications, and industry association data. A robust triangulation approach integrated both bottom-up market sizing with top-down demand analysis.
Segmentation dimensions modeled include product type, end-use industry, distribution channel, form, and regional regulatory compliance for non-GMO soybeans. The analytical framework projects market trajectories across the analysis window, with CAGRs derived from historical growth rates and future demand projections. Key industry-specific forecast inputs included plant-based protein consumption trends and the evolving costs associated with non-GMO certification.
Underlying assumptions cover stable regulatory frameworks and consistent consumer demand, with deviation risk concentrated in unforeseen GM contamination events or sudden trade policy shifts. Forecasts reflect these documented assumptions. Revision becomes warranted when these regulatory or contamination thresholds are significantly crossed.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market