
 North America Online Gambling Market | 2026-2036
North America Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Online Gambling Market Outlook
Market Context
The United States is fragmenting across fifty distinct state regulatory regimes, each with divergent licensing timelines and tax structures. DraftKings Inc. leverages its daily fantasy sports heritage to secure early-mover positioning in newly opened jurisdictions. Flutter Entertainment PLC sustains cross-border operational scale through its FanDuel subsidiary, while MGM Resorts International anchors its digital footprint with integrated resort-brand loyalty conversion.
Technical Definition and Segment Structure
North America online gambling comprises digitally delivered wagering systems operating over secure TCP/IP networks with geolocation verification, KYC authentication, and real-time odds-engine processing for stakes placed on probabilistic outcomes. Sports betting dominates transaction velocity during NFL and NBA seasons, while slots generate sustained session frequency among casual gamers. Mobile device access captures the fastest-growing user cohort, whereas desktop retains higher average deposit values from VIP members. Cryptocurrencies emerge as a payment method where state banking restrictions limit conventional card processing.
Regulatory Framework
The Department of Justice Wire Act interpretation and state gaming commissions including the Nevada Gaming Control Board and New Jersey Division of Gaming Enforcement shape market access conditions and compliance costs. Ontario's Alcohol and Gaming Commission introduced Canada's first open competitive licensing regime, altering North American operator expectations. Stakeholders must monitor pending federal legislation and tribal compact renegotiations that could preempt or reinforce existing state architectures.
Market Dynamics
State-by-state legalization momentum in the United States fragments regulatory compliance costs while concentrating operator capital deployment into high-tax, high-barrier jurisdictions with first-mover advantages.
Growth Catalysts
- Mobile-first wagering infrastructure:Smartphone-native UX design captures millennial and Gen Z bettors who bypass desktop platforms entirely. Real-time push notifications and biometric login accelerate session frequency beyond legacy web interfaces.
- Ontario's open licensing regime:Canada's Alcohol and Gaming Commission of Ontario introduced competitive private-operator licensing, dismantling provincial monopoly structures and attracting cross-border platform investment.
- Live in-game betting engines:Micro-betting on individual plays during NFL and NBA broadcasts extends session duration and per-user deposit velocity through dynamic odds recalculation.
Market Restraints
- Payment processing friction:Federal banking restrictions under the Unlawful Internet Gambling Enforcement Act block conventional card networks, forcing reliance on costly ACH rails and cryptocurrency intermediaries with higher fraud exposure.
- Tax rate compression:New York and Pennsylvania impose effective tax rates exceeding 50% on gross gaming revenue, compressing operator margins below sustainable thresholds for market-making investment.
- Geolocation spoofing vulnerability:VPN and proxy server circumvention of state boundary verification creates regulatory enforcement liability and potential license revocation exposure.
Strategic Opportunities
- Tribal compact digital expansion:Class III gaming compact renegotiations in California and Florida open sovereign-nation mobile platforms with favorable tax treatment and exclusive market access.
- Esports wagering verticals:League of Legends and Counter-Strike competitions attract under-35 demographics with lower customer acquisition costs than traditional sports verticals.
- Cross-state liquidity pooling:Interstate poker networks under the Multi-State Internet Gaming Agreement aggregate player pools across Nevada, New Jersey, Delaware, and Michigan, improving tournament prize structures and rake economics.
Industry Challenges
- Responsible gaming algorithm deployment:Real-time behavioral analytics for problem-gambling detection require specialized data science talent scarce in gaming-adjacent labor markets.
- Legacy system API fragmentation:Acquired regional platforms operate on incompatible tech stacks, delaying unified wallet and loyalty program integration across state portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Online Gambling Market |
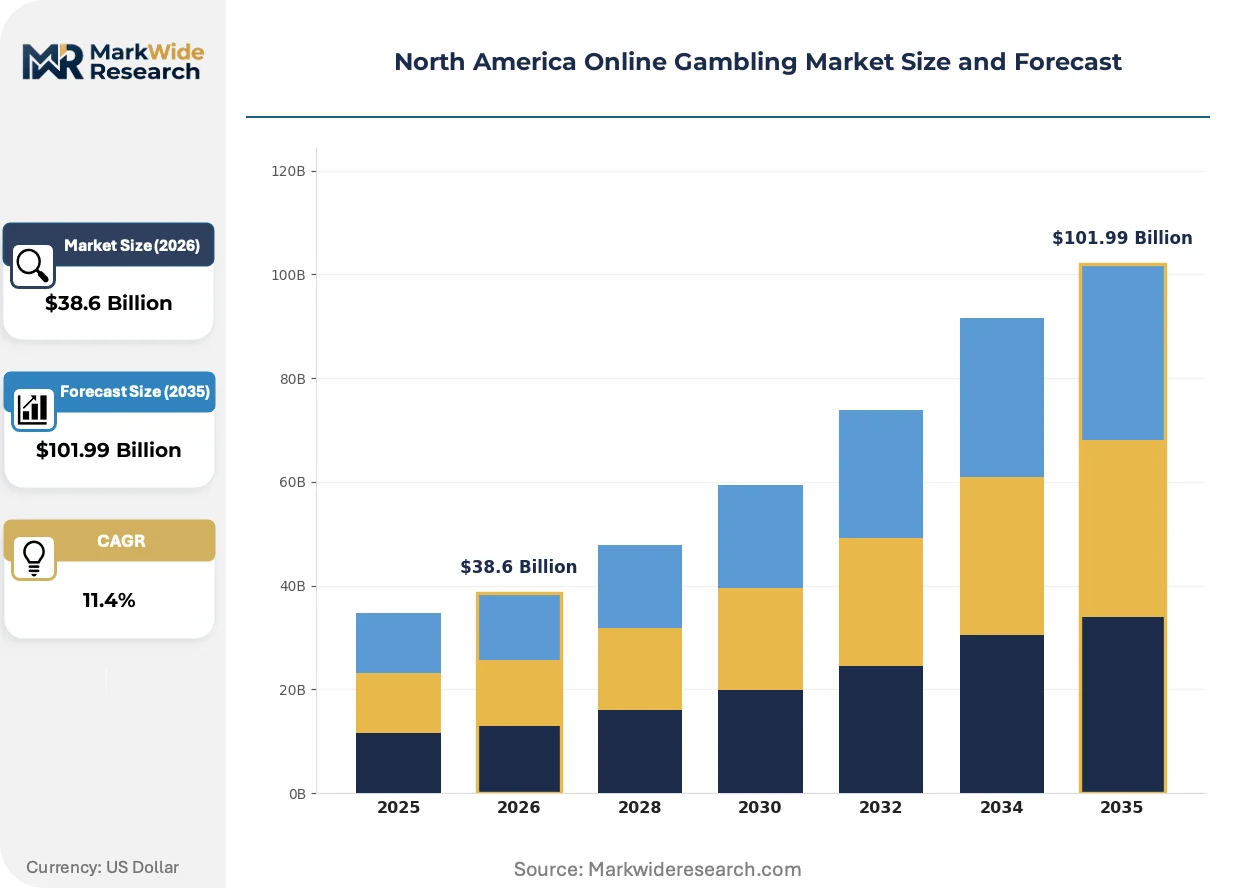
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Slots, Table Games, Sports Betting, Live Dealer Payment Method: Credit Cards, E-Wallets, Cryptocurrencies, Bank Transfers Device Type: Desktop, Mobile, Tablet, Smart TV Customer Segment: Casual Gamers, High Rollers, New Players, VIP Members |
| Companies Covered | DraftKings Inc., Caesars Entertainment, Inc., MGM Resorts International, Flutter Entertainment PLC, 888 Holdings PLC, bet365 Group Ltd., PENN Entertainment, Inc., Fanatics Sportsbook, Rush Street Interactive, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Online Gambling Market Strategic Shifts
Artificial intelligence and blockchain infrastructure are compressing settlement latency and personalizing risk management, while regulatory technology investments dominate capital allocation as compliance costs scale with jurisdictional fragmentation.
Machine learning-powered odds engines are rendering obsolete static pre-match linesetting. Tier-one sportsbooks deploy neural networks processing player injury reports, weather data, and social sentiment in sub-second intervals. In-play pricing precision now separates premium operators from commodity market-makers.
The Department of Justice's 2018 Wire Act reinterpretation enabled interstate wagering infrastructure while preserving state-level licensing authority. This federal-state tension forces platform architecture modularity. Operators now engineer state-specific compliance layers rather than unified national deployments.
Bettor acquisition patterns have compressed toward streaming-integrated wagering. Younger demographics place stakes through embedded Twitch and YouTube Sportsbook partnerships rather than standalone apps. This channel migration concentrates marketing spend with influencer networks and away from traditional affiliate SEO.
North America Online Gambling Market Segmentation
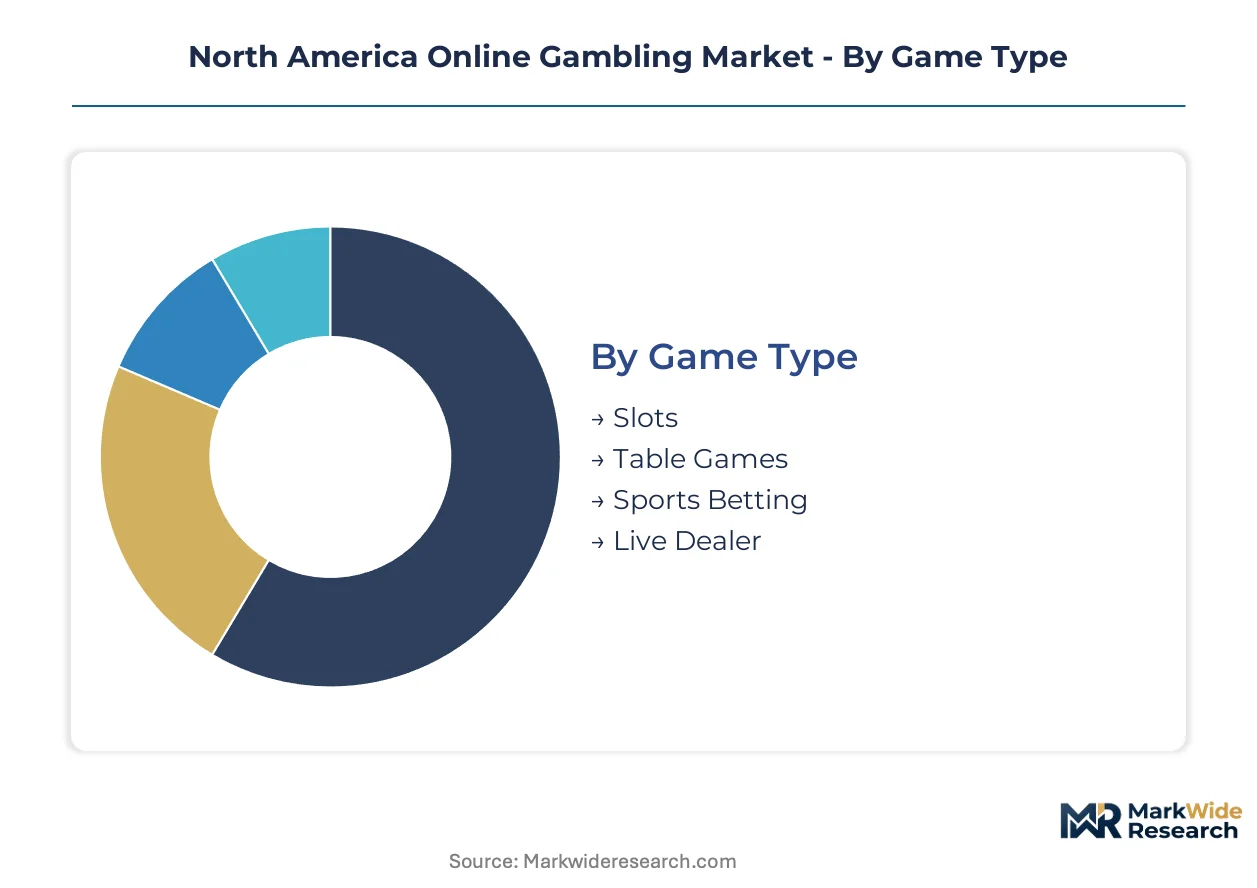
Segmentation in North American online gambling reveals divergent monetization profiles across wagering formats, payment rails, and player cohorts. Operators calibrate platform architecture, marketing spend, and compliance tooling to the specific technical and behavioral requirements of each slice.
Game Type:
Mature casino verticals coexist with emerging live-streamed formats, each demanding distinct latency tolerances and regulatory treatment.
- Sports Betting:Real-time odds engines process player prop, moneyline, and parlay stakes across NFL, NBA, and NHL seasons. Ontario's open licensing regime and New Jersey's established market infrastructure concentrate operator investment here, though New York's tax rate compression forces margin discipline.
- Slots:Random number generator algorithms power thousands of themed titles with return-to-player rates typically ranging 92-96%. Sustained session frequency among casual gamers in Michigan and Pennsylvania drives content licensing costs upward as exclusive studio partnerships become competitive differentiators.
- Table Games:Digital blackjack, roulette, and baccarat replicate house-edge mathematics with automated shuffling and bet-resolution protocols.
- Live Dealer:Video-streamed human croupiers operating from dedicated studios in Atlantic City, Las Vegas, and Toronto deliver immersive table experiences with higher minimum stakes.
Sports Betting retains volume leadership; Live Dealer holds the steepest expansion curve.
Payment Method:
Cost tier stratification separates legacy banking rails from high-friction alternatives, with significant jurisdictional variation in availability.
- E-Wallets:PayPal, Venmo, and Skrill integrations reduce deposit abandonment through one-tap authentication and instant balance reflection. Michigan and Ontario operators report highest adoption rates among millennial demographics seeking separation from primary bank statements.
- Credit Cards:Visa and Mastercard networks face blocking under federal banking restrictions, limiting availability to state-specific processor arrangements with elevated decline rates.
- Cryptocurrencies:Bitcoin and Ethereum settlements circumvent ACH delays where state banking restrictions apply, though volatility exposure and KYC complexity constrain mainstream penetration.
- Bank Transfers:ACH and wire rails remain the default for VIP deposit tiers above five-figure thresholds, with settlement latency of 1-3 business days accepted by high-value players prioritizing security over speed.
E-Wallets dominate transaction velocity; Cryptocurrencies are climbing the fastest among under-35 cohorts in banking-restricted states.
Device Type:
Customer type mapping reveals divergent session value profiles across screen formats, with mobile-native design now table stakes for acquisition.
- Mobile:Smartphone-native UX with biometric login and geolocation verification captures millennial and Gen Z bettors who bypass desktop entirely. Push notification-driven live betting during NFL broadcasts extends session duration in New Jersey and Illinois.
- Desktop:Larger screen real estate supports multi-table poker and complex parlay construction, retaining higher average deposit values from VIP members and serious sports handicappers.
- Tablet:Hybrid portability appeals to casual casino players seeking immersive slots graphics without mobile phone battery constraints.
- Smart TV:Emerging integration with streaming sports broadcasts enables second-screen wagering through voice and remote control interfaces, currently piloted in Nevada and Ontario test markets.
Mobile commands session frequency leadership; Smart TV represents the steepest expansion trajectory as streaming-integrated wagering matures.
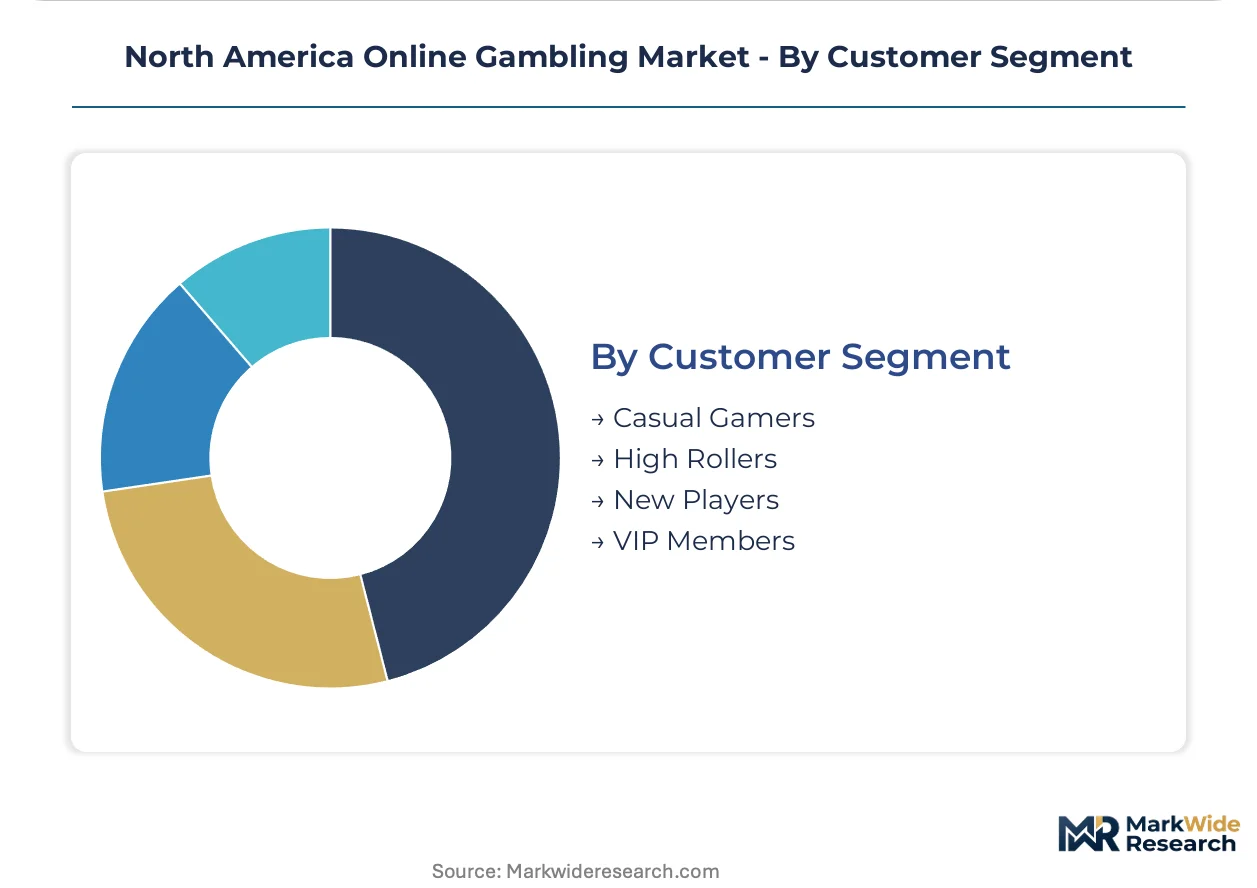
Customer Segment:
Margin structure varies dramatically across player lifetime value tiers, requiring differentiated retention economics and responsible gaming protocols.
- Casual Gamers:Low-stakes slots and occasional sports parlay players generate volume through micro-deposits and promotional bonus activation. Ontario's competitive market sees highest concentration here due to aggressive new-player incentive structures.
- VIP Members:Assigned account managers, expedited withdrawals, and exclusive event access sustain six-figure annual deposit levels. Nevada and Atlantic City integrated resorts leverage physical property amenities for digital loyalty conversion.
- High Rollers:Table game specialists and high-limit sports bettors demanding custom limits and loss-rebate negotiations.
- New Players:First-time depositors acquired through influencer partnerships and streaming-embedded sign-up flows, with cohort profitability hinging on second-deposit conversion rates.
Casual Gamers retain volume leadership; New Players hold the steepest expansion curve as legalization opens fresh state markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border fiber optic infrastructure linking Toronto, New York, and Chicago data centers underwrites North America's role as a high-frequency wagering corridor. Interstate banking networks and tribal sovereign connectivity extend this digital backbone into fragmented regulatory territories.
United States
Mobile sports betting adoption concentrates in New Jersey and Illinois where geolocation verification infrastructure matured earliest. The Department of Justice Wire Act interpretation and state gaming commissions including the Nevada Gaming Control Board shape licensing timelines. New York City's media density attracts operator headquarters despite tax rate compression exceeding fifty percent on gross gaming revenue.
Canada
Ontario's Alcohol and Gaming Commission introduced competitive private-operator licensing, dismantling provincial monopoly structures. Federal banking regulations through the Financial Consumer Agency of Canada enable streamlined payment processing unavailable in U.S. jurisdictions. Toronto's technology corridor hosts platform development centers serving both domestic and cross-border deployments.
Mexico
Regulatory liberalization under the Federal Gaming and Raffles Law permits limited online sports wagering through federally licensed operators. The Secretariat of the Interior (SEGOB) oversees concession allocations with stricter advertising controls than U.S. counterparts. Mexico City's metropolitan density represents the primary addressable market for Spanish-language platform localization.
North America Online Gambling Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying odds engines, KYC verification modules, and geolocation services. The vendor base stratifies across three tiers: daily fantasy heritage operators with first-mover state access, integrated resort conglomerates leveraging physical property loyalty, and European-headquartered specialists importing cross-jurisdictional technology. Dominant competitive moves include state-by-state license acquisition racing and tribal compact renegotiation for sovereign-nation mobile access.
Within the daily fantasy heritage tier, DraftKings Inc. and FanDuel (Flutter Entertainment PLC) exemplify early-mover positioning secured through pre-legalization user base conversion. MGM Resorts International anchors the integrated resort vector, converting physical property loyalty into digital wallet adoption. European specialists including 888 Holdings PLC and bet365 Group Ltd. occupy positions defined by cross-border technology transfer and Ontario market penetration.
| Leading Market Players |
|---|
| DraftKings Inc. |
| Caesars Entertainment, Inc. |
| MGM Resorts International |
| Flutter Entertainment PLC |
| 888 Holdings PLC |
| bet365 Group Ltd. |
| PENN Entertainment, Inc. |
| Fanatics Sportsbook |
| Rush Street Interactive |
| Others |
Value Chain & Pricing Dynamics
Geolocation spoofing vulnerability determines both margin compression thresholds and platform architecture investment cycles across state-licensed operators. Tax rate differentials exceeding fifty percentage points between New York and Nevada force tiered revenue-share negotiations with technology vendors, while payment processing friction elevates cryptocurrency settlement costs in banking-restricted jurisdictions.
Pricing Analysis
Volume-discount tiering structures separate VIP account management packages from standard self-service platforms. Pricing stratifies across premium white-label solutions, standard turnkey integrations, and economy API-only modules based on customization depth and regulatory coverage breadth. Cost compression in the economy tier intensifies because ACH rail intermediaries extract elevated transaction fees under federal banking restrictions. Casual gamers exhibit highest price sensitivity to deposit minimums, whereas VIP members prioritize withdrawal velocity over fee transparency.
Supply Chain Analysis
Upstream feedstock for odds-engine technology draws from Israel, Malta, and the United Kingdom, where specialized quantitative development clusters concentrate algorithmic talent. KYC verification modules and geolocation authentication services rest on Estonian digital identity infrastructure and Irish data center capacity. Single-source vulnerability concentrates in Nevada-based live dealer studio operations serving multiple state jurisdictions. Distribution runs through platform integrators who bundle component licensing with compliance overlay management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America online gambling market sits in a cyclical recovery phase driven by state legalization waves cresting through California and Florida tribal compact negotiations.
For Market Incumbents: Insulate margin structures through backward integration into proprietary odds-engine development, reducing third-party licensing exposure. Secure exclusive tribal compact access in sovereign-nation territories before competitor saturation erodes first-mover economics. Vertical control over KYC verification technology buffers against regulatory chokepoint vulnerability. For New Entrants and Emerging Players: Pursue esports wagering verticals where customer acquisition costs trail traditional sports betting by substantial margins. Target Ontario's competitive licensing regime for platform proof-of-concept before U.S. state-by-state expansion. Embedded Twitch partnership channels offer the most penetrable go-to-market angle for under-35 demographic capture. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors daily-fantasy-heritage operators with established state access pipelines. Long-term viability hinges on cross-state liquidity pooling infrastructure under Multi-State Internet Gaming Agreement frameworks. Acquisition targets should demonstrate tribal compact negotiation capabilities or proprietary responsible gaming algorithm deployment. The signal to watch is federal Wire Act reinterpretation momentum that could preempt existing state architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Tribal Compact Digital Expansion | Sovereign-nation mobile platforms in California and Florida secure favorable tax treatment unavailable to state-licensed competitors. |
| Cross-State Liquidity Pooling | Interstate poker networks under MSIGA aggregation improve tournament economics across Nevada, New Jersey, Delaware, and Michigan. |
| Esports Wagering Vertical Launch | League of Legends and Counter-Strike competitions attract under-35 demographics with superior lifetime value metrics. |
| Streaming-Integrated Platform Development | Embedded Twitch and YouTube Sportsbook partnerships concentrate marketing spend away from saturated affiliate SEO channels. |
| Responsible Gaming Algorithm Investment | Real-time behavioral analytics deployment addresses regulatory enforcement liability and license revocation exposure. |
Study Parameters
Desk research of state gaming commission licensing databases, tribal compact filings, and federal Wire Act interpretation precedents preceded structured interviews with platform engineering directors, regulatory compliance officers, tribal gaming authority negotiators, and payment processing specialists. Secondary validation drew from SEC 10-K disclosures, state revenue reporting systems, and Ontario's Alcohol and Gaming Commission public registry. Bottom-up state-by-state market sizing triangulated against top-down North American aggregate demand estimates.
Assumptions held fixed across the modeling period include existing state tax rate structures and federal banking restriction enforcement intensity; variables tested encompass tribal compact renegotiation timelines and cryptocurrency payment adoption curves. Segmentation dimensions modeled span game type, payment method, device type, and customer segment alongside jurisdictional regulatory cluster. CAGRs derived from historical legalization velocity patterns and per-capita deposit benchmarks. Forecast inputs incorporated mobile penetration rates and streaming platform partnership density.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and interest rate environments would shift the trajectory. Forecasts reflect documented assumptions regarding state legislative session calendars and Department of Justice enforcement posture. Quarterly review of tribal compact negotiation progress and federal preemption legislative activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Online Gambling Market
Digital Media
Asia-Pacific Inflight Entertainment and Connectivity Market
Digital Media
Media Gateway Market
Digital Media
United States Sports Betting Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Pro AV Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Social TV Market
Digital Media
Asia Pacific Photography Service Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Asia-Pacific Animation Market
Digital Media
Wedding Photography Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
3D Animation Market
Digital Media
Middle East Gaming Market
Digital Media
Multichannel Network Market