
 Asia-Pacific Animation Market | 2026-2036
Asia-Pacific Animation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Animation Market Outlook
Subscription bundling of animation libraries with gaming and music services is pivoting how consumers discover and pay for content across the Asia-Pacific region. Toei Animation leverages its decades-long franchise ownership to sustain recurring revenue through theatrical and streaming windows. Tencent anchors its animation strategy through vertical control over distribution platforms and IP monetization. Studio Ghibli differentiates through a premium positioning that commands theatrical exclusivity before any digital release.
Asia-Pacific animation encompasses the production, post-production, and distribution of motion content created through frame-by-frame manipulation of two-dimensional artwork, three-dimensional digital models, stop-motion puppets, or motion graphics software, typically rendered at 24 frames per second for cinematic exhibition and delivered via digital cinema packages or streaming codecs. The primary commercial purpose spans entertainment consumption, brand communication, educational content, and interactive media integration. 3D animation now leads production value due to its scalability across film, television, and video game pipelines, while motion graphics captures the fastest expansion as corporations and advertisers shift budgets toward short-form digital content. Stop motion retains niche premium positioning where tactile aesthetic distinction justifies higher per-minute production costs.
Japan's METI oversees content industry promotion frameworks that directly subsidize animation export capacity, while South Korea's MFDS and cultural ministry coordinate digital content tax credits that shape studio location decisions. China's NMPA and SAMR enforce content review standards that determine which productions receive theatrical or streaming distribution licenses. Stakeholders must monitor how divergent content approval timelines and subsidy eligibility rules across these regulators affect co-production structuring and IP ownership terms.
Market Dynamics
Streaming platform commissioning power is restructuring production economics across the Asia-Pacific animation sector, shifting risk from studios to distributors and compressing traditional theatrical windowing models.
Growth Catalysts
- Japan's METI Content Export Framework:Direct subsidies for international distribution rights acquisition are lowering market entry barriers for regional studios seeking offshore audiences.
- Real-time rendering engines:Unreal Engine and Unity pipelines are collapsing production timelines for 3D episodic content, enabling weekly delivery schedules previously impossible.
- Southeast Asian co-production treaties:Singapore, Thailand, and Vietnam have established bilateral IP ownership structures that split regulatory compliance burdens across jurisdictions.
Market Restraints
- Rendering compute cost volatility:Cloud GPU pricing fluctuations from AWS, Azure, and Alibaba Cloud are destabilizing project budgeting for mid-sized studios.
- Seoul-Incheon cluster concentration:Over 60% of premium 3D post-production capacity sits within 50 kilometers, creating single-point-of-failure exposure for international clients.
- China's NMPA content review queues:Approval timelines stretching 8-14 months are freezing capital in completed productions awaiting distribution licenses.
Strategic Opportunities
- India's domestic streaming subscriber base:JioCinema and Disney+ Hotstar are commissioning original animated features for underpenetrated tier-2 and tier-3 city audiences.
- South Korea's MFDS digital content tax credits:30% production cost offsets for VFX and animation are attracting Japanese and Chinese co-production investment.
- Motion graphics-advertising convergence:Short-form branded content for TikTok and Instagram Reels is opening new revenue streams outside traditional entertainment licensing.
Industry Challenges
- Real-time technical artist scarcity:Pipeline engineers capable of Unreal Engine optimization command 3-4x standard animator salaries, constraining studio expansion.
- Cross-border IP licensing complexity:Divergent work-for-hire doctrines across Japan, South Korea, and China are generating ownership disputes in co-financed productions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Animation Market |
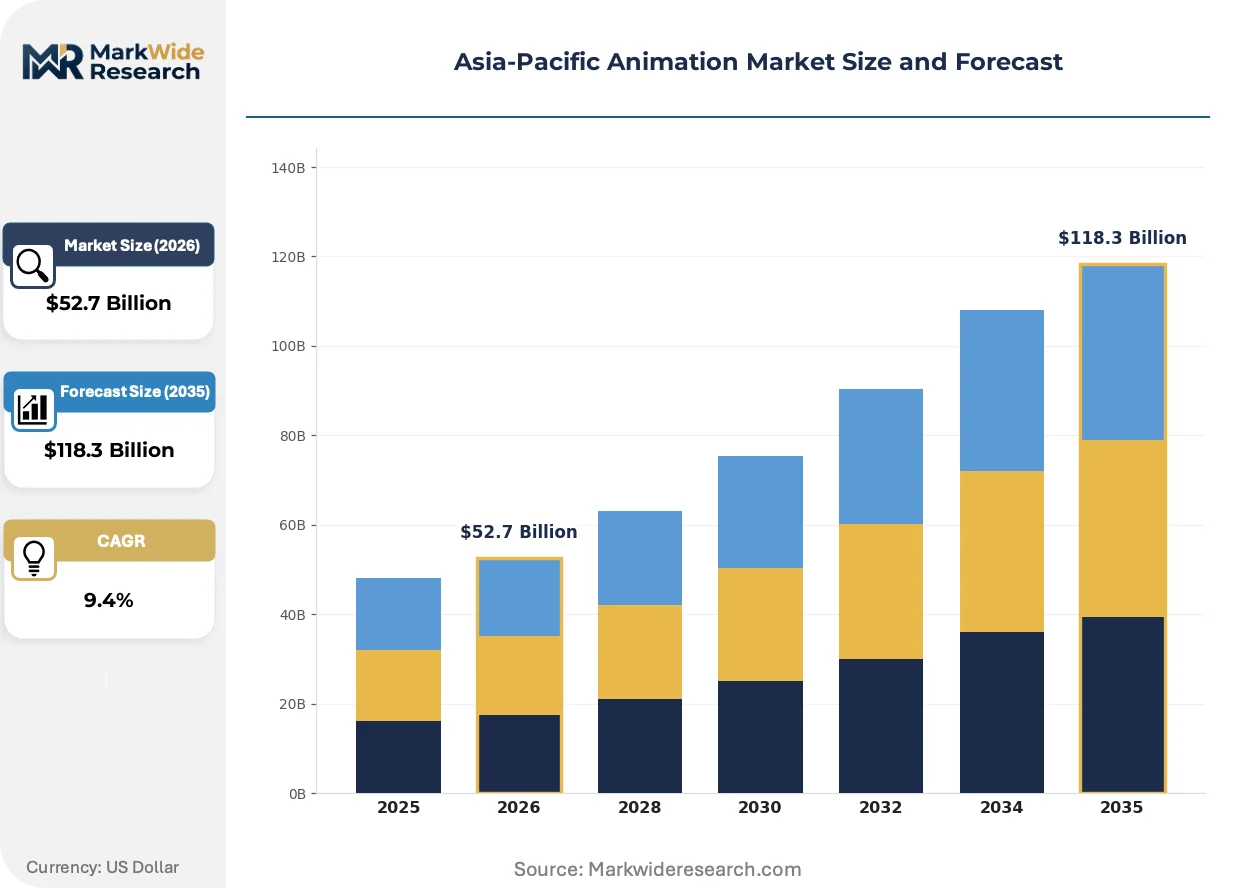
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $118.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Animation, 3D Animation, Stop Motion, Motion Graphics Application: Film Production, Television Series, Video Games, Advertising End User: Studios, Educational Institutions, Corporations, Freelancers Distribution Channel: Online Platforms, Television, Theatrical Releases, Merchandising |
| Companies Covered | DeeDee Animation Studio, ONE ANIMATION, Toei Animation, Studio Mir, Bandai Namco Filmworks, Studio Ghibli, WAU Animation, Tencent, Production I.G, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Animation Market Strategic Shifts
Generative AI tooling is penetrating production pipelines faster than regulatory frameworks can adapt, forcing studios to restructure creative workflows around human-machine collaboration rather than replacement.
AI-assisted inbetweening and background generation is modularizing the traditional 2D animation pipeline. Mid-tier studios in Bangkok and Ho Chi Minh City are adopting these tools to compete on volume with established Japanese incumbents. Labor arbitrage advantages are compressing as automation standardizes output quality across geographies.
South Korea's cultural ministry has expanded MFDS digital content tax credits to include AI-assisted production equipment depreciation. Studios in Seoul are restructuring capital expenditure plans to maximize subsidy capture. The policy is accelerating technology adoption timelines beyond what market incentives alone would drive.
Subscription bundling across Disney+ Hotstar, Netflix, and regional platforms is fragmenting content discovery. Indian audiences increasingly encounter animation through gaming-music-entertainment packages rather than dedicated browsing. Studios must now optimize for algorithmic recommendation systems rather than traditional marketing campaigns.
Asia-Pacific Animation Market Segmentation
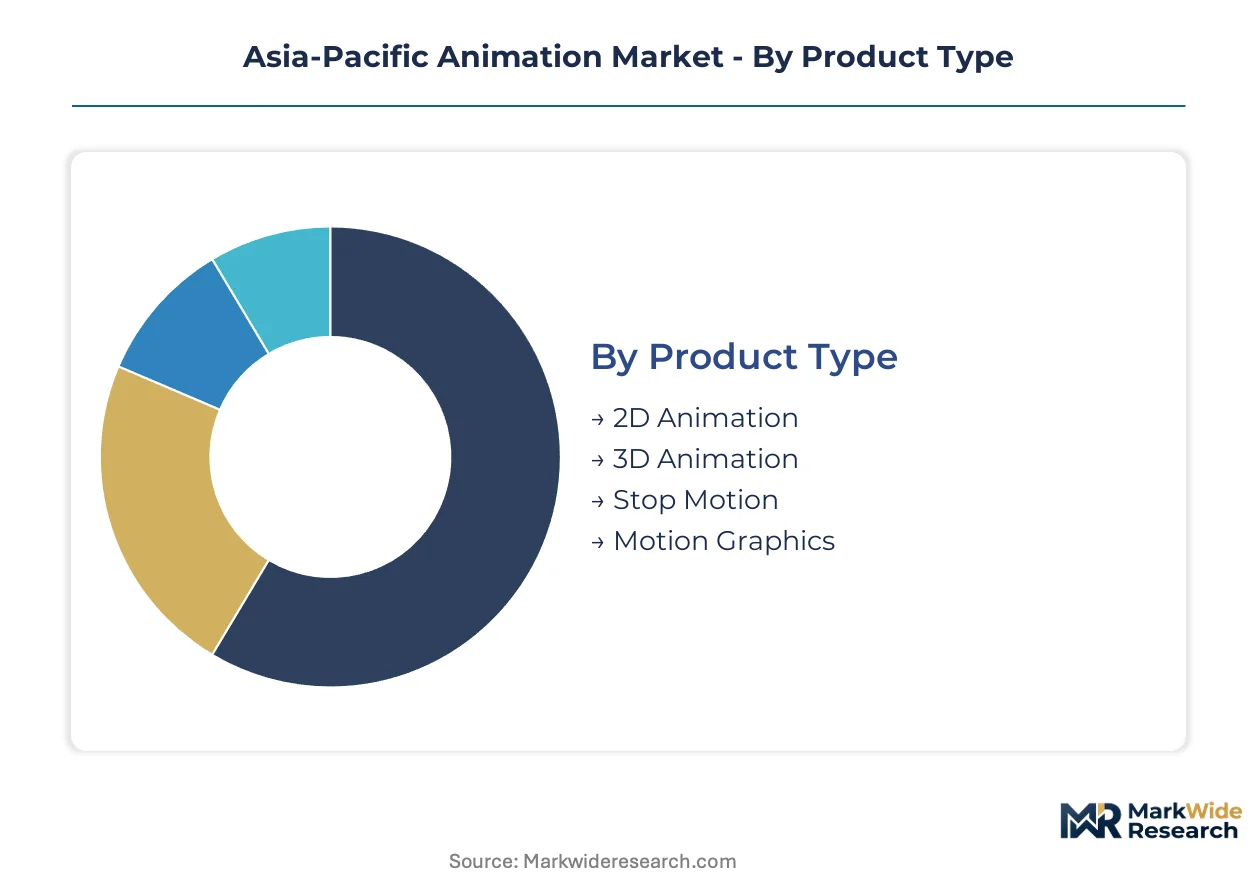
Production technology choices in Asia-Pacific animation carry decade-long infrastructure commitments. Studios selecting between 2D and 3D pipelines lock in talent bases, software licensing, and co-production partnerships that resist rapid reconfiguration. Segmentation reveals how these technical divides map onto revenue stability versus growth potential.
Product Type:
Upgrade cycles for rendering hardware and software licenses drive replacement decisions every 3-5 years, pushing studios toward formats with scalable toolchains.
- 3D Animation:Digital model-based production utilizing rigged characters and environmental assets rendered through real-time engines. Japanese studios service Netflix and Crunchyroll contracts; South Korean facilities handle Tencent and NetEase game cinematics. Pipeline standardization across Unreal Engine and Maya enables labor mobility between film and interactive projects.
- 2D Animation:Frame-by-frame illustration pipelines relying on vector-based software and AI-assisted inbetweening. Philippine and Vietnamese studios compete for Disney+ and HBO Max series work through cost-advantaged digitized cel workflows. Talent retention challenges intensify as senior animators migrate to 3D or gaming roles.
- Stop Motion:Physical puppet fabrication with tactile material aesthetics.
- Motion Graphics:Vector-based animated typography and logo treatments for commercial clients.
Volume placements concentrate in 3D Animation; the faster expansion belongs to Motion Graphics.
Application:
Customer procurement patterns separate long-form content investments from campaign-based advertising spend with distinct margin profiles.
- Television Series:Episodic content production for streaming platform commissioning cycles. Indian studios supply JioCinema and Disney+ Hotstar with regionally localized originals. Season renewal dependencies create revenue predictability but limit pricing power.
- Film Production:Theatrical and direct-to-streaming feature animation with 90-120 minute formats. Japanese theatrical windows sustain Toei and Toho distribution economics; Chinese NMPA licensing queues tie up capital for 8-14 months post-completion.
- Video Games:Real-time cinematics and in-engine character animation.
- Advertising:Branded short-form content for digital platforms.
Revenue stability clusters in Television Series; steepest expansion trajectory appears in Advertising.
End User:
Organizational scale determines access to tax incentives, co-production treaties, and platform direct relationships.
- Studios:Incorporated production entities with permanent staff and facility leases. Seoul-Incheon cluster houses 60% of premium 3D post-production capacity for international clients. South Korea's MFDS tax credits offset 30% of VFX and animation costs for qualifying facilities.
- Corporations:In-house brand content teams and agency-affiliated production units. Motion graphics demand from TikTok and Instagram Reels campaigns drives procurement of short-turnaround animation services.
- Educational Institutions:Training programs and curriculum development.
- Freelancers:Independent contractors on project-based engagements.
Contract value aggregates at Studios; the fastest share gain belongs to Corporations.
Distribution Channel:
Windowing strategies fragment across platform types with divergent exclusivity requirements and revenue share terms.
- Online Platforms:Subscription streaming and ad-supported digital distribution. Netflix, Disney+ Hotstar, and regional services commission originals for India, Southeast Asia, and Australia. Algorithmic recommendation systems displace traditional marketing for content discovery.
- Theatrical Releases:Cinema exhibition with exclusive windowing before digital availability. Studio Ghibli and Toei Animation sustain premium positioning through controlled release sequencing. Japanese box office concentration supports higher per-ticket pricing than regional markets.
- Television:Linear broadcast and cable carriage.
- Merchandising:Licensed character products and IP derivatives.
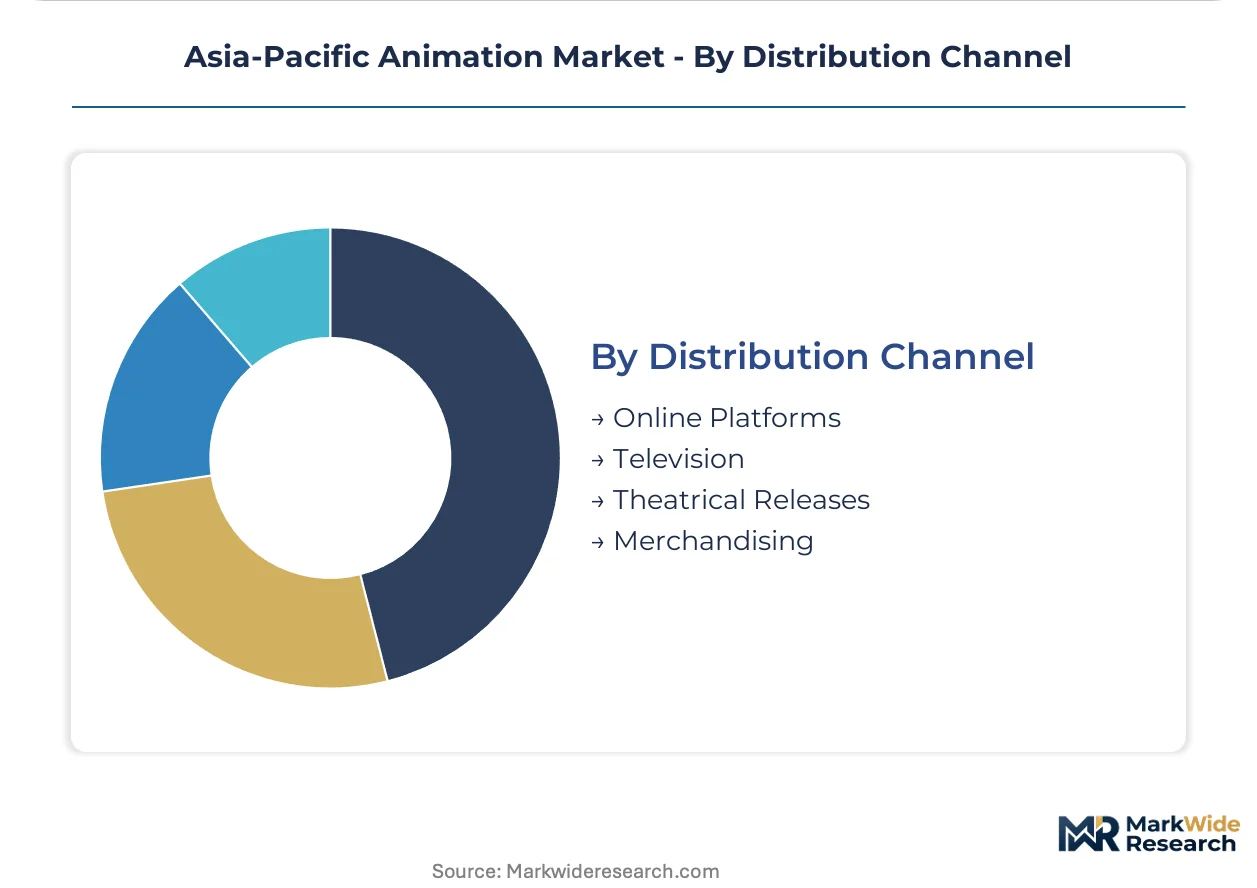
Commissioning power concentrates in Online Platforms; margin expansion favors Theatrical Releases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Seoul-Incheon special economic zone anchors premium 3D post-production capacity through MFDS tax credits offsetting 30% of animation costs. This incentive architecture has concentrated international commissioning power within a 50-kilometer radius.
Japan
Tokyo's Kanto region houses Toei Animation and Studio Ghibli, sustaining theatrical windowing economics through franchise ownership and premium positioning. METI's content export framework subsidizes international distribution rights acquisition for regional studios. The cluster dominates episodic production for Netflix and Crunchyroll through decades-long IP library control.
China
Tencent anchors vertical platform-distribution integration across Shenzhen and Beijing production facilities. NMPA content review queues stretching 8-14 months freeze capital in completed theatrical productions awaiting distribution licenses. The Yangtze River Delta cluster services NetEase and domestic streaming platform cinematics demand.
India
Mumbai and Bangalore studios supply JioCinema and Disney+ Hotstar with original animated features targeting tier-2 and tier-3 city subscriber expansion. Domestic facilities now service major international streaming contracts through cost-advantaged digitized workflows. Government production-linked incentives for digital content are accelerating facility expansion.
South Korea
Seoul's MFDS digital content tax credits attract Japanese and Chinese co-production investment into the Incheon cluster. Over 60% of premium 3D post-production capacity sits within 50 kilometers, creating single-point-of-failure exposure for international clients. Real-time rendering pipelines through Unreal Engine dominate game cinematics for Tencent and NetEase.
Southeast Asia
Bangkok and Ho Chi Minh City mid-tier studios adopt AI-assisted inbetweening to compete on volume with Japanese incumbents. Singapore, Thailand, and Vietnam bilateral IP ownership treaties split regulatory compliance burdens across jurisdictions. Labor arbitrage advantages compress as automation standardizes output quality.
Asia-Pacific Animation Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific animation sector. Market structure tilts toward consolidation among platform-integrated entities while mid-tier studios fragment across cost-driven geographies. Three archetypes dominate: vertically integrated platform owners, franchise-dependent theatrical specialists, and volume-oriented service studios. Competitive moves center on co-production treaty exploitation and real-time pipeline technology licensing.
Among Japan-based franchise holders, Toei Animation and Studio Ghibli exemplify theatrical-windowing specialists commanding premium positioning through controlled release sequencing. Tencent occupies the platform-integrated archetype through distribution infrastructure and IP monetization verticals. These entities represent divergent strategic paths: one sustaining recurring revenue through decades-long IP ownership, the other anchoring market power through captive distribution channels.
| Leading Market Players |
|---|
| DeeDee Animation Studio |
| ONE ANIMATION |
| Toei Animation |
| Studio Mir |
| Bandai Namco Filmworks |
| Studio Ghibli |
| WAU Animation |
| Tencent |
| Production I.G |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in South Korea and family-owned mid-caps in Japan anchor supply discipline through MFDS tax credit capture and decades-long franchise retention, creating pricing power asymmetries that favor vertically integrated platform owners over pure-play service studios.
Pricing Analysis
Cost-down pressure on mid-tier episodic work accelerates because AI-assisted inbetweening tools from Bangkok and Ho Chi Minh City studios compress labor arbitrage premiums. Project-based per-minute pricing dominates commissioning contracts, with differentiation hinging on real-time engine capability and NMPA pre-approval status. Indian facilities serving JioCinema and Disney+ Hotstar face acute sensitivity to volume discounts, while Toei Animation and Studio Ghibli command theatrical window premiums that insulate against streaming price erosion.
Supply Chain Analysis
Cloud GPU provisioning rests on AWS, Azure, and Alibaba Cloud data centers across Singapore, Tokyo, and Seoul, with rendering compute feeding from NVIDIA hardware allocations and Unreal Engine pipeline licenses. Single-point vulnerability concentrates in the Seoul-Incheon corridor where over sixty percent of premium 3D post-production capacity clusters within fifty kilometers. Distribution runs through platform-direct commissioning relationships that displace traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time rendering engines are displacing legacy Maya-based pipelines, restructuring talent requirements and capital deployment timelines across production facilities.
For Market Incumbents: Anticipate margin compression from AI-assisted studios in Southeast Asia by deepening captive distribution relationships with Netflix and Crunchyroll. Secure Unreal Engine technical artist pipelines through Seoul-Incheon cluster partnerships before wage premiums render expansion uneconomical. For New Entrants and Emerging Players: Streaming platform commissioning departments represent the most penetrable channel partner type for volume-oriented studios. Target Disney+ Hotstar's tier-2 and tier-3 Indian original slate through cost-advantaged digitized 2D workflows. Position motion graphics capabilities for TikTok and Instagram Reels branded content procurement. For Investors and Strategic Acquirers: MFDS tax credit expansion to include AI-assisted production equipment is the leading indicator that Seoul-based facility valuations will decouple from pure labor-cost metrics. Prioritize acquisition targets with locked platform commissioning relationships and depreciable technology asset bases. Watch for NMPA queue clearance acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Pipeline Adoption | Unreal Engine integration collapses episodic delivery timelines for Netflix and Crunchyroll commissions. |
| Co-Production Treaty Structuring | Singapore-Thailand-Vietnam bilateral IP splits reduce NMPA and SAMR compliance burdens for Chinese partners. |
| Tax Credit Optimization | MFDS digital content offsets attract Japanese and Chinese investment into Seoul-Incheon facilities. |
| Platform-Direct Commissioning | Disney+ Hotstar and JioCinema relationships displace traditional distributor intermediaries in India. |
| AI-Assisted Workflow Integration | Mid-tier Bangkok and Ho Chi Minh City studios compete on volume with established Japanese incumbents. |
Study Parameters
Multi-period observation of streaming commissioning volumes, tax credit utilization rates, and platform subscriber expansion anchored the trend analysis, supplemented by interviews with animation studio executives, platform content acquisition leads, post-production facility managers, and regulatory affairs specialists across Japan's METI, South Korea's MFDS, and China's NMPA. Secondary validation drew from SEC filings of platform-integrated conglomerates, customs data on rendering hardware imports, and production incentive disclosure databases. Bottom-up facility capacity modeling and top-down platform content spend estimates were triangulated.
Input-output matrices structured the analytical framework across production technology type, application format, end-user scale, and distribution channel exclusivity terms throughout the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market boundary conditions. Forecast inputs incorporated real-time engine adoption curves and regulatory approval timeline distributions.
Several conditions sit outside the modeled scope, including geopolitical disruption to co-production treaty enforcement and unanticipated generative AI regulatory frameworks. Forecasts reflect stated assumptions on platform commissioning growth and tax credit continuity. A small set of named triggers warrants ongoing watch: NMPA queue clearance rates, Seoul-Incheon cluster concentration events, and cloud GPU pricing volatility from hyperscaler capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
3D Animation Market
Digital Media
Digital Distribution Market
Digital Media
Japan Webtoons Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
Africa Animation Market
Digital Media
Digital Music Content Market
Digital Media
Visual Effects (VFX) Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
In Flight Entertainment Market
Digital Media
Online Gambling Market
Digital Media
Projection Mapping Market
Digital Media
VFX Market
Digital Media
Stock Photography Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Latin America Inflight Entertainment and Connectivity Market
Digital Media
Digital Entertainment in the Home Market