
 Wedding Photography Market | 2026-2036
Wedding Photography Market Size, Share, and Industry Trends Forecast 2026-2036
Wedding Photography Market Analytics
India's metropolitan wedding corridors is rewriting competitive dynamics for photography studios. George Street Photo & Video leverages franchise-based coverage across multiple U.S. states. Jose Villa anchors the fine art segment through film-based aesthetic specialization. Norman & Blake competes on editorial-style destination wedding coverage.
Wedding photography encompasses professional image capture, post-production editing, and curated delivery of visual narratives documenting marriage ceremonies and associated celebrations, typically employing full-frame digital cameras with low-light sensors, RAW workflow processing, and color-grading suites calibrated for skin-tone accuracy. The primary commercial purpose centers on producing permanent, emotionally resonant visual records for couples while generating recurring referral revenue through vendor network relationships. Documentary photography commands premium pricing due to its unposed authenticity and extended event-hour requirements. Digital albums dominate delivery mode volume, though printed albums retain margin concentration among luxury package tiers. Custom packages represent the fastest-growing package size category as couples reject standardized offerings.
ISO certification requirements for digital asset management and color workflow consistency shape studio operational standards, while GDPR compliance in Europe imposes strict client data handling protocols for online gallery platforms. The U.S. Federal Trade Commission's truth-in-advertising guidelines govern portfolio representation and package pricing disclosures. Stakeholders must monitor how generative AI tools for image enhancement and automated editing reshape labor models and client expectations around turnaround speed.
Market Dynamics
Social media platform algorithm shifts toward video-first content are compressing traditional still-image delivery timelines and forcing studios to restructure post-production workflows around motion assets.
Growth Catalysts
- Destination wedding planners:This buyer segment is expanding adoption of multi-day coverage packages across international locations, driving demand for travel-ready production crews.
- GDPR compliance frameworks:European online gallery platforms are investing in client data handling infrastructure that enables premium-tier service differentiation.
- Film-based aesthetic specialization:Fine art photographers are commanding premium pricing through chemical-process workflows that signal craft authenticity.
Market Restraints
- Full-frame sensor supply concentration:Japanese and German optical component manufacturers control critical CMOS fabrication capacity, creating equipment procurement bottlenecks.
- Generative AI substitution threat:Automated image enhancement tools are compressing turnaround expectations and eroding traditional editing labor value.
- RAW workflow storage costs:High-resolution capture requirements impose escalating cloud infrastructure and local server capital burdens on independent studios.
Strategic Opportunities
- India's metropolitan wedding corridors:Mumbai, Delhi, and Bangalore clusters show concentrated demand for documentary-style coverage with unposed authenticity positioning.
- Printed album margin concentration:Luxury package tiers retain physical product differentiation as digital delivery becomes commoditized.
- ISO 9001 certification tailwinds:Studios achieving digital asset management standardization are winning corporate hospitality and hotel chain contracts.
Industry Challenges
- Color-grading suite calibration expertise:Skin-tone accuracy workflows require specialized post-production talent that remains scarce outside major metropolitan markets.
- Vendor network referral system integration:Studios struggle to maintain reciprocal relationships with florists, venues, and planners across fragmented regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wedding Photography Market |
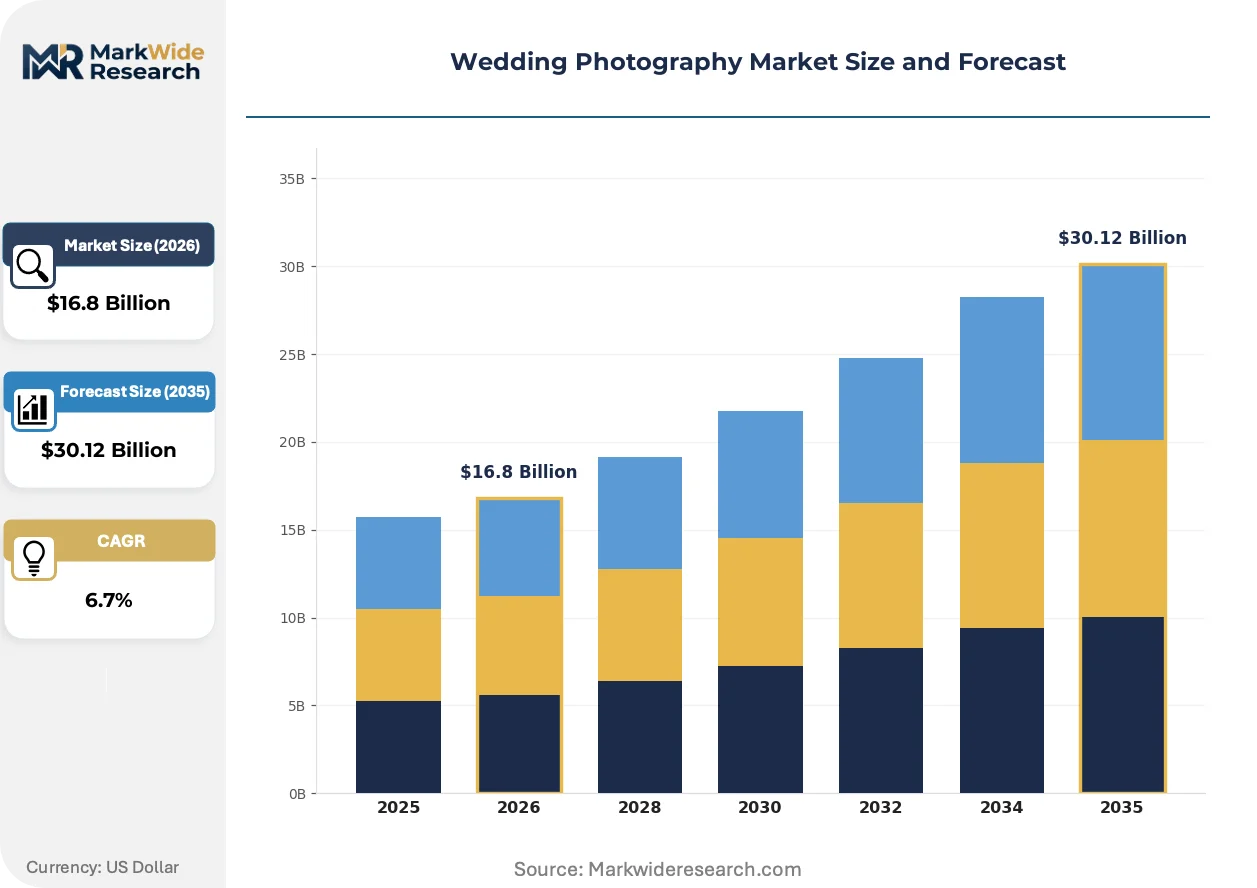
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $30.12 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Photography, Documentary Photography, Fine Art Photography, Editorial Photography Delivery Mode: Digital Albums, Printed Albums, Online Galleries, DVD/Blu-ray Package Size: Basic Package, Standard Package, Premium Package, Custom Package Customer Type: Couples, Wedding Planners, Event Coordinators, Venues |
| Companies Covered | Photography.com, Norman & Blake, George Street Photo & Video, Jose Villa, KT Merry, American Wedding Group, Cashman Photo, Hunter Ryan Photo, Bella Pictures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wedding Photography Market Evolving Landscape
Motion-first content requirements are restructuring how wedding photographers capture, edit, and deliver visual narratives, with technology and procurement patterns shifting in parallel.
Hybrid cinema cameras with dual photo-video capture capabilities are virtualizing the traditional separation between still and motion specialists. Destination wedding planners now specify single-operator coverage that delivers both formats, compressing vendor roster sizes and enabling studios to capture margin previously split across multiple contractors.
The U.S. Federal Trade Commission's truth-in-advertising guidelines are tightening portfolio representation standards. Studios must now document that displayed images reflect actual delivered package quality, affecting how sample galleries are curated and labeled. California and New York studios report increased compliance review activity.
Custom package rejection of standardized offerings is fragmenting buyer segments. Couples now specify à-la-carte hour counts, deliverable formats, and timeline requirements through direct-to-photographer platforms, bypassing traditional bridal fair intermediaries. This pattern concentrates in metropolitan corridors where digital-native planning tools have highest penetration.
Wedding Photography Market Segmentation
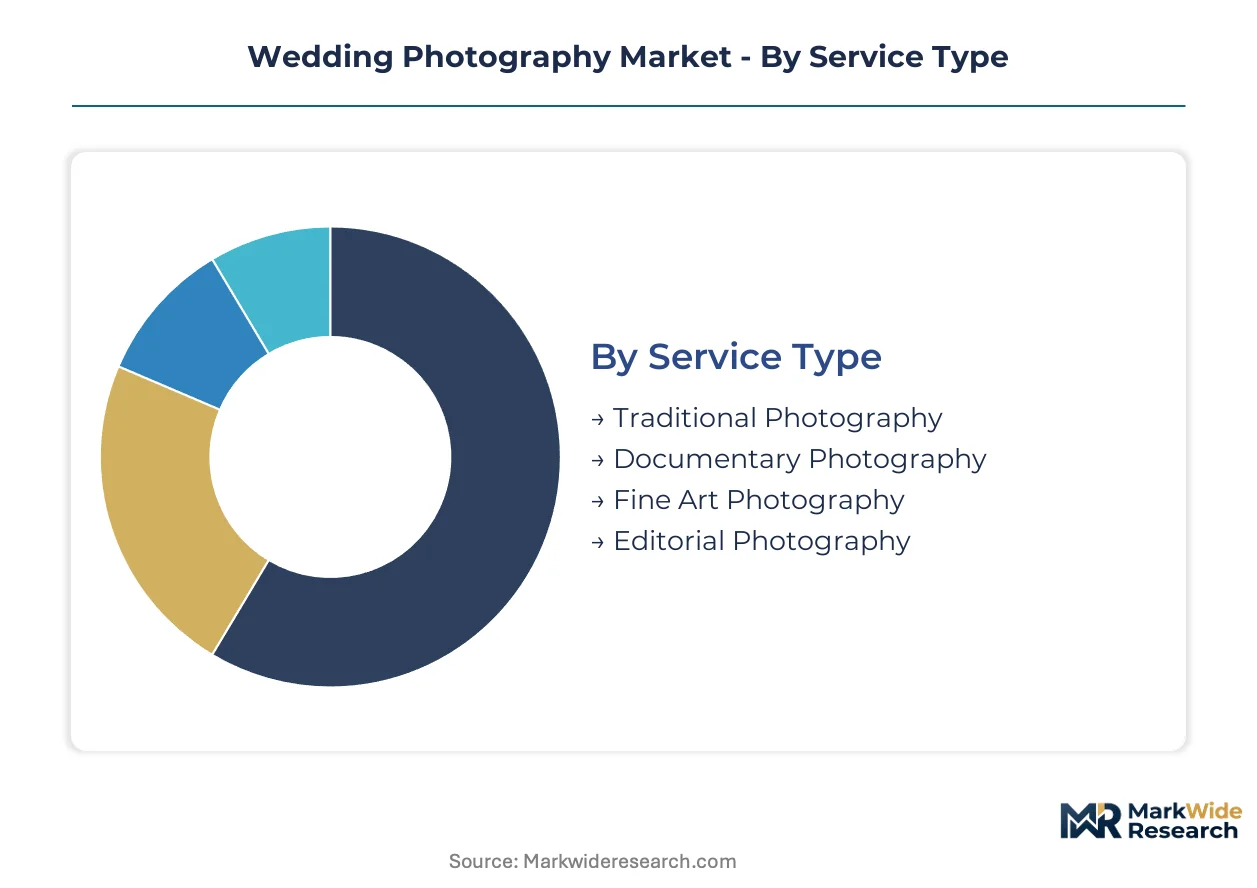
Service differentiation in wedding photography creates distinct operational rhythms and margin profiles across studios. Cycle times vary dramatically between documentary workflows requiring extended editing hours and traditional package formats with templated delivery.
Service Type:
Documentary formats turn over slowest due to extended culling and authentic-moment sequencing, while traditional packages move fastest through standardized pose libraries.
- Traditional Photography:Pose-directed sessions with controlled lighting setups and established shot lists dominate suburban markets. Mumbai studios report compressed booking-to-delivery cycles through templated workflows.
- Documentary Photography:Unposed authenticity demands extended event-hour coverage and intensive post-production sequencing. Premium pricing reflects labor intensity and scarcity of candid-capture expertise in Delhi and Bangalore corridors.
- Fine Art Photography:Film-based chemical processes and medium-format aesthetics signal craft authenticity for luxury-tier buyers.
- Editorial Photography:Fashion-influenced styling and location scouting concentrate in destination wedding markets.
Traditional photography anchors the volume base while documentary photography gains share at the steepest rate.
Delivery Mode:
Margin concentration separates physical from digital formats, with printed products commanding premium tier pricing despite lower volume throughput.
- Digital Albums:Cloud-hosted galleries with download permissions dominate volume delivery. GDPR-compliant European platforms invest in client data handling infrastructure that enables service differentiation.
- Printed Albums:Hand-bound leather and lay-flat binding retain margin concentration among luxury package tiers. Bangalore studios report physical product differentiation as digital delivery commoditizes.
- Online Galleries:Password-protected platforms with social sharing integration serve mid-market couples.
- DVD/Blu-ray:Archival physical media persists in legacy-format preference segments.
Digital albums anchor the volume base while printed albums expand most quickly among premium repositioning studios.
Package Size:
Customer specification patterns fragment standardized tiers, with à-la-carte construction displacing off-the-shelf selection in metropolitan corridors.
- Custom Package:Hour-count specification and deliverable format selection through direct-to-photographer platforms bypass traditional bridal fair intermediaries. Digital-native planning tools drive penetration in metropolitan clusters.
- Premium Package:Multi-day coverage with second shooters and cinematic add-ons targets destination wedding planners.
- Standard Package:Eight-hour coverage with digital delivery serves mid-market volume.
- Basic Package:Ceremony-only capture with limited editing meets entry-tier price sensitivity.
Standard packages anchor the volume base while custom packages climb the fastest as couples reject standardized offerings.
Customer Type:
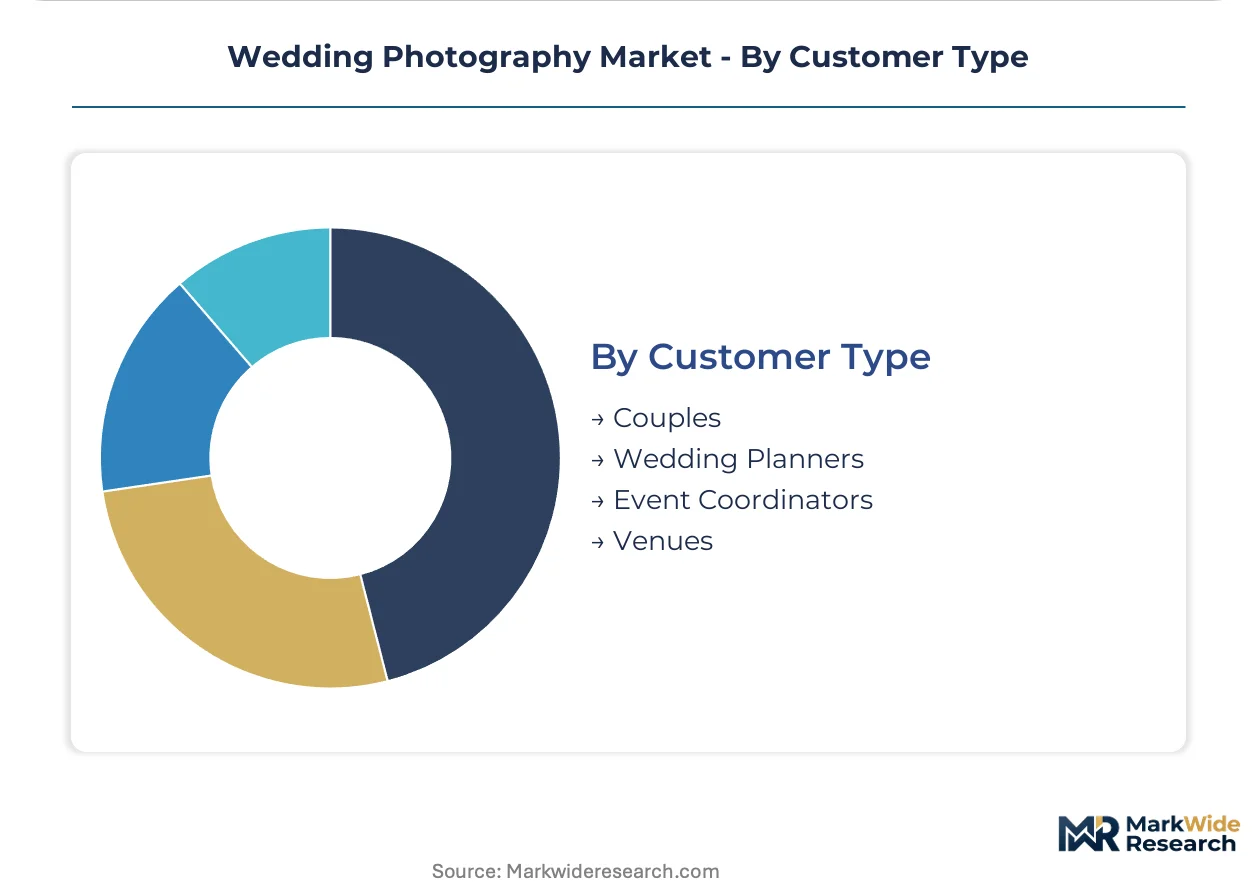
Procurement authority concentrates with planners for destination events, while direct couple bookings dominate local metropolitan markets.
- Wedding Planners:Multi-day international coverage specifications drive demand for travel-ready production crews. Vendor roster compression favors single-operator hybrid photo-video capabilities.
- Couples:Direct platform engagement fragments buyer segments through à-la-carte specification. Social media algorithm shifts toward video-first content alter how studios market to this segment.
- Event Coordinators:Corporate hospitality and hotel chain contracts require ISO 9001 certification for digital asset management standardization.
- Venues:Preferred vendor list placement generates recurring referral revenue through reciprocal florist and planner relationships.
Couples anchor the volume base while wedding planners gain procurement influence at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication for professional imaging systems concentrates in Japanese and German optical manufacturing corridors, while service delivery demand fragments across metropolitan wedding clusters in North America, Europe, and South Asia. The analysis window tracks divergent regulatory pressures on data handling and distinct procurement patterns between destination planners and direct couple bookings.
United States
Destination wedding planners in Florida and California drive multi-day coverage specifications for travel-ready production crews. The Federal Trade Commission's truth-in-advertising guidelines tighten portfolio representation standards, requiring documented alignment between displayed images and delivered package quality. New York and Los Angeles studios anchor the editorial photography segment with fashion-influenced styling workflows.
India
Mumbai, Delhi, and Bangalore metropolitan corridors concentrate demand for documentary-style coverage with unposed authenticity positioning. The Bureau of Indian Standards oversees quality benchmarks for printed album materials and binding durability. Delhi-NCR studios report the steepest adoption of custom package construction through direct-to-photographer digital platforms.
United Kingdom
London-based studios command premium positioning in the fine art segment through film-based chemical process specialization. GDPR compliance frameworks impose strict client data handling protocols for online gallery platforms, enabling service differentiation through certified infrastructure. The Southeast England cluster leads printed album margin concentration among luxury-tier buyers.
Germany
Bavaria and North Rhine-Westphalia host precision optical component manufacturers controlling CMOS sensor fabrication capacity. REACH regulations govern chemical processing materials used in fine art film workflows. Berlin studios anchor the editorial segment with destination wedding coverage spanning Mediterranean and Alpine locations.
Australia
New South Wales and Victoria metropolitan markets show concentrated demand for hybrid photo-video capture capabilities from single operators. The Therapeutic Goods Administration's peripheral role in imaging equipment safety standards affects professional camera import pathways. Sydney studios lead adoption of ISO 9001 certification for digital asset management standardization targeting corporate hospitality contracts.
Wedding Photography Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in optical fabrication and post-production software. The vendor base distributes across fragmented independent studios, regional franchise networks, and boutique fine art specialists. Three archetypes dominate: scale-driven franchise operators with multi-state coverage, craft-authentic film specialists commanding premium pricing, and hybrid photo-video single operators compressing vendor rosters. Competitive moves center on geographic expansion through franchise licensing and vertical integration into album printing and online gallery infrastructure.
Within the franchise tier, George Street Photo & Video anchors multi-state coverage models, while Norman & Blake exemplify editorial-style destination wedding positioning. Jose Villa occupies the fine art archetype through film-based aesthetic specialization, with these three representing distinct strategic vectors in service differentiation.
| Leading Market Players |
|---|
| Photography.com |
| Norman & Blake |
| George Street Photo & Video |
| Jose Villa |
| KT Merry |
| American Wedding Group |
| Cashman Photo |
| Hunter Ryan Photo |
| Bella Pictures |
| Others |
Value Network & Pricing Analysis
Pacific Rim freight corridors connecting Japanese optical component hubs to Indian metropolitan studios carry sensor and lens assemblies whose transit cost volatility directly shapes equipment procurement budgets and downstream package pricing tiers across documentary and fine art segments.
Pricing Analysis
The FTC's truth-in-advertising guidelines dictate the pricing tier structure by mandating documented alignment between portfolio displays and delivered outputs, compressing margin flexibility for studios misrepresenting capabilities. Three-tier pricing structure across premium, standard, and economy levels separates film-based chemical process specialists from digital workflow studios and entry-tier ceremony-only providers. Cost compression in the standard tier is intensifying because generative AI tools compress editing labor value and turnaround expectations. Couples booking through direct-to-photographer platforms exhibit highest price sensitivity, while destination wedding planners demonstrate lowest sensitivity due to bundled multi-day coverage specifications.
Supply Chain Analysis
Precision optical contract manufacturers in Japan and Germany hold dominant CMOS sensor and lens assembly capacity, with secondary fabrication clusters in Taiwan and South Korea. Professional imaging systems draw from full-frame sensor arrays, precision glass optics, and color-calibration hardware. Single-source vulnerability concentrates in Japanese CMOS fabrication facilities controlling low-light sensor supply. Distribution runs through authorized dealer networks serving independent studios, with franchise operators leveraging direct manufacturer relationships for volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating with destination wedding planners who compress vendor rosters and specify hybrid photo-video deliverables, fragmenting traditional still-specialist revenue pools while elevating single-operator capabilities.
For Market Incumbents: Entrench documentary-style positioning through extended event-hour coverage commitments that resist AI editing substitution, while securing ISO 9001 certification to capture corporate hospitality contracts from hotel chains. Backward integration into album printing infrastructure defends margin concentration as digital delivery commoditizes.
For New Entrants and Emerging Players: Build out unposed authenticity expertise in Delhi and Bangalore metropolitan corridors where demand concentrates and candid-capture talent remains scarce. Target custom package construction through direct-to-photographer platforms, bypassing bridal fair intermediaries with digital-native planning tool integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from regional franchise networks with multi-state coverage licenses and established vendor referral systems. Long-term viability hinges on motion-first content capabilities and hybrid photo-video technical infrastructure. Monitor algorithm shifts by Instagram and TikTok as inflection indicators for studio marketing spend reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Photo-Video Capability Investment | Single-operator coverage captures margin previously split across multiple contractors for destination wedding planners. |
| ISO 9001 Certification Pursuit | Standardized digital asset management unlocks corporate hospitality contracts with hotel chains and event coordinators. |
| Direct-to-Photographer Platform Integration | Digital-native planning tools in metropolitan corridors bypass bridal fair intermediaries and fragment buyer segments. |
| Film-Based Chemical Process Specialization | Craft authenticity signaling commands premium pricing from luxury-tier buyers seeking differentiation from digital workflows. |
| GDPR-Compliant Gallery Infrastructure | Certified client data handling protocols enable service differentiation for European online delivery platforms. |
Research Methodology
Cross-validation between primary interviews with wedding photographers, destination wedding planners, post-production editors, and equipment dealers and secondary sources including FTC enforcement records, BIS quality benchmarks, and GDPR compliance frameworks anchors the qualitative findings. Bottom-up triangulation aggregates studio-level booking data and package pricing structures, while top-down validation incorporates optical component trade flows and social media platform algorithm documentation.
Calibration against historical adoption curves for documentary-style coverage and motion-first content requirements shapes the analytical framework across the analysis window. Segmentation dimensions include service type, delivery mode, package size, and customer procurement authority. CAGRs derive from equipment replacement cycles, destination wedding frequency patterns, and metropolitan corridor demand concentration. Forecast inputs incorporate hybrid camera adoption rates and direct-to-photographer platform penetration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generative AI editing platforms or franchise network consolidators would shift outcomes beyond modeled ranges. Quarterly review of social media algorithm shifts, sensor supply lead times, and planner procurement specification changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Digital Effects Services Market
Digital Media
APAC DOOH Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Mobile Entertainment Market
Digital Media
Media Coding Service Market
Digital Media
Digital Audio Workstation (DAW) Market
Digital Media
Da Vinci Systems Market
Digital Media
Webtoons Market
Digital Media
Europe Online Video Platform Market
Digital Media
Europe Location-Based Entertainment Market
Digital Media
Social TV Market
Digital Media
US Automatic Content Recognition Market
Digital Media
Global Playout Automation and Channel in a Box Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
Drone Wedding Photography Market
Digital Media
Online Gambling Market