
 Media Gateway Market | 2026-2036
Media Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Media Gateway Market Analysis
Enterprise buyer concentration is decoupling from traditional telecom carrier dominance as mid-market corporations and cloud-native service providers fragment procurement across multiple vendor channels. Cisco Systems Inc. leverages its installed base of enterprise routing equipment to cross-sell integrated gateway solutions. Huawei Technologies Co. Ltd. anchors significant manufacturing scale across its domestic supply chain and select export markets. AudioCodes Ltd. specializes in Microsoft Teams-certified session border controllers that capture hybrid workplace demand.
A media gateway is a network device that translates communications between disparate network types, typically converting time-division multiplexing voice circuits into packet-switched IP data streams using codecs such as G.711 and G.729 with jitter buffers and echo cancellation. Its primary commercial purpose is enabling interoperability between legacy public switched telephone networks and modern VoIP or IMS core infrastructures while preserving service quality. Session border controllers represent the fastest-expanding product type as carriers deploy them at network edges to manage security policy and interconnection compliance. Cloud-based deployment models are displacing on-premises installations among enterprises seeking operational flexibility without capital-intensive hardware commitments.
The FCC mandates STIR/SHAKEN caller ID authentication standards that force gateway vendors to embed cryptographic certificate handling directly into signaling path hardware. ETSI and the IETF shape international interoperability frameworks that determine which codec and protocol combinations gain market access across European and North American carrier procurement cycles. Stakeholders must monitor how quantum-resistant encryption requirements from NIST will reshape secure voice tunnel specifications in forthcoming gateway generations.
Market Dynamics
Telecom carriers are dismantling time-division multiplexing infrastructure and replacing it with packet-switched cores, forcing wholesale hardware replacement cycles across interconnection points and enterprise edge networks.
Growth Catalysts
- STIR/SHAKEN Mandates:The FCC's caller ID authentication framework compels US carriers to upgrade signaling path hardware with embedded cryptographic certificate handling, accelerating gateway refresh timelines.
- Hybrid Workplace Infrastructure:Enterprises deploying Microsoft Teams-certified session border controllers require media gateways that bridge legacy PBX systems with cloud-native collaboration platforms.
- IMS Core Modernization:Germany's Deutsche Telekom and Japan's NTT are retiring circuit-switched networks in favor of IP Multimedia Subsystem architectures, expanding procurement of transcoding and protocol-interworking equipment.
Market Restraints
- Silicon Supply Concentration:Advanced DSP and FPGA components for real-time voice processing concentrate among Taiwanese foundries and select US fabless designers, exposing procurement to geopolitical friction.
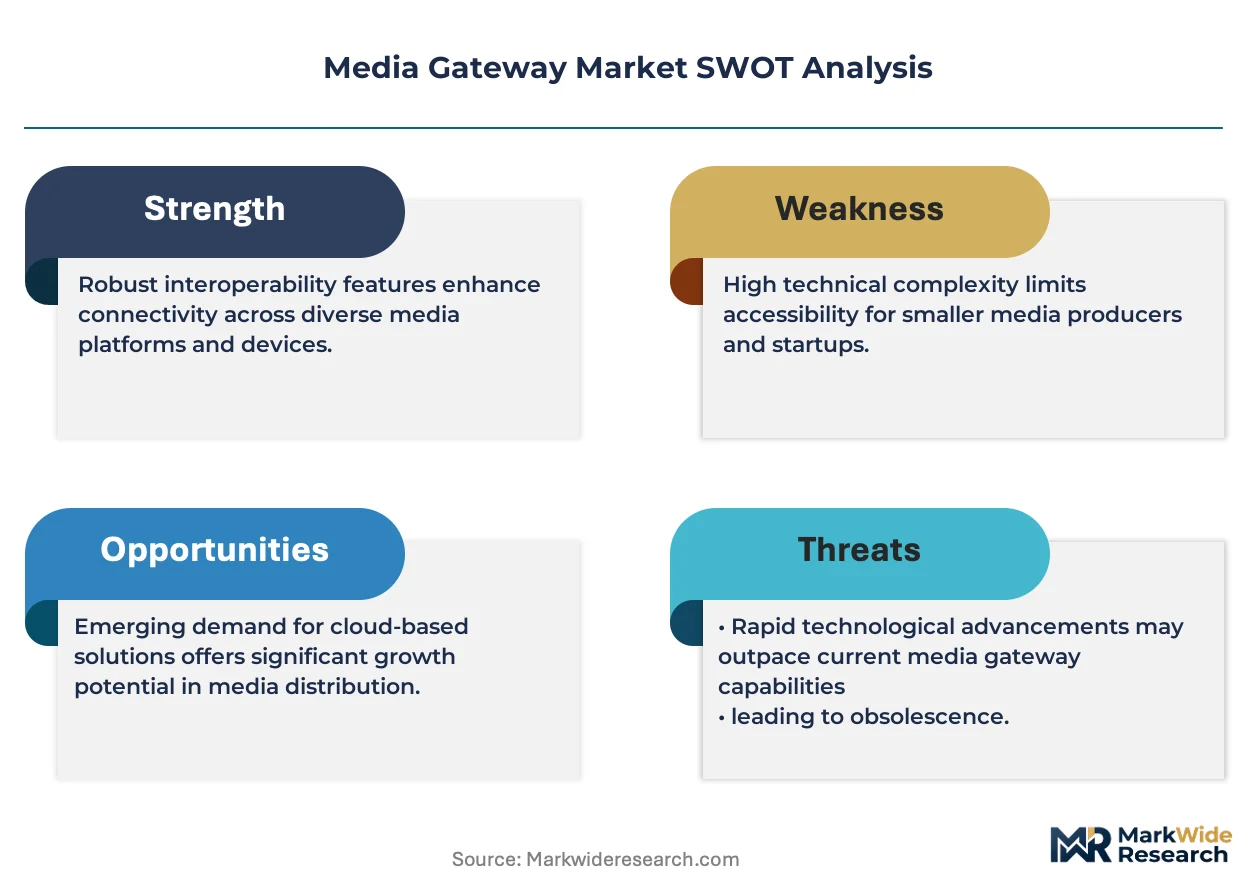
- Capital Intensity of Certification:Carrier-grade hardware must pass NEBS Level 3 environmental testing and ETSI interoperability validation, extending product development cycles and freezing out smaller vendors.
- Software-Defined Substitution:Virtualized session border controller functions running on commodity x86 servers threaten dedicated appliance demand in enterprise and smaller carrier segments.
Strategic Opportunities
- Quantum-Resistant Encryption:NIST's post-quantum cryptography standards will reshape secure voice tunnel specifications, creating replacement demand for gateway hardware lacking algorithm agility.
- Edge Computing Convergence:Media gateways integrating containerized network functions with local compute resources capture demand from distributed enterprises requiring on-premise call processing with cloud management planes.
- Rural Broadband Buildouts:US Rural Digital Opportunity Fund subsidies and India's BharatNet program extend packet voice infrastructure to underserved markets, opening procurement channels outside incumbent carrier hierarchies.
Industry Challenges
- Legacy TDM Integration Complexity:Carriers must maintain five-nines availability while grafting IP gateways onto decades-old switching fabrics, requiring specialized signaling protocol expertise that has aged out of the workforce.
- Multi-Vendor Interoperability Certification:Each carrier network combines equipment from Cisco, AudioCodes, Huawei, and niche specialists, forcing vendors to maintain extensive protocol-variant testing labs that duplicate costs across the supply base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Gateway Market |
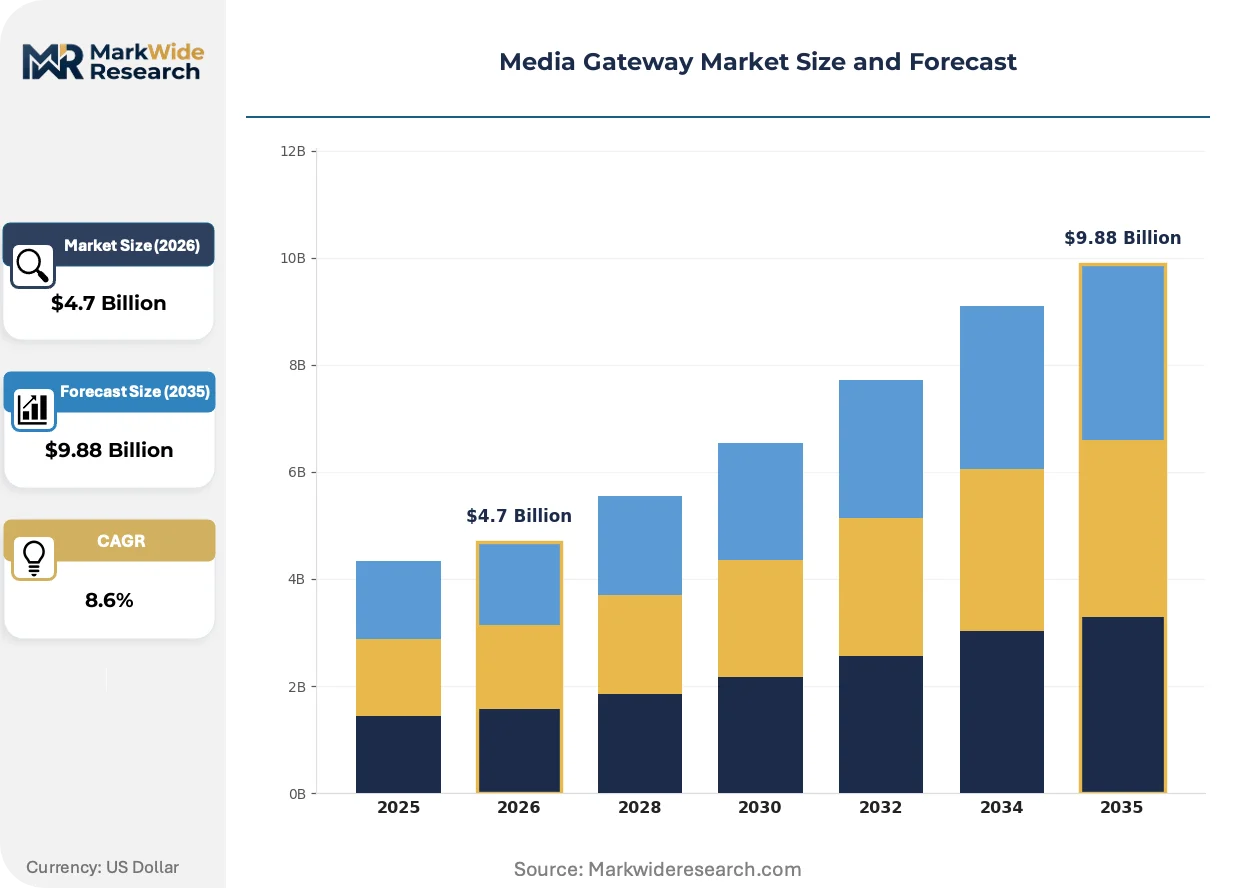
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Gateways, Digital Gateways, Hybrid Gateways, Session Border Controllers Connection Type: Wireless, Wired, Fiber Optic, Satellite End User: Telecom Providers, Enterprises, Government, Residential Users Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual |
| Companies Covered | Avaya Inc., Cisco Systems Inc., Nokia Corporation, Dialogic Corporation, Huawei Technologies Co. Ltd., AudioCodes Ltd., Ericsson, ZTE Corporation, Ribbon Communications Operating Company Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Gateway Market Emerging Trajectories
Cloud-native architectures are redefining how voice interconnection hardware is deployed, consumed, and monetized, compressing traditional capex cycles into elastic operational expenditure models.
Containerized media gateway functions running on Kubernetes-orchestrated infrastructure are absorbing transcoding and signaling workloads that previously required dedicated appliances. Tier-2 carriers and cloud communications providers are adopting these disaggregated stacks to scale capacity elastically during traffic spikes. This absorption is compressing hardware refresh intervals while expanding addressable demand among buyers lacking facilities engineering expertise.
The European Union's Cybersecurity Act and NIS2 Directive are mandating security certification for critical digital infrastructure, including voice interconnection equipment. Hardware vendors must now obtain Common Criteria or EUCC evaluation before participating in member state carrier tenders. German and French procurement authorities are enforcing these requirements most stringently, filtering vendor pools and extending sales cycles.
Enterprise buyers are fragmenting procurement across direct vendor relationships, systems integrators, and managed service providers rather than consolidating through traditional telecom carriers. Mid-market corporations with hybrid cloud voice architectures favor subscription-based gateway-as-a-service arrangements over perpetual license purchases. This behavioral shift is most visible in US and UK markets where IT departments retain direct budget authority over collaboration infrastructure.
Media Gateway Market Segmentation
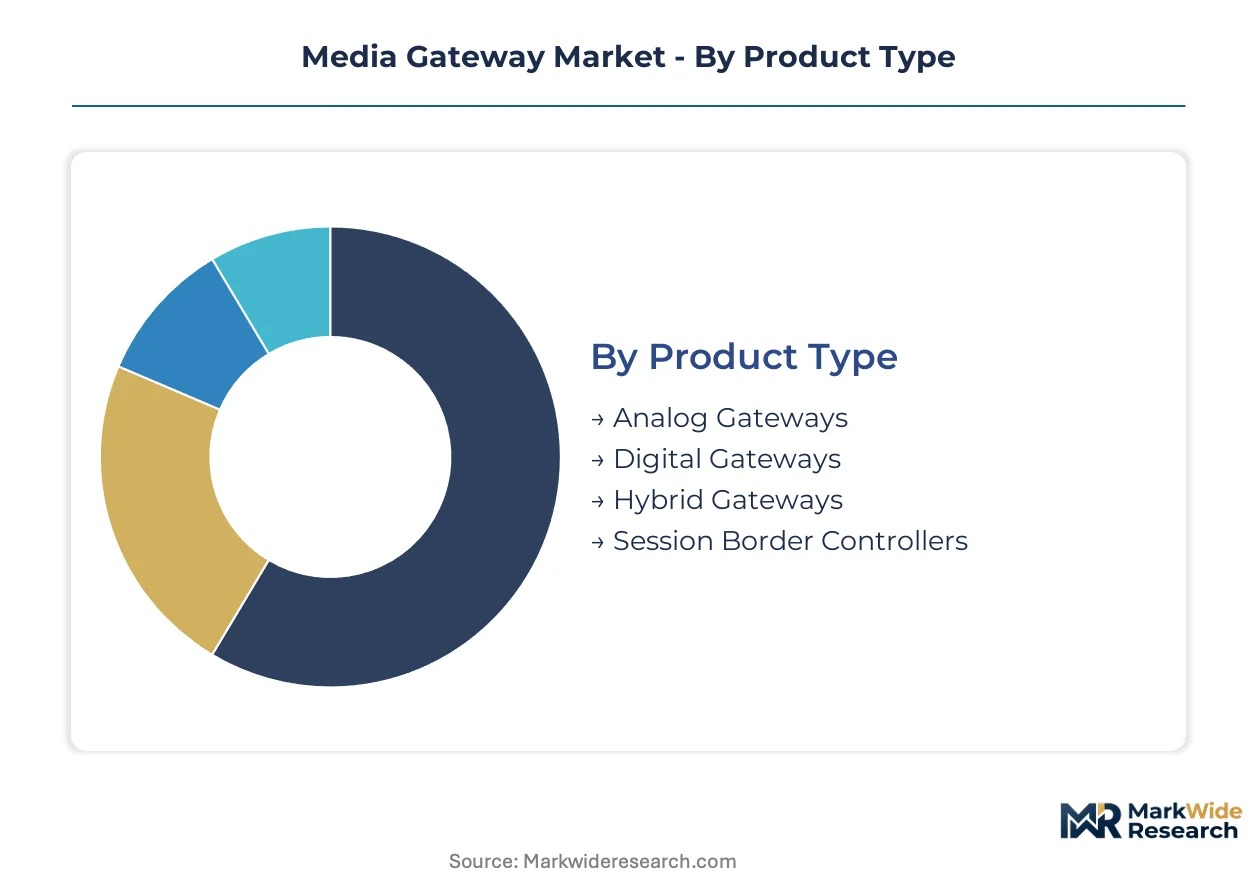
Media gateway procurement fragments across four distinct dimensions, each revealing divergent buyer priorities. Product architecture determines hardware refresh cycles. Deployment models expose the tension between capital preservation and operational control. Connection types and end-user profiles illuminate where interoperability complexity concentrates most acutely.
Product Type:
Supply concentration tilts toward vendors with integrated signaling protocol stacks and carrier-grade certification depth.
- Session Border Controllers:Edge-deployed appliances managing security policy, NAT traversal, and interconnection compliance between carrier networks. Deutsche Telekom and NTT procurement cycles prioritize SBCs with embedded STIR/SHAKEN certificate handling for robocall mitigation, accelerating replacement of legacy signaling hardware.
- Hybrid Gateways:Platforms bridging TDM trunking with IP packet cores through modular transcoding blades. US rural broadband buildouts under FCC subsidy programs favor hybrid architectures that preserve existing copper investment while enabling VoIP service delivery.
- Analog Gateways:Compact devices converting FXO/FXS loops to SIP trunks for small business PBX integration.
- Digital Gateways:E1/T1 PRI interfaces connecting legacy ISDN infrastructure to packet cores.
Today's leader: Session Border Controllers. Tomorrow's challenger: Hybrid Gateways.
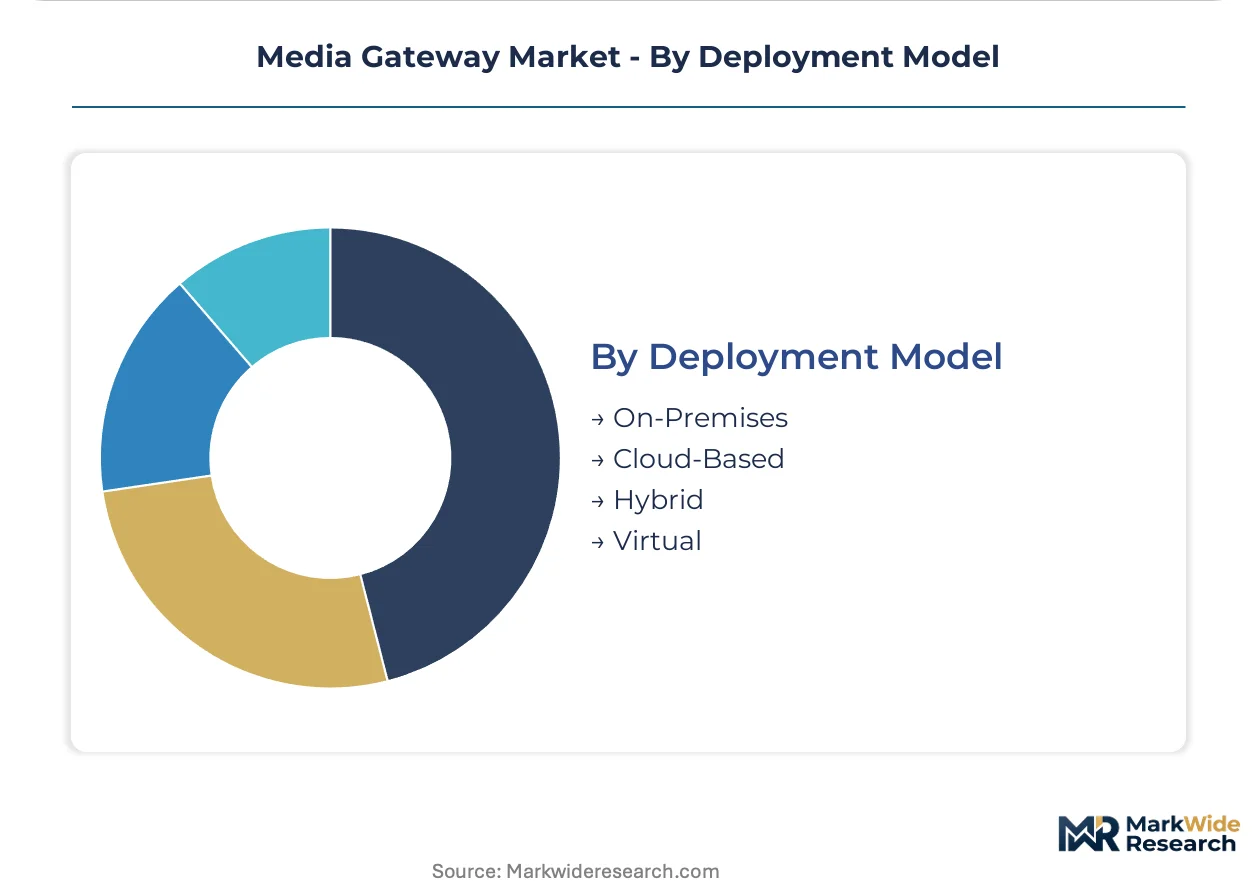
Deployment Model:
Cost tier stratification separates capital-intensive appliance buyers from subscription-oriented service consumers.
- Cloud-Based:Containerized gateway functions orchestrated through Kubernetes clusters, scaling transcoding capacity elastically without facilities engineering. Mid-market enterprises in the United States and United Kingdom favor subscription models that shift collaboration infrastructure from IT capital budgets to operational expenditure.
- On-Premises:Dedicated appliances installed in carrier central offices or enterprise data centers requiring NEBS Level 3 environmental certification. German and French procurement authorities enforce EU Cybersecurity Act certification requirements, filtering vendor pools for hardware with Common Criteria evaluation.
- Hybrid:Split architectures with local call processing and cloud management planes.
- Virtual:Software-only instances running on commodity x86 servers.
Cloud-Based deployment is climbing the fastest among buyers lacking internal facilities expertise. On-Premises retains margin concentration in carrier core network applications.
Connection Type:
Application context dictates physical layer selection, with fiber commanding interconnection density and wireless serving mobility requirements.
- Fiber Optic:High-density trunking between carrier points of presence using DWDM transport for transcoded voice streams. Japan's NTT and Germany's Deutsche Telekom specify fiber-connected gateways for IMS core modernization, replacing circuit-switched infrastructure with packet-based voice delivery.
- Wireless:Cellular backhaul and fixed wireless access deployments in underserved geographies. India's BharatNet program extends packet voice infrastructure to rural markets through wireless-connected gateways, bypassing fiber trenching economics.
- Wired:Copper-based Ethernet or T1/E1 connectivity for enterprise edge applications.
- Satellite:Remote coverage for maritime, aviation, and isolated terrestrial locations.
Fiber Optic dominates carrier procurement volume. Wireless represents the steepest expansion trajectory for rural broadband subsidy programs.
End User:
Customer type determines purchasing authority structure, certification burden, and integration complexity tolerance.
- Telecom Providers:Tier-1 and Tier-2 carriers with dedicated network engineering teams managing multi-vendor interoperability testing. FCC STIR/SHAKEN mandates force US carriers into accelerated hardware refresh cycles, embedding cryptographic certificate handling directly into signaling path equipment.
- Enterprises:Mid-market corporations and cloud-native service providers fragmenting procurement across direct vendor relationships and managed service channels. Microsoft Teams certification requirements drive gateway selection for hybrid workplace infrastructure bridging legacy PBX systems with cloud collaboration platforms.
- Government:Agencies with stringent security evaluation requirements under national critical infrastructure frameworks.
- Residential Users:Consumer-grade VoIP adapters and integrated access devices supplied through retail or ISP bundling.
Telecom Providers anchor procurement volume. Enterprises are gaining share fastest as IT departments retain direct budget authority over voice infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers with legacy TDM protocol expertise concentrate in Germany, Japan, and the United States, anchoring carrier infrastructure modernization programs that drive gateway procurement. These talent pools support complex signaling interwork between circuit-switched heritage and packet-based replacements.
United States
Rural broadband buildouts and enterprise cloud migration generate dual demand streams for hybrid and virtualized gateway platforms. FCC STIR/SHAKEN mandates compel carriers to embed cryptographic certificate handling into signaling hardware, accelerating replacement cycles. Dallas-Fort Worth hosts major carrier engineering centers where interconnection testing labs validate multi-vendor interoperability.
Germany
Deutsche Telekom's IMS core retirement of circuit-switched infrastructure expands procurement of transcoding and protocol-interworking equipment. EU Cybersecurity Act certification requirements filter vendor participation in public tenders, extending sales cycles. Munich and Frankfurt concentrate carrier procurement authority and interoperability testing facilities for Central European networks.
Japan
NTT's nationwide migration from TDM to IP Multimedia Subsystem architectures sustains demand for high-density fiber-connected gateways. METI industrial policy supports domestic vendor participation in critical infrastructure procurement. Tokyo and Osaka metropolitan areas anchor carrier network engineering and equipment qualification laboratories.
India
BharatNet rural broadband subsidies extend packet voice infrastructure to underserved markets through wireless-connected gateway deployments. TRAI interconnection regulations shape procurement specifications for carrier network edges. Bangalore and Hyderabad host systems integration centers supporting distributed enterprise voice deployments.
United Kingdom
Mid-market enterprise fragmentation toward direct vendor procurement shifts gateway purchasing from carrier channels to IT department budgets. Ofcom regulatory frameworks influence security and interoperability requirements for voice infrastructure. London's financial services sector sustains demand for low-latency session border controller deployments.
Media Gateway Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor structure concentrates around three strategic archetypes: integrated networking conglomerates with enterprise routing installed bases, telecommunications equipment specialists with carrier-grade certification depth, and software-centric vendors pursuing cloud-native disaggregation. Competitive positioning hardens through vertical integration into semiconductor supply chains and strategic partnerships with hyperscale cloud providers.
Within the integrated networking tier, Cisco Systems Inc. and Nokia Corporation exemplify archetypes leveraging broad infrastructure portfolios to cross-sell gateway functionality. AudioCodes Ltd. and Ribbon Communications Operating Company Inc. represent specialists concentrating on session border controller certification and Microsoft Teams ecosystem integration. Huawei Technologies Co. Ltd. anchors manufacturing scale advantages across domestic and select export markets. Ericsson and ZTE Corporation occupy positions bridging carrier core infrastructure with edge gateway deployment.
| Leading Market Players |
|---|
| Avaya Inc. |
| Cisco Systems Inc. |
| Nokia Corporation |
| Dialogic Corporation |
| Huawei Technologies Co. Ltd. |
| AudioCodes Ltd. |
| Ericsson |
| ZTE Corporation |
| Ribbon Communications Operating Company Inc. |
| Others |
Supply Flow & Price Mechanics
Carrier procurement programs in Germany, Japan, and the United States concentrate demand for NEBS Level 3 certified hardware, anchoring premium pricing for appliances with embedded STIR/SHAKEN cryptographic modules while subscription models fragment enterprise spending.
Pricing Analysis
Bundled appliance sales with perpetual licensing dominate carrier procurement, while unbundled SaaS tiers capture mid-market enterprise demand. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade certified hardware from virtualized instances and consumer adapters. Cost compression in virtualized tiers is intensifying because containerized network functions displace dedicated appliances. Enterprise IT departments exhibit highest price sensitivity, while Tier-1 carriers prioritize certification depth over unit economics.
Supply Chain Analysis
Warehouse-distribution layers concentrate in regional hubs serving Dallas-Fort Worth, Munich, and Tokyo carrier engineering centers with just-in-time appliance fulfillment. Manufacturing draws from Taiwan for advanced DSP and FPGA components, China for printed circuit board assembly, and domestic facilities in Germany and Japan for final integration and certification testing. Single-source vulnerability in Taiwanese foundry capacity for real-time voice processing silicon exposes procurement to geopolitical friction. Distribution runs through authorized value-added resellers for enterprise segments and direct carrier procurement teams for Tier-1 infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Media Gateway Market functions as a stable compounder, with FCC-mandated hardware refresh cycles generating predictable replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Acquire specialized signaling protocol engineering teams to address workforce aging and legacy TDM integration complexity. Deepen backward integration into FPGA and DSP semiconductor supply to mitigate Taiwan foundry concentration risk. Fortify Microsoft Teams certification pipelines against AudioCodes specialization in hybrid workplace infrastructure. For New Entrants and Emerging Players: Cloud-native deployment channels offer the lowest barrier to entry for containerized session border controller functions targeting mid-market enterprises. Rural broadband subsidy programs in the United States and India present the most penetrable procurement channels outside incumbent carrier hierarchies. Lead with gateway-as-a-service subscription models that shift buyer budgets from capital to operational expenditure. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking edge computing convergence capabilities for distributed enterprise voice workloads. Targets with quantum-resistant encryption algorithm agility command premium positioning as NIST post-quantum standards reshape secure voice specifications. Watch for containerized network function adoption rates in Tier-2 carrier procurement as the signal for hardware displacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| STIR/SHAKEN Hardware Certification | FCC mandates accelerate replacement cycles for US carriers embedding cryptographic handling. |
| Microsoft Teams Ecosystem Integration | AudioCodes certification depth captures hybrid workplace demand from enterprise IT budgets. |
| Containerized Network Function Development | Kubernetes-orchestrated transcoding displaces dedicated appliances in Tier-2 carrier networks. |
| Quantum-Resistant Encryption Investment | NIST post-quantum standards reshape secure voice tunnel specifications for next-generation hardware. |
| Rural Broadband Subsidy Program Participation | US Rural Digital Opportunity Fund and India's BharatNet extend procurement beyond incumbent hierarchies. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market combining interviews with carrier network engineering directors, enterprise IT procurement officers, session border controller product managers, and systems integration specialists. Secondary validation draws from FCC equipment authorization databases, ETSI interoperability test reports, TRAI regulatory filings, and carrier capital expenditure disclosures. Bottom-up unit shipment estimates triangulate against top-down infrastructure replacement cycle analysis.
Rate-of-change decomposition separates volume growth from value migration across the analysis window, modeling product architecture, deployment model, connection type, and end-user segmentation dimensions. CAGRs derive from carrier infrastructure retirement schedules, enterprise cloud migration trajectories, and regulatory mandate compliance timelines. Forecast inputs incorporate Deutsche Telekom and NTT IMS modernization disclosures alongside FCC robocall mitigation enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for software-defined substitution would alter the outlook if virtualized session border controllers capture carrier core networks faster than projected. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
United Kingdom Webtoons Market
Digital Media
Social TV Market
Digital Media
North America Webtoons Market
Digital Media
Video Content Management Market
Digital Media
LED Stadium Screens Market
Digital Media
Music Rights Management Market
Digital Media
Digital Music Services Market
Digital Media
Video Production Market
Digital Media
Stream Hosting Market
Digital Media
Digital Content Market
Digital Media
Digital Content Creator Market
Digital Media
Projection Mapping Market
Digital Media
Digital Content Creation Market
Digital Media
Anime Market
Digital Media
Webtoons Market
Digital Media
Africa Animation Market