
 3D Animation Market | 2026-2036
3D Animation Market Size, Share, and Industry Trends Forecast 2026-2036
3D Animation Market Intelligence
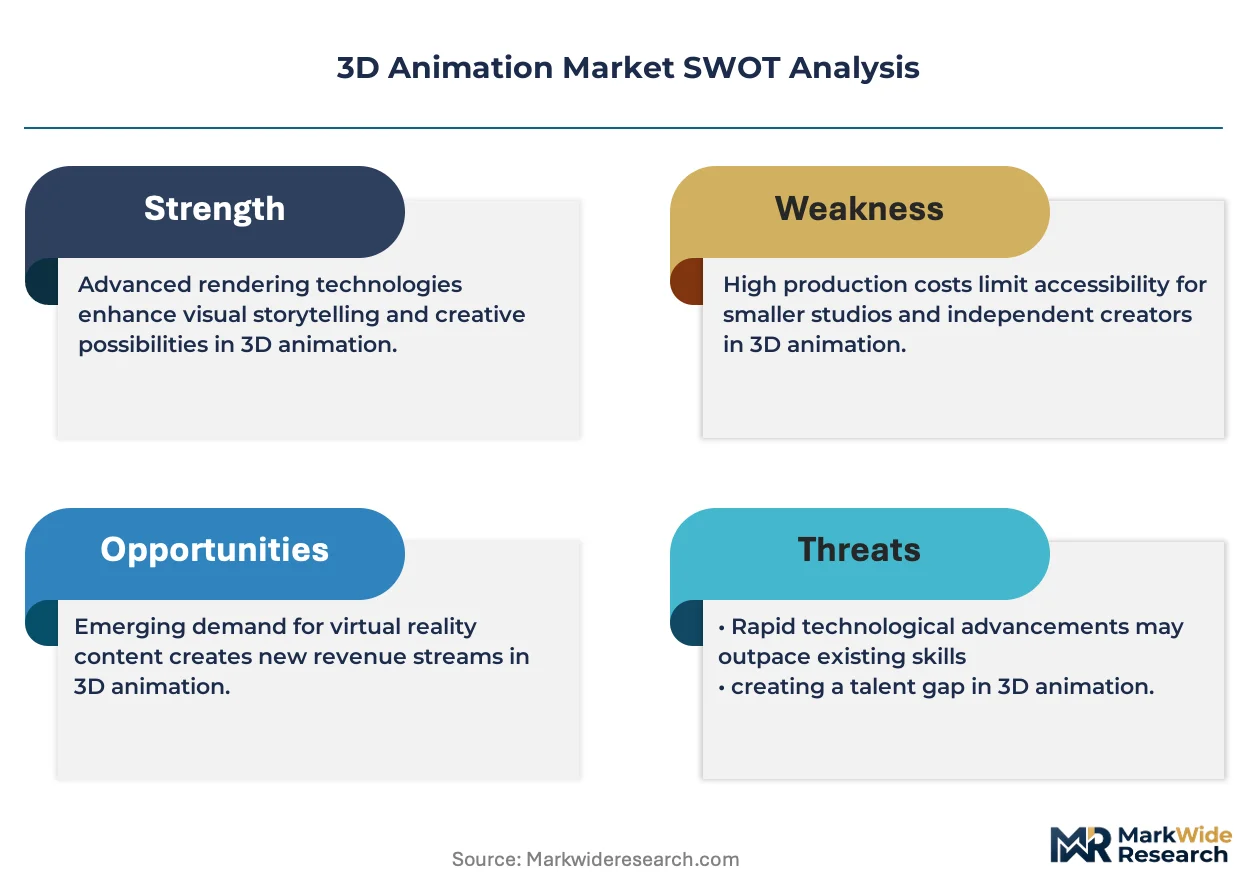
Platform licensing is fragmenting as studios decouple rendering engines from proprietary toolchains and monetize modular subscriptions. Pixar Animation Studios leverages its RenderMan technology to anchor high-end cinematic pipelines across external clients. DreamWorks Animation sustains competitive pressure through proprietary MoonRay renderer development and cloud-optimized production infrastructure. OmegaRender specializes in architectural visualization services, occupying a distinct margin tier below entertainment-focused competitors.
3D animation encompasses the computational generation of three-dimensional moving imagery through polygonal modeling, rigging, and keyframe or physics-based interpolation, typically rendered at 24-120 frames per second for perceptual fluidity. Its primary commercial purpose spans entertainment production, product visualization, and interactive simulation where spatial fidelity drives audience engagement or training efficacy. Motion capture technology leads deployment in high-budget entertainment, while physics-based animation captures expanding share in simulation and virtual reality applications where real-time behavioral accuracy determines utility. Cloud-based deployment is accelerating fastest among marketing agencies and content creators seeking elastic compute without capital-intensive render farm investment.
FCC content guidelines and emerging FDA standards for medical simulation training shape product safety and accuracy requirements in US-facing 3D animation outputs. The EU AI Act imposes disclosure obligations on generative 3D content, compelling studios to restructure metadata pipelines and provenance tracking. Stakeholders must monitor regulatory divergence between jurisdictions as compliance architecture becomes a determinative cost factor in cross-border project bidding.
Market Dynamics
Real-time rendering pipelines are compressing production timelines and forcing studios to restructure asset creation workflows around game-engine architectures rather than traditional offline rendering farms.
Growth Catalysts
- EU AI Act disclosure mandates:Studios investing in provenance-tracking infrastructure gain competitive advantage in European commissioning. Metadata pipeline upgrades differentiate compliant bidders.
- Motion capture deployment:Entertainment producers accelerate volume-stage adoption for virtual production. Real-time performance capture reduces post-production iteration cycles.
- Los Angeles production clustering:Talent density and infrastructure concentration sustain premium project gravity. Vancouver facilities expand to capture spillover demand.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints create render-farm procurement bottlenecks. Cloud compute pricing volatility follows semiconductor input costs.
- Cross-border regulatory divergence:EU AI Act disclosure requirements clash with US FCC content guidelines. Multi-jurisdiction projects face compliance architecture cost multiplication.
- Proprietary format lock-in:Major engine ecosystems maintain incompatible asset pipelines. Interoperability gaps force redundant production work.
Strategic Opportunities
- Medical simulation training:FDA standards for surgical visualization create certified-content demand. Specialized studios capture healthcare vertical premiums.
- Architectural visualization services:Real-estate marketing budgets shift toward interactive 3D walkthroughs. Lower production cost structures enable mid-market penetration.
- Cloud-native creator tools:Elastic compute subscriptions displace capital-intensive render farm ownership. Marketing agencies adopt browser-based collaboration platforms.
Industry Challenges
- Real-time technical artist scarcity:Shader programming and engine optimization skills command wage premiums. Training pipelines lag behind production demand.
- Generative content authentication:Provenance tracking integration extends delivery timelines. Client education requirements add project management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Animation Market |
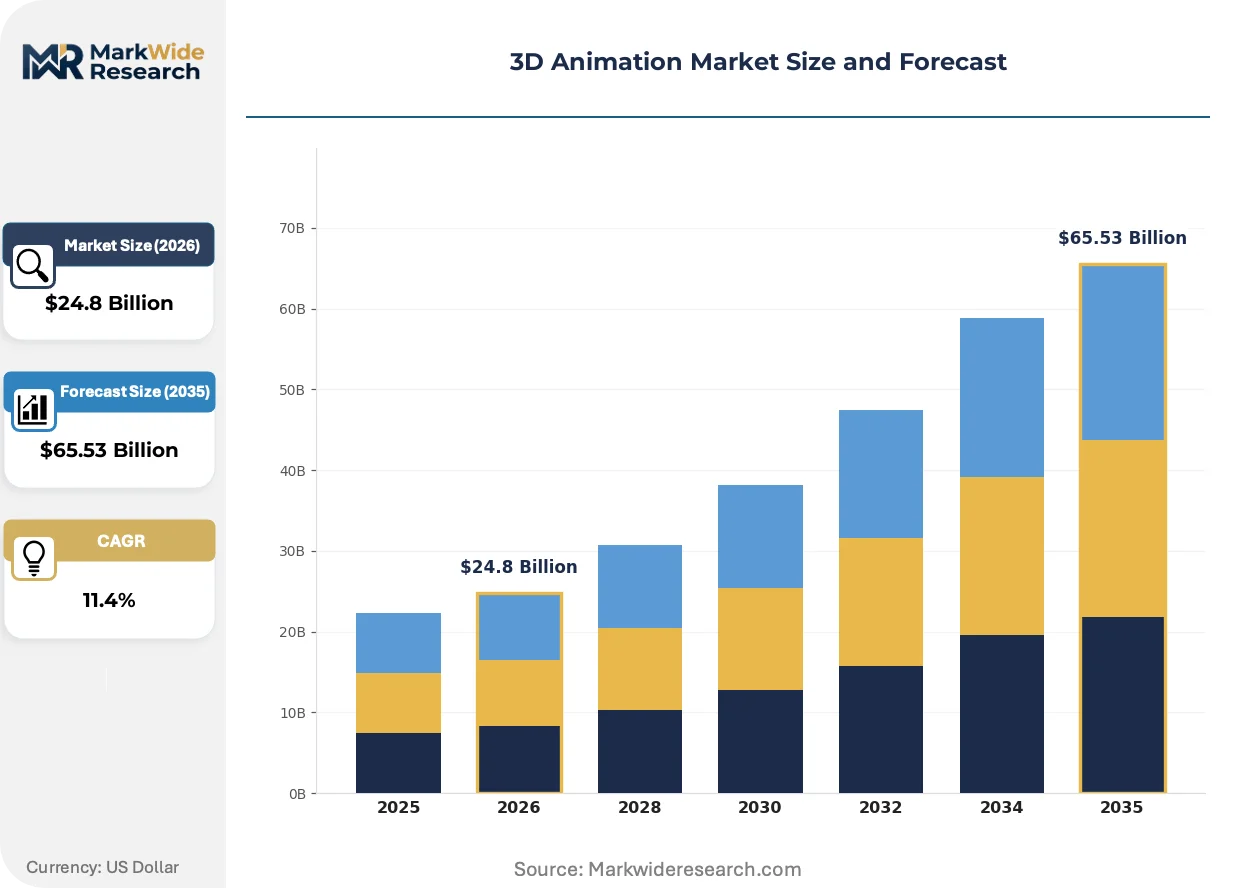
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $65.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Entertainment, Advertising, Education, Virtual Reality, Architecture, Simulation Technology: Motion Capture, Rotoscoping, Procedural Animation, Keyframe Animation, Physics-Based Animation, Cel Animation End User: Game Developers, Marketing Agencies, Educational Institutions, Architectural Firms, Simulation Providers, Content Creators Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Platforms, Desktop Software |
| Companies Covered | Sony Pictures Animation, Arktek 3D Studio, Pixar Animation Studios, OmegaRender, The Motion Tree, Walt Disney Animation Studios, Illumination, DBOX, DreamWorks Animation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Animation Market Strategic Shifts & Innovations
Neural rendering techniques are collapsing the boundary between captured and synthetic imagery, forcing studios to retrain traditional lighting and compositing specialists.
Gaussian splatting is digitizing volumetric scene representation through point-based radiance field reconstruction. Architectural visualization firms adopt this for rapid client iteration without mesh optimization delays. The technology is digitizing location-scout workflows by enabling real-time environment manipulation from photogrammetry captures.
REACH substance restrictions on certain polymer feedstocks are compelling hardware manufacturers to reformulate motion-capture suit materials. EU-based volume stages face equipment procurement timeline extensions. German production facilities accelerate supplier qualification processes to maintain stage utilization rates.
Subscription-based asset marketplaces are displacing perpetual-license content libraries among independent creators. Freelance animators in the United States prioritize modular tool procurement over integrated suite investments. This pattern concentrates in solo practitioners and small-team productions where capital flexibility outweighs feature depth.
3D Animation Market Segmentation
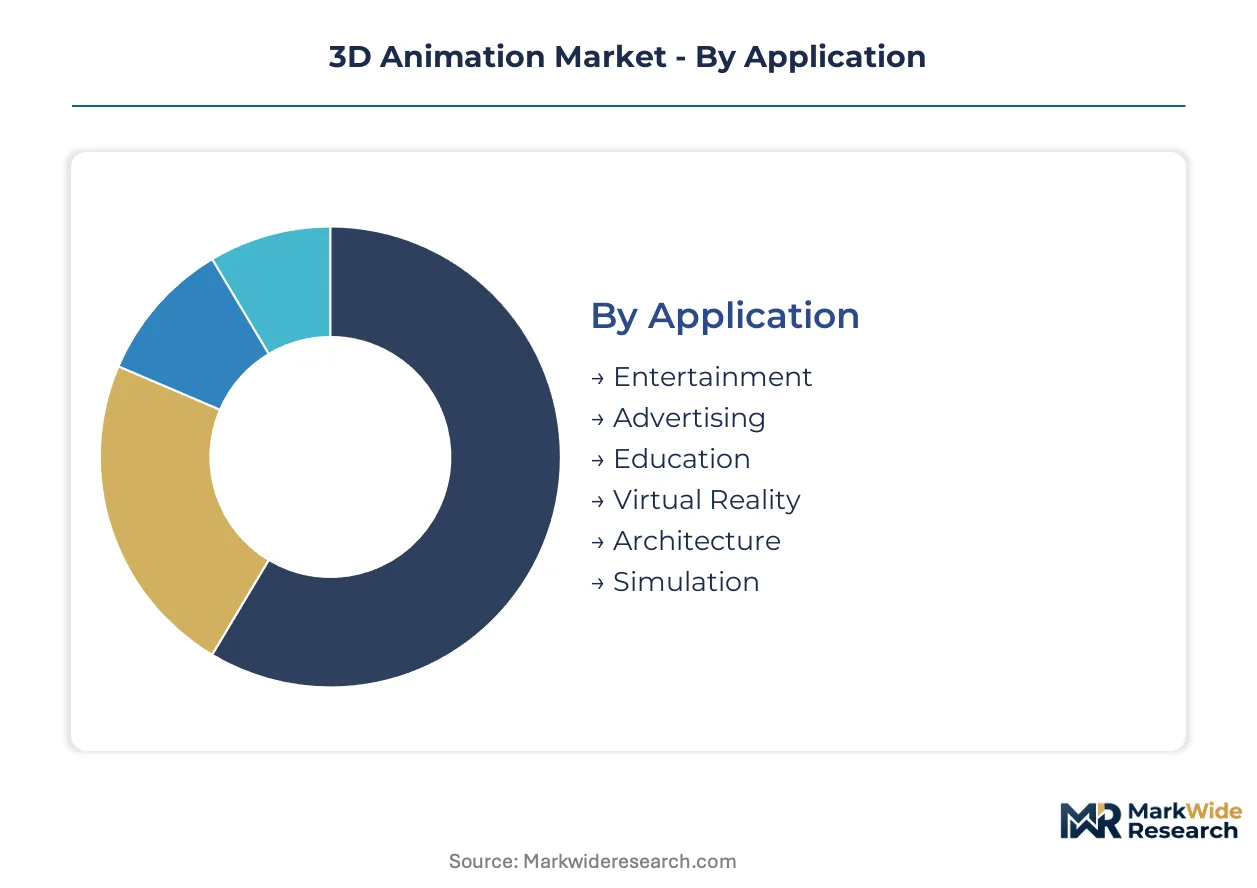
Segmentation in 3D animation reveals how divergent technical requirements and budget tiers fragment procurement patterns. Studios configure entirely different infrastructure stacks depending on whether they serve cinematic entertainment or real-time architectural walkthroughs.
Application:
Application segments map directly to production budget tiers and frame-rate requirements, from 24fps cinematic delivery to 90fps VR immersion.
- Entertainment:Feature films and episodic series demand 4K-8K offline rendering with path-traced lighting. Los Angeles and Vancouver facilities concentrate volume-stage investment for virtual production. EU AI Act disclosure mandates reshape metadata pipelines for generative-assisted sequences.
- Advertising:Campaign cycles compress delivery windows to days rather than months. Motion capture stages in New York and London prioritize rapid turnaround over pixel-perfect refinement.
- Virtual Reality:Real-time stereoscopic rendering at 90fps minimum strains GPU allocation. Medical and military simulation providers drive hardware specification premiums.
- Education:Institutional procurement favors perpetual licenses over subscription burn. K-12 districts and universities prioritize browser-accessible tools with minimal IT footprint.
- Architecture:Real-estate marketing budgets shift toward interactive walkthroughs pre-construction. Unreal Engine and Unity dominate this segment for real-time client iteration.
- Simulation:FDA-certified surgical training modules require geometric accuracy validation. Physics engines must pass regulatory scrutiny before deployment.
Entertainment commands the established base. The steepest expansion runs through Virtual Reality.
Technology:
Technology categories stratify by the ratio of artist labor to computational automation in production pipelines.
- Motion Capture:Optical and inertial systems record performer kinematics for digital character translation. Volume stages in Los Angeles, London, and Auckland sustain premium day rates for feature production. Real-time facial capture reduces post-production iteration cycles.
- Physics-Based Animation:Rigid-body and fluid simulations compute behavioral dynamics without keyframe intervention. Automotive crash testing and cloth simulation for fashion visualization drive adoption.
- Keyframe Animation:Traditional pose-to-pose methodology persists where artistic intent overrides physical accuracy. Independent animators and prestige feature work retain this craft-intensive approach.
- Procedural Animation:Algorithmic generation populates crowd scenes and environmental detail. Game engines integrate Houdini-derived tools for runtime variation.
- Rotoscoping:Traced reference footage underlies stylized motion in adult animation. Netflix and HBO Max commissions sustain specialized boutique houses.
- Cel Animation:Two-dimensional aesthetic rendered through 3D pipelines preserves hand-drawn visual language. Japanese production studios hybridize this with polygonal environments.
Motion Capture holds the revenue concentration. Physics-Based Animation is climbing the fastest as simulation fidelity demands intensify.
End User:
End user categories reflect fundamentally different procurement cadences, from enterprise capital cycles to freelance tool subscriptions.
- Game Developers:Real-time engine integration demands shader programming and technical art specialization. AAA studios in Tokyo, Montreal, and Stockholm maintain proprietary toolchains. Indie developers rely on Unity and Unreal marketplace assets.
- Marketing Agencies:Campaign-driven workflows prioritize elastic cloud compute over render farm ownership. Browser-based collaboration platforms displace desktop suite procurement.
- Content Creators:Solo practitioners and micro-studios subscribe to modular asset libraries rather than integrated suites. YouTube and TikTok monetization drives tool investment thresholds.
- Architectural Firms:Visualization departments contract external studios or build internal real-time capabilities. Client presentation requirements determine pipeline selection.
- Simulation Providers:Medical and defense contractors pursue FDA and military certification for training content. Accuracy validation extends delivery timelines.
- Educational Institutions:Curriculum integration and site licensing dominate procurement evaluation. Autodesk and Adobe education pricing shapes adoption.
Game Developers anchor the spending base. Marketing Agencies are gaining share fastest as real-time advertising formats proliferate.
Deployment:
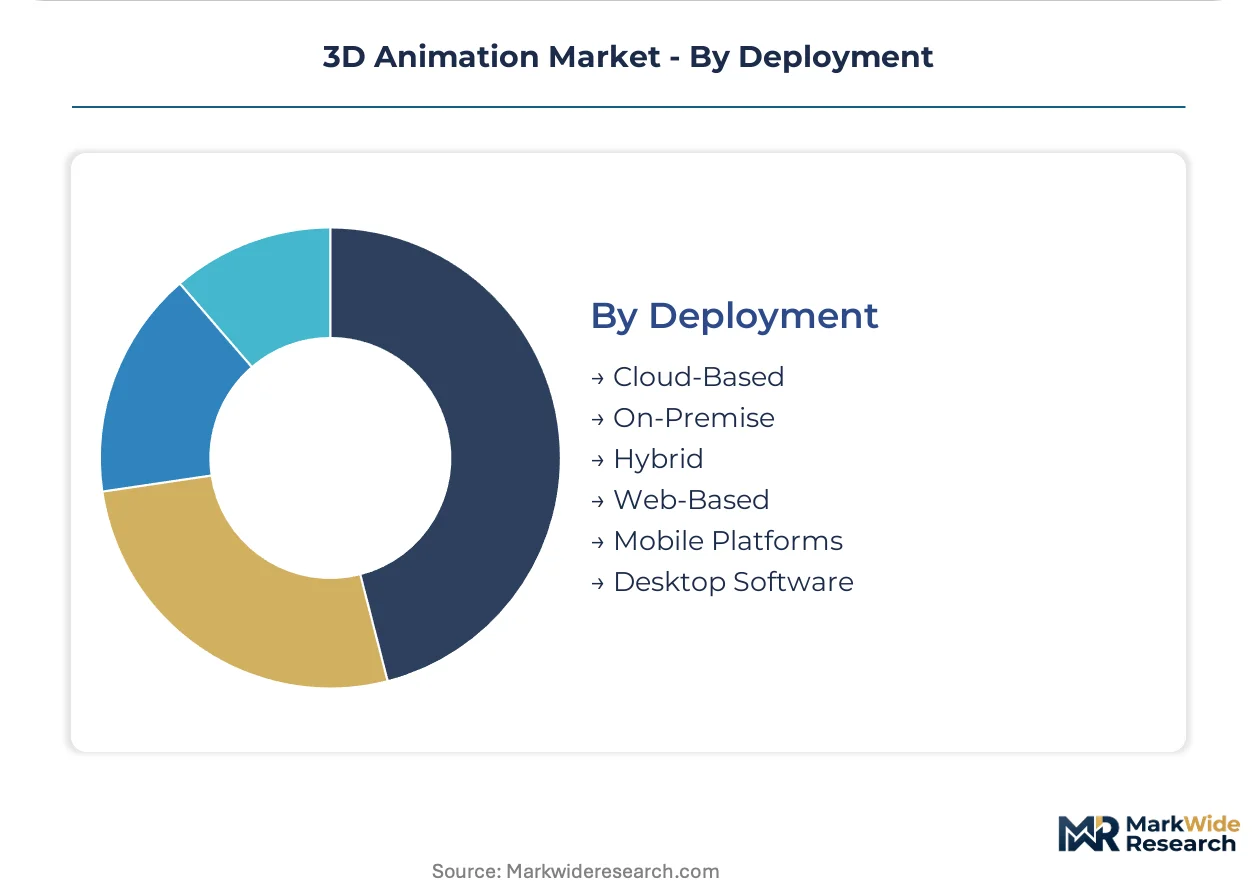
Deployment modes segment by capital intensity preference and data sovereignty requirements across studio types.
- Cloud-Based:Elastic compute subscriptions eliminate render farm capital expenditure. Marketing agencies and mid-tier entertainment producers adopt this for burst capacity during delivery crunches.
- On-Premise:Dedicated render farms and workstation clusters protect intellectual property and minimize latency. Major feature studios in Burbank and Emeryville maintain this architecture for security-sensitive projects.
- Hybrid:Core asset development on-premise with cloud burst for final rendering optimizes cost and control. Emerging as the dominant configuration for studios above fifty employees.
- Web-Based:Browser-accessible editors target education and rapid prototyping segments. Limited by GPU API constraints and asset library integration.
- Desktop Software:Perpetual license holdouts persist in institutional and government contracting where subscription accounting complicates budgeting.
- Mobile Platforms:Tablet and smartphone-based tools enable location scouting reference capture and rough blocking. Not yet viable for final production delivery.
On-Premise retains the installed base. Hybrid configurations are expanding most quickly as studios optimize capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States studios prioritize cinematic virtual production pipelines. European markets emphasize regulatory-compliant generative workflows. Asian markets concentrate on real-time engine optimization for mobile and interactive formats.
United States
Feature film production and advertising campaigns drive volume demand. FCC content guidelines govern broadcast animation standards. Los Angeles and Vancouver anchor the continent's largest volume-stage clusters, with facilities expanding real-time capture capabilities for streaming content.
United Kingdom
Advertising and episodic series production compress delivery timelines. Advertising Standards Authority codes influence content clearance workflows. London motion-capture stages prioritize rapid-turnaround commercial work over cinematic refinement.
Germany
Industrial visualization and automotive simulation anchor demand. REACH substance restrictions compel hardware manufacturers to reformulate motion-capture suit materials. Berlin and Munich studios accelerate supplier qualification to maintain stage utilization.
Japan
Cel-shaded hybrid production and game-engine animation dominate output. METI technology promotion programs support real-time rendering R&D. Tokyo and Osaka studios integrate polygonal environments with hand-drawn aesthetic preservation.
Canada
Vancouver facilities capture spillover demand from Los Angeles production overflow. Federal and provincial tax incentives structure studio location decisions. Toronto emerging as a secondary cluster for educational and simulation content development.
3D Animation Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. Premium cinematic pipelines cluster around studios with proprietary renderer technology and decades of feature production expertise. Mid-tier service providers compete on turnaround speed and vertical specialization. Dominant competitive moves include strategic technology licensing partnerships and cloud infrastructure co-development agreements.
Within the premium cinematic tier, Pixar Animation Studios and DreamWorks Animation exemplify renderer-anchored competitive positioning. Pixar leverages RenderMan licensing to external clients while maintaining internal pipeline dominance. DreamWorks sustains pressure through MoonRay development and cloud-optimized infrastructure. OmegaRender occupies a distinct position in architectural visualization services, operating below entertainment-focused margin tiers.
| Leading Market Players |
|---|
| Sony Pictures Animation |
| Arktek 3D Studio |
| Pixar Animation Studios |
| OmegaRender |
| The Motion Tree |
| Walt Disney Animation Studios |
| Illumination |
| DBOX |
| DreamWorks Animation |
| Others |
Cost & Logistics Intelligence
Taiwan-based foundry capacity constraints for high-end GPUs determine both pricing tier spreads and supply chain shape in 3D animation infrastructure procurement. GPU supply bottlenecks compress margins for cloud render services while amplifying premiums for on-premise hardware ownership, forcing studios to restructure procurement between capital expenditure and operational expenditure models.
Pricing Analysis
Project-based contracts dominate cinematic production while subscription tiers capture marketing agency and independent creator segments. Price differentiation rests on rendering resolution certification and real-time capability guarantees, with FDA-validated medical simulation content commanding substantial premiums. Cost compression in mid-tier architectural visualization intensifies as browser-based tools proliferate. Freelance animators exhibit highest price sensitivity, while defense contractors and major feature studios prioritize performance guarantees over unit economics.
Supply Chain Analysis
TSMC and Samsung Foundry hold decisive capacity for AI-training and rendering-optimized GPUs that feed animation infrastructure deployment. Manufacturing concentrates in Taiwan, South Korea, and select United States facilities for advanced node production. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized substrates. Single-source vulnerability around CoWoS packaging capacity creates procurement timeline risk. Distribution runs through authorized component distributors and direct cloud-service provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time rendering adoption in medical training and architectural marketing signals early-cycle expansion with substantial runway ahead. Penetration in FDA-certified simulation and interactive real-estate visualization remains below saturation thresholds across major markets.
For Market Incumbents: Pre-empt generative AI disruption by accelerating provenance-tracking infrastructure investment ahead of EU AI Act enforcement waves. Secure exclusive volume-stage capacity in Los Angeles and Vancouver through multi-year lease structures. Deepen backward integration into proprietary render engine development to escape middleware licensing dependencies.
For New Entrants and Emerging Players: German industrial visualization and Japanese cel-shaded hybrid production represent geographic underpenetration with accessible entry points. Mid-market architectural walkthrough services in secondary Canadian and UK cities offer lower competitive density. Pursue browser-native tool positioning to bypass established desktop suite procurement cycles.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized infrastructure plays over horizontal software consolidation. Five-to-ten year viability hinges on regulatory compliance architecture and real-time technical artist pipeline development. Target acquisition profiles center on volume-stage operators with proven European commissioning relationships. Monitor GPU supply normalization and EU AI Act implementation timelines as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Provenance-Tracking Infrastructure Investment | EU AI Act disclosure mandates compel metadata pipeline upgrades for competitive bidding qualification. |
| Volume-Stage Capacity Expansion | Los Angeles and Vancouver facility investments capture spillover demand from streaming content acceleration. |
| Medical Simulation Certification | FDA validation pathways unlock healthcare vertical premiums for specialized studio capabilities. |
| Cloud-Native Tool Development | Browser-based platforms displace capital-intensive render farm ownership among marketing agencies. |
| Real-Time Engine Optimization | Unreal Engine and Unity integration expertise commands wage premiums as technical artist scarcity intensifies. |
Research Approach
Initial hypotheses were tested against primary input from animation studio technology officers, cloud infrastructure procurement leads, volume-stage operations managers, and medical simulation content directors and refined through secondary validation. Primary fieldwork drew from SEC filings of listed entertainment technology providers, hyperscaler capex disclosure reports, EU regulatory documentation, and industry association production surveys. Bottom-up project pipeline enumeration triangulated against top-down market sizing from equipment manufacturer shipment data.
Demand-supply balance modeling across the projection horizon incorporated deployment mode segmentation, application-specific frame-rate requirements, and end-user procurement cadence differentiation. CAGRs were derived from slope analysis of technology adoption curves and capacity expansion announcements. Industry-specific inputs included GPU supply allocation forecasts, volume-stage utilization rates, and regulatory implementation timelines.
Practitioners should monitor GPU foundry capacity announcements, EU AI Act delegated act publications, and real-time technical artist wage indices for early signals of forecast revision. Quarterly review of volume-stage booking backlogs, cloud render pricing volatility, and generative AI disclosure compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Webcomics Market
Digital Media
ACGN Subculture Market
Digital Media
LED Stadium Screens Market
Digital Media
Digital Music Services Market
Digital Media
Middle East Media and Entertainment Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Middle East and Africa Animation Market
Digital Media
Adult Entertainment Market
Digital Media
Anime Market
Digital Media
Entertainment Transcription Market
Digital Media
India Webtoons Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Entertainment Market
Digital Media
Video Player Market
Digital Media
Sound Effects Services Market
Digital Media
Media Coding Service Market