
 Pro AV Market | 2026-2036
Pro AV Market Size, Share, and Industry Trends Forecast 2026-2036
Pro AV Market Intelligence
Buyer concentration in the Pro AV Market is shifting as corporate IT departments consolidate vendor relationships while education and government procurement fragments across regional integrators. Crestron leverages its control-system ecosystem to anchor enterprise accounts with tightly integrated automation platforms. QSC Audio Products sustains competitive positioning through in-house amplification and loudspeaker manufacturing that spans live events and installed sound. Legrand | AV dominates connectivity infrastructure with structured cabling and signal distribution portfolios that feed downstream display and switching deployments.
Professional audiovisual systems encompass engineered hardware and software for commercial-grade sound reinforcement, video distribution, and environmental control, typically operating across 20 Hz to 20 kHz audio bandwidths with 4K/8K video throughput and sub-10 millisecond latency for live synchronization. These systems serve primary commercial purposes in corporate collaboration, broadcast production, and public venue entertainment where reliability and scalability override consumer-grade specifications. Displays and video switchers command the largest installed base across live events and digital signage applications where pixel density and seamless source routing determine competitive viability. Audio systems and wireless technology segments are expanding fastest in conferencing and education deployments as IT managers prioritize cable-free flexibility and cloud-managed firmware updates.
FCC equipment authorization requirements shape RF-based wireless AV product development timelines in the United States, while CE marking and RoHS compliance govern electromagnetic compatibility and substance restrictions for European market access. China's MIIT enforces GB standards for wireless transmission power that directly constrain microphone and presentation system specifications. Stakeholders must monitor evolving HDMI specification releases and emerging government procurement sustainability mandates to align product roadmaps with compliance windows and buyer evaluation criteria.
Market Dynamics
Hybrid work permanence is compressing refresh cycles for corporate conferencing infrastructure as IT departments prioritize interoperability certification over brand loyalty in vendor selection.
Growth Catalysts
- HDMI 2.1 specification adoption:Broadcast and live event venues in the United States are mandating 48Gbps bandwidth support for uncompressed 8K distribution, forcing upgrade waves across switching and display estates.
- Germany's federal building efficiency mandates:Public sector procurement now requires AV systems with embedded power management and automated standby protocols, creating specification pull-through for control platforms.
- Cloud-native firmware architectures:Education and healthcare facilities in China are prioritizing MIIT-compliant wireless presentation systems with over-the-air update capabilities to reduce on-site maintenance visits.
Market Restraints
- Semiconductor allocation constraints:FPGA and high-speed SerDes chip supply concentrates with Taiwan-based foundries, extending lead times for video processing hardware by 16-24 weeks.
- Wireless spectrum congestion:FCC Part 15 unlicensed device density in urban United States markets is triggering interference mitigation costs and site survey complexity for microphone deployments.
- Copper and rare earth magnet volatility:Loudspeaker driver and cable manufacturing faces input cost pressure from commodity price swings in neodymium and oxygen-free copper.
Strategic Opportunities
- India's smart city infrastructure rollout:Municipal digital signage and public address networks remain underpenetrated, with BIS certification creating a compliance moat for early entrants.
- Software-defined audio networking:Convergence of Dante, AES67, and Milan protocols is enabling single-cable campus-wide audio distribution that displaces analog snake infrastructure.
- EU Green Deal procurement criteria:Public tenders in France and Germany now weight embodied carbon and repairability scores, favoring modular hardware with field-replaceable subassemblies.
Industry Challenges
- Network security certification backlog:Enterprise IT departments are demanding SOC 2 Type II and ISO 27001 attestation for AV-over-IP endpoints, extending vendor sales cycles by 4-6 months.
- Legacy control protocol fragmentation:RS-232, IR, and proprietary serial integrations in existing installed bases complicate cloud-managed platform migrations without rip-and-replace capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pro AV Market |
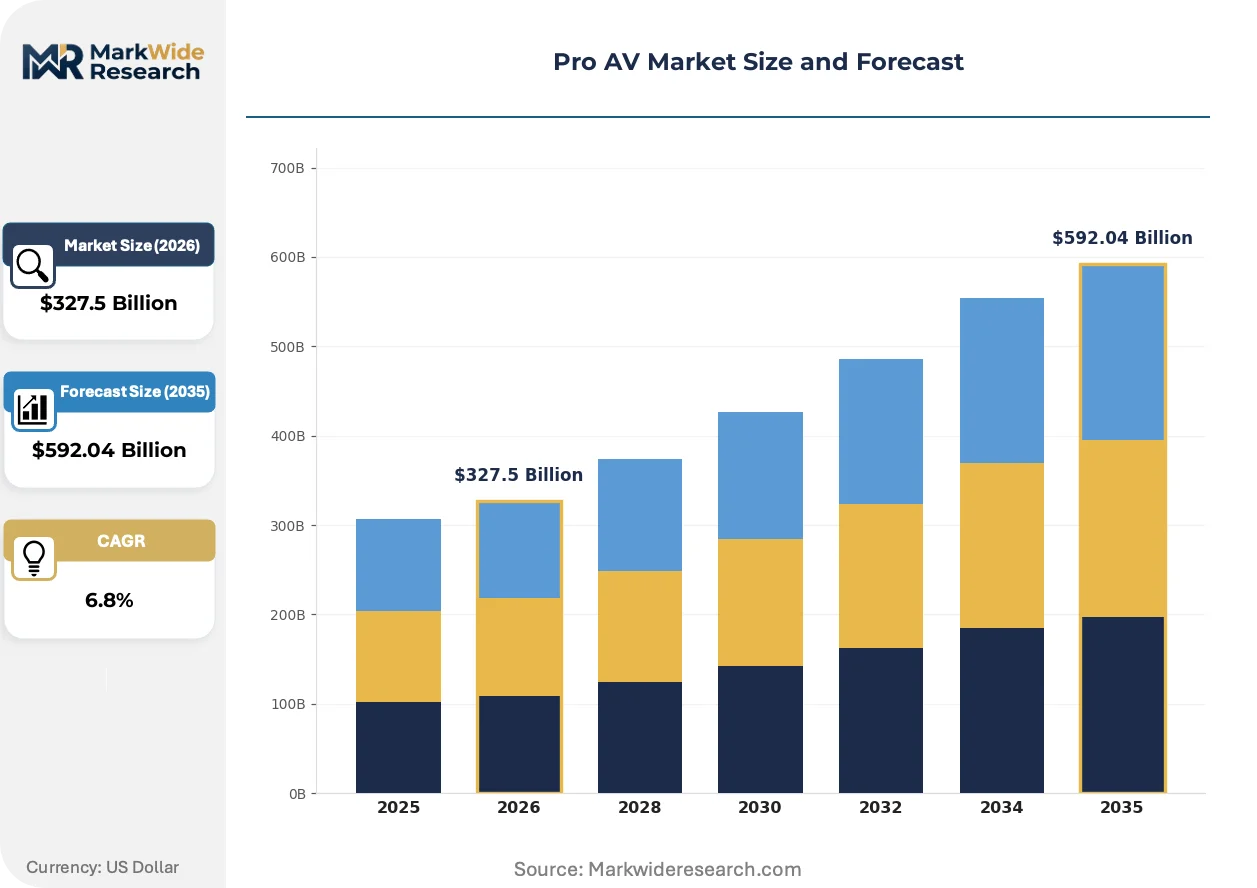
| Market Size in 2026 | $327.5 Billion |
| Market Size in 2035 | $592.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Audio Systems, Projectors, Video Switchers End User: Corporate, Education, Government, Entertainment Technology: LED, LCD, Wireless, HDMI Application: Live Events, Conferencing, Digital Signage, Broadcasting |
| Companies Covered | Ford AV, Vistacom, Crestron, StormAudio, Corporate Optics, QSC Audio Products, AVI Systems, Legrand | AV, Harman Luxury Audio Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pro AV Market Strategic Shifts & Innovations
AV-over-IP transport is displacing dedicated matrix switching as the dominant signal distribution architecture, compressing hardware margins while expanding software licensing revenue pools.
USB-C with DisplayPort Alt Mode is absorbing the connectivity layer across huddle rooms and hot-desking installations. Corporate real estate teams in the United States are standardizing on single-cable docking for BYOD scenarios. This convergence is absorbing dedicated HDMI and VGA infrastructure from new build specifications, collapsing the addressable market for legacy switcher categories.
China's MIIT is tightening GB standard enforcement for wireless transmission power in unlicensed bands, directly constraining microphone range specifications for products seeking domestic market access. Manufacturers are responding with adaptive frequency hopping algorithms and localized SKU fragmentation. The compliance burden falls heaviest on presentation and collaboration hardware targeting education and government verticals.
IT department ownership of AV procurement is displacing traditional facilities-driven purchasing across Fortune 500 accounts in Germany and the United States. Network operations centers now evaluate endpoints on VLAN segmentation, certificate-based authentication, and API programmability rather than audiovisual performance metrics alone. This shift is most visible in financial services and pharmaceutical headquarters where cybersecurity governance overrides legacy vendor relationships.
Pro AV Market Segmentation
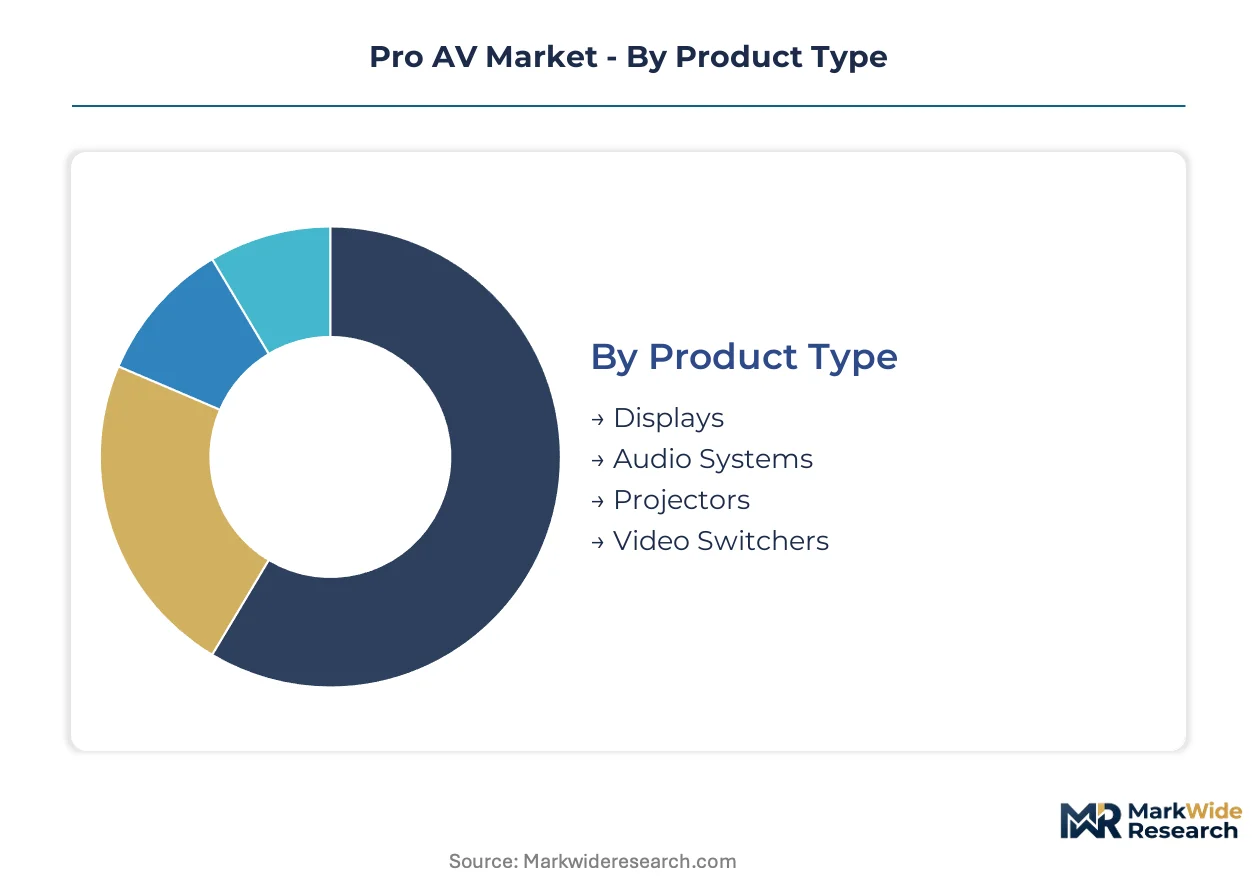
Pro AV procurement splits sharply between volume-driven refresh cycles in education and government, and premium specifications in broadcast and live event verticals. Understanding where buyers prioritize cost efficiency versus performance benchmarks determines vendor portfolio construction and channel strategy.
Product Type:
Volume concentration sits with display panels, while premium capture flows to integrated control and switching platforms that anchor enterprise accounts.
- Displays:LCD and direct-view LED panels dominate physical installed base across digital signage and conferencing deployments. Corporate real estate teams in the United States specify 4K minimum resolution with sub-3mm bezel widths for video wall configurations, compressing margins on commodity SKUs while sustaining premium tiers for HDR-capable fine-pitch LED.
- Audio Systems:Line arrays and networked loudspeakers integrate DSP and amplification into single-enclosure designs that reduce rack footprint. Germany's federal building mandates for energy-efficient standby modes are accelerating specification of PoE-powered ceiling speakers in public sector conference rooms.
- Projectors:Laser phosphor light engines displace lamp-based units in museum and higher education installations where maintenance access is costly.
- Video Switchers:Hardware-based matrix routing faces margin pressure from AV-over-IP software licensing models.
Today's leader: Displays. Tomorrow's challenger: Video Switchers.
End User:
Corporate IT departments consolidate vendor relationships around interoperability certification, while education and government procurement fragments across regional integrators with localized service capabilities.
- Corporate:Hybrid work permanence compresses refresh cycles for huddle room and boardroom infrastructure. Fortune 500 network operations centers evaluate endpoints on VLAN segmentation and API programmability rather than audiovisual performance metrics alone, with cybersecurity governance overriding legacy vendor relationships in financial services and pharmaceutical headquarters.
- Education:K-12 and university facilities prioritize cable-free flexibility and cloud-managed firmware updates to reduce on-site maintenance visits. China's MIIT-compliant wireless presentation systems with over-the-air update capabilities are gaining specification in smart campus deployments.
- Government:Public sector tenders in France and Germany weight embodied carbon and repairability scores, favoring modular hardware with field-replaceable subassemblies.
- Entertainment:Live event venues mandate 48Gbps bandwidth support for uncompressed distribution, forcing upgrade waves across switching estates.
Corporate procurement anchors current revenue; education verticals are climbing the fastest as federal connectivity subsidies flow into institutional infrastructure.
Technology:
Connectivity standards and display architectures are bifurcating between mature LCD cost curves and emerging LED performance tiers.
- LED:Direct-view fine-pitch panels below 1.5mm pixel pitch displace projection in broadcast studios and corporate flagship locations where ambient light rejection and seamless scaling override legacy lamp-based economics.
- LCD:Volume manufacturing concentration in East Asian panel fabs sustains cost leadership for sub-85" conferencing displays, though differentiation has collapsed to bezel width and color calibration services.
- Wireless:Adaptive frequency hopping algorithms respond to China's tightened GB standard enforcement for unlicensed band transmission power, fragmenting SKUs between domestic and export configurations.
- HDMI:Specification 2.1 adoption with 48Gbps bandwidth support is becoming mandatory for broadcast and live event venues, extending hardware refresh timelines.
LCD owns installed base economics; LED is gaining share fastest in premium venue replacement cycles.
Application:
Conferencing infrastructure carries the steepest near-term growth trajectory as hybrid work models mature, while live events recover toward pre-pandemic capital deployment levels.
- Live Events:Touring and fixed installation sound reinforcement demand integrated amplification and loudspeaker manufacturing that spans rapid deployment and long-term reliability. Copper and rare earth magnet volatility in driver manufacturing creates input cost pressure that concentrates procurement with vertically integrated suppliers.
- Conferencing:USB-C with DisplayPort Alt Mode is absorbing connectivity layers across huddle rooms and hot-desking installations. Single-cable docking standardization for BYOD scenarios is collapsing addressable markets for legacy switcher categories.
- Digital Signage:Municipal networks in India's smart city infrastructure rollout remain underpenetrated, with BIS certification creating compliance moats for early entrants.
- Broadcasting:8K distribution requirements and HDR workflows sustain premium specification tiers despite smaller absolute unit volumes.
Conferencing commands current investment priority; digital signage in emerging economies offers the most open competitive terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise AV infrastructure spending concentrates differently across mature economies, with the United States and Germany prioritizing cybersecurity-certified conferencing systems while China and India scale smart campus and municipal deployments under distinct regulatory frameworks.
United States
Fortune 500 headquarters in financial services and pharmaceuticals drive premium conferencing refresh cycles where FCC Part 15 compliance for wireless microphones intersects with enterprise IT security governance. Network operations centers evaluate endpoints on VLAN segmentation and API programmability rather than legacy AV performance metrics alone. Installation density peaks in New York Metro and Greater Boston corridors where hybrid work permanence sustains huddle room buildouts.
Germany
Federal building efficiency mandates from Berlin accelerate specification of PoE-powered ceiling speakers and control platforms with embedded power management across public sector conference rooms. The EU Green Deal procurement criteria weight embodied carbon and repairability scores, favoring modular hardware with field-replaceable subassemblies. Industrial demand clusters in Bavaria and North Rhine-Westphalia where automotive and chemical headquarters maintain broadcast-grade presentation facilities.
China
MIIT enforcement of GB standards for wireless transmission power constrains microphone range specifications, fragmenting SKUs between domestic and export configurations. Education and healthcare facilities in the Yangtze River Delta prioritize MIIT-compliant wireless presentation systems with over-the-air firmware updates to reduce on-site maintenance visits. Smart campus deployments in Beijing-Tianjin-Hebei absorb substantial LED display and networked audio volumes.
India
Municipal digital signage and public address networks remain underpenetrated across smart city infrastructure rollouts, with BIS certification creating compliance moats for early entrants in surveillance-integrated AV systems. Federal connectivity subsidies flow into institutional infrastructure in Maharashtra and Karnataka, accelerating education vertical procurement. Regional integrators dominate project execution outside Delhi-NCR and Mumbai metropolitan clusters.
Japan
METI industrial standards and JIS certification requirements shape product development timelines for broadcast and corporate presentation hardware targeting domestic enterprise accounts. Precision manufacturing heritage sustains demand for high-reliability switching and signal processing in Tokyo-Osaka corridor financial headquarters. Aging facility infrastructure in Kansai region drives replacement cycles for lamp-based projection with laser phosphor alternatives.
Pro AV Market Key Industry Players
United States producers anchor the premium control-system tier; European specialists hold connectivity infrastructure positions. Market structure bifurcates between vertically integrated automation platforms and component-focused fabricators. Three archetypes dominate: ecosystem orchestrators bundling software and hardware, connectivity specialists feeding downstream switching deployments, and amplification manufacturers spanning live events and installed sound. Competitive moves concentrate on interoperability certification acquisition and cloud-native firmware architecture development.
Within the ecosystem orchestrator tier, Crestron and Legrand | AV exemplify divergent strategic positions. Crestron represents tightly integrated automation platform providers anchoring enterprise accounts through control-system ecosystems. Legrand | AV occupies the connectivity infrastructure specialist position with structured cabling and signal distribution portfolios. QSC Audio Products sits within the in-house manufacturing archetype, sustaining positioning through captive amplification and loudspeaker production that spans live events and installed sound applications.
| Leading Market Players |
|---|
| Ford AV |
| Vistacom |
| Crestron |
| StormAudio |
| Corporate Optics |
| QSC Audio Products |
| AVI Systems |
| Legrand | AV |
| Harman Luxury Audio Group |
| Others |
Cost & Logistics Intelligence
Neodymium and oxygen-free copper feedstock volatility cascades through loudspeaker driver manufacturing into tiered pricing stratification across live event and installed sound portfolios. Taiwan-based FPGA foundry allocation constraints compress margins on video processing hardware while concentrating procurement leverage with vertically integrated control-system vendors.
Pricing Analysis
Capacity additions in China's LED panel fabs are reshaping price floors for sub-1.5mm pixel pitch displays. Three-tier pricing structure across premium, standard, and economy levels separates HDR-capable fine-pitch LED from commodity LCD conferencing panels. Cost compression in switching hardware intensifies because AV-over-IP software licensing displaces dedicated matrix routing. Education verticals exhibit highest price sensitivity; broadcast and live event venues remain least sensitive due to specification mandates.
Supply Chain Analysis
Photoresist-grade semiconductor supply rests on Taiwan, South Korea, and Japan specialty producers. High-speed SerDes chips, FPGA silicon, and rare earth magnets feed from concentrated upstream nodes. Single-source vulnerability concentrates with Taiwan-based foundries for video processing hardware. Distribution runs through regional AV integrators in mature markets and project-based system integrators in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pro AV Market compounds steadily as hybrid work permanence sustains infrastructure refresh cycles across corporate real estate portfolios. Enterprise IT governance standardization creates durable demand for interoperability-certified endpoints.
For Market Incumbents: Cement ecosystem lock-in through cloud-native firmware architectures that reduce on-site maintenance visits. Deepen backward integration into PoE-powered speaker manufacturing to capture Germany's federal building efficiency mandates. Prioritize SOC 2 Type II certification investment to compress enterprise sales cycles threatened by security attestation backlogs.
For New Entrants and Emerging Players: Regional integrators in India's smart city deployments represent the most penetrable channel partner type for municipal digital signage networks. Target BIS certification early to establish compliance moats before infrastructure rollout accelerates. Pursue software-defined audio networking specialization to displace analog snake infrastructure in campus-wide deployments.
For Investors and Strategic Acquirers: Consolidation pressure builds where control-system vendors lack cloud-managed platform capabilities. Five-to-ten year viability favors modular hardware specialists with field-replaceable subassemblies aligned to EU Green Deal procurement criteria. Monitor HDMI specification release cadence as inflection indicator for hardware refresh timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Firmware Architecture | Reduces on-site maintenance visits for education and healthcare facilities in China. |
| HDMI 2.1 Certification Investment | Unlocks 48Gbps bandwidth mandates from United States broadcast venue procurement. |
| Backward Integration into Amplification | Captures margin from neodymium magnet volatility in live event loudspeaker manufacturing. |
| BIS Certification for India Entry | Establishes compliance moat in underpenetrated municipal digital signage networks. |
| Modular Hardware Platform Development | Aligns with EU Green Deal repairability scoring in France and Germany public tenders. |
Research Approach
Coverage spans the United States, Germany, China, and India, with primary inputs from each regional cluster. Primary interviews with AV system integrators, corporate IT procurement officers, broadcast engineering directors, and education facilities managers combined with secondary validation from FCC equipment authorization databases, MIIT GB standard filings, EU tender documentation, and customs trade records. Bottom-up project pipeline analysis triangulates against top-down spending estimates from enterprise real estate and public sector budget disclosures.
Segmentation granularity spans product type, end user vertical, display technology, and application use case across the projection horizon. CAGRs derive from fitted growth curves against historical refresh cycle patterns and regulatory compliance windows. Forecast inputs include hybrid work permanence indicators, HDMI specification adoption trajectories, and wireless spectrum allocation decisions from national regulators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity expansion and evolving government procurement sustainability mandates. Forecasts reflect documented assumptions regarding enterprise IT governance standardization and federal connectivity subsidy flows. Material deviation in FCC Part 15 enforcement intensity or MIIT GB standard revision timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Media Gateway Market
Digital Media
Online Entertainment Market
Digital Media
Cognitive Media Market
Digital Media
Playout Solutions Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Online Art Market
Digital Media
Photography Services Market
Digital Media
Webcomics Market
Digital Media
Media Coding Service Market
Digital Media
Digital Music Services Market
Digital Media
China Webtoons Market
Digital Media
Wedding Photography Market
Digital Media
Digital Content Locker Market
Digital Media
In Flight Entertainment Market
Digital Media
Saudi Arabia Webtoons Market
Digital Media
Asia-Pacific Animation Market