
 Asia-Pacific Inflight Entertainment and Connectivity Market | 2026-2036
Asia-Pacific Inflight Entertainment and Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Inflight Entertainment and Connectivity Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from upfront hardware sales across the Asia-Pacific Inflight Entertainment and Connectivity landscape. Panasonic Corporation leverages its satellite antenna integration expertise to capture recurring connectivity fees from regional carriers. Thales Group anchors its position through deep relationships with flag carriers in Singapore and Thailand. Safran SA specializes in lightweight seat-embedded display systems that reduce fuel burn per passenger seat.
Asia-Pacific Inflight Entertainment and Connectivity encompasses satellite-linked broadband distribution, seatback and bring-your-own-device content delivery, and real-time data transmission operating across Ku-band, Ka-band, and L-band frequencies with latency targets below 500 milliseconds for interactive applications. The primary purpose is to transform aircraft cabins into revenue-generating digital platforms while satisfying passenger connectivity expectations on long-haul routes spanning the Pacific Rim. Streaming Services and Wi-Fi Connectivity command the largest current revenue share as airlines monetize bandwidth through tiered access models. Satellite-Based Systems represent the fastest-expanding technology category as low-earth-orbit constellations from providers like OneWeb and Starlink reshape competitive economics for over-ocean routes where geostationary alternatives falter.
TRAI spectrum rules, CAAC airworthiness directives for satellite terminal certification, and Australia's ACMA radiocommunications licensing collectively shape equipment approval timelines and service launch cadences across the region. These frameworks determine which connectivity platforms gain market access and influence airline procurement specifications for next-generation retrofits. Stakeholders must monitor spectrum harmonization progress between national regulators to anticipate where satellite service providers can achieve economies of scale.
Market Dynamics
Low-earth-orbit satellite constellations are collapsing the cost economics of over-ocean connectivity, forcing incumbent geostationary providers to restructure pricing models and compress hardware refresh cycles across Asia-Pacific airline fleets.
Growth Catalysts
- TRAI spectrum allocation:India's framework for satellite connectivity above ten thousand feet enables domestic carriers to deploy Ka-band terminals without cross-border licensing delays.
- Seatback screen reconfiguration:Full-service carriers in Southeast Asia treat passenger experience as a competitive battleground, accelerating hardware replacement programs.
- Domestic aviation rebound:China's traffic volumes have exceeded pre-pandemic thresholds, creating concentrated demand for bandwidth-heavy streaming services on trunk routes.
Market Restraints
- Terminal certification timelines:CAAC airworthiness directives for satellite terminal approval extend equipment deployment schedules by twelve to eighteen months.
- Input cost volatility:Gallium arsenide and silicon germanium substrate prices fluctuate with semiconductor foundry capacity allocation, pressuring antenna component margins.
- Geostationary lock-in:Long-term bandwidth contracts with legacy satellite operators restrict carrier flexibility to adopt LEO alternatives.
Strategic Opportunities
- Secondary city penetration:Tier-two airports in Vietnam and Indonesia remain underserved by high-throughput satellite coverage, creating first-mover positioning for regional LEO resellers.
- Content platform convergence:Integration of live sports streaming with loyalty program data monetization opens ancillary revenue streams beyond connectivity fees.
- Australia's ACMA licensing:Streamlined radiocommunications permits for non-geostationary systems reduce regulatory friction for service launches across Oceania.
Industry Challenges
- RF engineering talent scarcity:Phased-array antenna design expertise concentrates in defense contractors, forcing commercial suppliers to compete for limited specialist pools.
- Retrofit integration complexity:Legacy aircraft wiring harnesses lack power and data capacity for next-generation seatback displays, requiring expensive structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Inflight Entertainment and Connectivity Market |
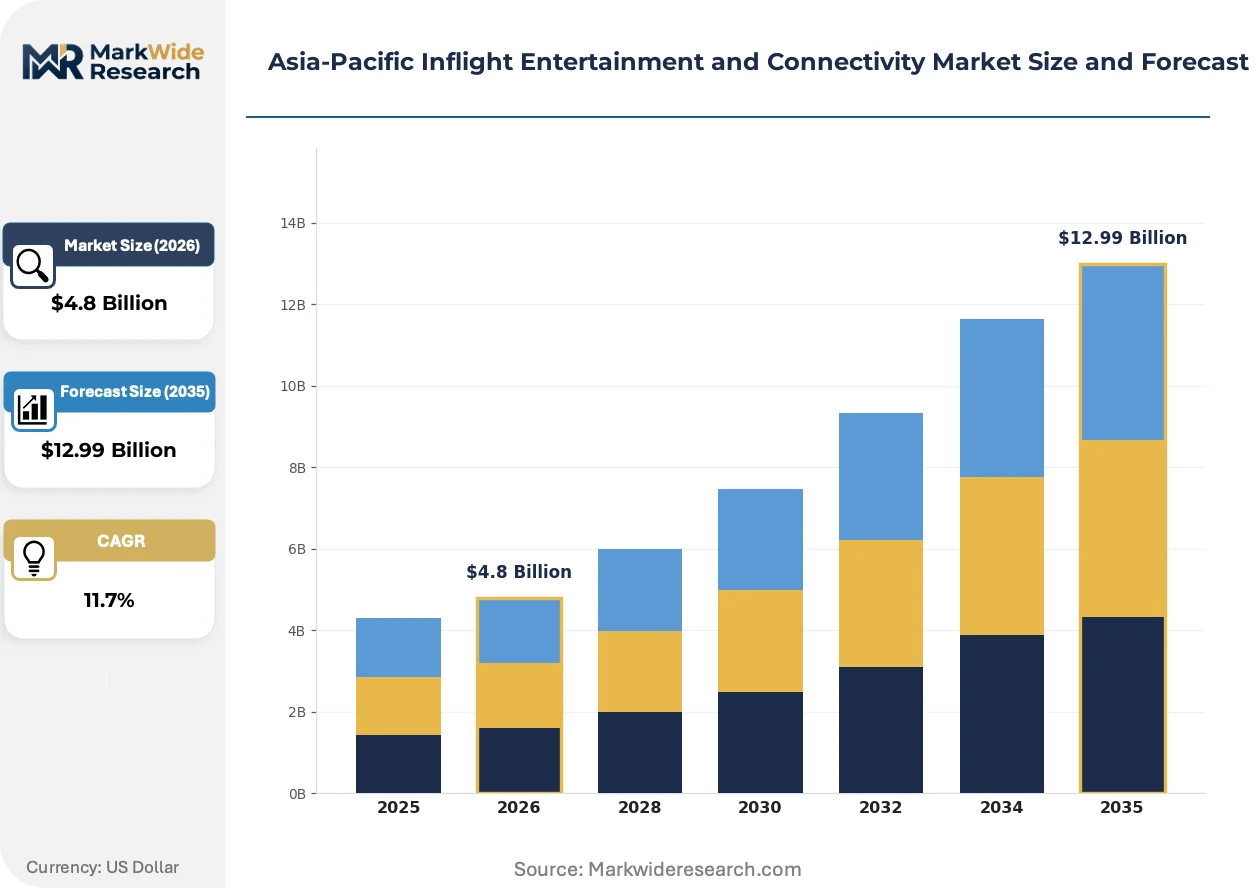
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Streaming Services, Live TV, On-Demand Content, Wi-Fi Connectivity End User: Airlines, Business Travelers, Leisure Travelers, Charter Services Technology: Satellite-Based Systems, Airborne Wi-Fi, In-Flight Entertainment Systems, Connectivity Platforms Content Type: Movies, TV Shows, Music, Games |
| Companies Covered | Envee Inflight Entertainment Co Ltd, Panasonic Corporation, Honeywell International Inc, Inmarsat Global Limited, Viasat Inc, Global Eagle, Thales Group, Safran SA, Collins Aerospace, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Inflight Entertainment and Connectivity Market Strategic Shifts
Active electronically steered antennas are collapsing the physical footprint and weight penalties of satellite connectivity hardware, enabling installations on narrow-body aircraft previously excluded from broadband retrofit programs.
Electronically steered arrays eliminate mechanical gimbals through solid-state beamforming. Regional carriers operating Airbus A320 and Boeing 737 fleets are adopting these units at triple-digit annual rates. The technology is collapsing minimum viable aircraft size thresholds for connectivity ROI, expanding addressable fleet populations across Asia-Pacific low-cost operators.
CAAC's satellite terminal certification framework mandates electromagnetic interference testing against domestic avionics standards. Manufacturers must establish in-country test facilities or partner with local aerospace institutes to obtain type approval. Chinese flag carriers delay procurement decisions until dual Ku-Ka band terminals receive unified certification, compressing vendor sales cycles.
Airlines unbundle connectivity from ticket prices, treating bandwidth as à-la-carte merchandise rather than bundled amenity. Frequent flyer programs integrate Wi-Fi passes as redemption options, displacing traditional loyalty catalog structures. This behavioral shift concentrates revenue yield management complexity in Japan and South Korea, where mileage program penetration exceeds fifty percent of active travelers.
Asia-Pacific Inflight Entertainment and Connectivity Market Segmentation
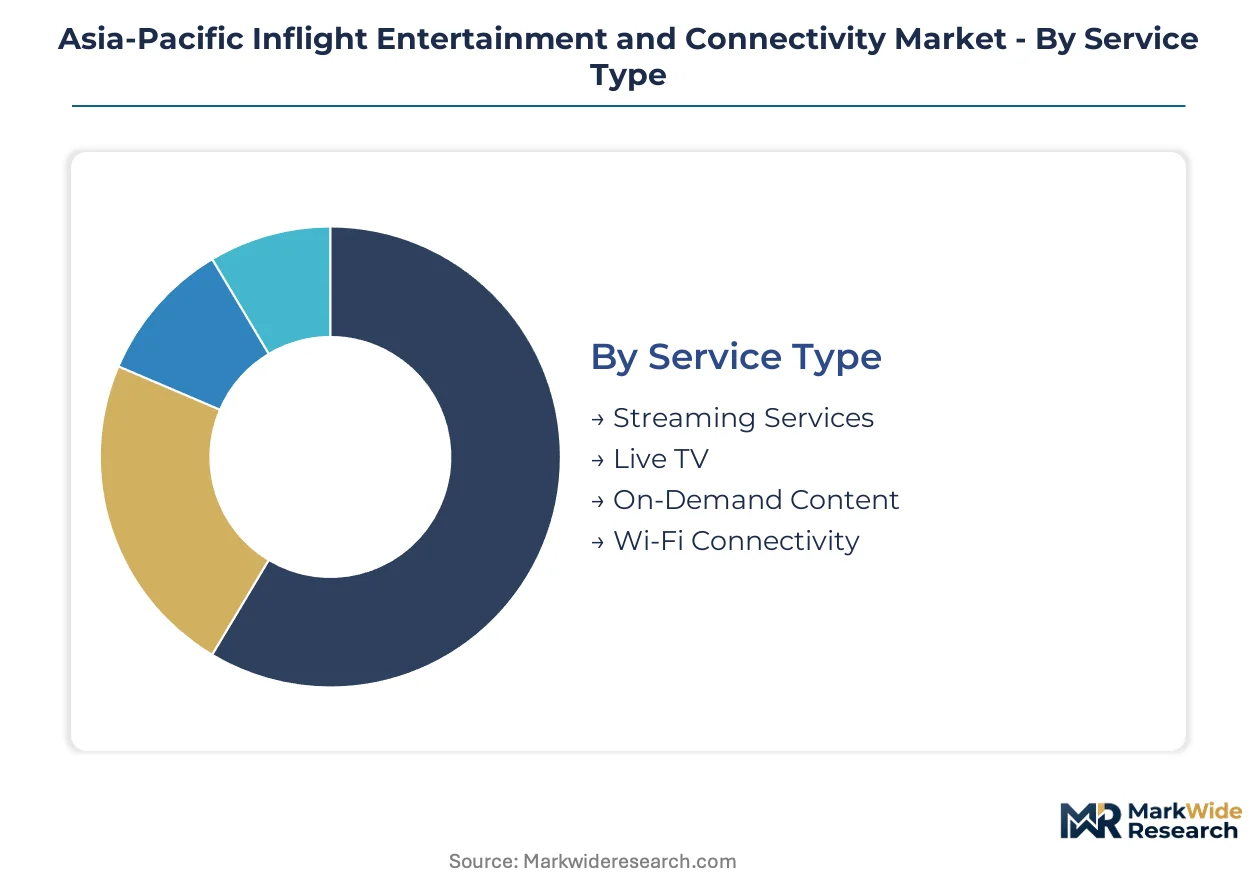
Segmentation in Asia-Pacific Inflight Entertainment and Connectivity reveals distinct procurement rhythms and margin profiles across service delivery models. Airlines structure capital deployment differently for hardware-intensive seatback systems versus recurring connectivity subscriptions, creating tiered vendor engagement strategies across the region's heterogeneous carrier base.
Service Type:
Streaming Services and Wi-Fi Connectivity turn over fastest as airlines renegotiate bandwidth contracts annually, while Live TV and On-Demand Content refresh on multi-year licensing cycles tied to studio agreements.
- Streaming Services:Bandwidth-intensive video delivery over Ku-band and Ka-band satellite links with adaptive bitrate protocols. Demand concentrates in China where domestic trunk routes carry bandwidth-heavy passenger loads exceeding pre-pandemic thresholds, driven by carrier competition for loyalty program engagement through content quality differentiation.
- Wi-Fi Connectivity:Tiered access models spanning basic messaging through full broadband with latency targets below 500 milliseconds for interactive applications. Expansion concentrates across Southeast Asian full-service carriers treating passenger connectivity as a competitive battleground on long-haul Pacific Rim routes.
- Live TV:Real-time broadcast distribution via satellite downlink with regional content localization requirements.
- On-Demand Content:Pre-loaded server-based media libraries with studio licensing windows governing refresh cadence.
Streaming Services dominates installed base revenue contribution. Wi-Fi Connectivity is where expansion concentrates.
End User:
Airlines command procurement volume as fleet-wide decision-makers, while passenger segments fragment into usage-pattern clusters with divergent willingness-to-pay profiles.
- Airlines:Fleet-scale procurement spanning hardware installation, connectivity contracts, and content licensing with 7-10 year amortization horizons. Procurement concentrates in flag carriers across Singapore and Thailand where Thales Group maintains established supplier relationships, driven by retrofit programs for next-generation seatback display deployments.
- Business Travelers:Premium connectivity subscribers requiring low-latency video conferencing and document synchronization. Demand clusters in Japan and South Korea where mileage program penetration exceeds fifty percent of active travelers, creating redemption-integrated Wi-Fi pass consumption patterns.
- Leisure Travelers:Price-sensitive casual users with intermittent messaging and entertainment streaming needs.
- Charter Services:Ad-hoc connectivity provisioning for corporate and VIP aircraft with customized service level agreements.
Airlines anchor hardware and bandwidth procurement volume. Business Travelers is where monetization sophistication concentrates.
Technology:
Satellite-Based Systems carry extended certification timelines under CAAC airworthiness directives, while Airborne Wi-Fi and Connectivity Platforms deploy through faster software-defined upgrade paths.
- Satellite-Based Systems:Ku-band, Ka-band, and L-band terminal integration with geostationary and emerging low-earth-orbit constellation compatibility. Deployment concentrates in over-ocean routes where LEO alternatives from OneWeb and Starlink are collapsing cost economics against legacy geostationary providers.
- In-Flight Entertainment Systems:Seat-embedded display hardware with lightweight design specifications reducing fuel burn per passenger seat. Adoption accelerates across narrow-body fleets previously excluded from broadband retrofit programs through active electronically steered antenna miniaturization.
- Airborne Wi-Fi:Cabin distribution networks bridging satellite terminals to passenger devices.
- Connectivity Platforms:Software layers managing authentication, billing integration, and service tier enforcement.
In-Flight Entertainment Systems dominates capital expenditure allocation. Satellite-Based Systems is where technology substitution concentrates.
Content Type:
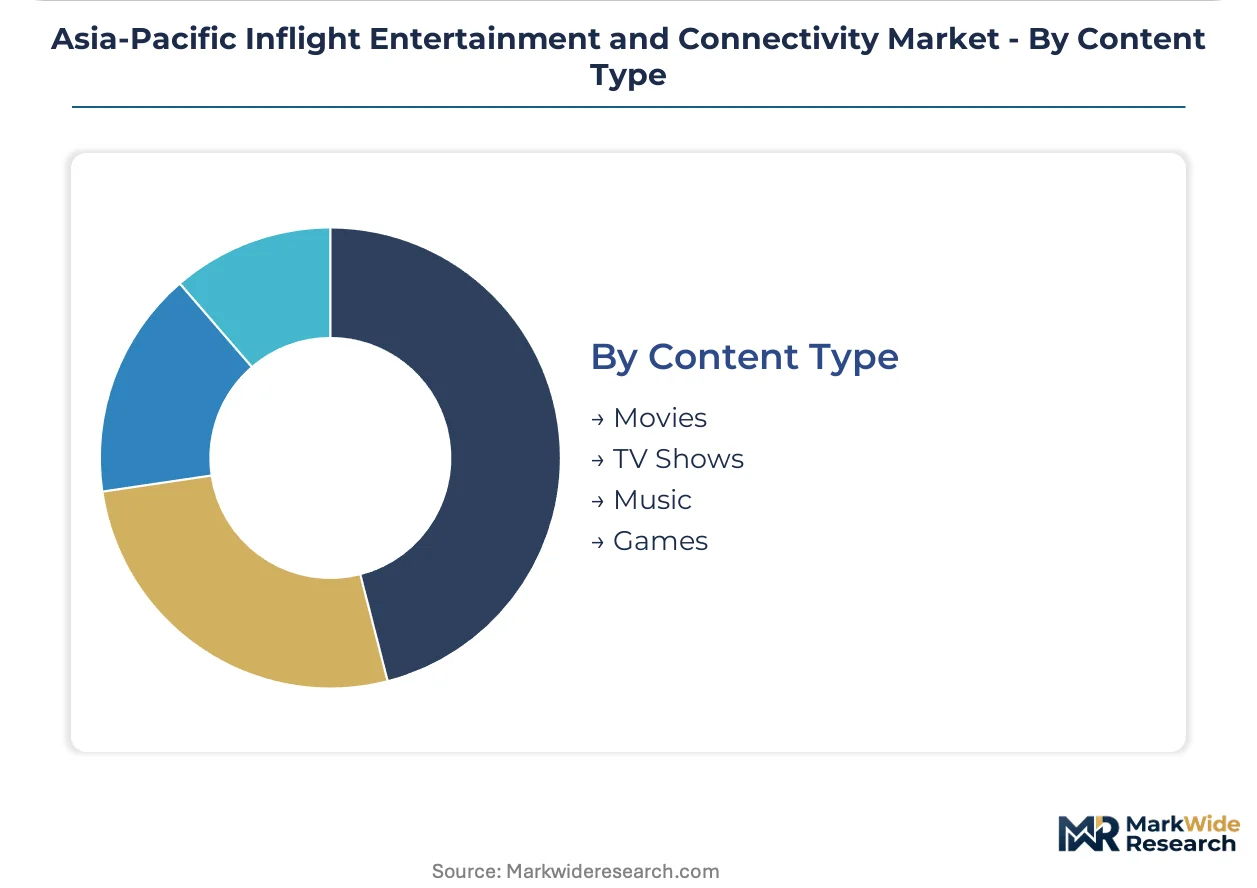
Movies and TV Shows refresh on quarterly licensing cycles with studio distributors, while Music and Games sustain longer catalog lifespans with lower renewal friction.
- Movies:First-run and library theatrical content with windowing restrictions tied to theatrical release schedules. Licensing concentrates through platform convergence strategies integrating live sports streaming with loyalty program data monetization, opening ancillary revenue streams beyond connectivity fees.
- TV Shows:Serialized episodic content with binge-release and weekly distribution models. Demand clusters in markets where unbundled connectivity pricing treats bandwidth as à-la-carte merchandise rather than bundled amenity, shifting yield management complexity toward content catalog curation.
- Music:Audio streaming and pre-loaded library access with lower bandwidth requirements than video alternatives.
- Games:Interactive casual and multiplayer titles with latency-sensitive real-time processing needs.
Movies dominates content licensing expenditure. TV Shows is where format experimentation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across the Asia-Pacific Inflight Entertainment and Connectivity Market. Flag carriers in Singapore and Australia absorb premium hardware costs without volume hesitation. Budget operators in Indonesia and Vietnam demand connectivity solutions under strict per-seat economic thresholds.
China
Domestic trunk routes now exceed pre-pandemic passenger loads, driving concentrated demand for bandwidth-heavy streaming deployments. CAAC airworthiness directives for satellite terminal certification compress vendor sales cycles as flag carriers await dual Ku-Ka band unified approvals. Shanghai and Beijing aerospace clusters host electromagnetic interference testing facilities that manufacturers must access for type certification.
India
Full-service carriers accelerate seatback screen reconfiguration programs as passenger experience emerges as a competitive differentiator. TRAI spectrum allocation frameworks for satellite connectivity above ten thousand feet eliminate cross-border licensing delays for Ka-band terminal deployment. Bengaluru and Hyderabad aviation maintenance hubs are expanding retrofit capacity to serve narrow-body fleet upgrade demand from IndiGo and Air India.
Japan
Business traveler segments exhibit sophisticated monetization patterns with mileage program penetration exceeding fifty percent of active travelers. METI coordination with international spectrum harmonization efforts shapes equipment approval timelines for next-generation connectivity platforms. Tokyo-Osaka corridor airlines are unbundling connectivity from ticket prices, treating bandwidth as à-la-carte merchandise integrated into loyalty redemption catalogs.
Australia
Long-haul Pacific Rim routes generate sustained demand for low-latency satellite solutions as airlines compete for premium passenger retention. ACMA streamlined radiocommunications licensing for non-geostationary systems reduces regulatory friction for LEO service launches across Oceania. Sydney and Melbourne maintenance facilities are specializing in active electronically steered antenna installations for Airbus A320 and Boeing 737 retrofits previously excluded from broadband programs.
Singapore
Flag carriers anchor fleet-scale procurement decisions with seven-to-ten-year amortization horizons for integrated hardware and connectivity contracts. Civil Aviation Authority of Singapore coordinates with regional regulators on spectrum harmonization to anticipate satellite service provider economies of scale. Changi aviation ecosystem concentrates vendor relationship management functions, with Thales Group maintaining established supplier positions through deep flag carrier partnerships.
Asia-Pacific Inflight Entertainment and Connectivity Market Competitive Environment
Capability concentration sits with defense-heritage electronics specialists; scale advantage sits with diversified industrial conglomerates. The Asia-Pacific Inflight Entertainment and Connectivity Market structures around three tiers: integrated satellite antenna manufacturers, seat-embedded display system fabricators, and software-defined connectivity platform operators. Strategic archetypes include full-stack hardware-software integrators, component specialists optimizing for fuel-burn reduction, and bandwidth resellers leveraging LEO constellation economics. Dominant competitive moves involve satellite antenna integration partnerships and lightweight display system portfolio diversification.
Within the integrated systems tier, Panasonic Corporation and Thales Group represent full-stack positioning across hardware and recurring connectivity revenue streams. Safran SA exemplifies the component specialist archetype with seat-embedded display systems designed for fuel efficiency optimization. These three entities anchor competitive dynamics as regional carriers weigh upfront capital deployment against long-term service contract structures.
| Leading Market Players |
|---|
| Envee Inflight Entertainment Co Ltd |
| Panasonic Corporation |
| Honeywell International Inc |
| Inmarsat Global Limited |
| Viasat Inc |
| Global Eagle |
| Thales Group |
| Safran SA |
| Collins Aerospace |
| Others |
Value Chain & Pricing Dynamics
Chinese gallium arsenide and silicon germanium substrate production concentrates upstream supply for phased-array antenna components, anchoring margin pools in recurring connectivity service contracts rather than upfront hardware sales across Asia-Pacific airline procurement cycles.
Pricing Analysis
Extended connectivity service contracts drive lifetime value capture for satellite terminal vendors. Three-tier pricing structure across premium, standard, and economy levels segments bandwidth access by latency guarantees and data caps. Price differentiation rests on certification tier under CAAC airworthiness directives and fleet-scale volume commitments from flag carriers. Cost compression in hardware components is intensifying because semiconductor foundry capacity allocation volatility pressures antenna subsystem margins. Budget operators in Indonesia and Vietnam exhibit highest price sensitivity, while Singapore and Australian flag carriers absorb premium positioning without volume hesitation.
Supply Chain Analysis
Supplier-financing facilities from Japanese trading houses and Singaporean aerospace banks extend payment terms for regional carriers undertaking narrow-body retrofit programs. Manufacturing concentrates in China, Japan, and Singapore for active electronically steered arrays and seat-embedded display systems. Raw material dependencies center on gallium arsenide substrates, silicon germanium wafers, and lightweight composite housing materials. Single-source vulnerability concentrates in defense-contractor phased-array design expertise pools. Distribution runs through airline procurement consortiums and direct OEM relationships with maintenance facility integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-earth-orbit constellation deployment constitutes a high-growth disruption reshaping competitive economics, with TRAI spectrum frameworks and CAAC terminal certification timelines determining first-mover positioning across the Asia-Pacific region.
For Market Incumbents: Entrench satellite antenna integration partnerships with flag carriers in Singapore and Thailand before LEO bandwidth resellers achieve scale. Secure backward integration into gallium arsenide substrate supply through captive semiconductor foundry arrangements. Defend against emerging component specialists by accelerating dual Ku-Ka band unified certification timelines under CAAC directives.
For New Entrants and Emerging Players: Pursue secondary city penetration across Vietnamese and Indonesian tier-two airports where high-throughput satellite coverage remains underserved. Target narrow-body fleet retrofit demand from Asia-Pacific low-cost carriers previously excluded from broadband programs. Establish go-to-market positioning through LEO constellation bandwidth resale partnerships with OneWeb or Starlink.
For Investors and Strategic Acquirers: Capital is best deployed toward full-stack hardware-software integrators with established CAAC electromagnetic interference testing capabilities and recurring connectivity revenue streams. Long-term viability over a multi-year horizon favors vendors capturing ancillary revenue through content platform convergence with loyalty program data monetization. Watch for TRAI-CAAC spectrum harmonization progress as the signal indicating where satellite service providers achieve economies of scale.
| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Partnership | OneWeb and Starlink bandwidth resale collapses cost economics for over-ocean routes. |
| Dual-Band Terminal Certification | CAAC unified Ku-Ka approval compresses vendor sales cycles for Chinese flag carriers. |
| Active Electronically Steered Antenna Miniaturization | Solid-state beamforming expands addressable fleet populations to narrow-body aircraft. |
| Content Platform Convergence | Live sports streaming integration opens ancillary revenue beyond connectivity fees. |
| Regional Maintenance Hub Specialization | Bengaluru and Sydney facilities build retrofit capacity for A320 and 737 fleets. |
Study Parameters
A spread of perspectives from airline procurement directors, satellite terminal engineering leads, regulatory affairs specialists at CAAC and TRAI, and maintenance facility operations heads converged on the working assumptions driving connectivity demand forecasts. Primary fieldwork combined structured interviews with secondary validation through customs trade data, airline fleet deployment databases, and national spectrum allocation filings. Bottom-up triangulation across equipment installation rates and top-down reconciliation against carrier capital expenditure disclosures anchored volume estimates.
Demand-supply balance modeling across the projection horizon integrated passenger traffic recovery trajectories, bandwidth consumption intensity per seat, and satellite constellation capacity expansion schedules. Segmentation dimensions spanned service delivery model, aircraft fleet type, connectivity technology tier, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical retrofit adoption patterns, with inputs including TRAI spectrum allocation implementation timelines and CAAC airworthiness directive revision cadences.
Sensitivities concentrate around LEO constellation deployment delays, semiconductor substrate price volatility, and CAAC certification timeline extensions. Forecasts reflect documented assumptions on passenger connectivity willingness-to-pay and airline unbundling adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Anime Market
Digital Media
Naruto Around Market
Digital Media
Manga Market
Digital Media
Visual Effects (VFX) Market
Digital Media
4K Content Market
Digital Media
Digital Content Market
Digital Media
Animation and VFX Market
Digital Media
Digital Rights Management in Media and Entertainment Market
Digital Media
Anime Derivatives Market
Digital Media
Art App Market
Digital Media
Global Digital Painting Market
Digital Media
Europe Online Video Platform Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Mobile Entertainment Market
Digital Media
Playout Solutions Market
Digital Media
Middle East Gaming Market