
 United States Sports Betting Market | 2026-2036
United States Sports Betting Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Betting Market Intelligence
Casual bettors are unwinding the dominance of professional gamblers as the primary revenue engine for U.S. sports wagering platforms. DraftKings leverages its daily fantasy heritage to anchor customer acquisition across state launches. FanDuel sustains market presence through aggressive parlay product engineering and live betting interfaces. BetMGM competes via casino cross-sell integration and loyalty program density in mature jurisdictions.
United States sports betting constitutes the commercial activity of placing wagers on athletic contest outcomes through licensed operators, with platforms processing bets via geofenced mobile applications that verify user location through GPS and Wi-Fi triangulation against state regulatory databases. The primary commercial purpose is to generate operator revenue through hold percentages on wagered volume while remitting state taxes and league integrity fees. Online betting commands the largest addressable base as broadband penetration and smartphone ubiquity eliminate retail dependency. Mobile apps capture the fastest expansion trajectory among product type segments, driven by in-game micro-betting and same-game parlay proliferation. Live betting concentrates margin pools through elevated vigorish and rapid price adjustment algorithms.
The National Indian Gaming Commission oversees tribal compacts that shape market access across reservation-adjacent states, while the IRS enforces reporting thresholds on winnings that influence platform withholding architecture. State gaming commissions in New Jersey, Pennsylvania, and Ohio set divergent tax rates and licensing caps that fragment operator profitability curves. Stakeholders must monitor the Supreme Court docket and federal legislative proposals for interstate compact preemption risks that could recalibrate state-by-state expansion economics.
Market Dynamics
Mobile-first wagering architectures are compressing legacy retail betting infrastructure as casual users demand frictionless account funding and same-game parlay execution through geofenced applications. This structural shift concentrates margin capture in platforms that integrate daily fantasy heritage with real-time odds adjustment engines.
Growth Catalysts
- State Regulatory Expansion:Post-PASPA jurisdiction unlocking continues to activate new licensed markets across the Midwest and Southeast corridors. Each state launch creates fresh addressable pools for mobile-first operators.
- In-Game Micro-Betting Technology:Sub-minute wagering intervals on possession-level outcomes are extending session duration and per-user monetization curves. Algorithmic price feeds enable rapid settlement without manual intervention.
- Smartphone Ubiquity:Near-universal iOS and Android penetration eliminates hardware barriers to entry. Native app performance standards set by Apple and Google force continuous UX refinement.
Market Restraints
- State Tax Rate Divergence:New York's 51% gross gaming revenue levy compresses operator margins compared to New Jersey's 13% structure. This fragmentation distorts capital allocation across state launches.
- Tribal Compact Exclusivity:Reservation-adjacent jurisdictions in Florida and California face market access constraints through National Indian Gaming Commission oversight. Compact renegotiation timelines extend commercial entry by years.
- Payment Rail Volatility:Credit card network policies and bank de-risking practices create deposit friction in certain states. ACH and prepaid alternatives add conversion steps that elevate customer acquisition costs.
Strategic Opportunities
- Untapped State Jurisdictions:California, Texas, and Florida represent substantial latent demand pools pending legislative activation. Early positioning through fantasy sports partnerships builds regulatory relationships.
- Casino Cross-Sell Integration:Physical gaming loyalty programs in mature markets like Pennsylvania and Michigan enable cost-effective user acquisition. Shared wallet architectures reduce verification overhead.
- Live Streaming Convergence:Embedded video feeds within wagering interfaces compress the decision-to-bet interval. League content partnerships in the Northeast corridor differentiate platform stickiness.
Industry Challenges
- Geolocation Verification Complexity:GPS and Wi-Fi triangulation against state regulatory databases produces false negatives at jurisdiction boundaries. Customer service overhead escalates when legitimate users face access denials.
- Responsible Gaming Compliance Burden:Self-exclusion registry integration and deposit limit enforcement require real-time system architecture. State gaming commission audit protocols demand substantial engineering resources.
- League Integrity Fee Negotiations:Major sports leagues extract commercial payments for official data access and marketing partnerships. These fixed costs pressure unit economics in competitive markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Betting Market |
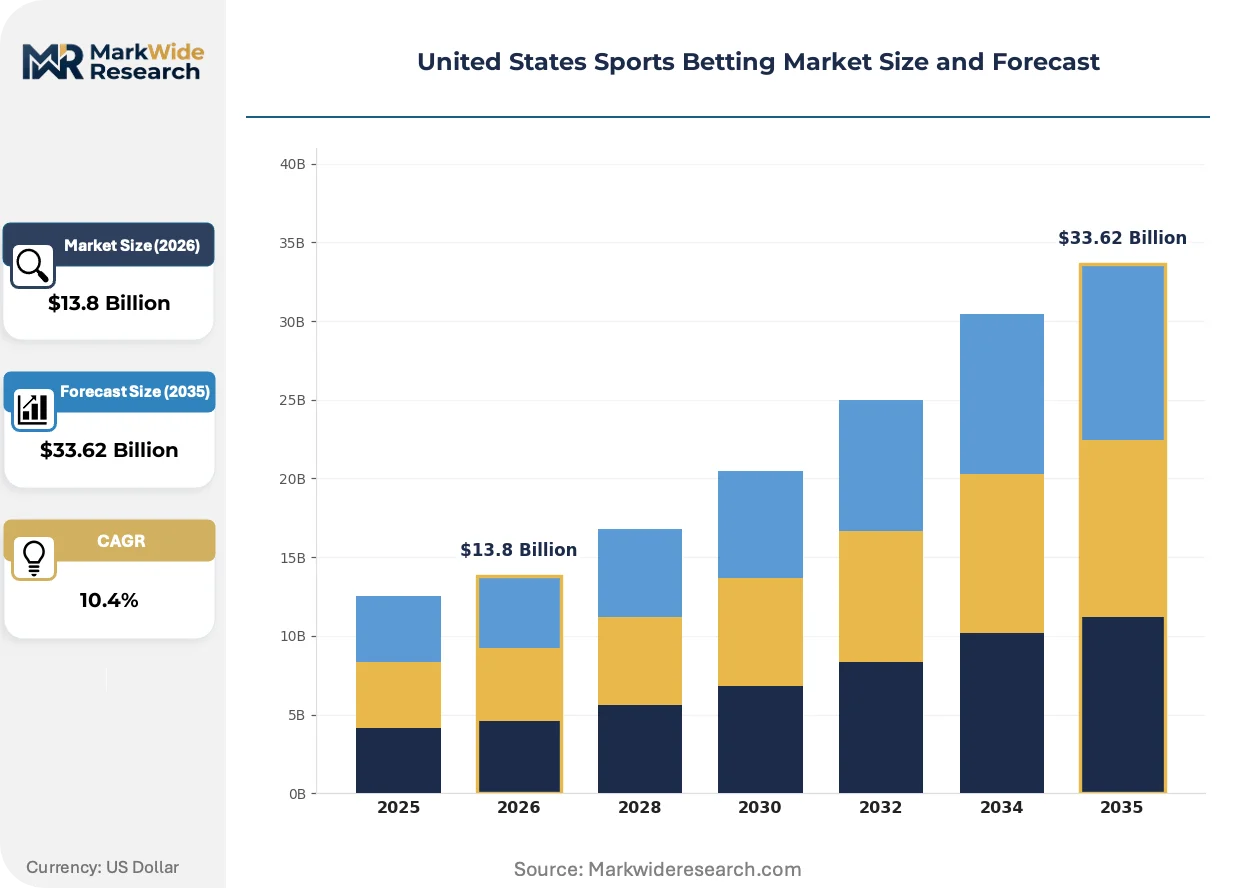
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online Betting, Retail Betting, Mobile Apps, Live Betting Customer Type: Casual Bettors, Professional Gamblers, Fantasy Sports Players, High Rollers Technology: Blockchain, Artificial Intelligence, Mobile Payment Systems, Augmented Reality Distribution Channel: Bookmaker Websites, Sports Apps, Casino Venues, Third-Party Platforms |
| Companies Covered | DraftKings, FanDuel, BetMGM, Caesars Sportsbook, bet365, ESPN BET, Fanatics, Hard Rock Bet, BetRivers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Betting Market Strategic Shifts & Innovations
Real-time data infrastructure and artificial intelligence are compressing the latency between sporting events and wagerable price updates. This convergence is reshaping how operators architect their trading floors and customer-facing interfaces.
Same-game parlay engines are displacing traditional single-outcome betting as the dominant product format across mobile platforms. Casual bettors in the Great Lakes corridor are adopting these complex wagers at accelerating velocity. This shift is concentrating margin pools through elevated vigorish and correlated outcome pricing that traditional bookmaking never captured.
State gaming commissions in Ohio and Massachusetts are imposing stricter advertising guidelines that restrict bonus-driven acquisition messaging. These frameworks force operators to pivot toward organic content and influencer partnerships. The Northeast market is responding with branded podcast networks and league-aligned sponsorships that navigate disclosure requirements.
Bettor acquisition patterns are rotating toward social referral mechanisms and embedded gaming content rather than direct paid media. Younger demographics in urban corridors are discovering platforms through Twitch streams and TikTok clips rather than television advertising. This channel migration is most visible in New Jersey and Pennsylvania, where traditional sportsbook marketing spend is decelerating while creator economy partnerships accelerate.
United States Sports Betting Market Segmentation
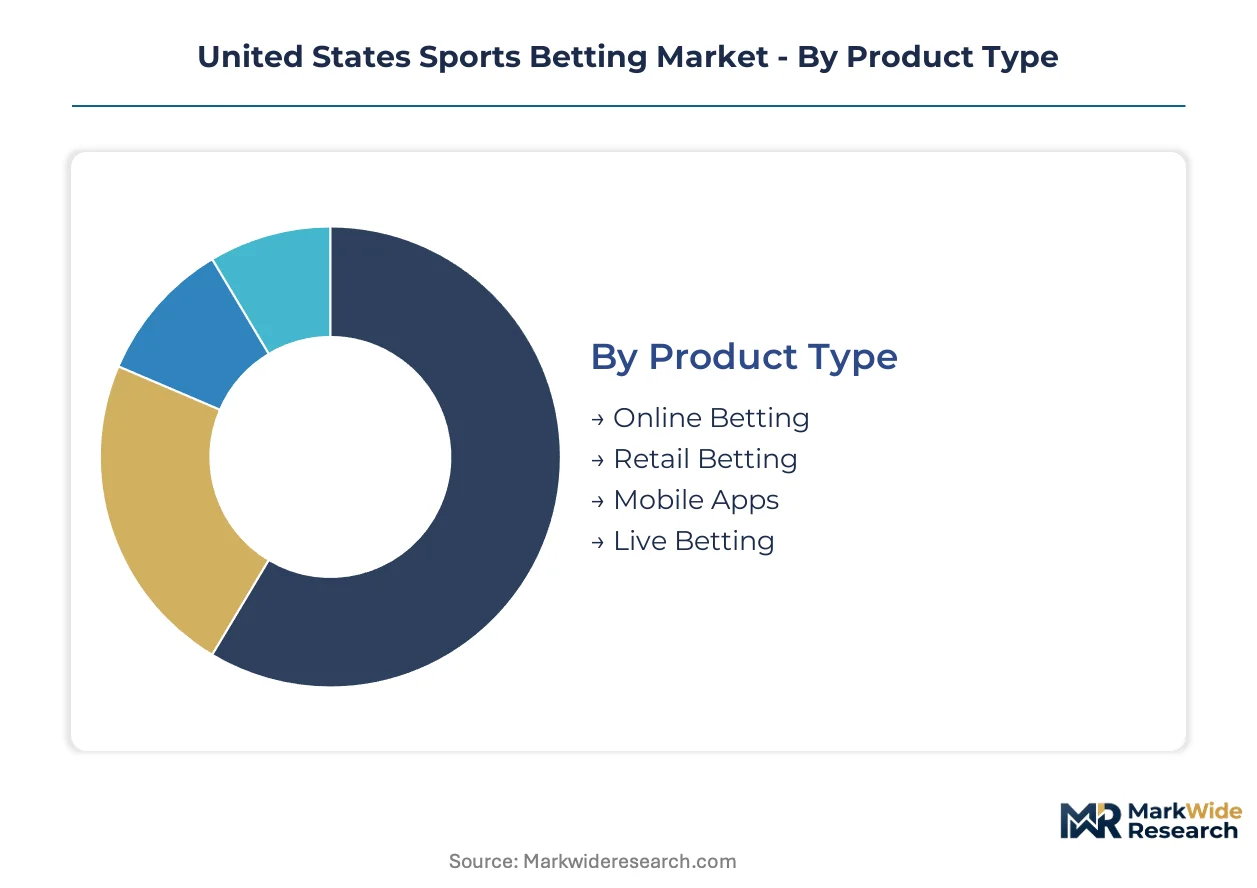
Sports betting operators architect distinct product and technology stacks to capture divergent customer lifetime values across state jurisdictions. Segmentation discipline separates high-frequency micro-bettors from seasonal casual users, enabling targeted margin structures and compliance architectures.
Product Type:
Geographic spread varies sharply: mobile-native formats concentrate in newly launched Midwestern states, while legacy retail maintains density in mature Northeast corridors.
- Online Betting:Browser-based wagering platforms process the majority of handle volume through responsive web interfaces. Demand concentrates in Pennsylvania and New Jersey, where broadband infrastructure and established regulatory frameworks support seamless account verification. State tax rate differentials drive operator prioritization of lower-levy jurisdictions.
- Mobile Apps:Native iOS and Android applications deliver geofenced access with GPS-Wi-Fi triangulation against state gaming commission databases. The steepest expansion runs through Ohio and Massachusetts launches, where smartphone penetration eliminates hardware barriers. Apple's App Store review protocols force continuous UX refinement cycles.
- Retail Betting:Physical sportsbook counters at casinos and racetracks serve cash-preferred demographics. Atlantic City and Las Vegas sustain the established footprint.
- Live Betting:In-game wagering on possession-level outcomes extends session duration through algorithmic price feeds. Great Lakes corridor adoption accelerates fastest.
Online betting commands the established base. The steepest expansion runs through mobile apps.
Customer Type:
Cost tier stratification separates mass-market acquisition targets from whale economics that sustain VIP trading floors.
- Casual Bettors:Recreational users placing sub-$50 wagers on marquee events drive volume scalability. Same-game parlay adoption concentrates in the Great Lakes corridor, where fantasy sports heritage normalizes complex wager construction. DraftKings and FanDuel anchor acquisition through low-friction onboarding flows.
- Professional Gamblers:Sharps exploiting market inefficiencies through statistical modeling trigger automated risk management responses. Nevada and New Jersey sustain the highest concentration of sophisticated accounts. Hold percentage compression forces operators to segment these users into restricted price tiers.
- Fantasy Sports Players:Daily fantasy heritage users convert to fixed-odds wagering through shared wallet architectures. Cross-sell pipelines run strongest in Pennsylvania and Michigan.
- High Rollers:VIP segments generating five-figure monthly handles demand dedicated account management. Casino loyalty program density in mature jurisdictions enables cost-effective identification.
Casual bettors anchor volume scalability. Professional gamblers are gaining sophistication fastest.
Technology:
Application maturity separates production-grade infrastructure from experimental pilots that remain pre-revenue.
- Artificial Intelligence:Machine learning models optimize real-time odds adjustment and fraud detection through pattern recognition on historical wager databases. Northeast operators deploy these systems most aggressively, where regulatory audit requirements demand explainable decision architectures. Algorithmic price feeds enable sub-minute settlement without manual trader intervention.
- Mobile Payment Systems:ACH, prepaid cards, and digital wallets process deposits through geofenced verification layers. Credit card network volatility in certain states elevates conversion friction. Alternative rail adoption climbs fastest in jurisdictions with restrictive banking policies.
- Blockchain:Distributed ledger pilots explore transparent settlement and smart contract automation. Nevada regulatory sandboxes host limited trials.
- Augmented Reality:Immersive visualization overlays remain experimental, with no commercial deployment at scale.
Mobile payment systems command the established base. Artificial intelligence is climbing the fastest.
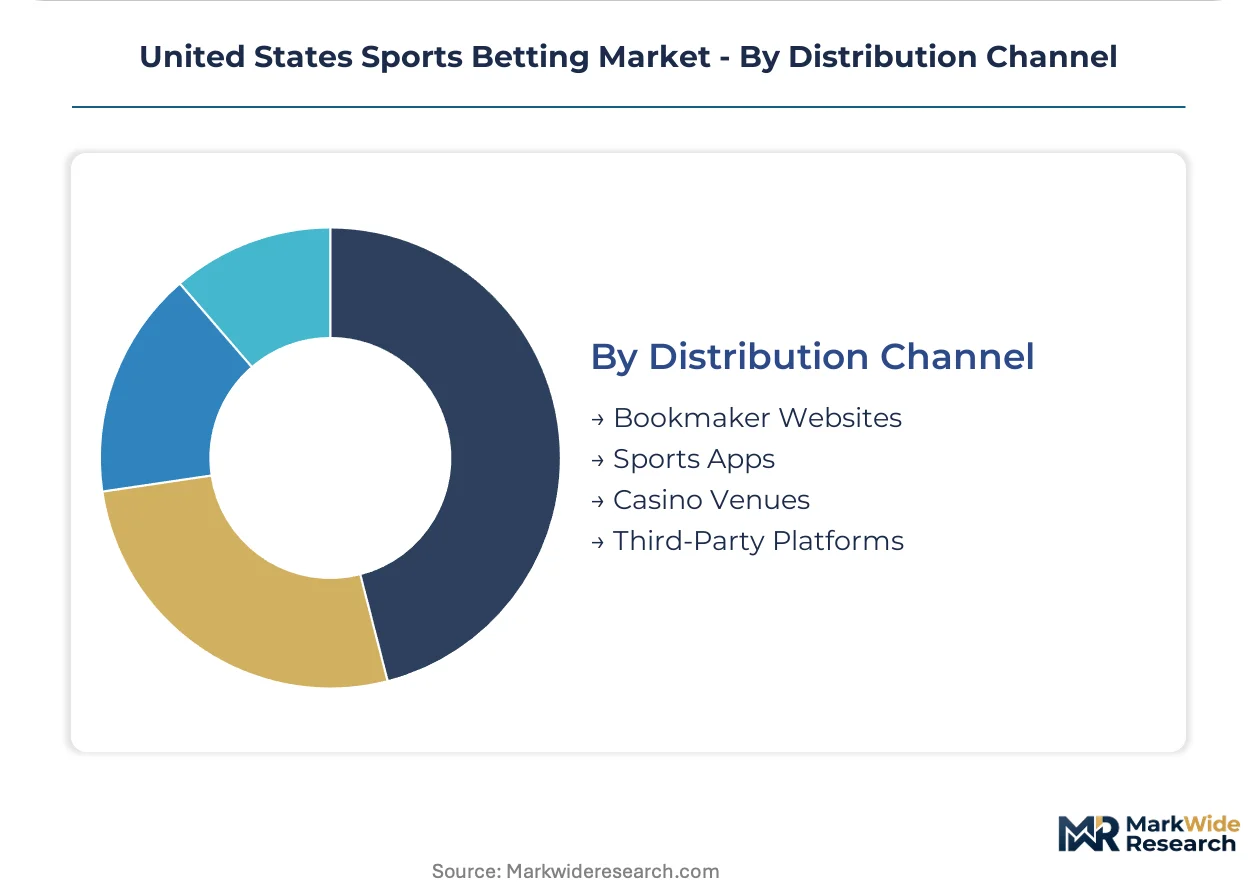
Distribution Channel:
Supply concentration favors vertically integrated operators against third-party aggregators facing margin compression.
- Sports Apps:Operator-owned mobile applications capture direct customer relationships without revenue sharing. Native performance optimization for iOS and Android eliminates third-party conversion leakage. New Jersey and Pennsylvania sustain the deepest penetration.
- Bookmaker Websites:Responsive web platforms serve desktop-preferred demographics and jurisdictions with restrictive app store policies. Ohio and Massachusetts launches prioritize browser-first strategies during regulatory approval windows.
- Casino Venues:Physical sportsbook counters leverage existing gaming floor traffic in mature markets. Michigan and Pennsylvania integrate these most densely.
- Third-Party Platforms:Aggregator and affiliate sites drive qualified traffic through revenue-share arrangements. Acquisition cost inflation is forcing operator pullback.
Sports apps command the established base. Bookmaker websites are gaining share fastest in newly launched states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Jersey exports mobile wagering infrastructure and regulatory frameworks to emerging state markets across the Great Lakes and Southeast corridors.
New Jersey
Atlantic City casino partnerships and the Division of Gaming Enforcement's mature licensing protocols sustain the densest operator concentration. The state's 13% gross gaming revenue tax rate attracts platform headquarters investment. Meadowlands Racetrack anchors retail-digital hybrid operations in the northern corridor.
Pennsylvania
Philadelphia and Pittsburgh metropolitan clusters drive handle volume through established casino loyalty program cross-sells. The Pennsylvania Gaming Control Board's tiered licensing structure accommodates both tribal and commercial operators. Parx Casino and Rivers Casino Philadelphia anchor integrated resort sportsbook footprints.
Ohio
Cleveland-Akron and Cincinnati-Dayton corridors concentrate newly launched mobile adoption among former daily fantasy players. The Ohio Casino Control Commission's Type A license caps create scarcity value for platform access. Hollywood Casino Columbus anchors the central Ohio retail-digital convergence.
New York
New York City metro demand compresses operator margins under the 51% state tax levy while sustaining massive per-capita handle generation. The New York State Gaming Commission's two-vendor mobile cap forces intense competitive positioning. Resorts World Catskills and del Lago Resort anchor upstate retail infrastructure.
Massachusetts
Greater Boston's educated demographic drives rapid same-game parlay adoption through fantasy sports heritage. The Massachusetts Gaming Commission's strict advertising guidelines force organic acquisition pivots. Encore Boston Harbor anchors the premium retail experience in the northeastern corridor.
United States Sports Betting Market Key Industry Players
Player mix skews toward daily-fantasy heritage platforms that converted fixed-odds wagering infrastructure post-PASPA. Market structure concentrates around three national-scale operators with state-by-state launch sequencing determining temporal market share. Strategic archetypes separate mobile-native platforms, casino-integrated incumbents, and international entrants with U.S. partnership strategies. Competitive moves center on exclusive league content partnerships and same-game parlay product engineering.
Within the mobile-native tier, DraftKings and FanDuel exemplify the daily-fantasy-to-sportsbook conversion archetype that dominates customer acquisition economics. BetMGM occupies a position representing casino-integrated operators leveraging physical gaming loyalty density for cost-effective user identification. These three anchors illustrate how heritage business models dictate divergent capital allocation across state launch prioritization and product development roadmaps.
| Leading Market Players |
|---|
| DraftKings |
| FanDuel |
| BetMGM |
| Caesars Sportsbook |
| bet365 |
| ESPN BET |
| Fanatics |
| Hard Rock Bet |
| BetRivers |
| Others |
Cost & Logistics Intelligence
Revenue-share agreements with major sports leagues lock in official data access costs and marketing partnership visibility for licensed operators. These multi-year commitments tether platform economics to fixed integrity fees while state tax rate fragmentation compresses margin curves across jurisdictions.
Pricing Analysis
Legacy retail infrastructure commands premium pricing against mobile-native platforms that compete on volume-scaled unit economics. Three-tier pricing structure across premium, standard, and economy levels separates VIP account management from mass-market self-service interfaces. Pricing pressure stems from New York's 51% gross gaming revenue levy forcing operators to absorb tax burdens rather than pass through to bettors. Casual bettors in newly launched Midwestern states exhibit highest price sensitivity, while high rollers in mature Northeast corridors tolerate elevated vigorish for dedicated service tiers.
Supply Chain Analysis
Port congestion at Long Beach and Savannah disrupts server hardware delivery timelines for platform infrastructure expansion. Supply concentrates in Taiwan for semiconductor components, Ireland for data center operations, and domestic colocation facilities for latency-sensitive trading engines. Raw material dependencies span GPU clusters for AI odds engines, fiber optic cable for low-latency feeds, and cooling systems for high-density server racks. Single-source vulnerability in geolocation verification chipsets creates chokepoint exposure. Distribution runs through direct operator procurement rather than third-party aggregator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
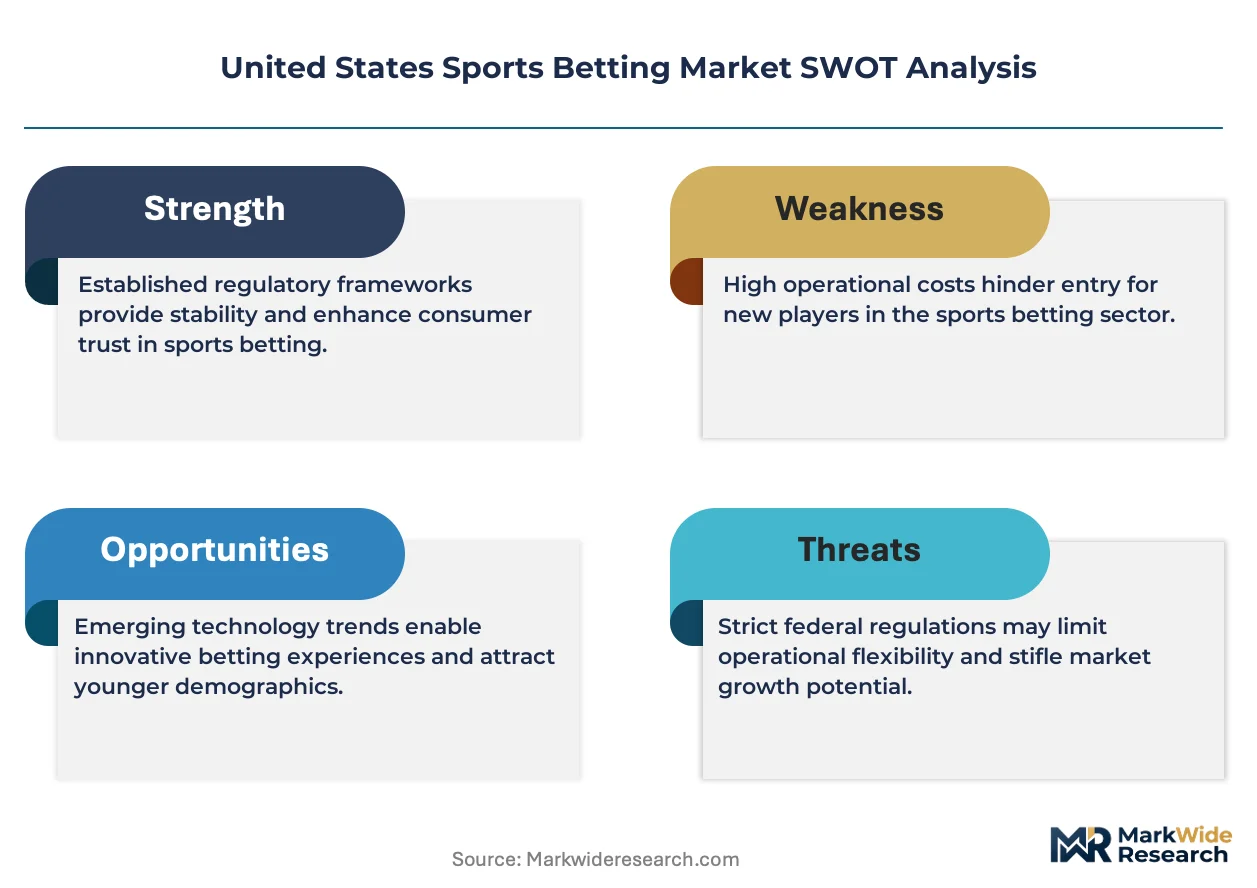
This market rewards regulatory entrenchment as a defensive moat. State-by-state licensing caps create artificial scarcity that protects incumbent positions against unlicensed competition.
For Market Incumbents: Secure exclusive league content partnerships before competitor activation in pending jurisdictions. Fortify geolocation verification infrastructure to reduce false-negative customer service overhead. State tax rate divergence threatens margin sustainability in high-levy corridors.
For New Entrants and Emerging Players: Anchor in California and Texas legislative advocacy to position for pending market activation. Target daily fantasy sports player databases as the most penetrable conversion pool. Deploy influencer-driven organic acquisition to navigate advertising restrictions in Massachusetts and Ohio.
For Investors and Strategic Acquirers: Mobile-native platforms with daily fantasy heritage command premium positioning due to superior customer acquisition economics. Long-term viability hinges on state regulatory expansion velocity rather than technology differentiation. Monitor tribal compact renegotiation timelines in Florida as the critical inflection signal for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Same-Game Parlay Engine Development | Captures margin pools through correlated outcome pricing that traditional bookmaking never accessed. |
| Live Streaming Content Integration | Compresses decision-to-bet intervals through embedded video feeds within wagering interfaces. |
| Casino Loyalty Program Cross-Sell | Reduces customer acquisition costs through shared wallet architectures in Pennsylvania and Michigan. |
| Tribal Compact Partnership Structuring | Unlocks reservation-adjacent market access under National Indian Gaming Commission oversight. |
| Responsible Gaming Compliance Architecture | Satisfies state gaming commission audit protocols through real-time self-exclusion registry integration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with platform product executives, state gaming commission officials, casino loyalty program directors, and daily fantasy sports conversion specialists. Secondary validation drew from state regulatory filings, SEC operator disclosures, tribal compact databases, and league partnership announcements. Bottom-up handle volume estimates triangulated against top-down state tax revenue aggregates.
Across the analysis window, forecasts segment by product type, customer tier, technology deployment, and distribution channel. CAGRs derive from historical launch velocity curves in comparable state markets, adjusted for tax rate and competitive density differentials. Inputs include smartphone penetration trajectories, broadband infrastructure buildouts, and legislative session calendars.
Material uncertainties — federal interstate compact preemption, tribal exclusivity litigation, payment rail policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about state launch sequencing and hold percentage stability. Practitioners should keep alternative scenarios live as regulatory and technological conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
North America Photographic Services Market
Digital Media
Blockchain in Media and Entertainment Market
Digital Media
Adult Entertainment Market
Digital Media
Digital Distribution Market
Digital Media
Digital Media Production Software Market
Digital Media
Digital Content Locker Market
Digital Media
India Webtoons Market
Digital Media
Da Vinci Systems Market
Digital Media
Global Digital Painting Market
Digital Media
Mexico Webtoons Market
Digital Media
Asia-Pacific Webtoons Market
Digital Media
Digital Content Creation Market
Digital Media
3D Anaglyph Glasses Market
Digital Media
Global Virtual Goods Market
Digital Media
Media and Entertainment Market
Digital Media
LED Stadium Screens Market