
 Global Cloud Office Services Market | 2026-2036
Global Cloud Office Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Office Services Market Foresight
Proprietary on-premises productivity software is hardening into a legacy cost burden as enterprises migrate to subscription-based cloud delivery. Microsoft leverages its Azure backbone to anchor enterprise workloads across hybrid configurations. Google competes through deep integration of generative AI into Workspace applications. Salesforce specializes in CRM-linked document workflows that differentiate its platform from generalist suites.
Cloud office services encompass hosted productivity applications delivered through internet-accessible infrastructure with guaranteed uptime thresholds, multi-tenant architecture, and API-based extensibility for third-party integrations. These systems replace local installation models with centralized software maintenance, patch management, and elastic capacity scaling. Hybrid cloud deployment now captures the largest margin pools as enterprises retain sensitive data on private nodes while pushing routine collaboration to public infrastructure. Workflow automation within solution offerings represents the fastest-expanding category as organizations embed robotic process automation into document-centric tasks. Virtual desktop infrastructure remains mature with slower growth but sticky renewal dynamics in regulated industries.
GDPR in Europe, the EU AI Act, and HIPAA in the United States impose divergent compliance architectures that vendors must navigate to maintain market access across jurisdictions. The EU AI Act specifically classifies certain automated decision tools within office suites as high-risk, triggering conformity assessment obligations before deployment. Stakeholders must monitor how fragmentation between European and American data sovereignty frameworks reshapes cross-border service delivery architectures.
Market Dynamics
Hybrid cloud deployment architectures are forcing vendors to re-engineer service delivery models as enterprises demand seamless orchestration between on-premises data sovereignty nodes and elastic public infrastructure.
Growth Catalysts
- Generative AI integration:Large language model capabilities embedded into document editing and email workflows are pulling financial services firms toward comprehensive suite upgrades.
- GDPR Article 32 mandates:European data processing agreements now require encryption and access logging that cloud-native platforms deliver more cost-effectively than retrofitted legacy systems.
- Japan's METI digital transformation incentives:Tax deductions for SaaS migration are accelerating replacement of on-premises productivity infrastructure in manufacturing and trading conglomerates.
Market Restraints
- Cross-border data transfer friction:Divergent interpretations of GDPR adequacy decisions and US CLOUD Act subpoena powers are complicating multi-jurisdiction contract structures.
- Specialized compliance tooling costs:HIPAA Business Associate Agreements and EU AI Act conformity assessments add implementation overhead that squeezes margins in mid-market segments.
- Latency-sensitive workload limitations:Real-time collaborative editing in bandwidth-constrained environments remains technically constrained compared to local application performance.
Strategic Opportunities
- India's PLI scheme for IT hardware:Local data center buildouts under production-linked incentives are creating captive cloud office hosting capacity for domestic enterprises and multinational back-office operations.
- Workflow automation convergence:Robotic process engines fused with document-centric collaboration tools open white space in insurance claims processing and contract lifecycle management.
- API-first ecosystem expansion:Vertical industry marketplaces connecting cloud office platforms to specialized compliance, analytics, and industry-specific applications represent underdeveloped revenue pools.
Industry Challenges
- Multi-cloud identity architecture complexity:Enterprises operating across Microsoft, Google, and Salesforce environments face skill shortages in unified access management and single sign-on federation.
- EU AI Act high-risk system classification:Automated decision tools within recruitment and performance management modules trigger conformity assessment timelines that delay product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Office Services Market |
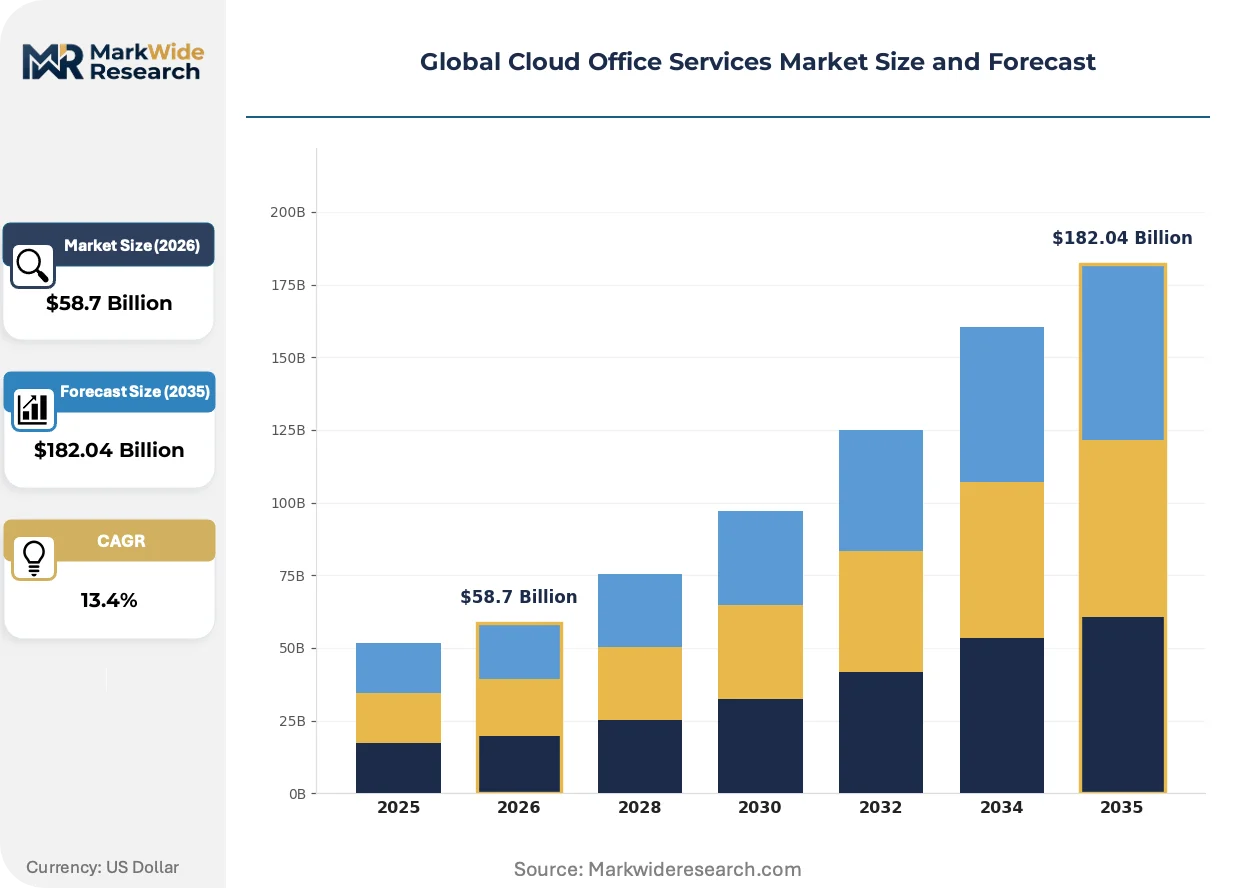
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $182.04 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Collaboration Tools, Document Management, Email Hosting, Virtual Desktop Infrastructure, Workflow Automation Use Case: Remote Team Collaboration, Project Management, Secure File Sharing, Real-Time Communication, Performance Analytics End User Industry: Information Technology, Financial Services, Education, Telecommunications, Legal Services |
| Companies Covered | Microsoft, Google, Amazon, Salesforce, IBM, Zoho, Atlassian, Dropbox, Box, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Office Services Market Shifts & Advancements
Artificial intelligence capabilities are compressing feature differentiation cycles across vendor portfolios while regulatory fragmentation forces architectural investments that favor scale players over niche competitors.
Real-time collaborative editing with embedded generative assistance is overtaking traditional asynchronous document workflows in enterprise procurement evaluations. Financial services compliance teams now mandate live co-authoring with automatic version control and audit trails. This capability compression is collapsing the evaluation cycle for standalone document management systems.
The EU AI Act's high-risk classification system is reshaping product roadmaps for automated decision support tools embedded in productivity suites. Vendors must complete conformity assessments before deploying recruitment analytics and performance scoring modules. German and French enterprise buyers are now requiring AI Act compliance documentation in procurement checklists ahead of contract execution.
Consumption-based licensing tied to active user sessions is displacing traditional per-seat annual contracts in mid-market segments. Value-added resellers and managed service providers are capturing margin by bundling usage optimization consulting with platform subscriptions. This pattern is most pronounced in United States healthcare and professional services verticals where seasonal workforce fluctuations make fixed licensing economically inefficient.
Global Cloud Office Services Market Segmentation
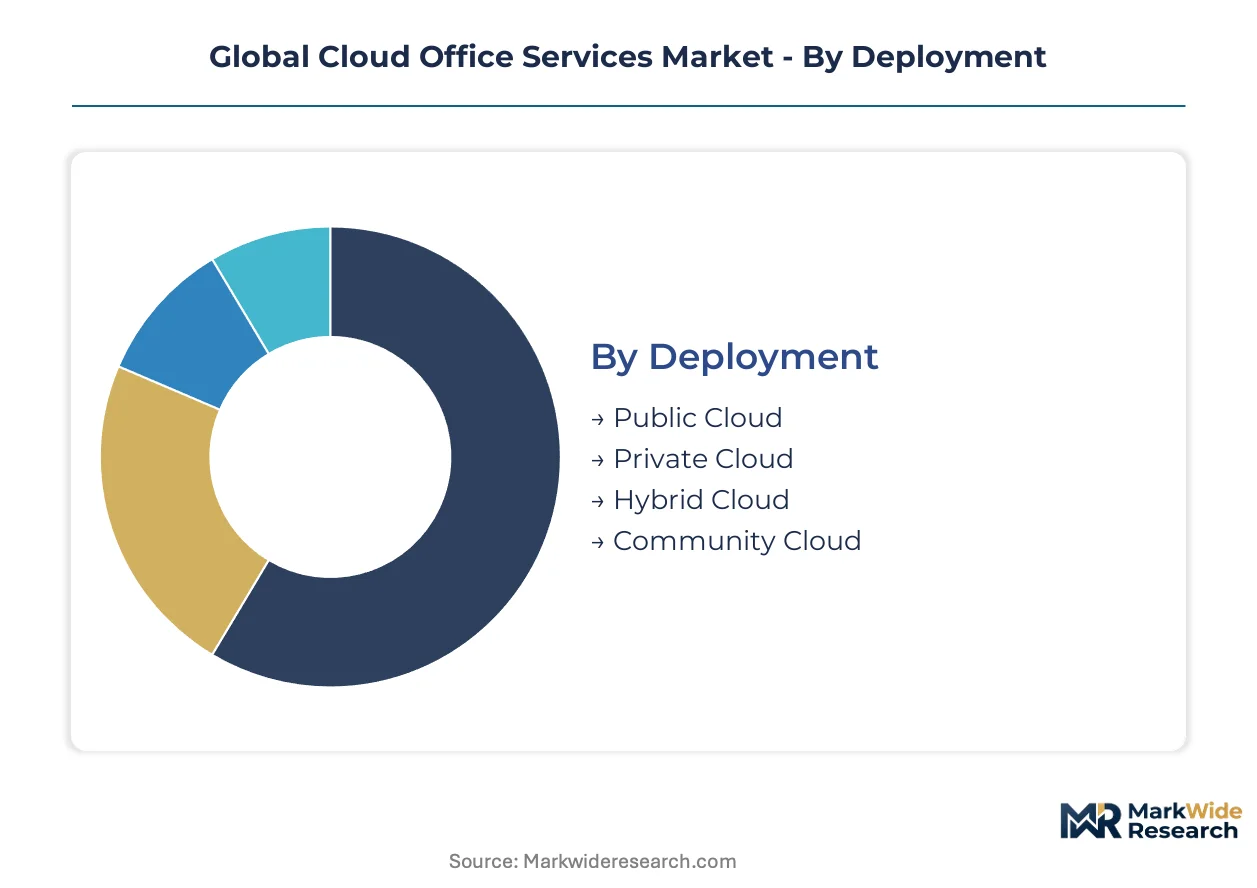
Cloud office services fragment across deployment architectures, solution types, and industry verticals with divergent compliance and performance requirements. Understanding these segment boundaries clarifies where vendors invest R&D versus where channel partners capture implementation margin.
Deployment:
Volume deployment concentrates in public infrastructure while premium workloads command private and hybrid configurations with data sovereignty guarantees.
- Public Cloud:Multi-tenant infrastructure delivers elastic capacity scaling without capital expenditure. Demand concentrates among mid-market professional services firms in the United States seeking rapid provisioning without dedicated hardware overhead.
- Private Cloud:Single-tenant environments provide isolated compute and storage resources with dedicated security boundaries. German financial institutions and Japanese trading houses deploy these configurations to satisfy METI data localization guidelines and GDPR Article 44 transfer restrictions.
- Hybrid Cloud:Orchestrated environments split sensitive data processing across private nodes while pushing routine collaboration to public infrastructure. This architecture captures the largest margin pools as enterprises balance sovereignty with cost efficiency.
- Community Cloud:Shared infrastructure serving organizations with common compliance requirements, such as HIPAA-covered entities or EU public sector bodies. Specialized Business Associate Agreements and AI Act conformity assessments create implementation friction.
Mature deployment sits with Public Cloud. Newer deployment is concentrated in Hybrid Cloud.
Solution Offering:
Application breadth versus depth determines vendor positioning, with integrated suites competing against best-of-breed specialists.
- Collaboration Tools:Real-time co-authoring, video conferencing, and persistent chat channels form the engagement layer. Financial services compliance teams in the United States now mandate live editing with automatic audit trails.
- Document Management:Centralized repositories with version control, metadata tagging, and retention policies. Legal services firms in Germany and France require AI Act documentation for automated classification features.
- Email Hosting:Managed messaging infrastructure with anti-phishing, encryption, and e-discovery capabilities. Sticky renewal dynamics persist in regulated industries despite slower feature innovation.
- Virtual Desktop Infrastructure:Streamed desktop environments delivering consistent application access across endpoint devices. Healthcare organizations under HIPAA maintain these deployments for controlled access to patient systems.
- Workflow Automation:Robotic process engines embedded within document-centric tasks. Insurance claims processing and contract lifecycle management in Japan's manufacturing sector are expanding most quickly.
Established revenue sits with Email Hosting. Expansion concentrates in Workflow Automation.
Use Case:
Functional application of cloud office capabilities maps to organizational maturity and digital transformation priorities.
- Remote Team Collaboration:Distributed workforce coordination through shared workspaces and asynchronous communication. Technology sector adoption in the United States has normalized this as default operating mode.
- Project Management:Task tracking, resource allocation, and milestone visualization integrated with document workflows. Professional services firms bundle these capabilities into client delivery methodologies.
- Secure File Sharing:Encrypted transmission and access-controlled repositories for sensitive document exchange. GDPR Article 32 encryption mandates drive replacement of consumer-grade alternatives in European legal services.
- Real-Time Communication:Synchronous voice, video, and messaging with presence indicators and meeting transcription. Financial services trading floors require sub-second latency that challenges pure cloud architectures.
- Performance Analytics:Usage dashboards, productivity scoring, and predictive insights from collaboration patterns. EU AI Act high-risk classification triggers conformity assessments for automated performance scoring modules.
Baseline adoption sits with Remote Team Collaboration. Regulatory complexity concentrates in Performance Analytics.
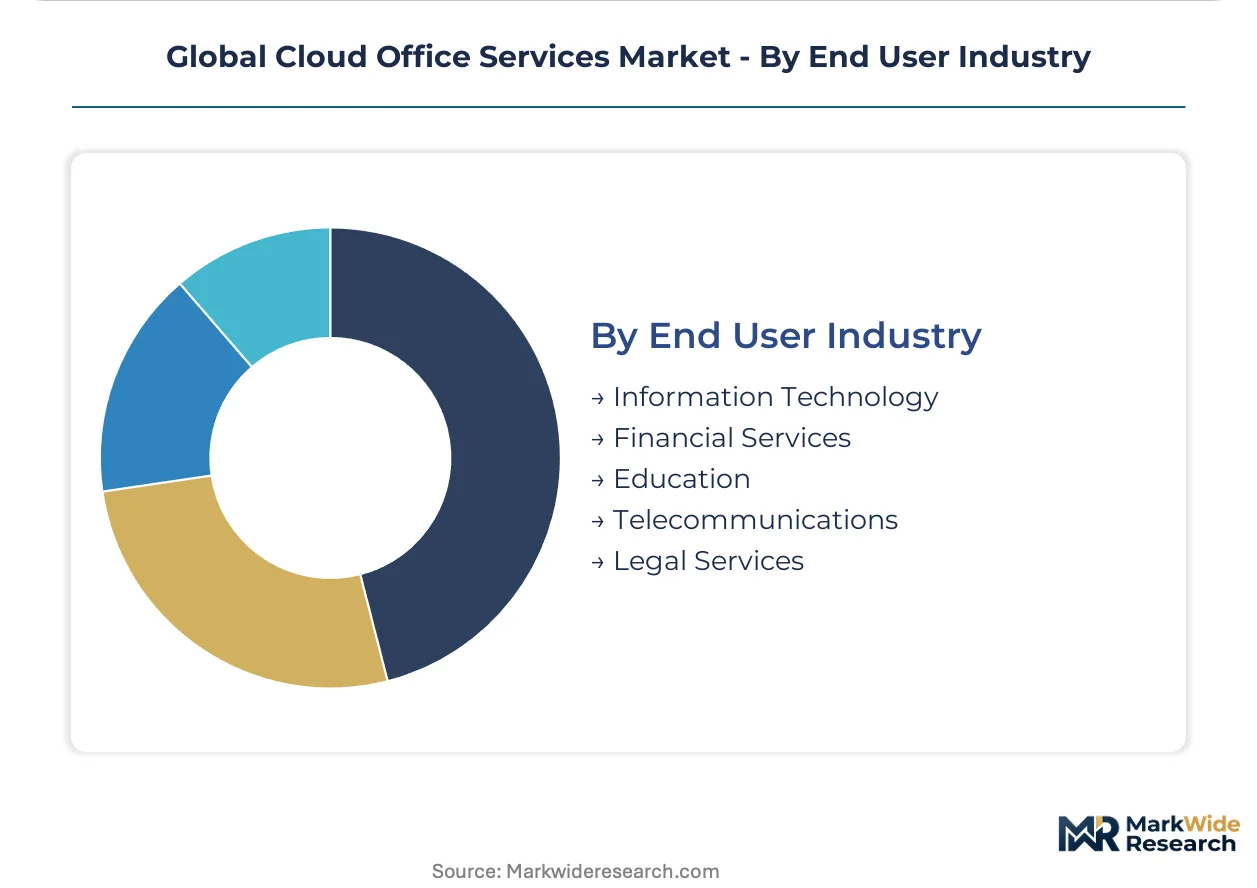
End User Industry:
Vertical specialization demands shape feature roadmaps and compliance certification investments.
- Information Technology:Early adopters driving API-first integration patterns and consumption-based licensing models. Technology vendors use their own platforms as reference architectures for enterprise sales.
- Financial Services:Banks, insurers, and asset managers with stringent audit, retention, and real-time collaboration requirements. SEC record-keeping rules and GDPR data processing agreements create dual compliance burdens.
- Education:K-12 and higher education institutions with seasonal licensing fluctuations and FERPA privacy obligations. State procurement frameworks in the United States favor multi-year enterprise agreements.
- Telecommunications:Service providers integrating cloud office suites into bundled connectivity offerings. Customer churn reduction through sticky collaboration tools drives platform selection.
- Legal Services:Law firms and corporate legal departments with matter-centric document organization and privilege protection. German and French buyers now require EU AI Act compliance documentation ahead of contract execution.
Volume concentration sits with Information Technology. Compliance-driven replacement concentrates in Legal Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as enterprises modernize legacy productivity infrastructure and navigate divergent data sovereignty frameworks. Financial services firms across these markets are accelerating cloud migration to satisfy encryption mandates and AI governance requirements.
United States
Financial services and technology sectors drive procurement of generative AI-enabled collaboration suites. SEC record-keeping rules and HIPAA Business Associate Agreements create dual compliance burdens that favor established cloud-native platforms. New York and San Francisco metropolitan clusters anchor enterprise deployment volumes for hybrid cloud architectures.
Germany
Manufacturing conglomerates and financial institutions prioritize data localization under GDPR Article 44 transfer restrictions. The EU AI Act's high-risk classification system triggers conformity assessments for automated decision tools in recruitment modules. Frankfurt and Munich host concentrated demand for private cloud configurations serving automotive and industrial engineering headquarters.
Japan
METI digital transformation incentives accelerate SaaS migration among manufacturing and trading conglomerates. Tax deductions for cloud adoption are displacing on-premises productivity infrastructure in Osaka and Nagoya industrial corridors. Tokyo financial districts demand sub-second latency for real-time collaborative trading floor applications.
United Kingdom
Legal services and professional services firms require AI Act compliance documentation ahead of contract execution for automated classification features. London's financial center drives consumption-based licensing adoption among hedge funds and asset managers. Manchester and Birmingham technology clusters are expanding mid-market workflow automation deployments.
India
PLI scheme incentives for IT hardware are creating captive cloud office hosting capacity under domestic data center buildouts. Bengaluru and Hyderabad technology corridors serve multinational back-office operations with API-first integration patterns. Mumbai financial institutions are adopting hybrid configurations to satisfy emerging data localization guidance from the central bank.
Global Cloud Office Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium positioning against best-of-breed document workflow specialists. The vendor base organizes around three strategic archetypes: hyperscale cloud infrastructure operators, enterprise software incumbents with productivity heritage, and vertical specialists in CRM-linked collaboration. Competitive moves center on generative AI feature integration and hybrid cloud orchestration capabilities that bridge sovereign data nodes with elastic public capacity.
Within the hyperscale tier, Microsoft and Google exemplify divergent platform strategies, with the former anchoring enterprise workloads across hybrid Azure configurations and the latter competing through deep generative AI integration into productivity applications. Salesforce occupies a distinct position linking document workflows to customer relationship management data models, differentiating from generalist suite providers. Zoho represents the mid-market specialist archetype with bundled pricing approaches targeting professional services verticals in emerging economies.
| Leading Market Players |
|---|
| Microsoft |
| Amazon |
| Salesforce |
| IBM |
| Zoho |
| Atlassian |
| Dropbox |
| Box |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure operators backed by public equity markets anchor supply concentration in cloud office services, translating capital discipline into pricing power through multi-year enterprise commitments and consumption-based contract structures.
Pricing Analysis
Volume deployment in public cloud infrastructure captures thin margins through elastic capacity provisioning, while hybrid and private configurations command premium pricing through data sovereignty guarantees. Pricing stratifies across premium, standard, and economy tiers based on compliance certification level and geographic delivery cost, with EU AI Act conformity assessments adding substantial overhead to high-risk system deployments. Cost compression in mid-market segments is intensifying because managed service providers bundle optimization consulting with platform subscriptions. Healthcare and professional services verticals exhibit the highest price sensitivity due to seasonal workforce fluctuations, whereas financial services firms demonstrate lower sensitivity given regulatory mandates for audit trails and encryption.
Supply Chain Analysis
Dual-sourcing requirements from German financial institutions and Japanese trading conglomerates mandate multi-supplier qualification across hyperscale cloud providers, preventing single-vendor lock-in for critical productivity infrastructure. Supply concentration rests on data center buildouts in the United States, Germany, and Japan, with India's PLI scheme accelerating captive hosting capacity for domestic enterprises. Raw material dependencies center on specialized server hardware, encryption accelerators, and fiber-optic connectivity infrastructure. Single-source vulnerability persists in generative AI model training clusters concentrated among a limited set of hyperscale operators. Distribution runs through direct enterprise sales teams, value-added resellers, and managed service providers bundling implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
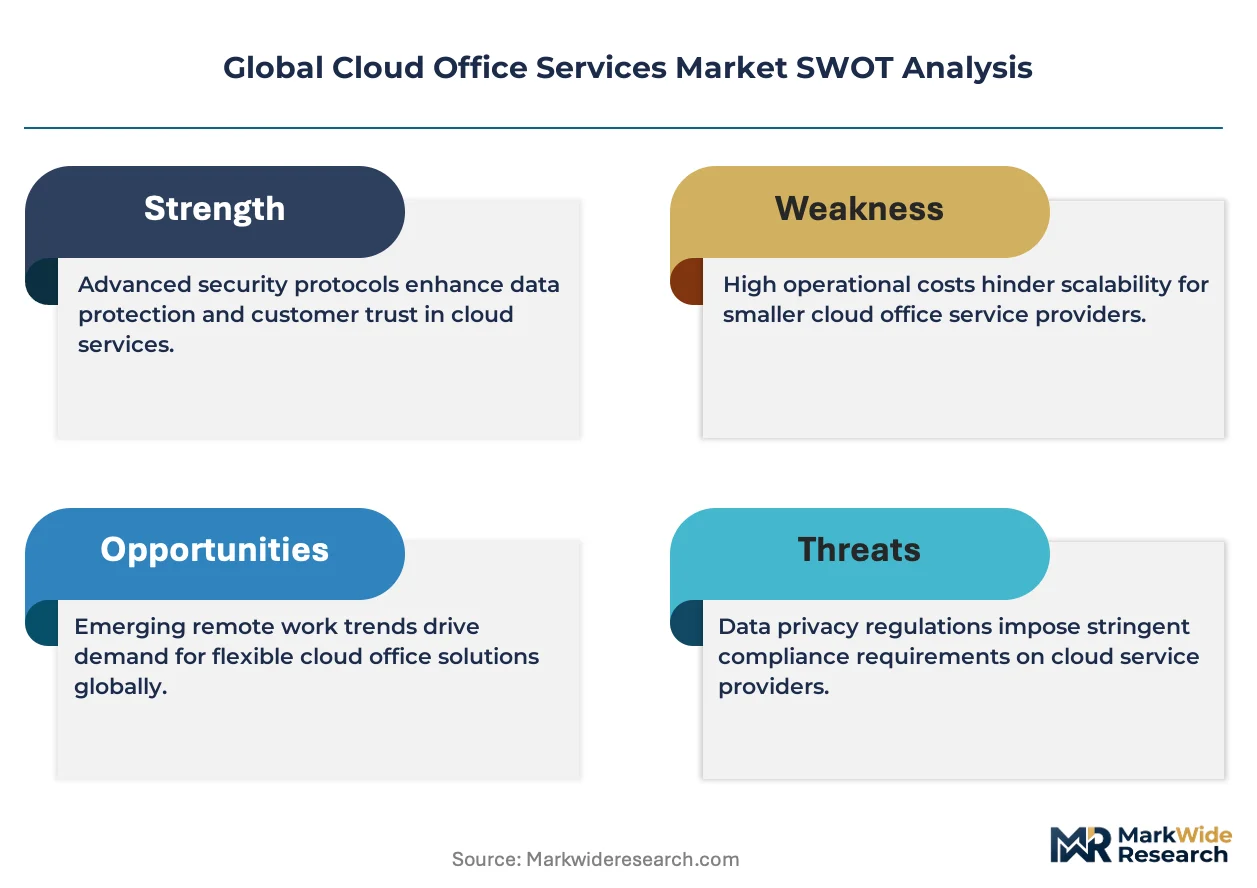
This market reads as a cost-of-compliance story where the EU AI Act's high-risk system classification creates a substantial barrier-to-entry moat for vendors possessing pre-certified automated decision tools.
For Market Incumbents: Lock in enterprise relationships through multi-year hybrid cloud orchestration contracts that embed EU AI Act conformity assessments into standard service level agreements. Threat from Google Workspace's generative AI integration demands accelerated R&D investment in embedded large language model capabilities. Channel control through exclusive managed service provider partnerships represents the critical lever for defending margin position in mid-market segments. For New Entrants and Emerging Players: India's PLI scheme for IT hardware opens a window for captive cloud office hosting capacity targeting multinational back-office operations in Bengaluru and Hyderabad technology corridors. White space concentrates in workflow automation for insurance claims processing and contract lifecycle management, where robotic process engine integration remains underdeveloped. Go-to-market through API-first ecosystem partnerships with vertical industry marketplaces bypasses direct competition with established suite providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance-specialist vendors in Germany and France possessing pre-validated EU AI Act documentation ahead of procurement checklist mandates. Long-term viability favors acquisition targets with established private cloud configurations serving automotive and industrial engineering headquarters. Signal to watch: acceleration of consumption-based licensing adoption in United States healthcare verticals indicating platform stickiness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Pre-certification of automated decision tools accelerates procurement cycles with German and French enterprise buyers. |
| Hybrid Cloud Orchestration Capability | Seamless integration between Azure sovereign nodes and elastic public infrastructure anchors Microsoft enterprise retention. |
| Workflow Automation Platform Expansion | Robotic process engines embedded in document-centric tasks capture insurance and manufacturing verticals in Japan. |
| API-First Ecosystem Development | Vertical marketplaces connecting cloud office platforms to specialized compliance applications unlock underdeveloped revenue pools. |
| Consumption-Based Licensing Transition | Active user session pricing displaces fixed annual contracts in United States healthcare and professional services segments. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, enterprise SaaS migration patterns, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with CTOs, IT procurement officers, platform engineers, and channel partners at cloud office vendors and enterprise adopters. Secondary validation drew from SEC filings, EU AI Act implementation guidance, METI digital transformation incentive documentation, and HIPAA Business Associate Agreement templates. Bottom-up deployment volume estimates triangulated against top-down market sizing from infrastructure capacity announcements.
Input-output matrices modeled demand drivers across deployment architecture, solution offering, use case, and end-user industry dimensions, with cross-elasticity parameters capturing substitution effects between public, private, and hybrid configurations. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated METI tax deduction utilization rates, GDPR Article 32 enforcement intensity, and generative AI feature adoption curves in financial services procurement evaluations.
The model assumes a particular technology adoption path for embedded large language model capabilities; alternative pathways for on-premises AI inference would alter the outlook for hybrid cloud demand. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and enterprise digital transformation budget availability. Deviation in EU AI Act high-risk classification scope or CLOUD Act subpoena power expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Europe Cloud Managed Networking Market
Cloud Computing
Cloud-Based Repository Services Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Global Multi Cloud Management Market
Cloud Computing
Government Cloud Computing Market
Cloud Computing
North America Cloud Microservices Platform Market