
 Malaysia Luxury Goods Market | 2026-2036
Malaysia Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Luxury Goods Market Foresight
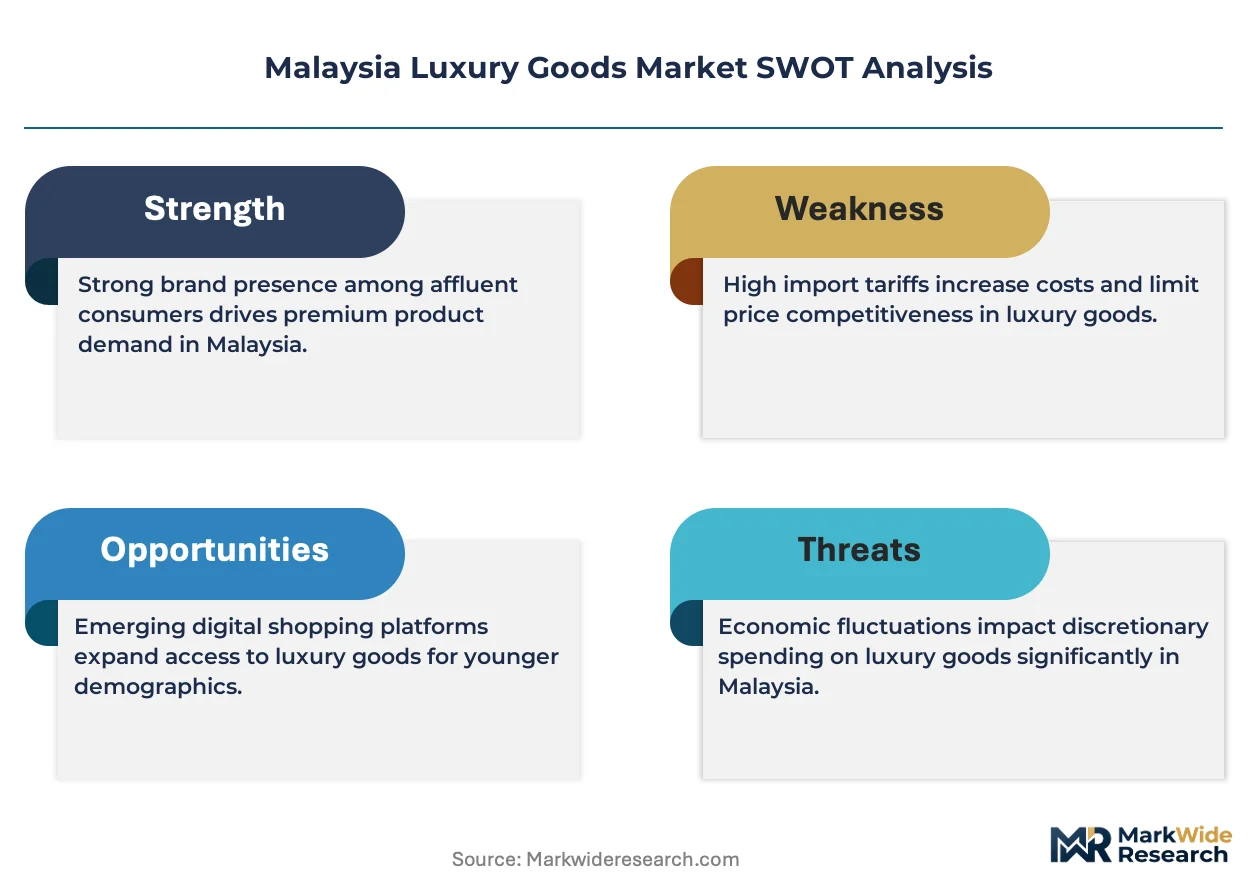
Lab-grown diamond technology is decoupling fine jewelry from mined stone dependency, compressing entry price points while preserving visual equivalence. LVMH Moët Hennessy Louis Vuitton leverages its multi-brand architecture to sustain dominance across leather goods and spirits categories in Malaysian malls. Hermès International S.A. anchors its ultra-premium positioning through deliberate scarcity of Birkin and Kelly allocations in Kuala Lumpur boutiques. Kering SA competes via Gucci's aggressive digital campaigns targeting younger affluent demographics in Penang and Johor Bahru.
Luxury goods encompass products commanding premium pricing through brand heritage, superior craftsmanship, and restricted supply, typically utilizing precious metals, exotic leathers, and hand-finished mechanical movements with tolerances below 0.1 millimeters. These items serve as wealth signaling instruments and portable value stores for high-net-worth individuals. Fashion and accessories occupy the largest revenue pool among product types, driven by repeat purchase frequency and logo visibility. Watches represent the fastest-growing segment as Malaysian collectors deepen interest in haute horlogerie complications from Swiss maisons. Online retail channels expand fastest among sales channels, though boutiques retain margin superiority through personalized clienteling and exclusive preview events.
The Royal Malaysian Customs Department enforces import valuation protocols that inflate landed costs for watches and jewelry, while Malaysia's Consumer Protection Act governs authenticity claims and counterfeiting penalties. BIS-equivalent quality benchmarks for precious metal fineness apply to locally retailed jewelry, ensuring consumer confidence in gold and platinum purchases. Stakeholders must monitor how Putrajaya's evolving e-commerce tax enforcement affects cross-border luxury consignment flows from European e-tailers.
Market Dynamics
Lab-grown diamond technology is compressing fine jewelry entry thresholds while preserving visual equivalence, forcing traditional maisons to recalibrate scarcity-based positioning against chemically identical alternatives.
Growth Catalysts
- Royal Malaysian Customs Department valuation protocols:Standardized import documentation reduces clearance friction for authorized distributors of Swiss timepieces and Italian leather goods. Kuala Lumpur's luxury mall operators leverage this predictability to anchor tenant mix around heritage maisons.
- High-net-worth individual wealth signaling:Portable value storage demand intensifies as affluent households in Selangor and Penang diversify from property into wearable assets. Repeat purchase frequency in fashion accessories outpaces other luxury categories.
- Klang Valley retail cluster density:Concentrated affluence across Kuala Lumpur and Petaling Jaya supports flagship boutique economics. Personalized clienteling and exclusive preview events sustain margin superiority against digital channels.
Market Restraints
- Precious metal fineness compliance:BIS-equivalent quality benchmarks for gold and platinum jewelry impose testing costs on smaller domestic retailers. Certification delays constrain inventory velocity for independent jewelers in secondary cities.
- Swiss movement supply concentration:Haute horlogerie complications depend on a narrow supplier base in Geneva and Vallée de Joux. Geopolitical friction or production bottlenecks there transmit directly to Malaysian collector waitlists.
- Exotic leather sourcing restrictions:CITES documentation requirements for crocodile and python skins inflate landed costs. European tannery capacity limits constrain entry-level exotic goods availability in Johor Bahru.
Strategic Opportunities
- Penang and Johor Bahru geographic expansion:Affluent diaspora communities in George Town and Iskandar Malaysia remain underpenetrated relative to Klang Valley saturation. Digital-native campaigns targeting younger demographics in these cities build brand awareness ahead of physical boutique rollout.
- E-commerce tax enforcement clarity:Putrajaya's evolving cross-border consignment rules create incentive for authorized local distribution. Domestic warehousing of European inventory circumvents duty uncertainty for direct-to-consumer shipments.
- Mechanical watch complication convergence:Fusion of traditional haute horlogerie with silicon escapement technology reduces service intervals. Malaysian collectors deepen technical literacy, expanding addressable market for mid-complication pieces.
Industry Challenges
- Artisanal watchmaking skill scarcity:Certified horologists capable of servicing Swiss complications remain concentrated in Kuala Lumpur. Talent pipeline constraints limit after-sales network expansion to secondary markets.
- Authentication technology capex:Counterfeit detection systems for leather goods and timepieces require substantial investment. Smaller multi-brand retailers face margin compression from mandatory verification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Luxury Goods Market |
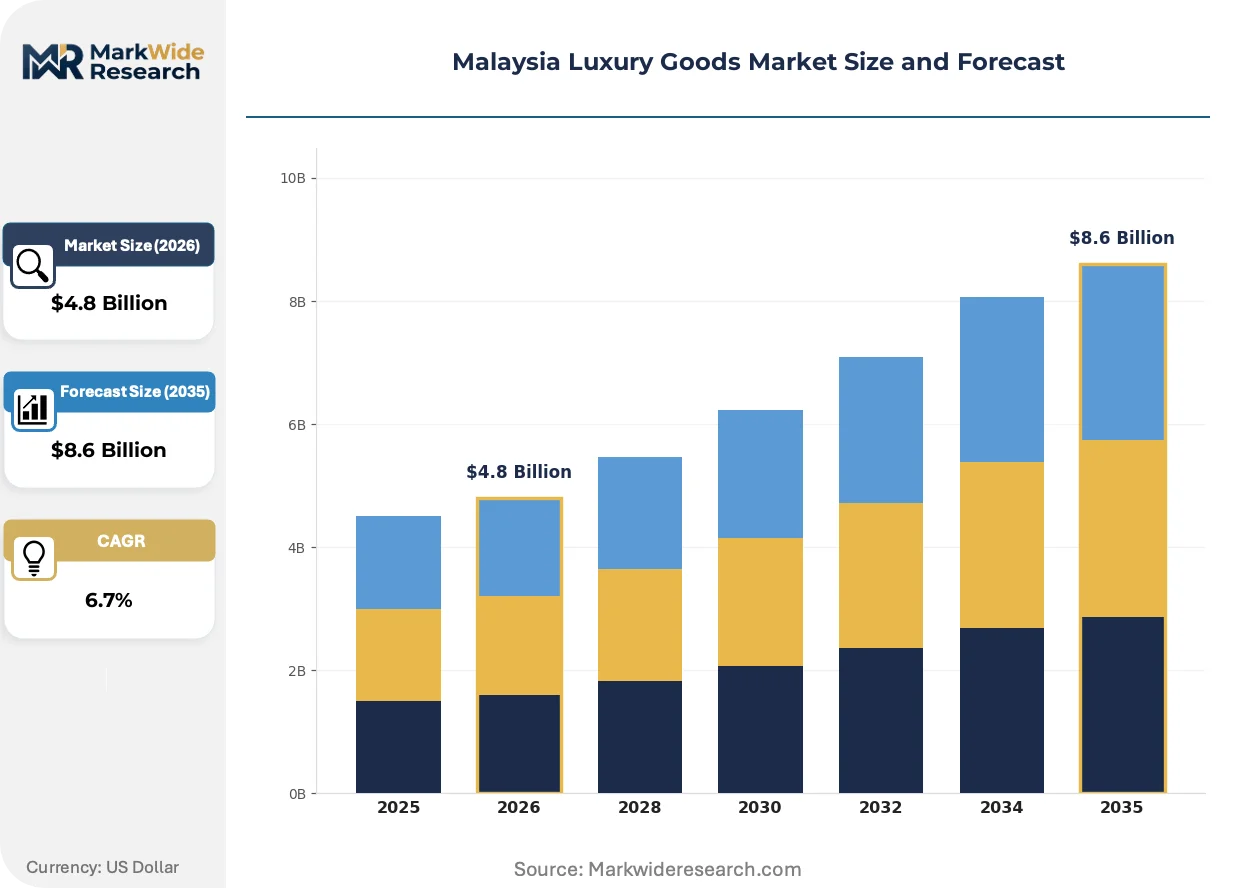
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Accessories, Jewelry, Watches Customer Type: Affluent Consumers, Tourists, Celebrities, Collectors Sales Channel: Online Retail, Department Stores, boutiques, Duty-Free Brand Category: High-End, Premium, Designer, Luxury |
| Companies Covered | Chanel Ltd., Burberry Group PLC, LVMH Moët Hennessy Louis Vuitton, Patek Philippe SA, Rolex S.A., Kering SA, Hermès International S.A., The Estée Lauder Companies Inc., Prada S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Luxury Goods Market Shifts & Advancements
Digitization of clienteling and authentication protocols is reconfiguring how heritage maisons engage Malaysian collectors, compressing the traditional boutique exclusivity model while elevating transparency expectations.
Blockchain-based provenance tracking is unifying certificate issuance, ownership transfer, and service history for high-value timepieces. Patek Philippe and Audemars Piguet collectors in Kuala Lumpur increasingly demand immutable records. This technology is unifying secondary market liquidity with primary retail confidence, narrowing the bid-ask spread on pre-owned complications.
Malaysia's Consumer Protection Act enforcement is tightening authenticity claim standards and counterfeiting penalties. The Royal Malaysian Customs Department coordinates with domestic retailers to intercept gray-market imports. Watch and jewelry segments with complex supply chains face elevated documentation burdens, pushing authorized distributors to consolidate procurement through single-country exporters.
Collector education investments are displacing passive brand loyalty among Malaysian haute horlogerie buyers. Enthusiast forums and independent authentication services in Penang and Selangor erode traditional boutique information asymmetry. This behavioral pivot concentrates demand on transparently documented pieces with complete service histories, compressing premiums for incomplete provenance.
Malaysia Luxury Goods Market Segmentation
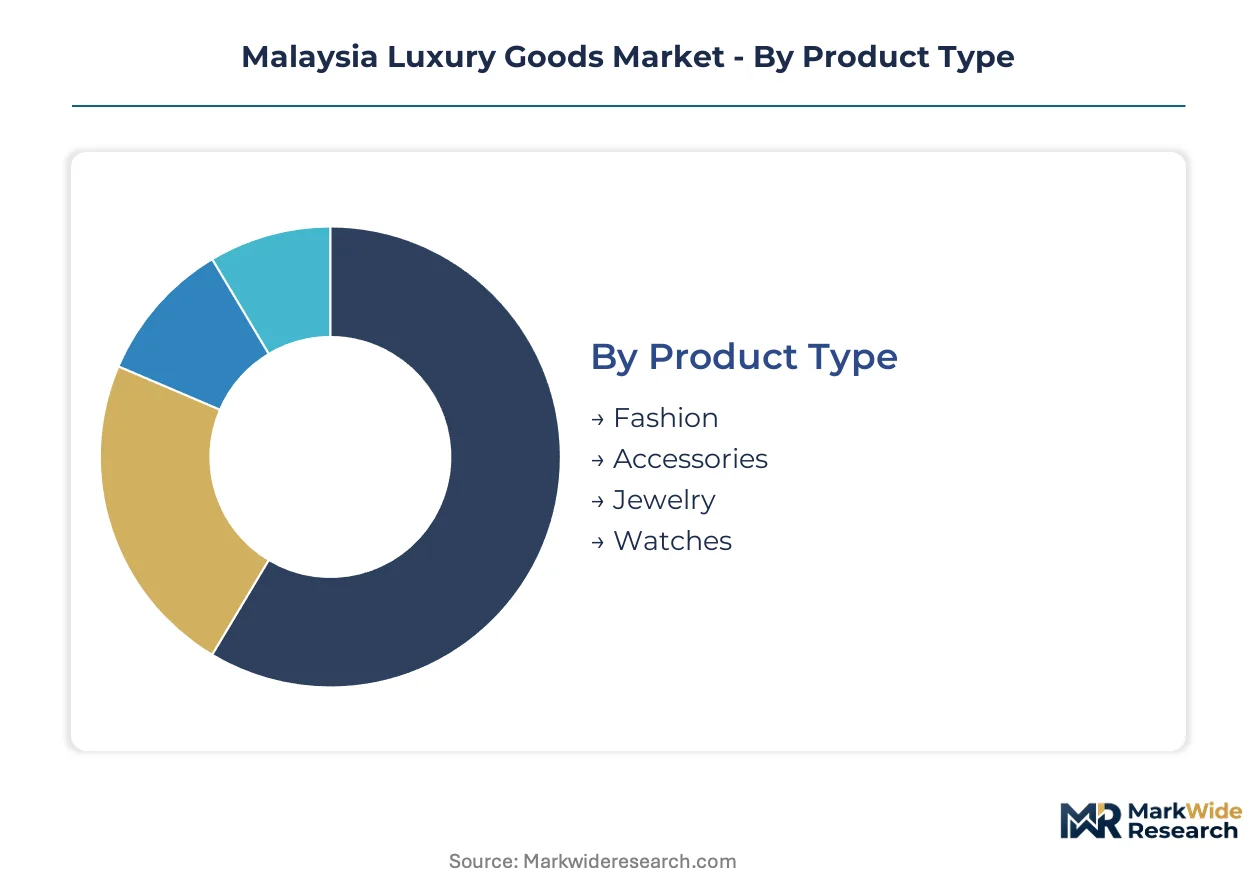
Malaysia's luxury goods segmentation reveals distinct upgrade cycles across product categories, with affluent households in Kuala Lumpur and Selangor driving replacement frequency in fashion and accessories while collectors pursue longer-horizon acquisitions in watches and jewelry.
Product Type:
Replacement cycles vary dramatically across physical goods, from seasonal wardrobe refreshes to generational heirloom acquisitions.
- Fashion:Ready-to-wear and leather goods from European maisons command the highest repeat purchase frequency among Malaysian consumers. Kuala Lumpur's mall clusters in Bukit Bintang and KLCC sustain inventory velocity through trunk shows and limited drops.
- Accessories:Silk scarves, small leather goods, and eyewear serve as entry-tier acquisitions for aspirational buyers in Petaling Jaya and Penang. Price accessibility expands the addressable base beyond core high-net-worth households.
- Jewelry:Fine jewelry incorporating lab-grown diamonds is compressing entry thresholds while preserving visual equivalence, forcing traditional maisons to recalibrate scarcity-based positioning.
- Watches:Haute horlogerie complications from Swiss manufacturers attract deepening technical literacy among Selangor collectors, expanding demand for mid-complication pieces with silicon escapement technology.
Fashion sits at the top of the volume ranking, with watches climbing the fastest.
Customer Type:
Purchase motivation and decision timelines diverge sharply across buyer profiles, from impulse tourists to methodical collectors.
- Affluent Consumers:Domestic high-net-worth individuals in the Klang Valley corridor concentrate demand for leather goods and fine jewelry, with wealth signaling driving portable asset diversification from property.
- Tourists:Visitors from China and the Middle East exploit Malaysia's duty-free allowances and favorable exchange rates for immediate acquisition of recognizable logo products.
- Celebrities:Local entertainment figures and social media influencers generate visibility-driven demand spikes for limited-edition releases, particularly in accessories categories.
- Collectors:Malaysian haute horlogerie enthusiasts in Penang and Johor Bahru increasingly demand blockchain-based provenance documentation and complete service histories, compressing premiums for incomplete records.
Affluent consumers dominate absolute volume, with collectors expanding most quickly as technical education displaces passive brand loyalty.
Sales Channel:
Channel economics reflect divergent margin structures, with personalized service commanding premium pricing against digital efficiency.
- Online Retail:Authorized e-commerce platforms expand fastest among channels, though Putrajaya's evolving cross-border consignment rules create incentive for domestic warehousing of European inventory.
- Department Stores:Anchor tenants in Suria KLCC and Pavilion Kuala Lumpur provide brand visibility but face margin pressure from concession fee structures and inventory risk.
- Boutiques:Flagship locations sustain margin superiority through personalized clienteling and exclusive preview events, with Klang Valley retail cluster density supporting flagship economics.
- Duty-Free:Kuala Lumpur International Airport and Langkawi outlets capture tourist traffic with price advantages, though selection concentrates on high-velocity SKUs rather than rare complications.
Boutiques retain the highest margin per transaction, with online retail gaining share fastest among domestic consumers.
Brand Category:
Brand tier determines pricing architecture and distribution exclusivity, with clear stratification across entry and ultra-premium positioning.
- High-End:Established heritage maisons with century-plus histories command automatic credibility among Malaysian collectors, particularly in mechanical watches and exotic leather goods.
- Premium:Accessible luxury brands target younger affluent demographics in Penang and Johor Bahru through aggressive digital campaigns and influencer partnerships.
- Designer:Fashion-forward labels with shorter heritage windows compete on trend velocity and celebrity placement rather than craftsmanship narratives.
- Luxury:Ultra-premium positioning through deliberate scarcity, as exemplified by controlled allocation of hand-finished leather goods in Kuala Lumpur boutiques.
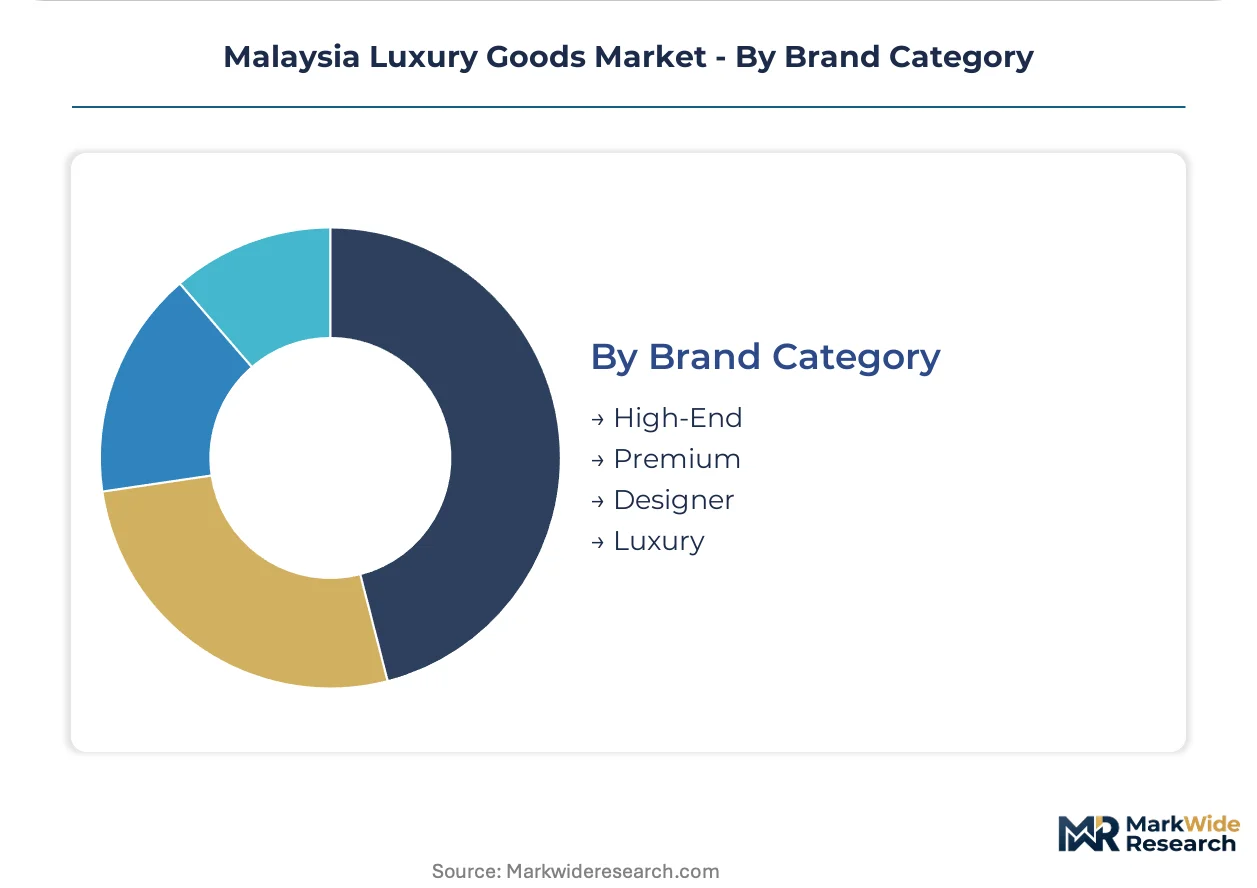
High-End captures the largest revenue pool, with Premium brands climbing fastest through digital-native customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Klang Valley corridor anchors Malaysia's luxury goods concentration, with Kuala Lumpur and Petaling Jaya generating the dominant share of high-end consumption. Affluent households in Selangor drive demand for Swiss timepieces and European leather goods through flagship boutiques in Bukit Bintang and KLCC mall clusters.
Kuala Lumpur
Flagship boutique economics concentrate in Bukit Bintang and KLCC districts, where personalized clienteling sustains margin superiority against digital channels. The Royal Malaysian Customs Department enforces standardized import documentation for authorized Swiss watch distributors. Heritage maisons anchor tenant mix in Pavilion Kuala Lumpur and Suria KLCC through exclusive preview events and trunk shows.
Selangor
Petaling Jaya and affluent suburbs in the Klang Valley support repeat purchase frequency in fashion accessories and ready-to-wear categories. Malaysia's Consumer Protection Act governs authenticity claims and counterfeiting penalties for domestic retailers. Mall operators in Sunway and One Utama leverage cluster density to attract younger affluent demographics through limited product drops.
Penang
George Town's affluent diaspora communities remain underpenetrated relative to Klang Valley saturation, creating expansion opportunities for digital-native campaigns. BIS-equivalent quality benchmarks for precious metal fineness apply to locally retailed jewelry, ensuring consumer confidence in gold purchases. Independent watch retailers in Gurney Plaza and Queensbay Mall deepen technical literacy among collector communities.
Johor Bahru
Iskandar Malaysia's proximity to Singapore creates cross-border shopping dynamics and duty-free arbitrage opportunities for luxury goods. CITES documentation requirements for exotic leather skins inflate landed costs for crocodile and python goods. Retailers in Johor Premium Outlets and City Square target price-sensitive aspirational buyers with accessible premium accessories.
Malaysia Luxury Goods Market Competitive Landscape
Scarcity-based allocation dominates the current landscape, with heritage maisons controlling supply of hand-finished leather goods and mechanical complications. The vendor base concentrates around multi-brand conglomerates with century-plus histories and independent family-owned watchmakers. Two strategic archetypes define positioning: ultra-premium scarcity players and accessible luxury digital marketers. Portfolio diversification and geographic expansion represent the dominant competitive moves, as players balance Klang Valley saturation against Penang and Johor Bahru penetration.
Within the ultra-premium scarcity tier, Hermès International S.A. and Patek Philippe SA exemplify deliberate supply constraint as a competitive weapon. LVMH Moët Hennessy Louis Vuitton anchors the multi-brand conglomerate archetype through leather goods and spirits dominance across Malaysian mall locations. These three entities occupy positions that smaller independent maisons cannot replicate without equivalent heritage narratives and controlled distribution architectures.
| Leading Market Players |
|---|
| Chanel Ltd. |
| Burberry Group PLC |
| LVMH Moët Hennessy Louis Vuitton |
| Patek Philippe SA |
| Rolex S.A. |
| Kering SA |
| Hermès International S.A. |
| The Estée Lauder Companies Inc. |
| Prada S.p.A. |
| Others |
Supply & Pricing Matrix
Ultra-premium scarcity positioning against accessible luxury digital channels bifurcates Malaysia's luxury goods landscape, with heritage maisons commanding 3-5x entry-tier premiums through controlled allocation while e-commerce compression forces margin recalibration on standardized SKUs. This divergence maps directly onto supply chain architectures: controlled scarcity depends on single-source European tanneries and Geneva movement suppliers, whereas accessible tiers draw from diversified Asian manufacturing hubs.
Pricing Analysis
Import duty pass-through from Royal Malaysian Customs Department valuation protocols anchors landed cost structures for Swiss timepieces and Italian leather goods. Price differentiation rests on brand heritage depth and hand-finishing certification tiers, with ultra-premium maisons extracting scarcity rents through deliberate allocation constraints. Cost compression in accessible jewelry intensifies as lab-grown diamond alternatives compress entry thresholds. Tourist buyers at Kuala Lumpur International Airport exhibit lowest price sensitivity, while aspirational domestic consumers in Johor Bahru drive volume through promotional accessibility.
Supply Chain Analysis
Single-source vulnerability sits with Swiss movement manufacturers in Geneva and Vallée de Joux, where haute horlogerie complications depend on artisanal suppliers with decade-long training pipelines. Raw material dependencies encompass CITES-regulated crocodile skins from European tanneries, platinum and gold bullion from South African refiners, and silicon wafer components for advanced escapements. Tariff exposure through Royal Malaysian Customs Department documentation requirements inflates landed costs for exotic leather goods. Distribution runs through Klang Valley flagship boutiques for margin capture, with online retail expanding through domestic warehousing of European inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's luxury goods market functions as a geographic-arbitrage play between Klang Valley saturation and Penang-Johor Bahru underpenetration, with duty-free allowances at Kuala Lumpur International Airport creating 15-20% cost differentials against Singapore retail.
For Market Incumbents: Acquire certified horologist talent pools to expand after-sales networks beyond Kuala Lumpur. Defensive consolidation demands backward integration into exotic leather tanning partnerships and blockchain-based provenance infrastructure deployment. Lab-grown diamond substitution threatens traditional jewelry scarcity positioning, requiring recalibration toward craftsmanship narratives and service bundling. Channel control through exclusive preview events sustains margin superiority against digital erosion. For New Entrants and Emerging Players: Enter via digital-native campaigns targeting George Town and Iskandar Malaysia's affluent diaspora communities ahead of physical boutique rollout. White-space concentration exists in mid-complication mechanical watches with silicon escapement technology, where technical literacy expansion outpaces supply. Penetrable segments include entry-tier accessories for aspirational buyers in secondary cities. Go-to-market execution should leverage influencer partnerships and limited product drops to build awareness without flagship capital commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with multi-brand conglomerates possessing heritage portfolio depth and controlled distribution architectures. Long-term viability across the projection horizon favors entities with century-plus brand narratives and scarcity-based allocation discipline. Acquisition target archetype: family-owned Swiss watchmakers with incomplete Asian distribution coverage. Signal to monitor: Putrajaya's cross-border e-commerce tax enforcement clarity as inflection indicator for domestic warehousing investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Brand Acquisition | Captures century-plus credibility narratives that challenger brands cannot replicate within Malaysian collector circles. |
| Blockchain Provenance Deployment | Unifies certificate issuance and ownership transfer for Patek Philippe and Audemars Piguet secondary market liquidity. |
| Penang-Johor Geographic Expansion | Exploits underpenetration in George Town and Iskandar Malaysia relative to Klang Valley saturation. |
| Domestic Warehousing Investment | Circumvents Royal Malaysian Customs Department duty uncertainty for direct-to-consumer European inventory flows. |
| Collector Education Programming | Builds technical literacy among Selangor enthusiasts to expand addressable market for mid-complication pieces. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with boutique managers, Swiss brand country representatives, Royal Malaysian Customs Department officials, and collector community organizers with secondary validation. Secondary sources encompassed customs valuation records, mall operator tenant mix disclosures, and BIS-equivalent precious metal certification databases. Bottom-up SKU-level demand modeling and top-down wealth distribution analysis were triangulated to anchor volume estimates.
Segment-weighting approaches distributed value across product type, customer archetype, sales channel, and brand tier dimensions throughout the forecast period. CAGRs were derived from affluence growth trajectories, replacement cycle compression in fashion categories, and collector penetration expansion in haute horlogerie. Industry-specific inputs included Klang Valley retail cluster density metrics, duty-free passenger traffic flows at Kuala Lumpur International Airport, and lab-grown diamond price elasticity assumptions.
Inputs from heritage maisons and authorized distributors were available through the study window; gaps in gray-market transaction volumes and private collector resale activity introduce uncertainty bands around secondary market sizing. Forecasts reflect documented assumptions regarding Putrajaya's regulatory enforcement trajectory and Swiss supplier capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Piano Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Wooden Watch Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
India Watch Market