
 Luxury Apparels Market | 2026-2036
Luxury Apparels Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Apparels Market Analysis
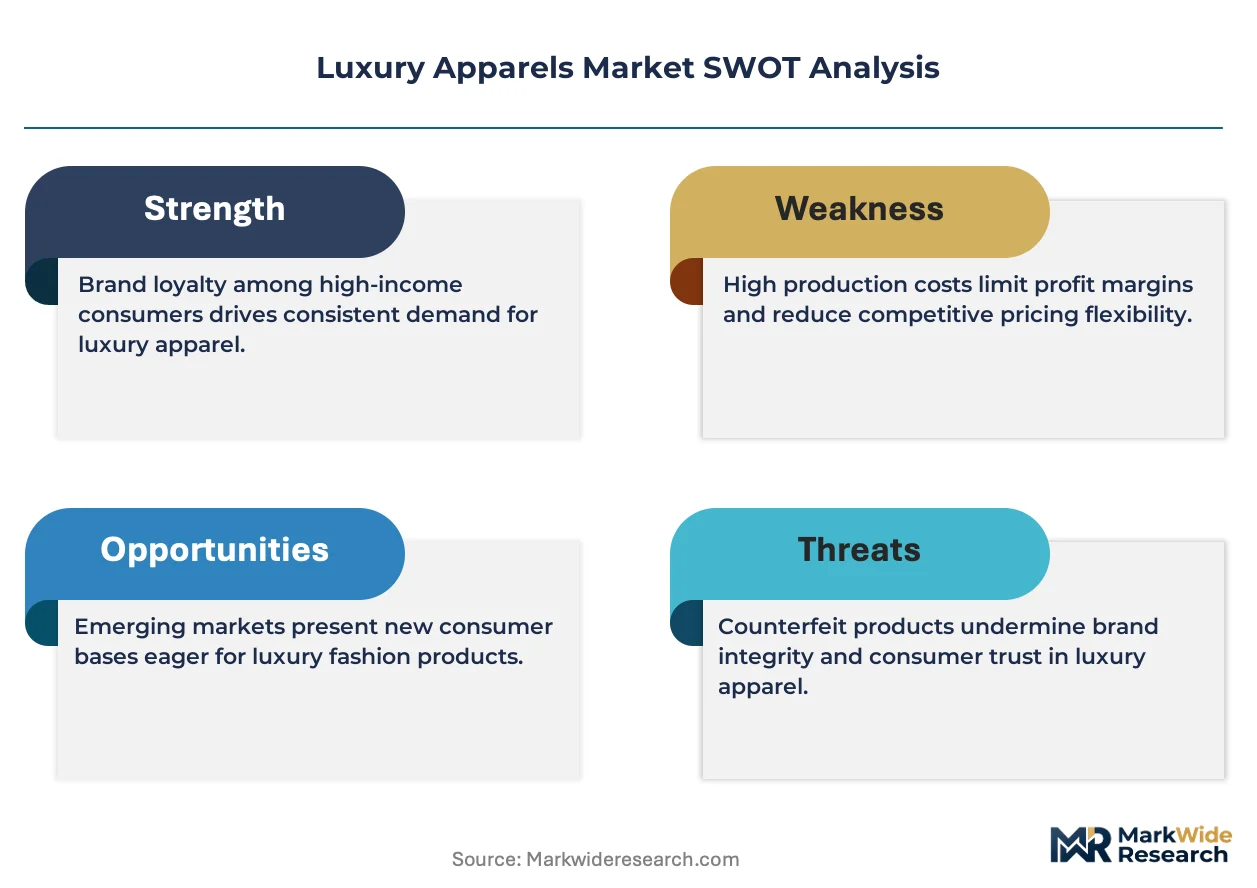
Asset-light licensing and franchise financing is fragmenting competitive barriers in luxury apparel, allowing regional aspirants to scale without capital-intensive retail buildouts. Kering SA leverages selective licensing partnerships to extend brand reach into secondary cities without direct store investment. LVMH Moët Hennessy Louis Vuitton sustains its position through captive manufacturing of leather goods and vertical control over raw material sourcing. Hermès International anchors its scarcity model through deliberate production constraints and wait-list mechanics that reinforce pricing power.
Luxury apparels encompass garments and accessories crafted from premium natural materials with exacting construction standards, typically involving hand-finished seams, bespoke pattern-making, and material grades that exceed conventional retail specifications by factors of ten or more in unit cost. These products serve as positional goods where utility functions as a carrier for social signaling and wealth demonstration. The women's end-user segment commands the deepest margin pools across dresses and handbags, while the online distribution channel represents the fastest structural expansion as brands deploy clienteling apps and virtual try-on tools. Leather as a material category dominates value concentration due to its durability premium and the technical complexity of tanning and finishing processes that resist commoditization.
The EU Green Deal and France's AGEC anti-waste law are reshaping compliance obligations through mandatory digital product passports and extended producer responsibility frameworks for textile waste. China's GB standards and evolving dual carbon goals are pressing domestic luxury production toward cleaner dyeing and finishing processes. Stakeholders must monitor how regulatory fragmentation across these jurisdictions reshapes cost structures and determines which suppliers retain market access.
Market Dynamics
EU Green Deal traceability mandates and France's AGEC law are forcing luxury apparel brands to reengineer supply chains around digital product passports, compressing margins for non-compliant suppliers while rewarding vertically integrated producers with verified sourcing.
Growth Catalysts
- Experiential luxury wardrobes:High-net-worth millennials and Gen Z consumers are expanding adoption of occasion-based rental and resale models that extend brand touchpoints beyond ownership.
- EU Green Deal:Mandatory digital product passports create competitive differentiation for early-compliant brands, locking in preferred supplier relationships before enforcement deadlines.
- Clienteling apps:Virtual try-on tools and AI-powered personalization are converting online browsers at rates that narrow the historical gap with physical retail conversion.
Market Restraints
- Raw material concentration:Premium leather tanning capacity clusters in Italian and French tanneries, creating single-source vulnerability for scarcity-positioned brands.
- AGEC compliance costs:France's anti-waste law mandates extended producer responsibility frameworks that add 8-12% to unit economics for small-batch producers.
- Silk and cashmere price volatility:Climate stress on Mongolian herding regions and Chinese sericulture belts is compressing gross margins on natural fiber-dependent collections.
Strategic Opportunities
- Secondary city penetration:China's domestic luxury consumption outpaces outbound purchasing, creating whitespace in Chengdu, Hangzhou, and Xi'an for experiential retail formats.
- Biomaterial convergence:Lab-grown leather and bacterial cellulose are crossing performance thresholds that enable regulatory-compliant positioning without scarcity trade-offs.
- Resale infrastructure:Authentication-as-a-service platforms unlock circular revenue streams while preserving brand equity through controlled secondary markets.
Industry Challenges
- Artisan skill scarcity:Hand-finishing expertise concentrates in aging European workforces, with apprenticeship pipelines failing to replace retiring pattern-makers.
- Multi-jurisdiction compliance:Divergent EU, Chinese GB standards, and emerging US state-level textile regulations fragment certification timelines and testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Apparels Market |
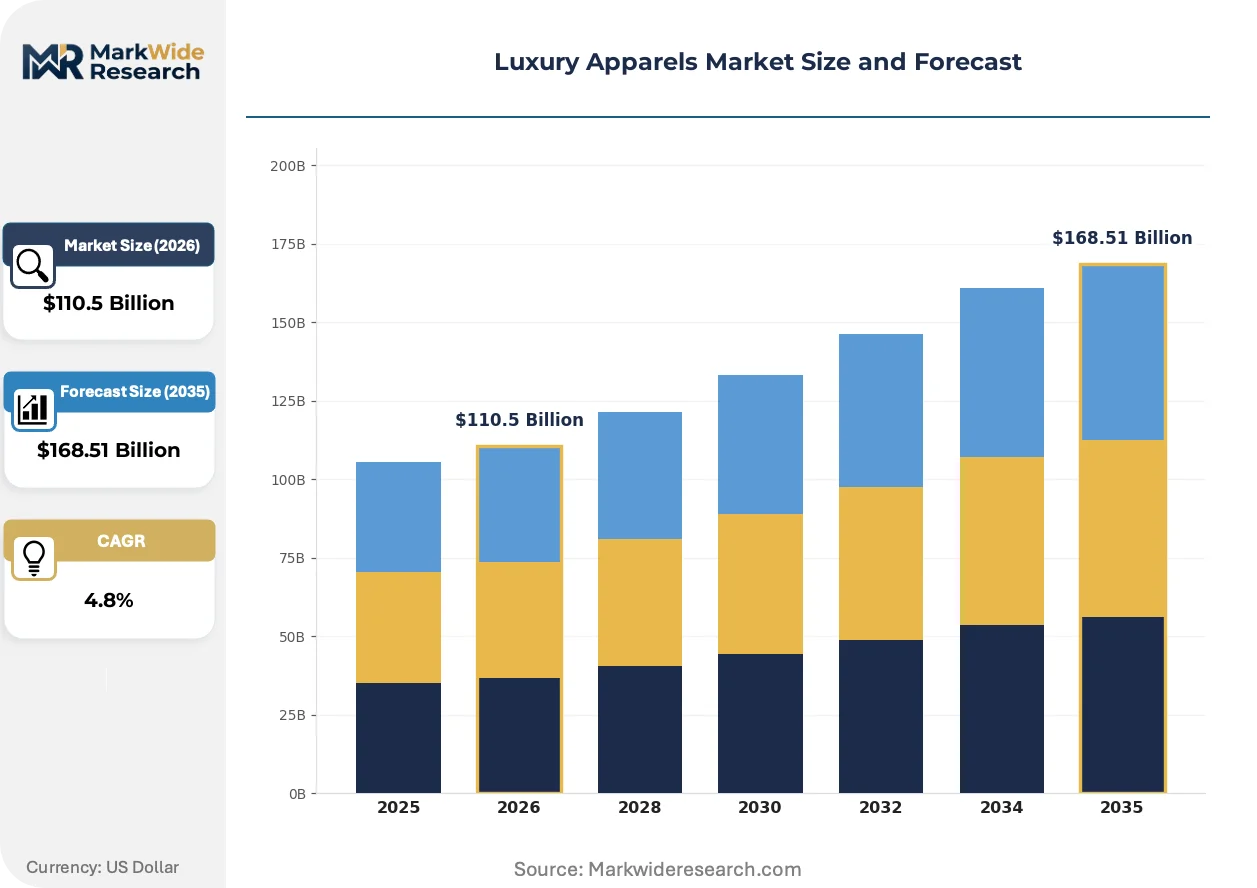
| Market Size in 2026 | $110.5 Billion |
| Market Size in 2035 | $168.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coats, Dresses, Handbags, Shoes Material: Cashmere, Silk, Leather, Wool End User: Women, Men, Children, Couples Distribution Channel: Online, Boutique Stores, Department Stores, Outlets |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering SA, Hermès International, Prada Holding, Giorgio Armani, Burberry Group, Ralph Lauren Corporation, Capri Holdings Limited, Chanel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Apparels Market Emerging Trajectories
Digital product passports and generative design tools are converging with biomaterial science to reshape how luxury apparel is sourced, certified, and consumed across primary and secondary markets.
Blockchain-enabled provenance tracking is digitizing supply chain verification for raw material origins, with Kering and LVMH piloting interoperable systems that trace leather from tannery to retail floor. Early adopters in the women's handbag segment are capturing price premiums of 15-20% for fully documented collections. This transparency infrastructure is digitizing the trust mechanics that previously required physical inspection and brand heritage.
France's AGEC law and the EU Green Deal are mandating extended producer responsibility for textile waste, forcing brands to internalize end-of-life costs previously externalized to municipal systems. Compliance deadlines in 2025 are accelerating investment in take-back logistics and fiber-to-fiber recycling partnerships. The women's ready-to-wear category faces the steepest restructuring, with Paris-based houses renegotiating supplier contracts to include waste clauses.
Secondhand platform integration is disrupting traditional channel hierarchies, with authenticated resale displacing outlet stores as the primary entry point for aspirational buyers. Gen Z consumers in China and the United States are treating resale platforms as discovery channels rather than discount destinations. This behavioral pivot is most visible in the sneaker and streetwear adjacencies, where limited drops now explicitly price future resale value into initial retail positioning.
Luxury Apparels Market Segmentation
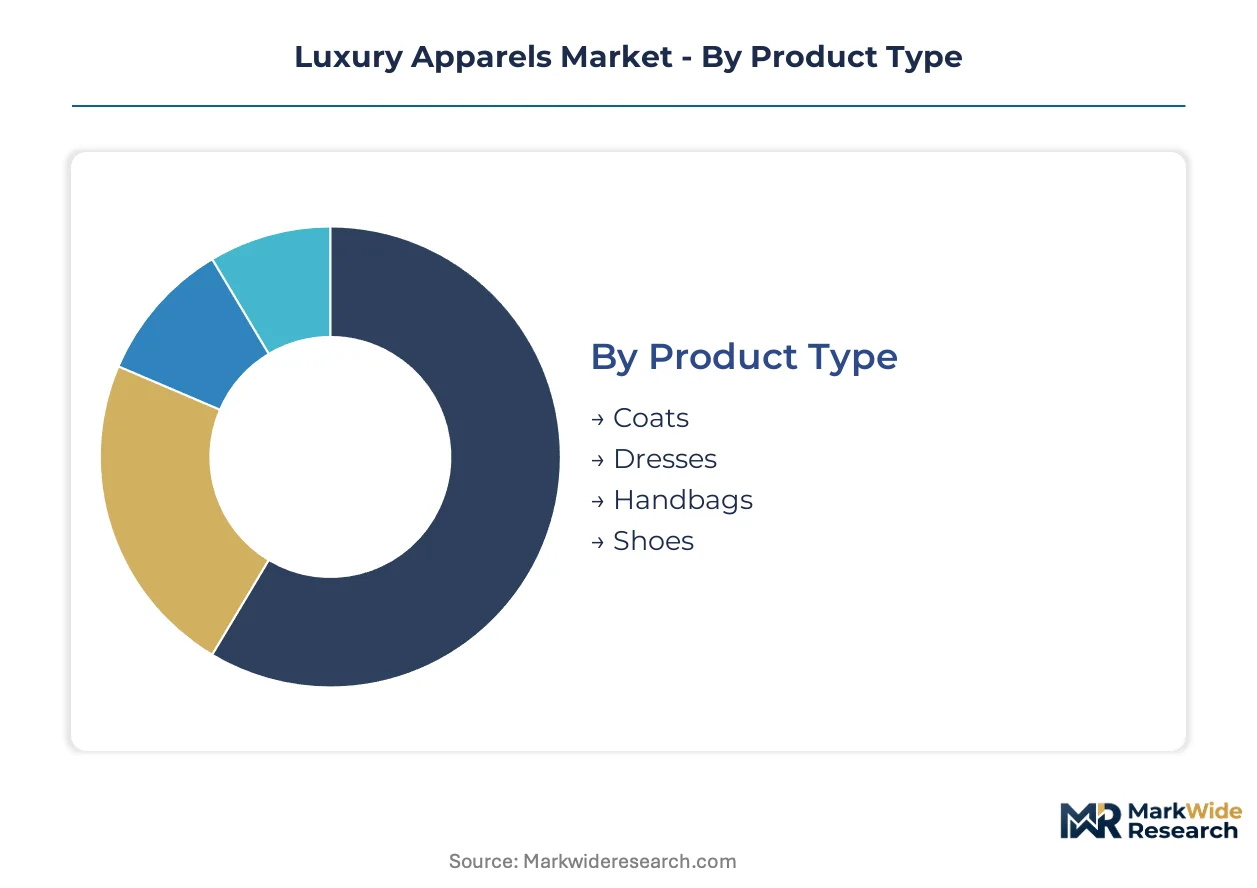
Segmentation in luxury apparel reveals how pricing power, material scarcity, and channel control intersect to determine margin capture. Distinct consumer cohorts, sourcing strategies, and retail formats demand tailored positioning rather than uniform market approaches.
Product Type:
Mature outerwear and accessories coexist with emerging experiential categories that blur ownership and access.
- Coats:Tailored outerwear incorporating hand-finished seams and premium insulation commands sustained pricing in European and Northeast Asian climates. Demand clusters in Milan, Paris, and Tokyo where seasonal wardrobes require investment-grade thermal protection.
- Dresses:Occasion-based silhouettes with bespoke pattern-making anchor the women's segment's deepest margin pools. High-net-worth collectors in Shanghai and New York drive made-to-measure commissioning for gala and wedding circuits.
- Handbags:Leather goods with scarcity-engineered distribution dominate value concentration per unit.
- Shoes:Artisan-constructed footwear with hand-stitched welts resists mass-manufacturing replication.
Dresses handle the majority of throughput; Handbags is expanding most quickly on share.
Material:
Cost tier stratification separates scarcity-positioned natural fibers from emerging biomaterial alternatives.
- Leather:Full-grain hides processed through vegetable tanning in Italian and French tanneries create durability premiums that resist commoditization. Technical complexity in finishing processes limits supplier pools to heritage clusters around Tuscany and Alsace.
- Cashmere:Fine undercoat fibers from Mongolian herding regions face climate stress compression on available supply. Processing concentration in Scottish and Italian mills creates bottleneck vulnerability for premium knitwear collections.
- Silk:Sericulture-dependent production in Chinese provinces faces water stress and labor migration challenges.
- Wool:Merino grades from Australian and New Zealand stations supply structured tailoring with traceable provenance.
Leather commands the dominant value concentration; Cashmere is gaining share fastest amid fiber substitution pressures.
End User:
Customer type determines collection breadth, with gendered segments showing divergent purchase frequency and margin profiles.
- Women:Multi-category purchasing across ready-to-wear, leather goods, and fine jewelry generates the highest lifetime value per account. Clienteling investments concentrate on this segment in flagship locations from Bond Street to Ginza.
- Men:Wardrobe-building around tailored clothing and accessories shows lower frequency but higher average transaction values. Bespoke services in London's Savile Row and Milan's Via Montenapoleone sustain artisan employment pipelines.
- Children:Occasion-driven purchasing for ceremonial events creates seasonal demand spikes.
- Couples:Coordinated gifting and wedding registry participation expand touchpoints for house entry.
Women handles the majority of throughput; Men is climbing the fastest on share as formal dressing resurges.
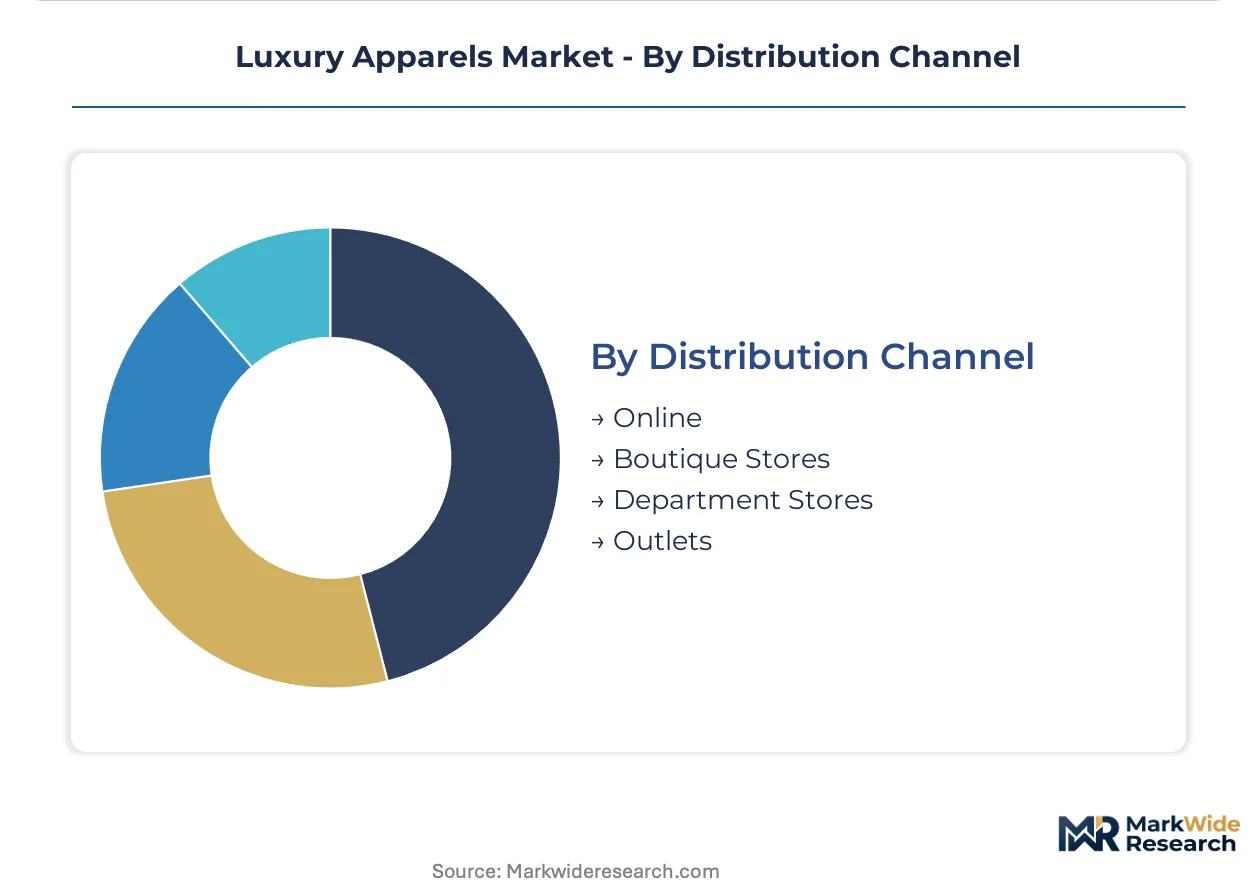
Distribution Channel:
Geography of engagement separates experiential retail destinations from convenience-oriented digital capture.
- Online:Clienteling apps with virtual try-on and AI-powered personalization are narrowing conversion gaps with physical retail. Investment in authenticated resale infrastructure is converting Chinese and American Gen Z browsers into primary market entrants.
- Boutique Stores:Flagship locations in Paris, Milan, and Shanghai provide immersive brand universe exposure that justifies full-price positioning. Experiential formats with private appointment suites capture ultra-high-net-worth clientele.
- Department Stores:Concession models in Harrods, Galeries Lafayette, and Bergdorf Goodman provide reach without capital-intensive buildouts.
- Outlets:Secondary channel positioning is being displaced by controlled resale platforms for aspirational buyer entry.
Boutique Stores handles the majority of throughput; Online shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and Italy maintain persistent trade surpluses in luxury apparel exports, while China absorbs the largest import share as domestic consumption displaces outbound purchasing. The United States and Japan represent mature absorption markets with divergent regulatory exposure.
France
Paris-based maisons drive haute couture commissioning and leather goods scarcity positioning. The AGEC anti-waste law mandates extended producer responsibility frameworks that restructure supplier contracts around waste clauses. Lyon and Alsace host heritage tanning clusters where vegetable-processing expertise concentrates for premium hide finishing.
Italy
Milan anchors ready-to-wear production and artisan footwear construction for global distribution. EU Green Deal traceability requirements are compressing margins for non-compliant suppliers while rewarding vertically integrated producers. Tuscany's Santa Croce sull'Arno tannery district supplies full-grain leather to scarcity-positioned brands facing single-source vulnerability.
China
Shanghai and Hangzhou concentrate experiential retail expansion as domestic luxury consumption outpaces outbound purchasing. GB standards and dual carbon goals press domestic production toward cleaner dyeing and finishing processes. Chengdu and Xi'an emerge as whitespace markets for flagship experiential formats targeting high-net-worth millennials.
United States
New York and Los Angeles sustain bespoke tailoring and celebrity-driven brand discovery for aspirational buyers. Emerging state-level textile regulations fragment certification timelines beyond federal frameworks. Miami and Dallas host secondary market authentication infrastructure displacing traditional outlet channels.
Japan
Tokyo's Ginza and Osaka's Shinsaibashi districts sustain ultra-high-net-worth clienteling with private appointment suites. METI standards intersect with consumer preference for provenance documentation in leather goods purchasing. Kyoto preserves artisan pattern-making pipelines that European houses increasingly recruit for hand-finishing expertise.
Luxury Apparels Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in tanning, embroidery, and hardware forging. The competitive set arranges into three tiers: conglomerate houses with captive manufacturing, independent family-controlled maisons with deliberate scarcity mechanics, and licensed regional operators scaling through asset-light partnerships. Consolidation pressure concentrates among mid-scale players lacking vertical control over raw material sourcing. Dominant competitive moves include selective licensing partnerships for secondary city penetration and backward integration into heritage tanneries.
Within the conglomerate tier, LVMH Moët Hennessy Louis Vuitton and Kering SA exemplify divergent sourcing strategies—one through captive leather goods manufacturing, the other through selective licensing for geographic extension. Hermès International occupies a position representing the independent family-controlled archetype with production constraint mechanics. These three anchors illustrate how competitive positioning in luxury apparel depends on supply chain configuration rather than marketing expenditure alone.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering SA |
| Hermès International |
| Prada Holding |
| Giorgio Armani |
| Burberry Group |
| Ralph Lauren Corporation |
| Capri Holdings Limited |
| Chanel |
| Others |
Supply Flow & Price Mechanics
Italian and French tannery clusters for full-grain vegetable-tanned leather concentrate upstream scarcity, locking margin capture downstream with scarcity-positioned maisons who engineer wait-list mechanics and deliberate production constraints. This geographic concentration of heritage finishing expertise enables pricing power that commodity tanneries cannot replicate, while EU Green Deal traceability mandates reward early-compliant brands with preferred supplier access ahead of enforcement deadlines.
Pricing Analysis
High-net-worth collectors anchor pricing stratification across premium, standard, and aspirational tiers in luxury apparel. Price differentiation rests on material grade certification, hand-finishing intensity, and provenance documentation depth. Cost compression in small-batch ready-to-wear intensifies as France's AGEC law mandates extended producer responsibility frameworks adding compliance overhead. Aspirational buyers entering through authenticated resale platforms exhibit highest price sensitivity, while ultra-high-net-worth clientele commissioning bespoke pieces show near-zero elasticity.
Supply Chain Analysis
Single-source vulnerability in Mongolian cashmere herding regions and Chinese sericulture belts dominates supply chain risk exposure for natural fiber-dependent collections. Raw material dependencies draw from premium hide inputs, Mongolian undercoat fibers, and Chinese silk filaments. Tariff exposure between EU and US jurisdictions fragments certification timelines for cross-border distribution. Distribution runs through flagship experiential retail in Paris, Milan, and Shanghai, supplemented by clienteling apps with virtual try-on conversion tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand-finishing expertise in aging European workforces represents the critical capability gap constraining production expansion, as apprenticeship pipelines fail to replace retiring pattern-makers in Tuscany and Alsace. This artisan scarcity rewards brands who secure employment pipelines ahead of competitor recruitment.
For Market Incumbents: Harden supplier relationships through backward integration into heritage tanneries in Santa Croce sull'Arno and Alsace, locking in vegetable-tanning capacity before competitor consolidation. Secure pattern-maker apprenticeships in Kyoto and Lyon to defend against artisan skill scarcity threatening collection expansion. Channel control through private appointment suites in flagship locations preserves full-price positioning against resale platform encroachment. For New Entrants and Emerging Players: Build out experiential retail formats in Chengdu, Hangzhou, and Xi'an where domestic Chinese luxury consumption outpaces outbound purchasing and incumbent flagship saturation remains low. Target high-net-worth millennials through clienteling apps with AI-powered personalization and virtual try-on tools that narrow conversion gaps with physical retail. Partner with authentication-as-a-service platforms to unlock circular revenue streams while preserving brand equity in controlled secondary markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional licensees scaling through asset-light partnerships without captive manufacturing depth. Long-term viability across the next decade hinges on vertical control over raw material sourcing and compliance infrastructure for EU Green Deal traceability mandates. Watch for AGEC enforcement deadline compliance gaps as inflection indicators separating acquisition-ready targets from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Tannery Acquisition | Captures vegetable-tanning expertise concentrated in Tuscany and Alsace for scarcity positioning. |
| Digital Product Passport Deployment | Locks in preferred supplier relationships ahead of EU Green Deal enforcement deadlines. |
| Biomaterial R&D Partnership | Crosses performance thresholds for lab-grown leather and bacterial cellulose regulatory compliance. |
| Secondary City Flagship Expansion | Captures whitespace in Chengdu, Hangzhou, and Xi'an as domestic Chinese consumption accelerates. |
| Artisan Apprenticeship Pipeline | Addresses pattern-maker scarcity in aging European and Japanese workforces threatening production capacity. |
Methodological Framework
A spread of perspectives from creative directors, supply chain officers at conglomerate houses, tannery operations managers in Tuscany, luxury retail buyers at Harrods and Galeries Lafayette, and sustainability compliance leads converged on the working assumptions. These primary insights combined with secondary validation from customs trade data, SEC 10-K filings, EU regulatory submissions, and textile certification databases. Bottom-up collection-level analysis and top-down market sizing triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segment dimensions including product type, material grade tier, end-user gender, and distribution channel complexity. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and generational consumption shifts. Forecast inputs incorporated climate stress on Mongolian herding regions, dual carbon goal implementation timelines in China, and AGEC compliance cost absorption rates.
Stress conditions across raw material price volatility, regulatory enforcement timelines, and artisan labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity between natural and biomaterial alternatives, resale platform penetration rates, and experiential retail conversion benchmarks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Watch Winder Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Europe Handbags Market
Luxury Goods
Mens Watch Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
United States Luxury Goods Market