
 GCC Personal Luxury Goods Market | 2026-2036
GCC Personal Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Personal Luxury Goods Market Intelligence
Modular capsule collections paired with exclusive hospitality experiences is repositioning how affluent buyers construct luxury wardrobes across the Gulf. LVMH Moët Hennessy Louis Vuitton leverages its integrated retail-hotel partnerships in Dubai to sustain year-round foot traffic. Chanel anchors its regional presence through private salon formats that dominate high-value client retention. Chalhoub Group competes via localized merchandising controls that extend its reach across Saudi mall developments.
Personal luxury goods encompass premium apparel, leather goods, timepieces, jewelry, and cosmetics distinguished by craftsmanship, heritage branding, and scarcity-driven pricing mechanisms. These products serve status-signaling functions for consumers while generating margin pools for operators through controlled distribution and limited-edition release cycles. Fashion and watches represent the most mature revenue categories, with jewelry capturing expanding share as Saudi women enter higher workforce participation. Tourists and high net worth individuals form the fastest-growing customer segments, while duty-free shops and boutiques concentrate margin capture through personalized service architectures.
Saudi Arabia's Fashion Commission and the UAE's commercial licensing frameworks shape product standards and market access for international houses. VAT treatment variations between Riyadh and Dubai create arbitrage conditions that influence inventory placement and pricing architecture. Stakeholders must monitor evolving local content requirements and e-commerce licensing protocols as Gulf governments tighten oversight on digital luxury transactions.
Market Dynamics
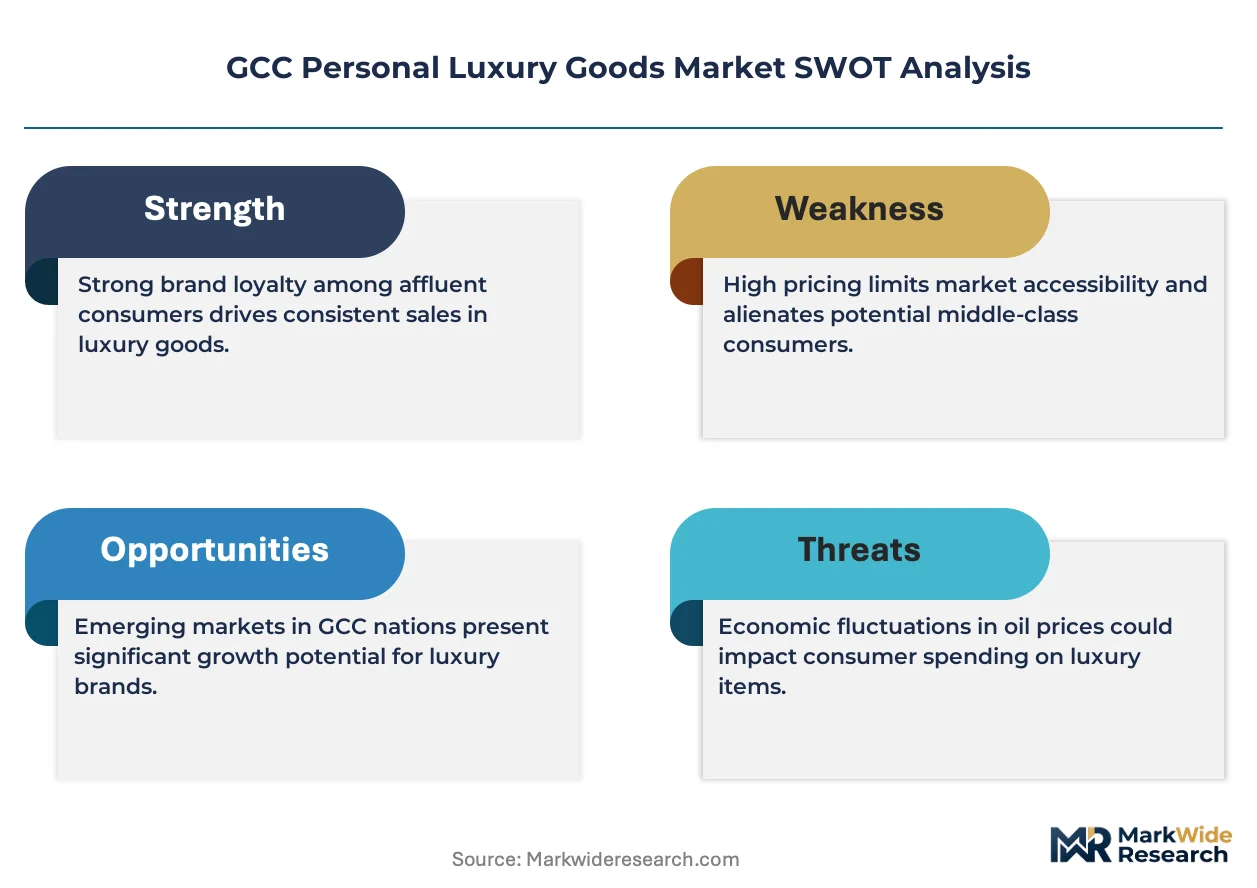
Saudi Arabia's Fashion Commission licensing mandates and the UAE's evolving e-commerce protocols are forcing international luxury houses to restructure their Gulf market entry frameworks around localized compliance rather than standardized global rollouts.
Growth Catalysts
- Experience-Retail Integration:Dubai Mall's hospitality-anchored formats and Riyadh Season's event-driven commerce are pulling tourist spending into high-margin personalized service environments.
- Saudi Workforce Participation:Expanding female labor force entry is accelerating jewelry and professional leather goods adoption as status-signaling categories.
- VAT Arbitrage Conditions:Divergent tax treatment between Riyadh and Dubai is incentivizing inventory placement optimization and regional pricing architecture recalibration.
Market Restraints
- Import Duty Volatility:GCC customs harmonization gaps create unpredictable landed cost structures for European leather goods and Swiss timepieces.
- Distribution Concentration:Mall operator oligopolies in Dubai and Riyadh extract premium lease terms that compress boutique-level margins.
- Authentication Technology Gaps:Digital provenance verification standards remain fragmented across Saudi and UAE regulatory frameworks, delaying resale market formalization.
Strategic Opportunities
- Kuwait and Bahrain Penetration:Underserved high-net-worth density in Manama and Kuwait City offers first-mover positioning ahead of mall infrastructure saturation.
- Concierge Platform Convergence:WhatsApp Business API integration with legacy clienteling systems is enabling hyper-personalized pre-arrival inventory curation.
- Local Content Incentives:Saudi Fashion Commission's domestic manufacturing credits create pathways for regional atelier establishment and craft workforce development.
Industry Challenges
- Arabic-Language Digital Talent Scarcity:Luxury e-commerce localization requires specialized UX and CRM expertise that regional labor markets undersupply.
- Legacy System Integration Friction:European headquarters' ERP architectures conflict with Gulf-specific VAT reporting and Sharia-compliant payment gateway requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Personal Luxury Goods Market |
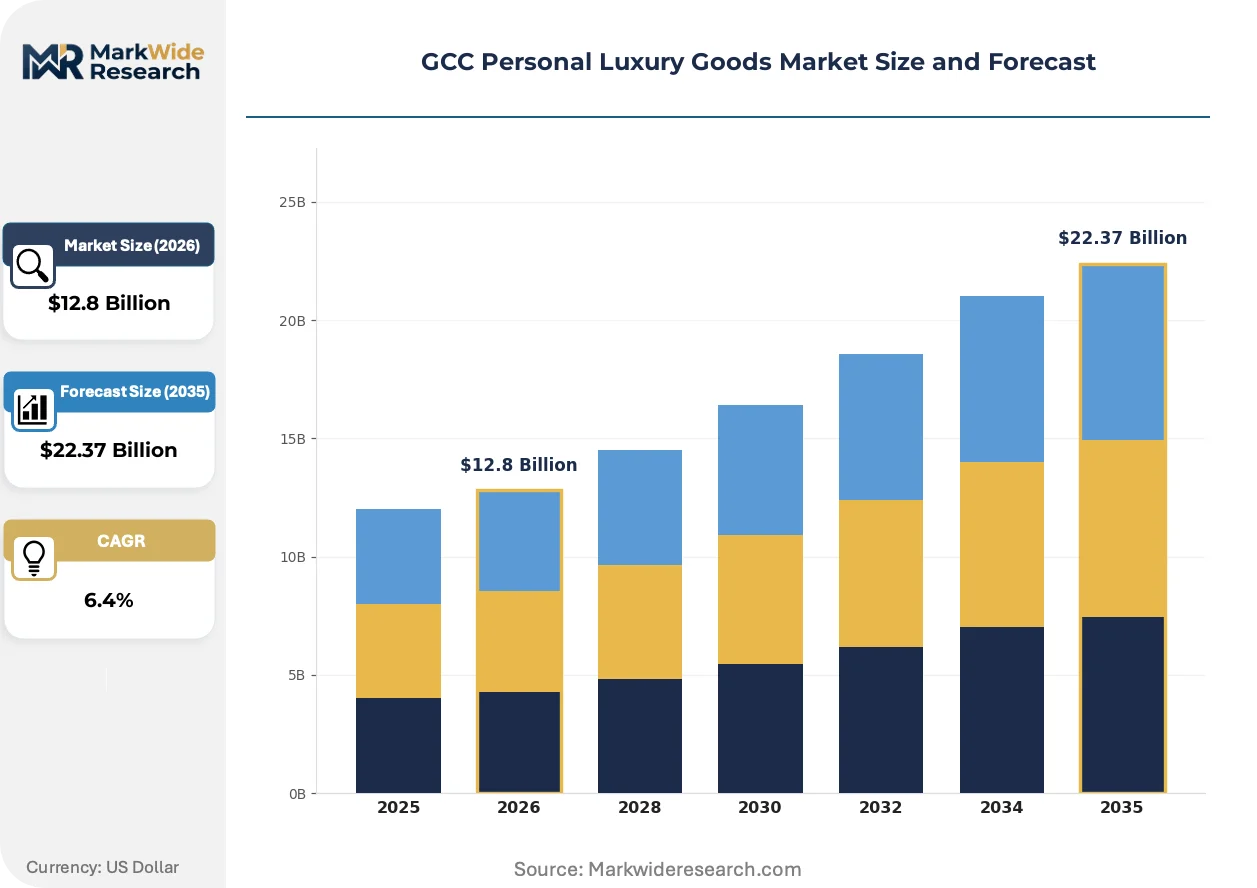
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
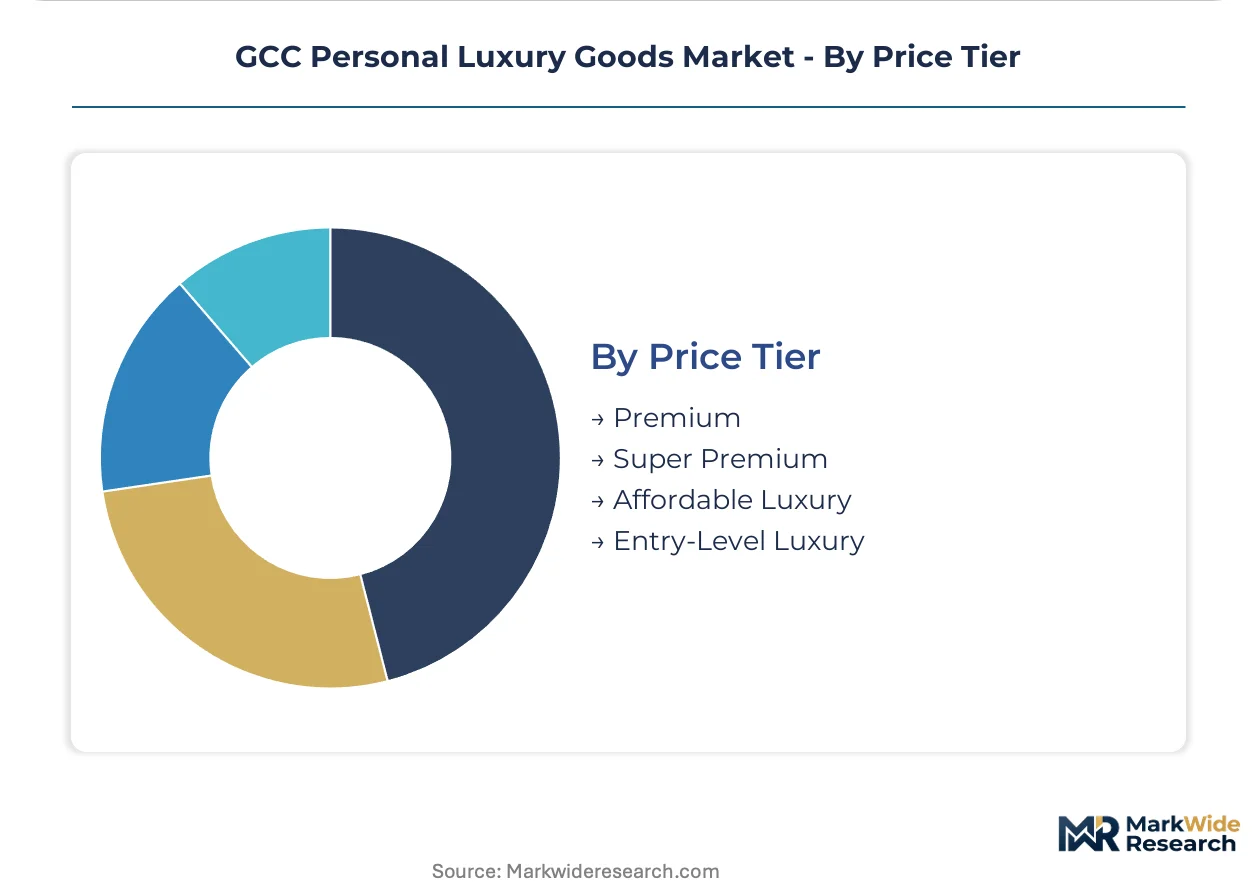
| Segmentation | Product Type: Fashion, Jewelry, Watches, Accessories Customer Type: Affluent Consumers, Millennials, High Net Worth Individuals, Tourists Distribution Channel: Department Stores, E-commerce, Boutiques, Duty-Free Shops Price Tier: Premium, Super Premium, Affordable Luxury, Entry-Level Luxury |
| Companies Covered | Chanel, Burberry Group, LVMH Moët Hennessy Louis Vuitton, Giorgio Armani, Prada Group, Kering, Estée Lauder Companies, Chalhoub Group, Compagnie Financière Richemont, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Personal Luxury Goods Market Strategic Shifts & Innovations
Digital authentication layers and regulatory localization are compressing how luxury houses architect trust and compliance across Gulf markets. These shifts favor operators with modular technology stacks and region-dedicated legal infrastructure.
Blockchain-based provenance verification is converging with physical product tags to create immutable ownership records for high-value timepieces and jewelry. Saudi collectors and UAE-based family offices are piloting these systems at scale. This convergence is compressing resale market opacity and enabling fractional ownership structures previously blocked by authentication risk.
The UAE's commercial licensing frameworks and Saudi Arabia's Fashion Commission technical standards are mandating expanded Arabic-language labeling and regional quality certification. Houses must now maintain parallel product documentation streams. Smaller leather goods and cosmetics categories face the steepest compliance timeline compression as enforcement windows narrow.
Experiential purchasing now dominates high-value client acquisition across Dubai and Riyadh. Private salon appointments and hospitality-anchored shopping itineraries are displacing traditional boutique walk-in traffic. This behavioral pivot is most visible among tourist segments and inter-Gulf high-net-worth buyers who prioritize exclusivity over convenience.
GCC Personal Luxury Goods Market Segmentation
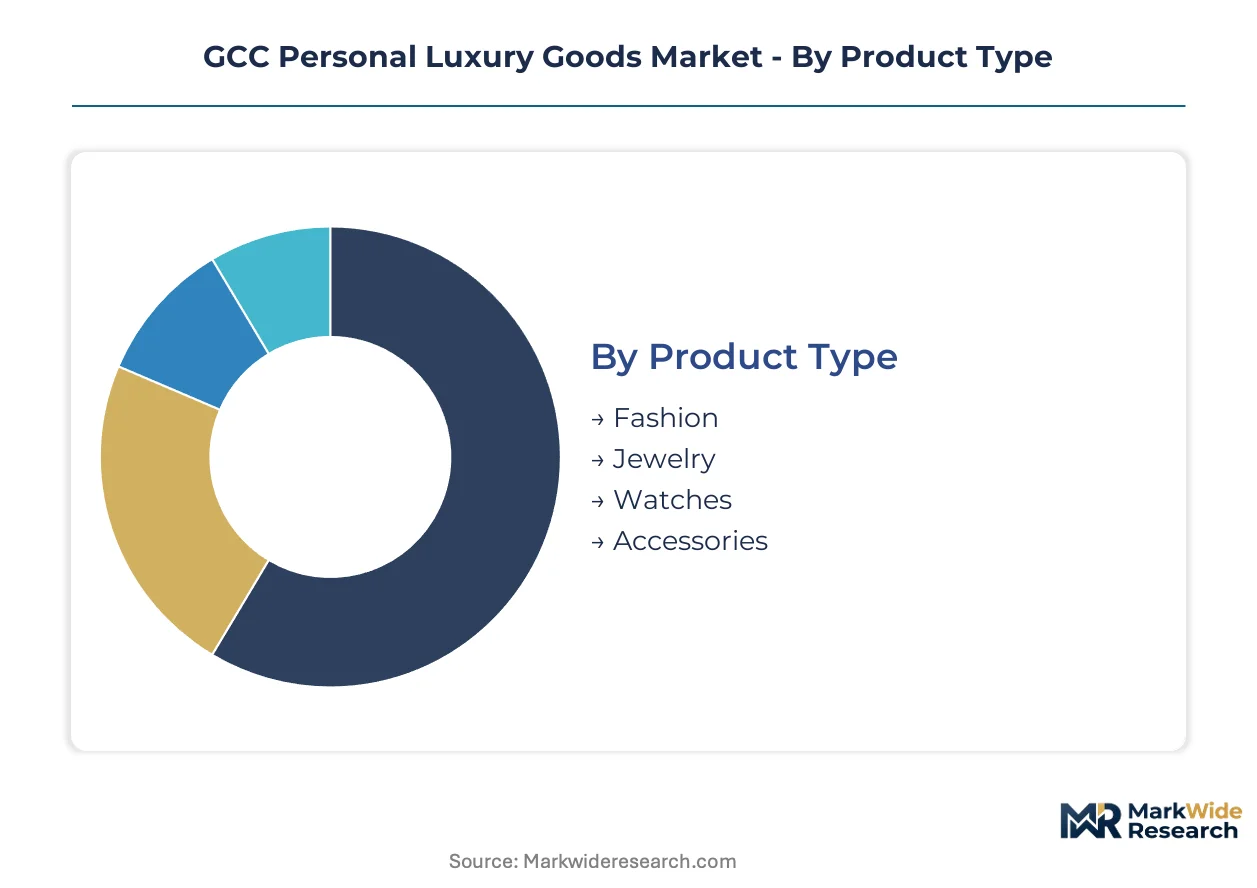
Personal luxury goods in the Gulf Cooperation Council region fragment across four distinct dimensions that shape inventory allocation, marketing spend, and margin capture strategies. Product type and customer type drive the highest-value purchasing decisions, while distribution channel and price tier determine operational architecture and competitive positioning.
Product Type:
Purchase frequency and occasion-based usage patterns determine how buyers navigate across apparel, jewelry, timepieces, and accessories in Dubai Mall and Riyadh Season environments.
- Fashion:Ready-to-wear collections and seasonal runway pieces dominate transaction volume across UAE mall boutiques. Saudi female workforce entry is accelerating professional wardrobe investment as status-signaling requirements intensify.
- Jewelry:High-karat gold and gem-set pieces anchor the highest average transaction values in the GCC. Riyadh's evolving social codes and Dubai's tourist gift economy concentrate demand for statement pieces that bridge heritage craftsmanship with contemporary design.
- Watches:Swiss mechanical timepieces retain collector density in Kuwait City and Manama family office circles.
- Accessories:Leather goods and small leather articles capture impulse purchase behavior at duty-free departure gates.
Volume sits with Fashion; growth tilts toward Jewelry.
Customer Type:
Wealth source and purchase motivation separate transient visitors from established residents and emerging affluent segments across the six GCC states.
- Affluent Consumers:Established Gulf nationals with inherited wealth sustain recurring purchase patterns across seasonal collections. Their brand loyalty and multi-generational relationships with European houses stabilize boutique revenue baselines in Dubai and Riyadh.
- Millennials:Digital-native buyers born between 1981 and 1996 prioritize experience-integrated purchasing and social media visibility. WhatsApp Business API clienteling and private salon access are displacing traditional counter service for this cohort.
- High Net Worth Individuals:Ultra-wealthy collectors with investable assets exceeding $30 million drive bespoke commissioning and limited-edition acquisition.
- Tourists:International visitors leverage VAT refund mechanisms and currency arbitrage to concentrate spending at Dubai Mall and airport duty-free zones.
Revenue concentrates among Affluent Consumers; expansion velocity is steepest among Tourists.
Distribution Channel:
Physical versus digital touchpoint preferences segment buyers by urgency tolerance and service intensity requirements.
- Department Stores:Multi-brand environments like Harvey Nichols and Bloomingdale's Dubai provide discovery access for emerging luxury buyers. These formats absorb higher customer acquisition costs but expose houses to cross-category purchase behavior.
- E-commerce:Brand-operated websites and Farfetch partnerships are capturing share among time-constrained professionals in Kuwait and Bahrain. Saudi Fashion Commission licensing requirements and UAE e-commerce protocols are forcing platform localization investments.
- Boutiques:Flagship and mall-based monobrand stores dominate high-value client retention through personalized service architectures.
- Duty-Free Shops:Airport-based retail captures impulse purchasing from transit passengers at Dubai International and King Khalid International.
Margin capture peaks at Boutiques; digital infrastructure investment is accelerating fastest at E-commerce.
Price Tier:
Accessibility thresholds and perceived exclusivity ratios determine how buyers self-select across entry-level and ultra-premium offerings.
- Premium:Core collections from established houses occupy the $500-$2,500 entry threshold. This tier captures first-time luxury buyers and gift purchasers across Saudi mall developments.
- Super Premium:Haute couture, high jewelry, and complications exceeding $50,000 anchor family office allocation strategies. Dubai's private salon formats and Riyadh's by-appointment services concentrate this tier's distribution.
- Affordable Luxury:Diffusion lines and accessible leather goods bridge mass-market and true luxury positioning.
- Entry-Level Luxury:Cosmetics and small leather goods at sub-$500 price points function as brand entry mechanisms.
Transaction frequency clusters at Premium; absolute margin contribution concentrates at Super Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GCC states consume the vast majority of regional personal luxury goods while producing negligible domestic manufacturing output. European houses dominate supply through Dubai and Riyadh distribution hubs. Regulatory divergence between member states is fragmenting what once operated as a unified Gulf market.
United Arab Emirates
Dubai Mall and Mall of the Emirates anchor tourist spending from Russia, China, and sub-Saharan Africa. MOHAP commercial licensing frameworks mandate Arabic-language labeling and regional quality certification for cosmetics and leather goods. Dubai International Airport duty-free zones capture transit passenger impulse purchases through personalized concierge architectures.
Saudi Arabia
Riyadh Season events and Diriyah Gate developments are pulling high-value client acquisition into experience-integrated formats. Saudi Fashion Commission technical standards and domestic manufacturing credits are forcing houses to establish regional ateliers. Jeddah's Red Sea coastline and Riyadh's financial district concentrate boutique expansion and private salon investment.
Kuwait
Kuwait City's family office density sustains collector-grade timepiece and high jewelry demand. The central bank's wealth management frameworks channel oil-derived liquidity into tangible asset acquisition. The Avenues Mall and Salhiya Complex host the most concentrated ultra-high-net-worth foot traffic outside Dubai.
Qatar
Msheireb Downtown Doha and Place Vendôme mall are repositioning Doha as a secondary luxury hub post-2022 World Cup infrastructure completion. Qatar Central Bank's investment authority backing creates stable commercial lease environments for European houses. The Pearl-Qatar marina district concentrates yacht-accessible retail and hospitality-anchored purchasing itineraries.
Bahrain
Manama's underserved high-net-worth density offers first-mover positioning ahead of mall infrastructure saturation. The central bank's regulatory sandbox for digital payments is enabling WhatsApp Business API clienteling pilots. City Centre Bahrain and Moda Mall anchor the limited existing luxury retail footprint with expansion timelines accelerating through 2026.
GCC Personal Luxury Goods Market Key Industry Players
The competitive structure tilts toward integrated European conglomerates with Gulf-dedicated legal infrastructure and localized compliance teams. LVMH Moët Hennessy Louis Vuitton and Kering anchor the consolidated tier through Dubai Mall flagship dominance and Riyadh Season hospitality partnerships. Three archetypes populate the field: vertically integrated European houses, regional distribution specialists, and independent Italian leather goods and timepiece makers. Geographic expansion through Saudi mall developments and technology licensing for digital authentication represent the dominant competitive vectors.
Within the European conglomerate tier, LVMH Moët Hennessy Louis Vuitton and Kering exemplify integrated retail-hotel partnership models that sustain year-round Gulf foot traffic. Chalhoub Group occupies a position as the dominant regional distribution specialist, leveraging localized merchandising controls across Saudi mall developments. These three anchors sit within a structure where compliance capability and Arabic-language digital infrastructure increasingly separate viable operators from marginal entrants.
| Leading Market Players |
|---|
| Chanel |
| Burberry Group |
| LVMH Moët Hennessy Louis Vuitton |
| Giorgio Armani |
| Prada Group |
| Kering |
| Estée Lauder Companies |
| Chalhoub Group |
| Compagnie Financière Richemont |
| Others |
Cost & Logistics Intelligence
Captive retail-hotel partnerships in Dubai anchor both supply positioning and pricing power for European luxury houses, compressing margin capture into controlled distribution architectures that limit third-party price competition. This vertical integration choice insulates premium tiers from VAT arbitrage pressures while exposing entry-level categories to duty-free discounting.
Pricing Analysis
Margin tightening in the Super Premium tier reflects inventory placement optimization between Riyadh and Dubai as VAT differentials widen. Three-tier pricing structure across Super Premium, Premium, and Entry-Level segments stratifies by exclusivity ratio and concierge service intensity. Cost-down pressure on Entry-Level cosmetics and small leather goods accelerates because duty-free operators extract volume commitments for airport access. Tourists exhibit highest price sensitivity through currency arbitrage behavior, while HNWIs demonstrate lowest sensitivity due to bespoke commissioning preferences.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Fashion Commission and UAE MOHAP force European houses to maintain parallel Arabic-language documentation and quality certification streams. Manufacturing concentrates in Italy, Switzerland, and France for leather goods and mechanical timepieces. Raw material dependencies span Tuscan vegetable-tanned leather, Valenza gold alloys, and Swiss movement components. Single-source vulnerability sits with heritage atelier craftsmanship capacity that cannot scale rapidly. Distribution runs through Dubai Mall flagship anchors, Riyadh Season pop-up infrastructures, and airport duty-free concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boutique-grade real estate scarcity in Dubai and Riyadh props pricing power by constraining competitor entry, creating a supply-constrained market structure that favors incumbents with established mall relationships.
For Market Incumbents: Cement dominance through exclusive hospitality-anchored retail formats that lock in year-round foot traffic ahead of Riyadh Season event saturation. Deepen backward integration into regional atelier establishment to capture Saudi Fashion Commission domestic manufacturing credits. Defend against Chalhoub Group's merchandising control expansion by accelerating private salon investment in Jeddah and Riyadh financial district clusters. For New Entrants and Emerging Players: Saudi Fashion Commission licensing requirements in Riyadh open a window for specialized compliance service providers and regional atelier partnerships. Target Kuwait City and Manama's underserved HNW density ahead of mall infrastructure saturation. Penetrate via WhatsApp Business API concierge platforms that bypass legacy boutique capital requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in regional distribution specialist acquisitions by European houses seeking localized compliance infrastructure. Long-term viability hinges on Arabic-language digital talent and Sharia-compliant payment gateway integration capabilities. Watch Saudi female workforce participation rates as the inflection signal for jewelry and professional leather goods demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Private Salon Format Expansion | Chanel's Riyadh by-appointment model captures HNWI retention through exclusivity architecture. |
| WhatsApp Business API Integration | Hyper-personalized pre-arrival curation displaces traditional counter service for Millennial segments. |
| Regional Atelier Establishment | Saudi Fashion Commission credits incentivize domestic craft workforce development in Riyadh. |
| Blockchain Provenance Pilot | Immutable ownership records compress resale market opacity for Kuwait City family office collectors. |
| Duty-Free Digital Concierge | Dubai International Airport personalized service architectures capture transit passenger impulse purchasing. |
Research Approach
Document review covered regulatory filings from Saudi Fashion Commission and UAE MOHAP, trade customs data, and mall operator lease disclosures, complemented by interviews with regional brand directors, luxury retail leasing managers, and hospitality partnership leads. Primary fieldwork with concierge platform developers and Arabic-language UX specialists validated digital infrastructure investment patterns. Secondary sources included VAT treatment documentation, e-commerce licensing protocols, and European house Gulf market segment reporting. Bottom-up transaction modeling triangulated against top-down macroeconomic consumption projections.
Value outputs across the projection horizon reflect segment-level demand elasticity modeling and inventory placement optimization scenarios. Segmentation dimensions spanned product type, customer archetype, distribution channel, and price tier, with regulatory cluster and tourist origin geography as cross-cutting variables. CAGRs derived from compound growth trajectory analysis against baseline consumption patterns. Forecast inputs incorporated female workforce participation velocity and hospitality-anchored retail format adoption curves.
The model assumes a particular technology adoption path for blockchain provenance verification; alternative pathways for digital authentication standards would alter the outlook for resale market formalization. Forecasts reflect assumptions on Saudi mall development timelines and Dubai tourist recovery trajectories. Deviation in GCC customs harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Secondhand Luxury Goods Market