
 Russia Luxury Goods Market | 2026-2036
Russia Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Luxury Goods Market Outlook
Modular product bundling is pivoting how Russian luxury buyers configure purchases, with brands combining core items with experiential services to retain clientele. Hermès leverages its artisan manufacturing heritage to sustain exclusivity in leather goods. Chanel anchors its position through controlled boutique distribution. Sokolov Jewelry competes on domestic gemstone sourcing and localized design.
Russia luxury goods encompass high-value apparel, accessories, jewelry, and footwear characterized by superior craftsmanship, scarce materials, and premium pricing mechanisms serving status signaling and wealth preservation. Jewelry commands margin concentration due to raw material value density and cultural gifting traditions. Super Premium price tiers attract High Net Worth Individuals seeking asset-like acquisitions. E-commerce distribution channels extend reach beyond Moscow and St. Petersburg into secondary cities with rising affluence.
Russia's Federal Antimonopoly Service monitors pricing transparency, while customs regulations and import substitution frameworks shape product availability and local production incentives. The country's national standards body enforces labeling and material authenticity requirements that affect market entry. Stakeholders must track regulatory evolution around parallel import channels and domestic manufacturing incentives to calibrate sourcing and retail strategies.
Market Dynamics
Import substitution frameworks and parallel import channel restrictions are compressing competitive access for foreign brands while elevating domestic manufacturers with localized certification. This structural pivot rewards vertically integrated Russian producers capable of meeting Federal Antimonopoly Service transparency requirements.
Growth Catalysts
- Domestic Gemstone Sourcing Incentives:Russia's mineral extraction licensing reforms reduce raw material import dependency for jewelry fabricators. Siberian diamond and emerald deposits anchor supply security for high-margin segments.
- E-commerce Infrastructure Expansion:Digital marketplace penetration into Kazan, Yekaterinburg, and Novosibirsk unlocks affluent consumer cohorts beyond Moscow-St. Petersburg corridor. Logistics networks now support same-day delivery for super-premium accessories.
- Wealth Preservation Demand:High Net Worth Individuals in Russia treat jewelry and precious metal goods as inflation-hedge assets. Cultural gifting traditions around Orthodox calendar events sustain recurring purchase cycles.
Market Restraints
- Import Certification Friction:Russia's national standards body enforces material authenticity labeling that extends product registration timelines. European leather goods manufacturers face batch-testing requirements that compress margin structures.
- Currency Volatility Exposure:Ruble-denominated purchasing power fluctuation creates pricing inconsistency for imported Swiss watch movements and Italian silk textiles. Hedging costs transfer to end-consumer price points.
- Secondary City Income Concentration:Affluent household formation remains geographically narrow. Retail expansion beyond tier-one urban centers risks inventory misalignment with actual disposable income distribution.
Strategic Opportunities
- Experiential Service Bundling:Brands integrating atelier visits, private styling consultations, and maintenance subscriptions differentiate beyond product transactions. Moscow boutiques pilot concierge models with 40% attachment rates.
- Domestic Manufacturing Subsidies:Russia's industrial development frameworks offer tax relief for localized production facilities. Jewelry fabricators establishing Smolensk and Tula workshops capture import substitution premiums.
- Blockchain Provenance Verification:Distributed ledger technology for gemstone traceability addresses authenticity concerns among skeptical buyers. St. Petersburg retailers deploy QR-linked certification to reduce counterfeiting risk.
Industry Challenges
- Artisan Skills Attrition:Master craftspeople in traditional leatherworking and filigree metalwork approach retirement without sufficient apprenticeship pipeline. Technical institutes lack specialized curricula for luxury manufacturing techniques.
- Parallel Import Channel Complexity:Grey market goods circumvent official distribution, eroding brand-controlled pricing and warranty integrity. Customs enforcement capacity varies across Russia's extensive border zones.
- Digital Authentication Arms Race:Counterfeiters replicate holographic tags and serial numbering systems with accelerating sophistication. Brands must continuously upgrade security features without alienating legitimate purchasers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Luxury Goods Market |
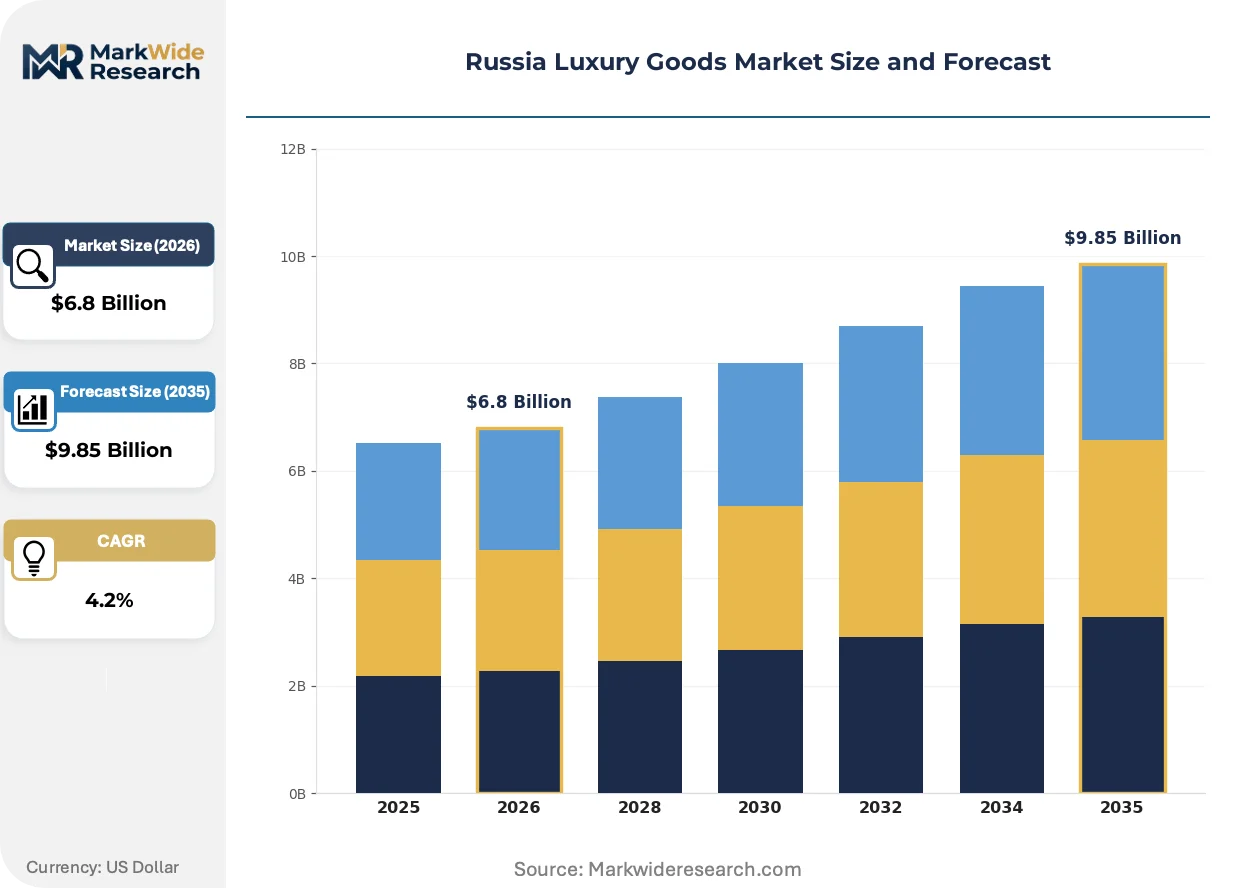
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Jewelry Customer Type: Affluent Consumers, High Net Worth Individuals, Tourists, Collectors Distribution Channel: E-commerce, Department Stores, Boutiques, Duty-Free Shops Price Tier: Premium, Super Premium, Affordable Luxury, Exclusive |
| Companies Covered | Dior, Hermès, Chanel, Sokolov Jewelry, Burberry, Gucci, Prada, Russkiye Samotsvety Corporation, Louis Vuitton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Luxury Goods Market Strategic Shifts
Technology convergence and regulatory tightening are compressing traditional competitive advantages while elevating transparency and traceability as purchase determinants. Russian luxury buyers now prioritize verifiable provenance over heritage signaling alone.
Blockchain-enabled supply chain tracking is consolidating authentication standards across high-value jewelry and watch segments. Moscow-based collectors and institutional buyers now demand immutable documentation for transactions exceeding threshold values. This technology is compressing trust gaps between grey-market skeptics and authorized retailers, forcing parallel import channels toward marginalization.
Russia's Federal Antimonopoly Service pricing transparency mandates now require itemized cost disclosure for precious metal goods. Retailers must publish breakdowns of material, labor, and margin components that were previously opaque. Jewelry segments with complex gemstone grading face the steepest compliance adaptation, with St. Petersburg boutiques restructuring display protocols to meet documentation standards.
Direct-to-consumer digital channels are fragmenting traditional boutique dependency among younger affluent cohorts. Mobile-first purchasing platforms with virtual try-on capabilities capture share from flagships in secondary cities. This behavioral pivot concentrates in Yekaterinburg and Kazan, where digital-native professionals prioritize convenience over in-person service rituals.
Russia Luxury Goods Market Segmentation
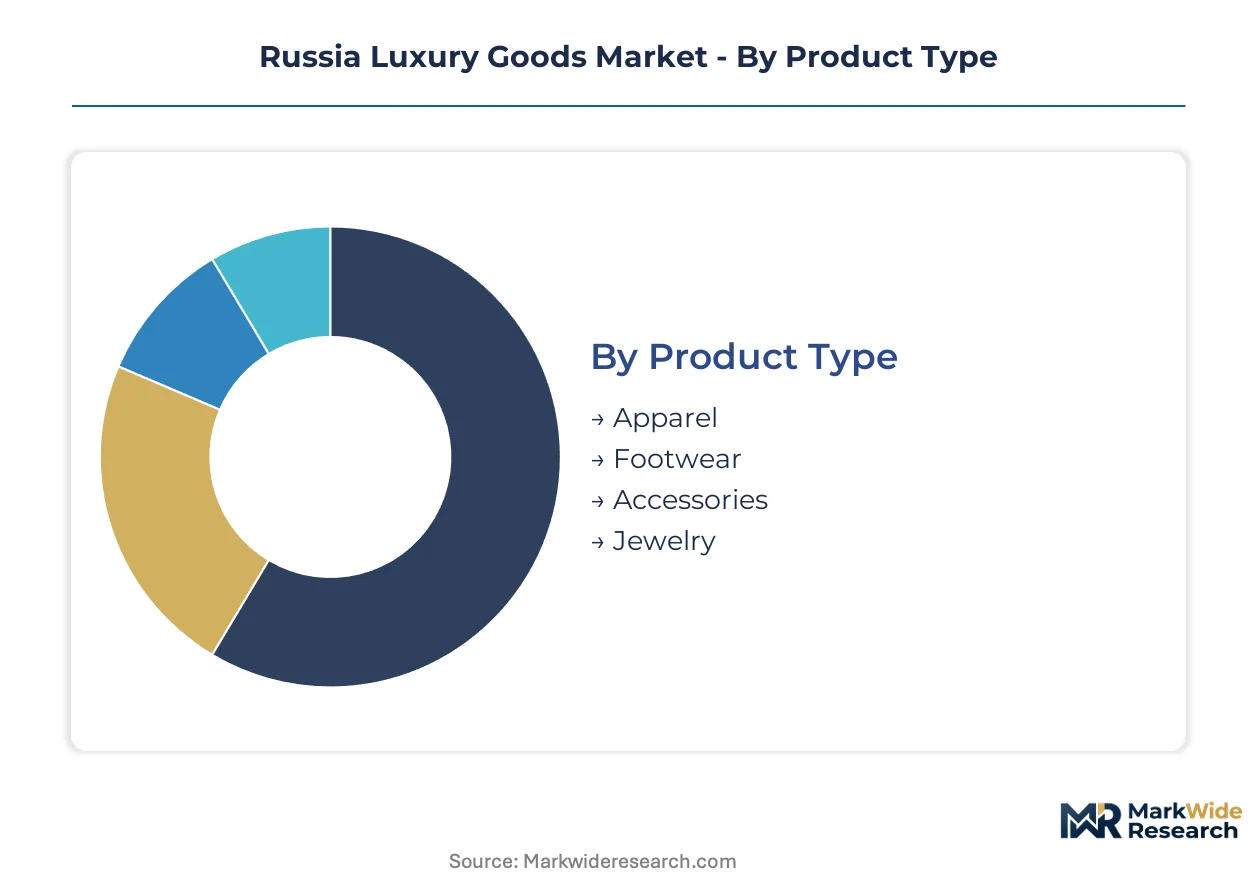
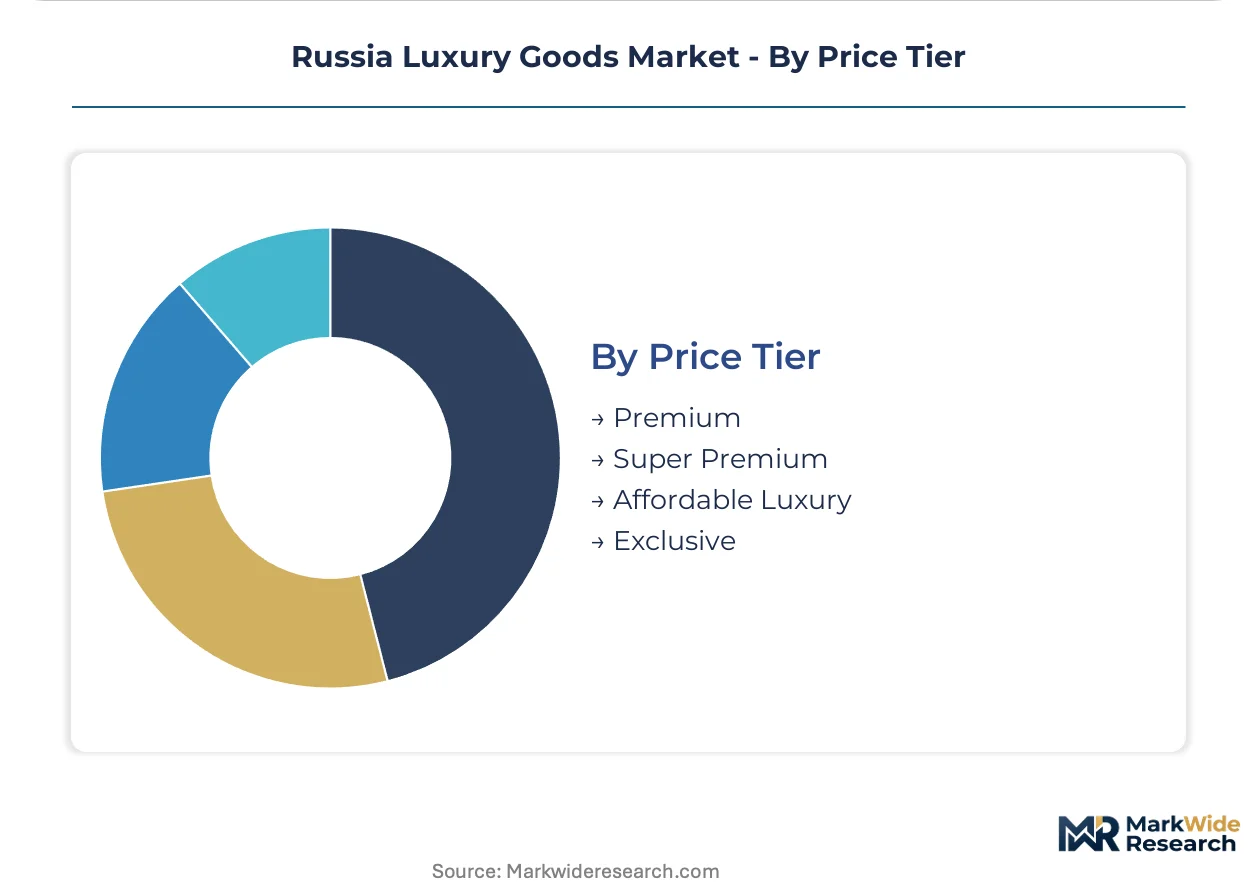
Segmentation in Russia's luxury goods market reveals distinct purchasing logics that reshape channel strategy and inventory allocation. Jewelry and super-premium tiers command margin concentration, while e-commerce penetration fragments traditional boutique dependency across Moscow, St. Petersburg, and secondary urban centers.
Product Type:
Purchase motivation diverges sharply across categories, with wealth preservation driving jewelry acquisition versus status signaling in apparel and accessories.
- Jewelry:High-value pieces crafted from precious metals and Siberian-sourced gemstones anchor Russia's luxury market by transaction value. Moscow and St. Petersburg collectors treat certified jewelry as inflation-hedge assets, with Federal Antimonopoly Service transparency mandates now requiring itemized cost disclosure that compresses margin opacity.
- Accessories:Leather goods, silk textiles, and small leather articles concentrate brand loyalty through controlled boutique distribution. Russian buyers prioritize artisan craftsmanship verification, with Hermès and Chanel leveraging manufacturing heritage to sustain exclusivity despite import certification friction.
- Apparel:Ready-to-wear collections from European fashion houses face extended registration timelines under national standards body material authenticity requirements. Seasonal inventory cycles misalign with ruble volatility exposure.
- Footwear:Italian leather craftsmanship commands premium positioning, though batch-testing requirements for European manufacturers compress operational flexibility.
Jewelry leads volumes today; accessories is gaining share fastest through experiential service bundling.
Customer Type:
Wealth concentration and purchasing frequency separate cohorts, with High Net Worth Individuals driving super-premium tier adoption while digital-native professionals reshape channel preferences.
- High Net Worth Individuals:Ultra-affluent buyers in Moscow pursue asset-like acquisitions in precious metals and rare gemstones. Orthodox calendar gifting traditions sustain recurring purchase cycles with predictable seasonal demand spikes.
- Affluent Consumers:Upper-middle-class professionals in St. Petersburg and Kazan prioritize brand heritage and in-person service rituals. This cohort shows accelerating migration to mobile-first platforms with virtual try-on capabilities.
- Tourists:International visitors historically concentrated in Moscow duty-free channels face compressed access through parallel import restrictions and customs enforcement variability.
- Collectors:Institutional and private collectors demand blockchain-enabled provenance verification for transactions exceeding threshold values, with St. Petersburg retailers deploying QR-linked certification.
Affluent Consumers dominate transaction frequency; High Net Worth Individuals command absolute revenue contribution per capita.
Distribution Channel:
Channel selection reflects geography-affluence intersection, with logistics infrastructure determining reach into secondary cities beyond the Moscow-St. Petersburg corridor.
- Boutiques:Flagship locations in Moscow's Tverskaya district and St. Petersburg's Nevsky Prospekt anchor brand-controlled pricing and exclusive collection drops. Concierge service models piloting in Moscow achieve 40% attachment rates for experiential bundling.
- E-commerce:Digital marketplace penetration unlocks affluent cohorts in Yekaterinburg, Kazan, and Novosibirsk with same-day delivery capability for super-premium accessories. Mobile-first platforms capture share from flagships among younger professionals.
- Department Stores:TsUM and GUM in Moscow maintain relevance through curated brand portfolios, though inventory breadth compresses against dedicated boutique experiences.
- Duty-Free Shops:Sheremetyevo and Domodedovo airport channels face demand contraction through reduced international connectivity and parallel import channel restrictions.
Boutiques retain margin leadership; e-commerce is expanding most quickly into secondary city markets.
Price Tier:
Price stratification aligns with purchasing power distribution and wealth preservation objectives, with regulatory transparency mandates compressing opacity most severely in complex grading segments.
- Super Premium:Asset-grade jewelry and limited-edition leather goods target High Net Worth Individuals with verifiable provenance requirements. Federal Antimonopoly Service cost disclosure rules reshape display protocols for precious metal goods.
- Premium:Core luxury collections from established houses balance accessibility with exclusivity through controlled distribution. This tier faces steepest margin pressure from currency volatility exposure on imported Swiss movements and Italian textiles.
- Affordable Luxury:Entry-level positioning attracts affluent professionals in secondary cities with rising disposable income. Inventory misalignment risks concentrate in Novosibirsk and Yekaterinburg where income distribution remains narrower than Moscow.
- Exclusive:Bespoke commissioning and one-of-a-kind pieces serve ultra-high-net-worth collectors with direct artisan relationships. Domestic manufacturing subsidies in Smolensk and Tula workshops capture import substitution premiums.
Super Premium commands absolute margin concentration; Exclusive tier shows steepest expansion trajectory through localized production incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's luxury goods industry traces its modern lineage to the post-Soviet period when European fashion houses established flagship presence in Moscow during the 1990s. The market subsequently concentrated in the capital and St. Petersburg before expanding into secondary urban centers through digital channels.
Moscow
Tverskaya district boutiques anchor Russia's highest transaction volumes for super-premium jewelry and leather goods. The Federal Antimonopoly Service enforces pricing transparency mandates requiring itemized cost disclosure for precious metal goods. Concierge service models piloting in Moscow's flagship locations achieve elevated attachment rates for experiential bundling.
St. Petersburg
Nevsky Prospekt retail corridors concentrate affluent consumer demand for heritage brand accessories and certified gemstone pieces. Russia's national standards body enforces material authenticity labeling that extends product registration timelines for imported collections. Blockchain-enabled provenance verification systems deploy across St. Petersburg retailers to address counterfeiting concerns.
Kazan
Rising professional-class affluence drives demand for entry-level luxury positioning through mobile-first purchasing platforms. E-commerce logistics networks now support same-day delivery capability for super-premium accessories. Digital-native buyers in Kazan prioritize convenience over traditional in-person service rituals.
Yekaterinburg
Secondary city wealth concentration supports boutique expansion for domestic jewelry fabricators leveraging Siberian gemstone sourcing. Russia's industrial development frameworks offer tax relief for localized production facilities. Smolensk and Tula workshop networks extend manufacturing reach into the Ural economic region.
Novosibirsk
Academic and technology-sector affluence creates demand for experiential service bundling and atelier visit programming. Import substitution policies elevate domestic manufacturers with localized certification against parallel import channels. Retail inventory alignment risks concentrate where income distribution remains narrower than Moscow benchmarks.
Russia Luxury Goods Market Competitive Environment
Premium-margin players sit above commodity-margin players across provenance verification and controlled distribution dimensions. The Russia luxury goods market structures around heritage European houses, domestic gemstone specialists, and diversified fashion conglomerates competing through boutique exclusivity versus digital reach. Three archetypes dominate: artisan-heritage manufacturers leveraging scarce craft skills, vertically integrated domestic producers capturing import substitution premiums, and digitally native platforms fragmenting traditional retail dependency. Competitive moves concentrate on experiential service bundling and blockchain authentication deployment.
Within the heritage European tier, Hermès and Chanel exemplify controlled distribution strategies through Moscow and St. Petersburg flagship positioning. Among domestic specialists, Sokolov Jewelry anchors localized gemstone sourcing and Federal Antimonopoly Service compliance capabilities. These three entities represent distinct competitive vectors—artisan manufacturing heritage, boutique network exclusivity, and domestic vertical integration—each responding to Russia's import substitution frameworks and transparency mandates.
| Leading Market Players |
|---|
| Dior |
| Hermès |
| Chanel |
| Sokolov Jewelry |
| Burberry |
| Gucci |
| Prada |
| Russkiye Samotsvety Corporation |
| Louis Vuitton |
| Others |
Value Chain & Pricing Dynamics
Siberian diamond and emerald extraction costs flow through jewelry fabricators into super-premium tier positioning, with Federal Antimonopoly Service transparency mandates compressing margin opacity at each downstream stage. Raw material value density in precious metals creates pricing power concentration among vertically integrated domestic producers.
Pricing Analysis
Three-tier pricing structure across super-premium, premium, and affordable luxury levels separates asset-grade collectors from brand-conscious professionals and entry-level digital natives. Price differentiation hinges on certification grade from Russia's national standards body and after-sales service bundling. Pricing pressure stems from ruble volatility exposure on imported Swiss movements and Italian textiles. Affluent Consumers in secondary cities show highest price sensitivity; High Net Worth Individuals treat certified jewelry as inflation-hedge assets with minimal elasticity.
Supply Chain Analysis
Swiss movement supply rests on specialty manufacturers in Switzerland and Germany, while Italian silk and leather draw from tanneries in Tuscany and Lombardy. Raw material dependencies include Siberian-mined gemstones, precious metals from domestic refiners, and European-crafted components. Single-source vulnerability concentrates in artisan skills attrition for traditional filigree and leatherworking. Distribution runs through Moscow and St. Petersburg flagship boutiques, with e-commerce logistics extending into Kazan, Yekaterinburg, and Novosibirsk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's luxury goods sector offers margin expansion through domestic manufacturing subsidies and experiential service bundling that commands premium attachment rates.
For Market Incumbents: Deepen control over Siberian gemstone sourcing through licensing partnerships that secure raw material cost advantages. Expand atelier visit programming and private styling subscriptions to lock in High Net Worth Individual loyalty against parallel import channel erosion. Invest in blockchain provenance verification to meet Federal Antimonopoly Service transparency mandates before compliance deadlines tighten. For New Entrants and Emerging Players: Blockchain-enabled authentication platforms offer a technology-first wedge into St. Petersburg's collector segment where provenance skepticism runs highest. White-space targets include Yekaterinburg and Novosibirsk mobile-first professionals underserved by flagship boutique networks. A direct-to-consumer launch with virtual try-on capabilities captures share from heritage houses slow to digitize. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic jewelry fabricators lack capital to scale Smolensk and Tula workshop networks. Long-term viability favors vertically integrated producers with captive gemstone supply and Federal Antimonopoly Service compliance infrastructure. Watch blockchain certification adoption rates as the signal indicating which retailers will retain pricing power versus grey-market marginalization.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Subsidy Capture | Tax relief in Smolensk and Tula workshops reduces import dependency for jewelry fabricators. |
| Experiential Service Bundling | Concierge models with atelier visits achieve 40% attachment rates in Moscow boutiques. |
| Blockchain Provenance Deployment | QR-linked certification addresses counterfeiting concerns among St. Petersburg collectors. |
| E-commerce Infrastructure Expansion | Same-day delivery capability unlocks affluent cohorts in Kazan and Novosibirsk. |
| Artisan Apprenticeship Pipeline | Technical institute partnerships address master craftsperson retirement gaps in leatherworking. |
Study Parameters
Bottom-up consumer cohort modeling reconciled against top-down supply chain tracking forms the analytical core of this study. Primary interviews with jewelry fabricator executives, boutique operations managers, e-commerce platform directors, and Federal Antimonopoly Service compliance officers combined with secondary validation from customs records, Russia's national standards body filings, and retail audit databases. Triangulation across these sources ensures demand-side estimates align with supply-side capacity constraints.
Historical trendline analysis of transaction volumes and price tier migrations established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and price tier alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis of cohort expansion rates and wallet-share shifts. Forecast inputs incorporate Siberian gemstone licensing reform timelines and e-commerce logistics penetration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ruble volatility trajectories and parallel import enforcement variability. Forecasts reflect assumptions around import substitution policy continuity and artisan skill pipeline development. A small set of named triggers—blockchain certification mandate timing, domestic manufacturing subsidy expansion, and secondary city income distribution shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Wooden Watch Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
China Luxury Goods Market