
 Italy Luxury Goods Market | 2026-2036
Italy Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Luxury Goods Market Outlook
Subscription-based styling and maintenance services is rebalancing how Italian houses monetize client relationships beyond single transactions. Prada SpA leverages its Miu Miu diffusion line to capture younger demographics through digital-native membership programs. Giorgio Armani SpA anchors its Milan-centric retail footprint with made-to-measure atelier services that resist e-commerce commoditization. Luxottica Group SpA dominates eyewear distribution through controlled optician networks and licensed boutique placements.
Italy luxury goods encompass high-value fashion apparel, leather accessories, precision timepieces, and fine jewelry distinguished by artisanal construction, heritage design codes, and region-specific manufacturing techniques such as Florentine goldsmithing and Vicenza jewelry casting. These products serve status signaling, wealth preservation, and personal identity expression for ultra-high-net-worth individuals and cultural tourists. Fashion apparel and handbags together occupy the deepest margin pools, buoyed by leatherworking traditions in Tuscany that command material premiums. Watches compete with Swiss counterparts through limited-edition mechanical complications from Milan-based ateliers. Jewelry segments sustain collector demand via Verona and Valenza gold districts where hand-finished settings differentiate mass-market alternatives.
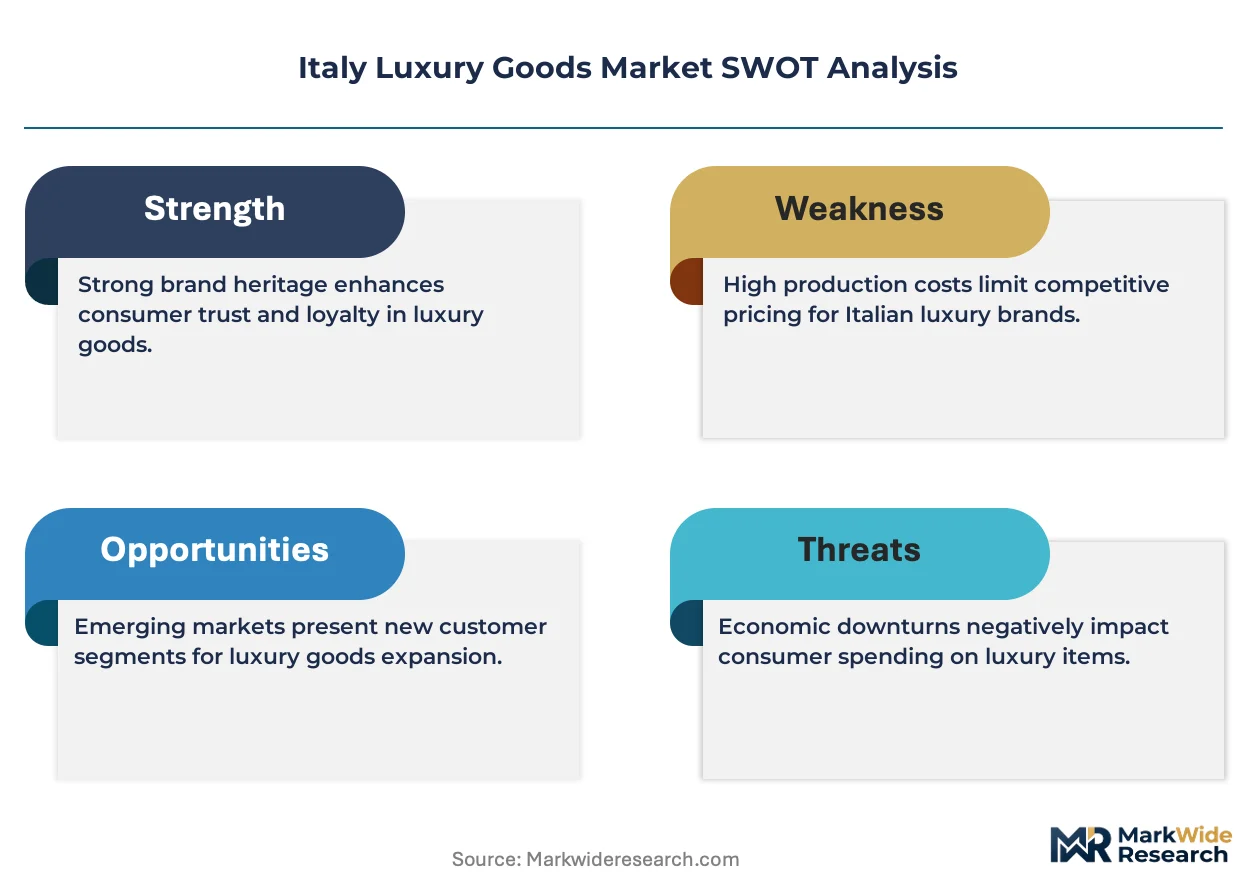
EU Green Deal sourcing mandates and the CSRD reporting framework compel Italian luxury houses to document supply chain emissions and leather tanning chemistry, tightening market access for non-compliant suppliers. Italy's national implementation of REACH chemical standards through ISPRA oversight further restricts chrome-based processing in Solofra and Santa Croce tanneries. Stakeholders must weigh capital allocation between heritage artisan preservation and automated traceability infrastructure that regulators will enforce without grandfathering traditional methods.
Market Dynamics
EU Green Deal mandates and digital product passport requirements are forcing Italian luxury houses to rebuild supply chain transparency from raw hide to finished leather goods, compressing margins for artisan tanneries in Solofra and Santa Croce while advantaging early adopters with capital for traceability infrastructure.
Growth Catalysts
- CSRD Reporting Framework:Mandatory emissions disclosure across the European Union is accelerating investment in low-impact vegetable tanning processes among Tuscany leather clusters.
- Asia-Pacific Cultural Tourism:Affluent visitors from China, South Korea, and Japan are driving experiential retail adoption across Milan, Florence, and Rome flagship locations.
- Blockchain Traceability Protocols:Distributed ledger verification of Vicenza goldsmithing provenance is electrifying collector demand for authenticated heritage pieces.
Market Restraints
- Chrome Tanning Chemistry Restrictions:ISPRA enforcement of REACH standards is eliminating traditional wet-blue processing for smaller Solofra tanneries lacking wastewater treatment capital.
- Raw Hide Supply Concentration:European cattle herd contraction and Brazilian hide export taxes are compressing input availability for Lombardy leatherworking belts.
- Swiss Mechanical Watch Competition:Geneva and Biel-based ateliers dominate high-complication collector markets, limiting Milan watchmaker pricing power above fifteen-thousand-euro entry points.
Strategic Opportunities
- Sicily and Apulia Manufacturing Expansion:Underutilized artisan capacity in Catania gold districts and Bari textile corridors offers cost-advantaged production for diffusion lines.
- Subscription-Based Styling Services:Digital-native membership programs for wardrobe curation and maintenance are creating recurring revenue streams beyond single-transaction luxury purchases.
- EU Digital Product Passport Mandate:Early compliance with 2030 traceability deadlines positions heritage houses to capture premium positioning as regulatory barriers exclude non-compliant competitors.
Industry Challenges
- Maestro Artisan Succession Crisis:Florentine goldsmithing and Valenza jewelry casting face generational knowledge transfer gaps as aging master craftspeople retire without trained successors.
- Legacy ERP Integration Friction:Family-owned manufacturers in Tuscany and Lombardy struggle to embed automated carbon accounting into decades-old inventory management systems ahead of CSRD deadlines.
- Dual Certification Burden:Simultaneous compliance with ISO 14064 carbon verification and EU Ecolabel standards strains quality assurance resources across mid-sized leather goods producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Luxury Goods Market |
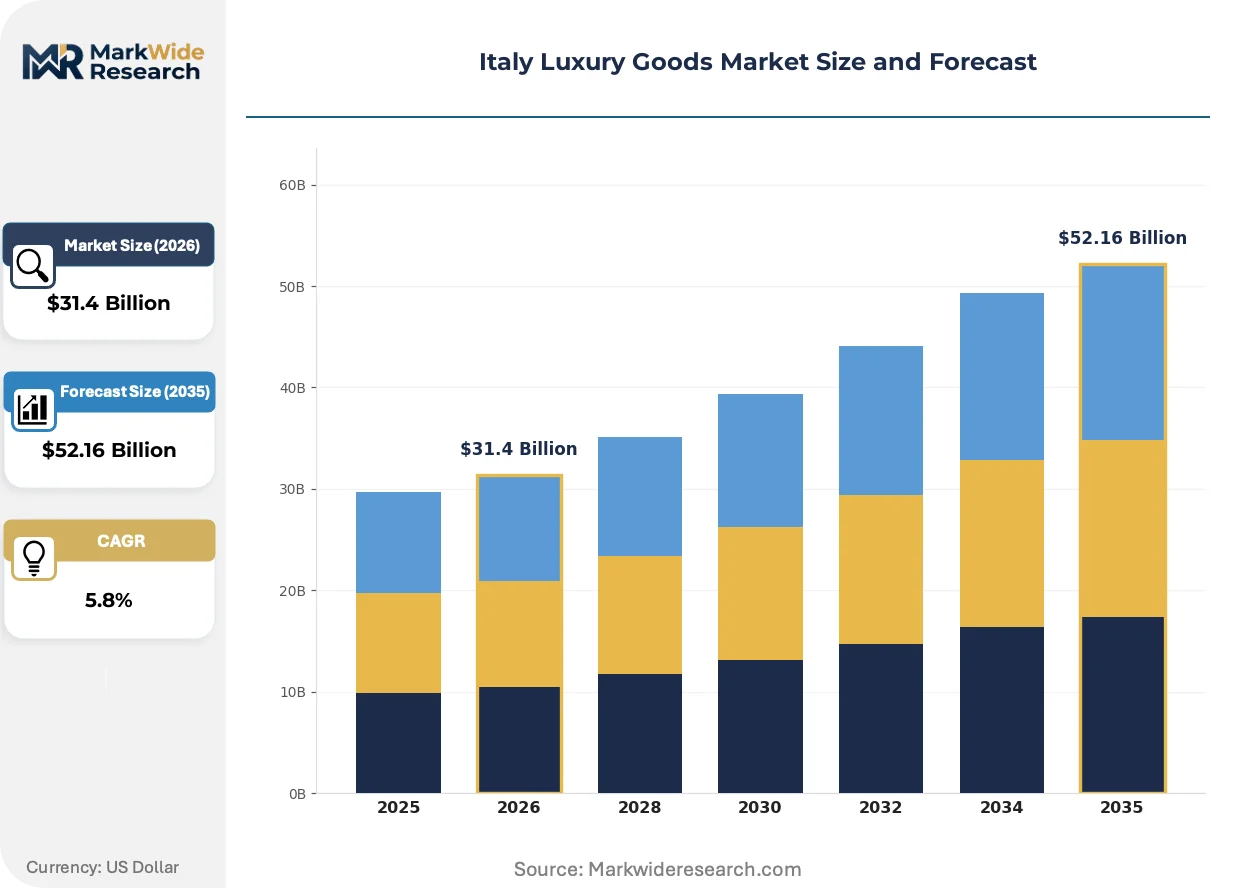
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watches, Fashion Apparel, Handbags, Jewelry Customer Type: Affluent Consumers, Tourists, Collectors, Retailers Distribution Channel: Exclusive Boutiques, Department Stores, Online Platforms, Duty-Free Shops Brand Positioning: High-End, Premium, Designer, Artisan |
| Companies Covered | Prada SpA, Giorgio Armani SpA, Moncler SpA, Luxottica Group SpA, Ermenegildo Zegna, Dolce & Gabbana S.r.l., OTB Group, Salvatore Ferragamo SpA, Tod's SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Luxury Goods Market Strategic Shifts
Italian luxury is undergoing a technological and regulatory transformation that redefines how heritage craftsmanship interfaces with digital verification and experiential commerce. Three forces are compressing traditional business models while opening new margin pools.
Near-field communication chips embedded in leather goods and jewelry are electrifying authentication workflows for secondary market resale and insurance valuation. Collector buyers in Asia-Pacific and Middle Eastern markets now expect tap-to-verify provenance as standard for pieces above entry-luxury price thresholds. This capability is compressing traditional certificate-of-authenticity paper trails while enabling fractional ownership platforms for ultra-high-net-worth asset portfolios.
The EU Green Deal's deforestation-free supply chain regulation is eliminating uncertified leather sourcing from Brazilian and Argentinian ranches by 2025. Italian tanneries in Tuscany and Veneto are responding by backward integration into traceable European hide procurement and vegetable tanning chemistry. This regulatory compression favors capital-rich houses capable of absorbing three-to-five-year payback periods on new wastewater and emissions infrastructure.
Cultural tourists from China and South Korea are displacing traditional wholesale distribution with direct experiential purchases in Milan, Florence, and Rome flagship locations. These buyers prioritize atelier visits, made-to-measure appointments, and limited-edition drops unavailable through domestic retail partners. This channel rotation is forcing heritage houses to rebalance capital allocation from Asian joint ventures toward domestic flagship experiential investments.
Italy Luxury Goods Market Segmentation
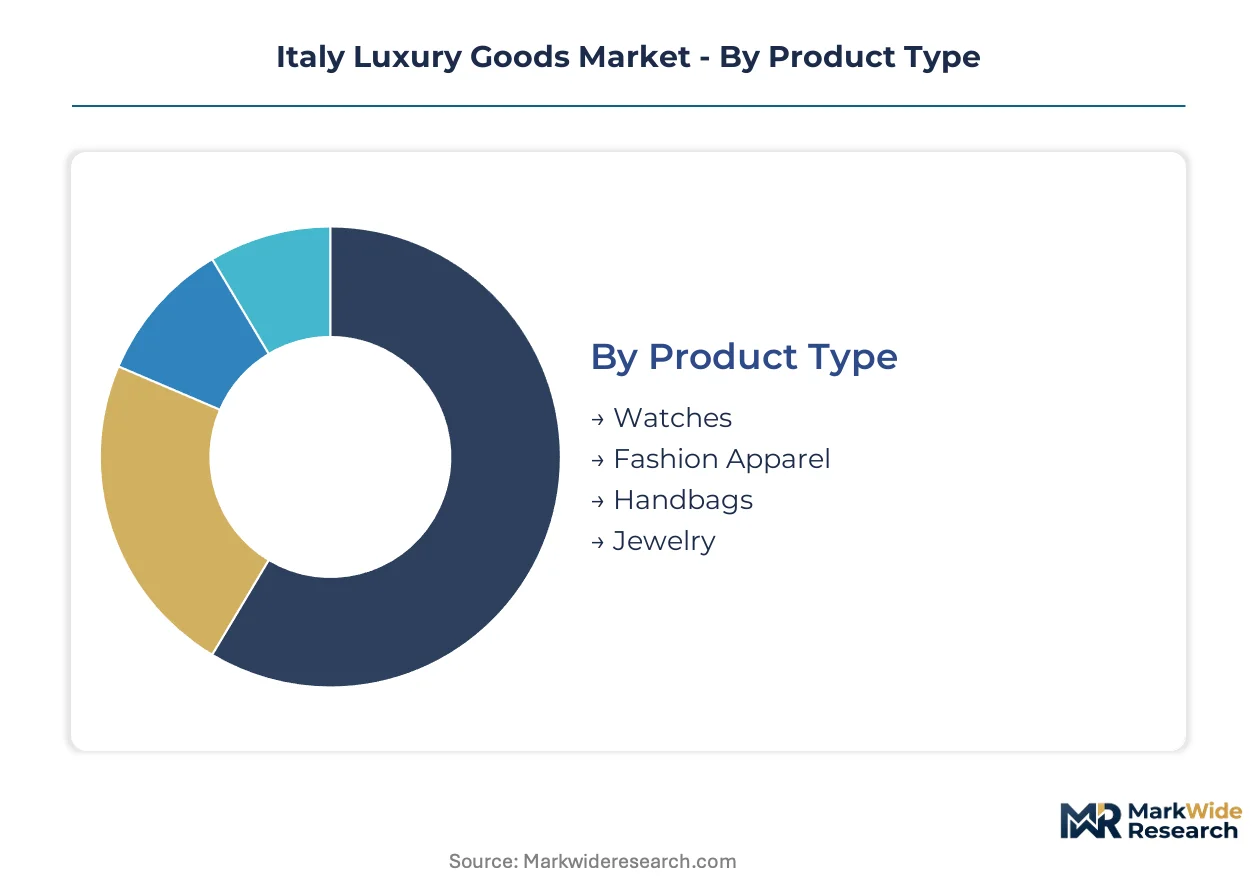
Italian luxury goods segmentation reveals how artisanal heritage, distribution control, and customer proximity interact to determine margin capture. Distinct technical specifications and channel strategies separate heritage houses from diffusion competitors across Tuscany and Lombardy production belts.
Product Type:
Material composition and manufacturing technique define performance benchmarks across Florentine leatherworking and Milanese metalcraft traditions.
- Fashion Apparel:Made-to-measure suiting and ready-to-wear collections from Lombardy ateliers dominate revenue pools. Milan flagship locations capture affluent Asian tourists seeking experiential purchases unavailable through wholesale partners.
- Handbags:Vegetable-tanned leather construction from Santa Croce tanneries commands material premiums. Tuscany production belts face CSRD compliance pressure to document emissions from raw hide through finished goods.
- Watches:Mechanical complications from Milan-based ateliers compete with Swiss counterparts through limited-edition releases.
- Jewelry:Hand-finished gold settings from Valenza and Vicenza districts sustain collector demand via provenance authentication.
Fashion apparel leads on scale; handbags lead on momentum.
Customer Type:
Purchase behavior and asset-holding patterns separate recurring revenue opportunities from single-transaction volume.
- Affluent Consumers:Ultra-high-net-worth individuals from China and South Korea drive domestic flagship traffic. Subscription-based styling services are rebalancing monetization beyond individual purchases.
- Tourists:Cultural visitors prioritize atelier visits and limited-edition drops over standardized retail inventory. Experiential retail investments in Rome and Florence concentrate on this segment.
- Collectors:Blockchain-verified provenance electrifies secondary market demand for authenticated heritage pieces.
- Retailers:Controlled optician networks and licensed boutique placements dominate eyewear distribution.
Affluent consumers anchor volume concentration; tourists are expanding most quickly.
Distribution Channel:
Channel selection determines margin retention and customer data ownership for heritage houses.
- Exclusive Boutiques:Flagship locations in Milan, Florence, and Rome capture direct experiential purchases. Capital allocation is shifting from Asian joint ventures toward domestic flagship investments.
- Online Platforms:Digital-native membership programs enable recurring revenue through wardrobe curation services.
- Department Stores:Wholesale partnerships face compression as tourists prefer direct flagship access.
- Duty-Free Shops:Airport retail captures transient high-value purchases with reduced experiential component.
Exclusive boutiques lead on scale; online platforms lead on momentum.
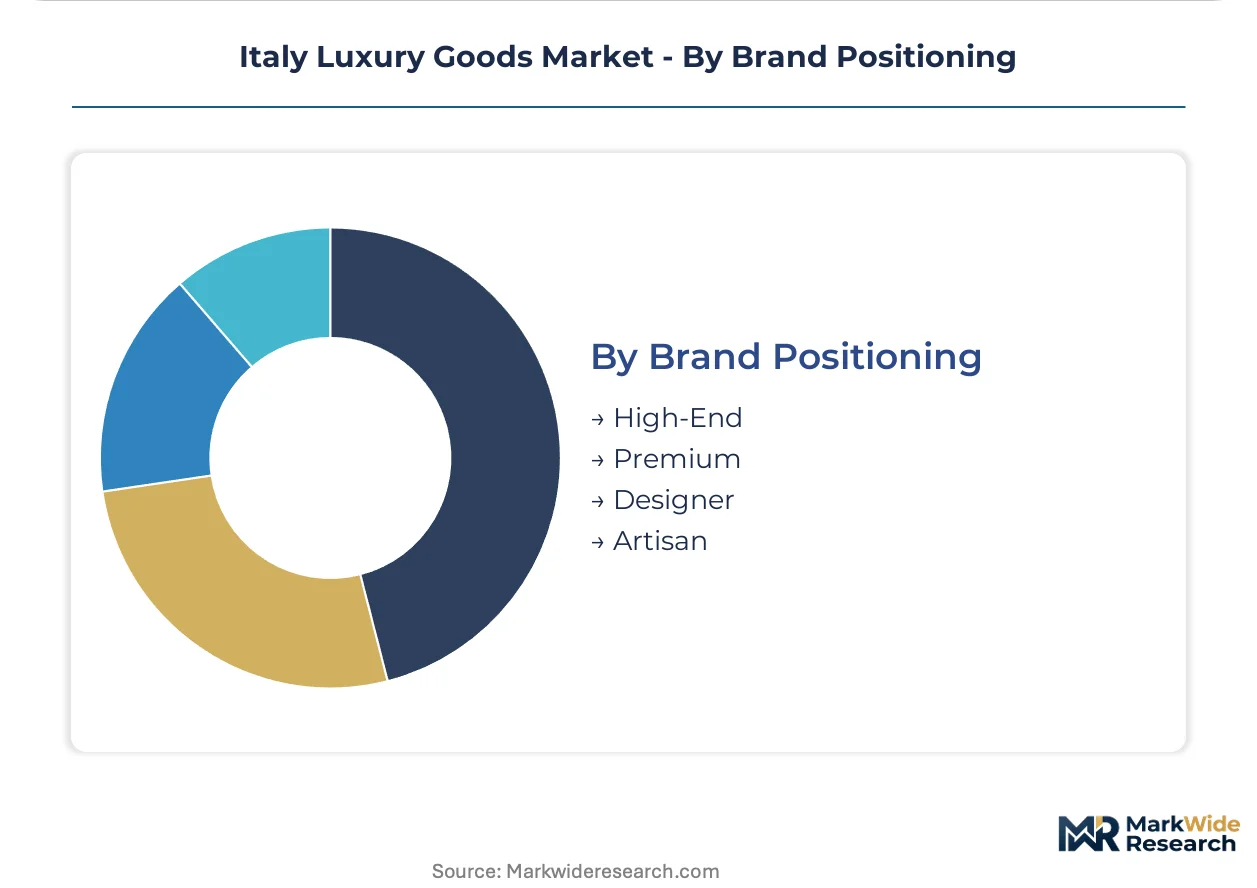
Brand Positioning:
Price architecture and production methodology separate accessible diffusion lines from unattainable heritage positioning.
- High-End:Limited mechanical complications and bespoke goldsmithing serve wealth preservation functions. Collector buyers expect NFC-enabled provenance verification as standard.
- Premium:Diffusion lines capture younger demographics through digital-native engagement without full atelier investment.
- Designer:Named creative direction commands editorial placement and cultural relevance.
- Artisan:Master craftsperson attribution sustains pricing power amid generational succession gaps in Florentine workshops.
High-End leads on scale; Premium leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing luxury manufacturing capacity toward regions where EU Green Deal compliance costs remain manageable. Italian houses now balance heritage cluster preservation against emerging production belts offering lower traceability infrastructure burdens.
Lombardy
Milan flagship density attracts affluent Asian tourists seeking experiential atelier services unavailable through wholesale channels. ISPRA enforcement of REACH standards pressures Santa Croce tanneries to eliminate chrome-based processing. The Lombardy leatherworking belt concentrates made-to-measure suiting and precision mechanical watch assembly.
Tuscany
Vegetable-tanned leather construction from Florence and Scandicci commands material premiums among heritage handbag collectors. CSRD reporting deadlines compel Tuscan clusters to document emissions across raw-hide-to-finished-goods chains. The Santa Croce tannery district faces capital flight toward compliant producers with wastewater treatment infrastructure.
Veneto
Vicenza goldsmithing and Valenza jewelry casting sustain collector demand through hand-finished settings and blockchain-verified provenance. EU deforestation-free supply chain regulations eliminate uncertified Brazilian hide sourcing by 2025. The Vicenza gold district anchors limited-edition mechanical complications competing with Swiss ateliers.
Sicily
Catania gold districts offer underutilized artisan capacity for diffusion line production at cost-advantaged rates. National implementation of EU Green Deal mandates through ISPRA oversight restricts traditional wet-blue processing. Sicilian manufacturing corridors attract capital from heritage houses seeking lower compliance burdens than Lombardy or Tuscany.
Lazio
Rome flagship locations capture cultural tourist spending through experiential retail investments and limited-edition drops. The EU Digital Product Passport mandate positions early-compliant houses to capture premium positioning ahead of 2030 deadlines. Roman retail clusters concentrate subscription-based styling services for recurring revenue generation.
Italy Luxury Goods Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heritage houses controlling distribution through exclusive boutiques while OEM suppliers capture volume in diffusion line production. The vendor base concentrates around family-owned manufacturers with generational craft expertise and capital-rich conglomerates with traceability infrastructure investment capacity. Three archetypes dominate: vertically integrated heritage houses, private-equity-backed portfolio aggregators, and specialist component suppliers. Competitive moves center on M&A for artisan capacity acquisition and strategic partnerships for blockchain traceability deployment.
Among Milan-based heritage houses, Prada SpA and Giorgio Armani SpA exemplify the vertically integrated archetype with controlled retail footprints and made-to-measure atelier services. Luxottica Group SpA represents the specialist component supplier model dominating eyewear distribution through controlled optician networks. These three entities anchor competitive positioning across distinct margin pools without overlapping core competencies.
| Leading Market Players |
|---|
| Prada SpA |
| Giorgio Armani SpA |
| Moncler SpA |
| Luxottica Group SpA |
| Ermenegildo Zegna |
| Dolce & Gabbana S.r.l. |
| OTB Group |
| Salvatore Ferragamo SpA |
| Tod's SpA |
| Others |
Value Chain & Pricing Dynamics
Affluent Asian tourists demanding experiential atelier services and blockchain-verified provenance are compressing wholesale margins while elevating direct-channel premiums, forcing heritage houses to absorb traceability infrastructure costs that artisan tanneries cannot shoulder alone.
Pricing Analysis
Retailer markup layers in exclusive boutiques sustain the highest margin capture, with three-tier pricing structure across premium, standard, and economy levels separating bespoke atelier services from diffusion-line accessibility. Price differentiation hinges on certification grade and geographic delivery cost, with EU Green Deal compliance adding cost layers that heritage houses pass through more effectively than smaller competitors. Pricing pressure stems from raw hide scarcity and Brazilian export taxes, with tourists showing lowest price sensitivity while domestic wholesale partners face margin compression.
Supply Chain Analysis
Master craftsperson shortages in Florence, Scandicci, and Valenza constrain output expansion for hand-finished goldsmithing and vegetable-tanned leather construction. Geographic supply concentration centers on Italy, France, and Switzerland for precision components, with raw material dependencies spanning European cattle hides, Vicenza gold alloys, and Milanese mechanical movements. Supply chain risk manifests through single-source vulnerability in generational artisan workshops. Distribution runs through controlled flagship networks and licensed optician placements that limit channel conflict.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian luxury goods represent a late-cycle quality story as affluent tourists pivot from standardized retail toward experiential atelier purchases with premium provenance specifications.
For Market Incumbents: Lock in maestro artisan succession pipelines through structured apprenticeship programs before generational knowledge gaps widen in Florentine goldsmithing clusters. Acquire compliant tannery capacity in Tuscany ahead of CSRD enforcement deadlines that will eliminate non-compliant wet-blue processors. Prioritize NFC-enabled provenance infrastructure to defend against blockchain-native entrants.
For New Entrants and Emerging Players: Begin with underutilized Sicilian and Apulian manufacturing corridors where EU Green Deal compliance costs remain below Lombardy and Tuscany levels. Target diffusion-line jewelry and leather accessories where heritage houses underinvest in digital-native engagement. Pursue direct-to-consumer subscription styling services that bypass wholesale channel establishment barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heritage houses possessing captive tannery capacity and controlled retail footprints that resist e-commerce commoditization. Long-term viability favors entities with documented artisan succession plans and early CSRD compliance infrastructure. Watch for inflection in tourist traffic recovery at Milan, Florence, and Rome flagship locations as demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Maestro Artisan Succession Programs | Structured apprenticeship pipelines in Florence and Valenza preserve generational craft knowledge transfer. |
| EU Digital Product Passport Compliance | Early traceability infrastructure investment positions heritage houses ahead of 2030 regulatory deadlines. |
| NFC-Enabled Provenance Verification | Embedded authentication chips electrify secondary market demand among Asia-Pacific collector buyers. |
| Experiential Flagship Expansion | Milan and Rome atelier investments capture tourist spending displaced from Asian wholesale channels. |
| Vegetable Tanning Process Conversion | REACH-compliant chemistry transitions in Santa Croce tanneries eliminate regulatory exclusion risk. |
Study Parameters
Bottom-up tourist spending and collector transaction modeling reconciled against top-down tannery output and goldsmithing capacity tracking forms the analytical core of this study. Primary interviews with heritage house brand directors, Tuscan tannery operations managers, Vicenza gold district master craftspeople, and Milan flagship retail executives combined with secondary validation from EU customs records, ISPRA emissions disclosures, CSRD implementation guidance, and Italian industrial association filings. Triangulation across supply-side capacity assessments and demand-side purchase pattern analysis ensures methodological rigor.
Historical trendline analysis of visitor spending patterns, leather goods export volumes, and mechanical watch production outputs established baseline trajectories across the projection horizon. Segmentation modeling incorporated product type, customer archetype, distribution channel, and regional manufacturing cluster dimensions. CAGRs derived from fitted growth curves adjusted for regulatory phase-in schedules and tourist traffic recovery assumptions. Forecast inputs included artisan capacity constraints, REACH compliance cost absorption rates, and blockchain traceability adoption curves.
Several conditions sit outside the modeled scope, including abrupt shifts in China outbound tourism policy, accelerated EU deforestation-free supply chain enforcement, and generational succession failures in master craftsperson workshops. Forecasts reflect assumptions about regulatory timeline adherence and tourist preference stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Europe Handbags Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market