
 Global Gold Jewelry Market | 2026-2036
Global Gold Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gold Jewelry Market Analysis
Capital-intensity divergence between artisanal ateliers and industrial manufacturers is bifurcating the competitive landscape. Cartier leverages vertically integrated Swiss and French workshops to sustain exclusivity in high-jewelry creation. Pandora competes through scalable Thai manufacturing that anchors its accessible 14K and 18K collections across mass-market retail.
Gold jewelry comprises ornamental articles fabricated from gold alloys, typically ranging from 14K to 24K purity, formed through casting, stamping, chain-making, or hand-fabrication processes for personal adornment, wealth storage, and ceremonial exchange. Rings and necklaces dominate volume throughput due to their centrality in bridal and gift-giving occasions across cultures. Contemporary and minimalist design styles are capturing fastest momentum among online shoppers, while traditional styles retain margin concentration through heritage brands and wedding-season demand spikes in South Asia and the Middle East.
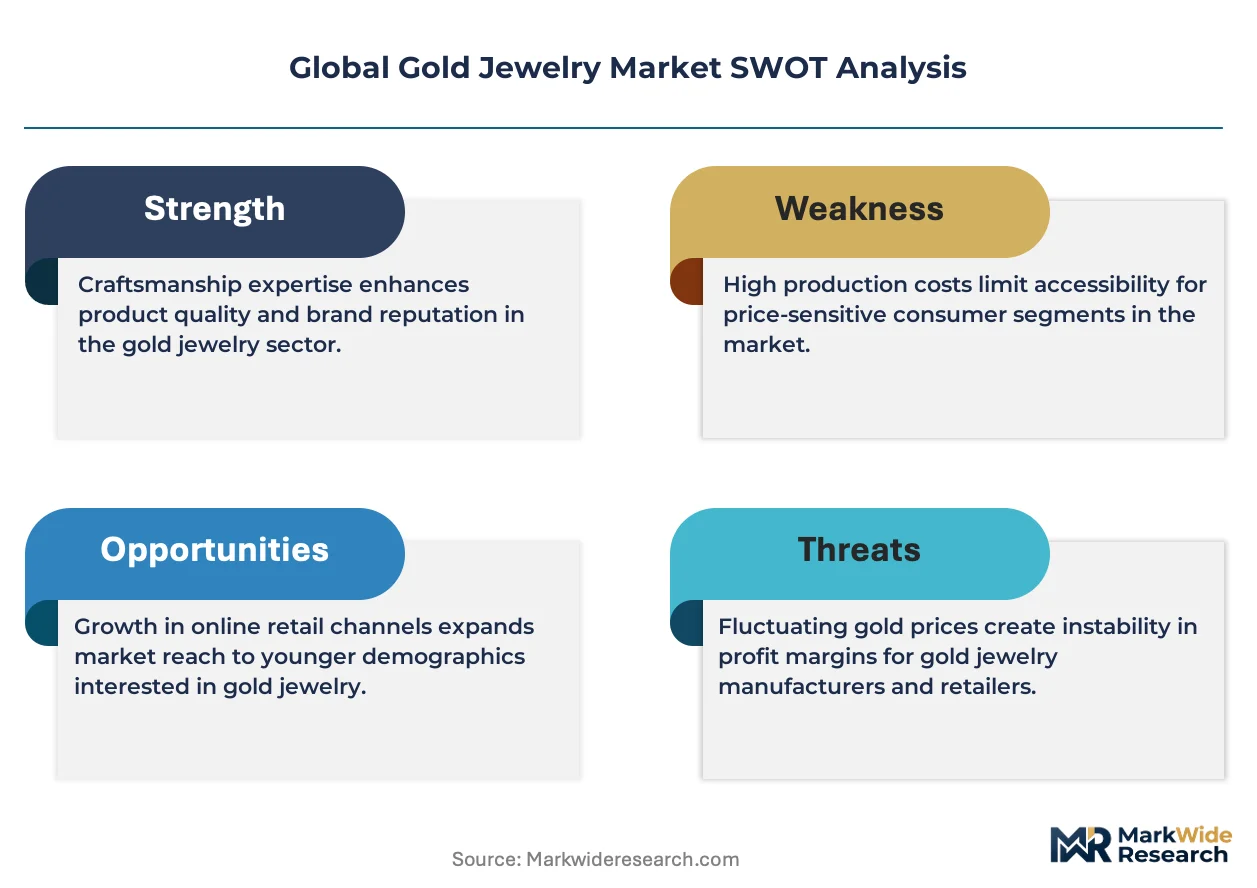
India's BIS hallmarking regulations, China's GB standards for precious metal labeling, and the EU's REACH restrictions on nickel release collectively shape product standards and cross-border market access for gold jewelry exporters. The US FTC's jewelry guides govern alloy disclosure and origin claims for domestic retail. Stakeholders must monitor hallmarking digitization and traceability mandates as these frameworks tighten purity verification and supply chain transparency requirements.
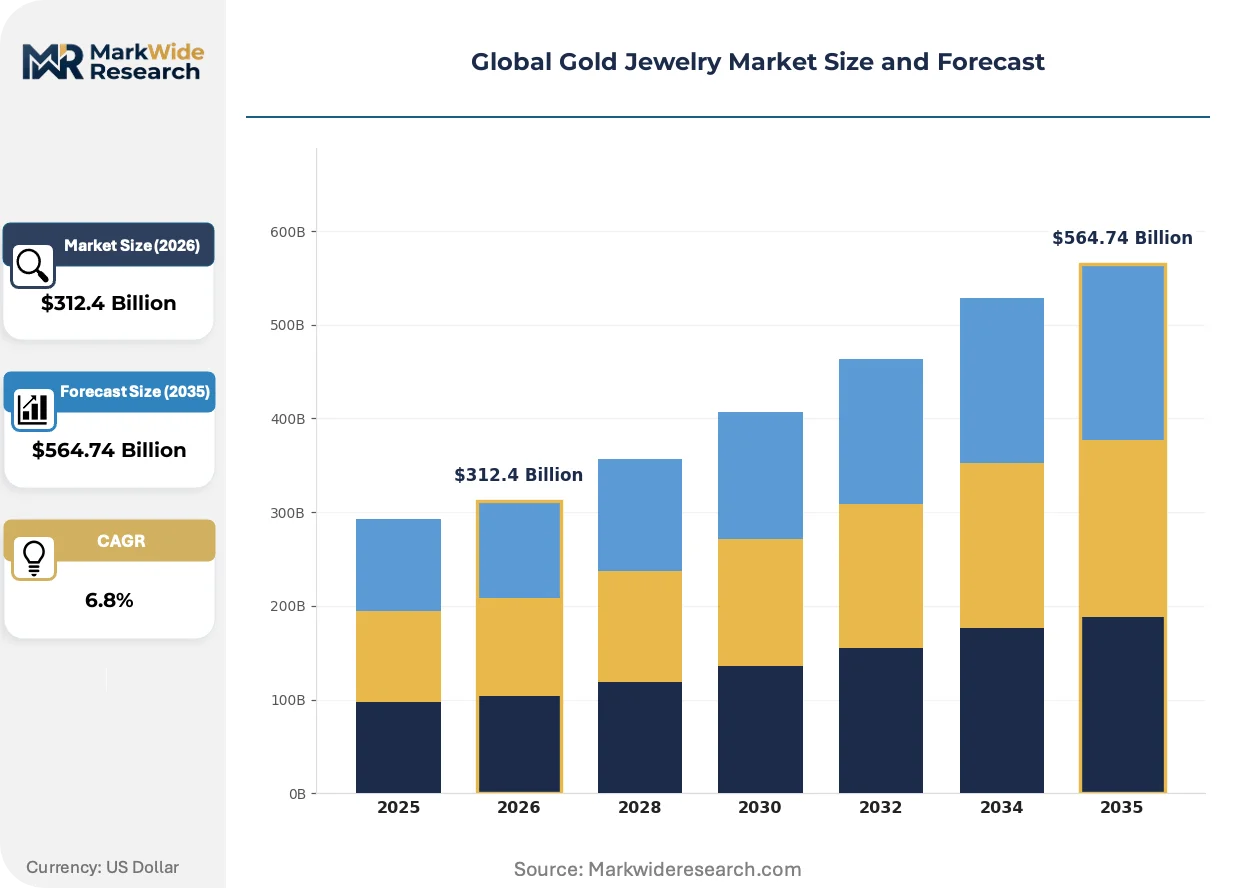
Market Dynamics
India's BIS hallmarking mandate is compressing purity disclosure timelines and forcing wholesale inventory turnover, while China's GB standards for precious metal labeling are tightening cross-border certification requirements for alloy composition accuracy.
Growth Catalysts
- Wedding-season demand spikes:Bridal jewelry procurement in South Asia and the Middle East drives concentrated volume throughput during Q3-Q4 ceremonial cycles.
- BIS Hallmarking Mandate:India's compulsory purity verification is accelerating formal channel migration and displacing unorganized retail participation.
- Digital traceability platforms:Blockchain-anchored provenance systems are penetrating high-value transactions in Swiss and UAE trading hubs.
Market Restraints
- Gold price volatility:London Bullion Market Association pricing swings compress margin predictability for 22K and 24K fabricators.
- Artisanal supply concentration:Hand-fabrication capacity clusters in Jaipur and Istanbul create bottleneck risk during peak seasonal demand.
- REACH nickel restrictions:EU ECHA thresholds on allergen release limit alloy formulation flexibility for export-oriented manufacturers.
Strategic Opportunities
- Vietnam's emerging bridal market:Urbanization in Ho Chi Minh City and Hanoi is expanding ceremonial jewelry procurement outside traditional South Asian corridors.
- Recycled gold certification:LBMA Responsible Gold Guidance compliance opens premium positioning in EU and North American retail channels.
- AI-driven design personalization:Generative tools converging with 3D printing are compressing custom jewelry development cycles for direct-to-consumer platforms.
Industry Challenges
- Master craftsperson scarcity:Hand-engraving and filigree specialization faces generational attrition in traditional manufacturing clusters.
- Hallmarking digitization capex:BIS-mandated testing infrastructure requires substantial capital deployment for mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gold Jewelry Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Rings, Bracelets, Earrings Customer Segment: Luxury Buyers, Middle-Class Consumers, Gift Shoppers, Online Shoppers Design Style: Traditional, Contemporary, Antique, Minimalist Metal Purity: 14K, 18K, 22K, 24K |
| Companies Covered | Graff, Pandora, Cartier, Mikimoto, Mejuri, Tiffany & Co., Van Cleef & Arpels, Boucheron, Bulgari, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gold Jewelry Market Emerging Trajectories
Laser-based manufacturing and purity verification technologies are compressing production timelines while regulatory digitization mandates are reshaping certification workflows across major trading jurisdictions.
Laser marking systems for micro-hallmarking are displacing mechanical stamping in high-throughput manufacturing facilities. Italian and Thai producers are adopting femtosecond laser platforms for precision alloy-layer identification. This displacement is enabling same-day certification turnaround and compressing inventory holding periods for export batches.
EU REACH restrictions on nickel release are forcing alloy reformulation across 18K and 14K product lines. ECHA compliance deadlines are accelerating substitution toward palladium-white gold blends in German and French manufacturing. Bridal segment producers are responding with pre-certified alloy libraries to preempt regulatory friction in cross-border retail.
Direct-to-consumer digital channels are capturing ceremonial jewelry procurement previously routed through family-owned retail networks. Chinese tier-one city buyers are bypassing traditional Shenzhen showrooms for live-stream commerce platforms. This channel rotation is most visible in anniversary and gift-giving occasions among urban professional demographics.
Global Gold Jewelry Market Segmentation
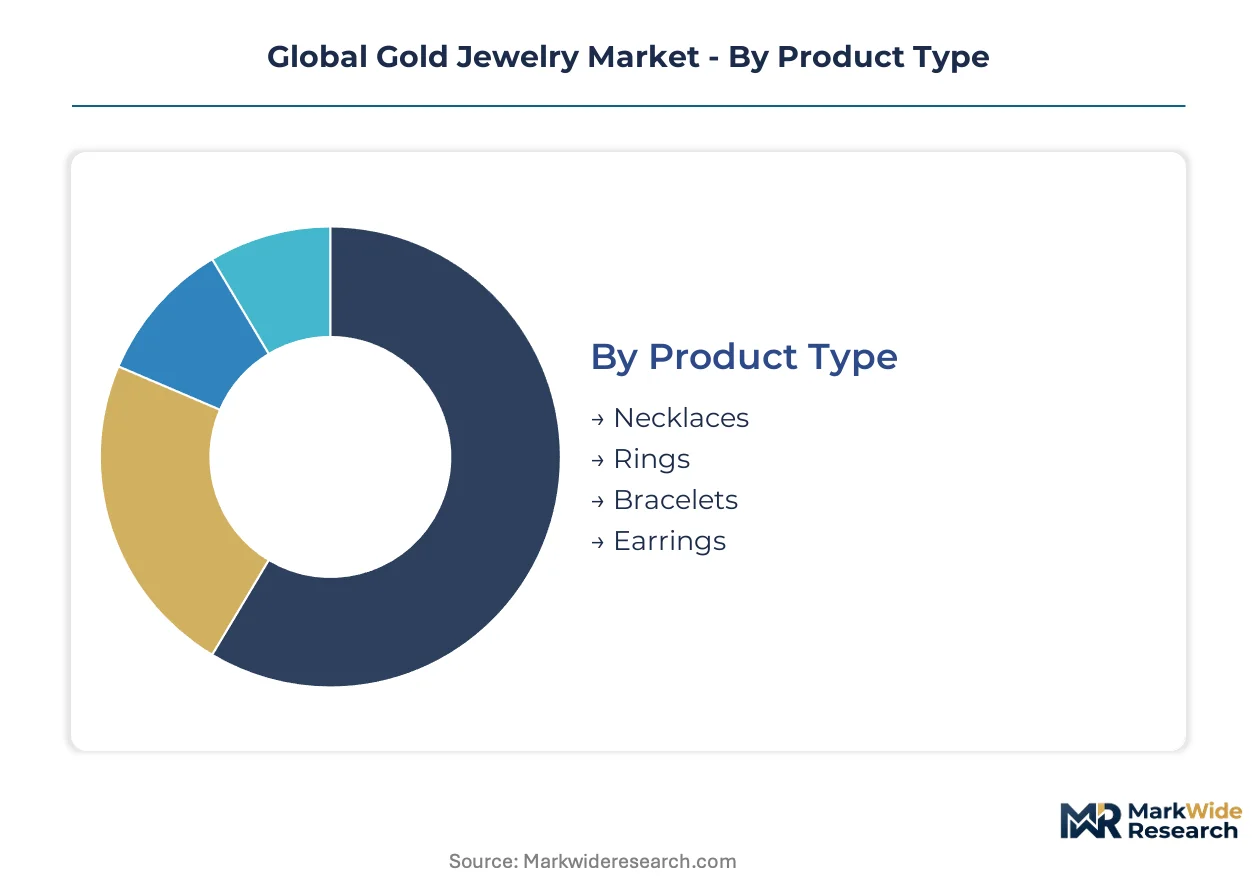
Gold jewelry segmentation reveals how ceremonial traditions, digital channel migration, and regulatory purity mandates fragment demand across distinct customer journeys. Understanding these divides exposes where margin pools concentrate and which alloy-design combinations unlock formal retail penetration.
Product Type:
Rings anchor domestic ceremonial procurement across South Asia and the Middle East, while necklaces dominate export-led wholesale to European and North American retail channels.
- Rings:Bridal and engagement specifications concentrate in 22K and 24K alloys for Indian, Pakistani, and UAE ceremonial markets. India's BIS hallmarking mandate accelerates formal channel migration for wedding-band procurement.
- Necklaces:Chain-making and casting throughput supplies both heritage bridal collections and contemporary lightweight designs for Chinese tier-one city buyers. Volume scales through Thai and Italian manufacturing clusters serving cross-border retail.
- Bracelets:Bangle fabrication retains artisanal concentration in Jaipur and Istanbul workshops.
- Earrings:Stud and drop configurations dominate gift-giving occasions across Southeast Asian urban markets.
Rings command the established base. The steepest expansion runs through necklaces as live-stream commerce penetrates Chinese anniversary and gift-giving occasions.
Customer Segment:
Cost-tier stratification separates bullion-weight purchasers from design-premium buyers, with digital-native segments forcing channel restructuring.
- Luxury Buyers:High-jewelry collections demand vertically integrated Swiss and French workshops for hand-fabrication exclusivity. Cartier and heritage maisons anchor this tier through controlled scarcity and provenance documentation.
- Middle-Class Consumers:Accessible 14K and 18K collections from scalable Thai manufacturing serve mass-market retail across North America and Europe. Pandora's production model captures this volume tier.
- Gift Shoppers:Seasonal procurement concentrates in Q3-Q4 ceremonial cycles across South Asian family networks.
- Online Shoppers:Direct-to-consumer platforms displace traditional Shenzhen showrooms for Chinese tier-one city professionals.
Luxury buyers anchor margin concentration. Online shoppers are gaining share fastest as generative design tools compress customization cycles.
Design Style:
Application context dictates style selection, with ceremonial requirements preserving traditional fabrication while urban professional wardrobes drive minimalist adoption.
- Traditional:Hand-engraving and filigree specialization faces generational attrition in Indian and Turkish manufacturing clusters. Wedding-season demand spikes in South Asia and the Middle East preserve formal atelier relationships.
- Contemporary:AI-driven personalization and 3D printing compression enable rapid prototyping for direct-to-consumer platforms. This segment captures fastest momentum among digitally native purchasers.
- Antique:Estate and reproduction markets concentrate in European auction channels and heritage brand archives.
- Minimalist:Clean geometric forms dominate Japanese and Scandinavian retail preferences for professional daily wear.
Traditional styles retain ceremonial lock-in. Contemporary designs are climbing the fastest as generative tools penetrate high-value transactions.
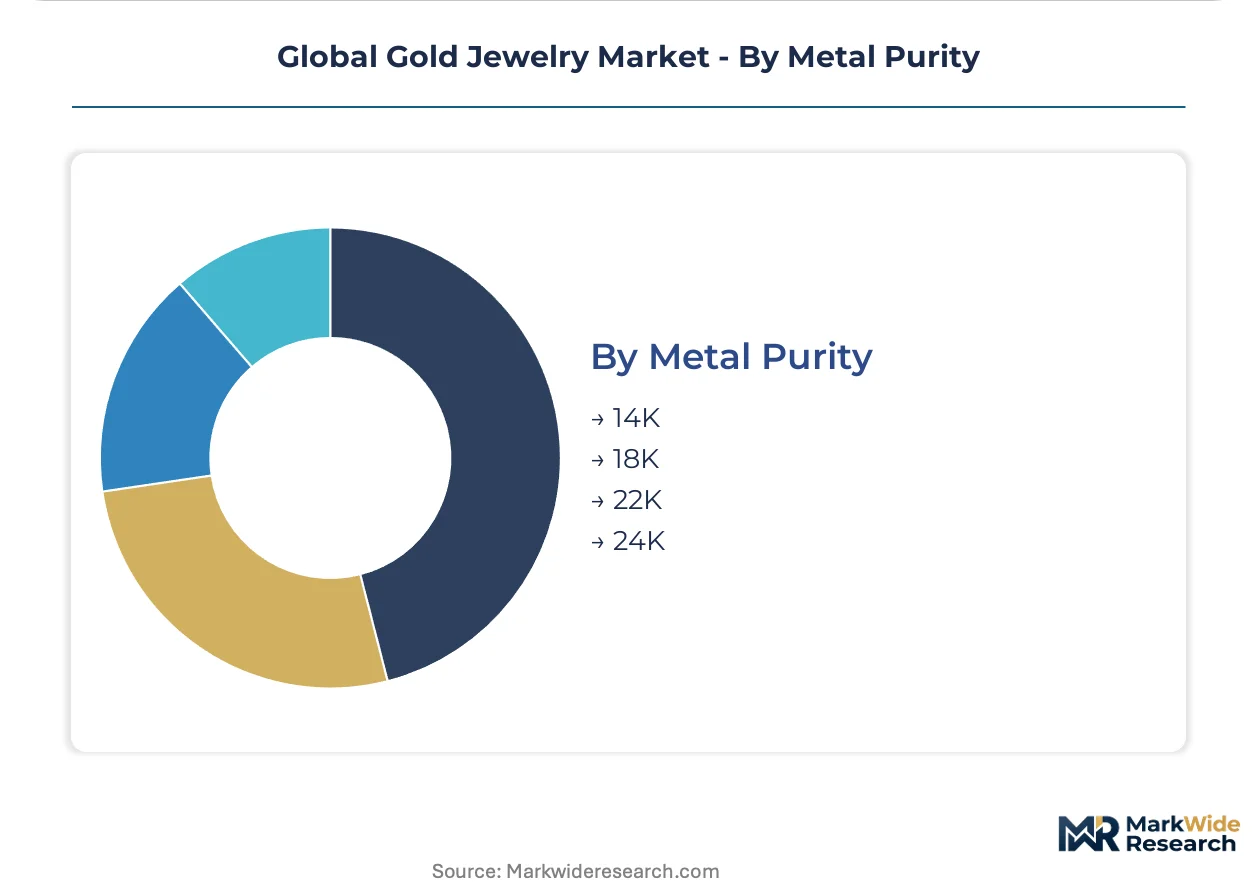
Metal Purity:
Regulatory frameworks and end-use durability requirements fragment alloy selection across geographic markets.
- 22K:Soft, high-gold-content alloys dominate Indian bridal procurement where BIS hallmarking mandates now enforce purity verification. This specification faces working-hardening limitations for daily-wear durability.
- 18K:Balanced gold-copper-silver formulations enable both casting intricacy and wear resistance for European and North American premium retail. EU REACH nickel restrictions force palladium-white gold substitution in German and French manufacturing.
- 14K:Cost-optimized alloys anchor mass-market accessible collections through Thai and Chinese volume manufacturing.
- 24K:Pure gold specifications concentrate in Chinese and Middle Eastern wealth-storage and ceremonial exchange contexts.
22K commands the established base in South Asian ceremonial markets. 18K is expanding most quickly as REACH-compliant alloy libraries preempt European regulatory friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian bridal buyers exhibit extreme price elasticity to 22K and 24K fluctuations, while Swiss and French heritage purchasers demonstrate inelastic demand for high-jewelry provenance. Chinese tier-one city professionals occupy a middle position, trading purity for design innovation in lightweight 18K procurement.
India
Wedding-season procurement drives concentrated Q3-Q4 volume spikes across family retail networks. The BIS hallmarking mandate compresses purity disclosure timelines and accelerates formal channel migration. Jaipur and Surat workshops face bottleneck risk as artisanal hand-fabrication capacity strains against mandate-driven inventory turnover.
China
Live-stream commerce platforms displace traditional Shenzhen showroom traffic among urban professional demographics. GB standards for precious metal labeling tighten cross-border certification requirements for alloy composition accuracy. Manufacturing clusters in Guangzhou and Shenzhen pivot toward lightweight contemporary designs for anniversary and gift-giving occasions.
United States
Accessible 14K and 18K collections anchor mass-market retail penetration across suburban mall networks. The FTC's jewelry guides govern alloy disclosure and origin claims for domestic retail compliance. Thai-manufactured imports through Los Angeles and New York distribution hubs supply volume-tier inventory.
Italy
Heritage atelier relationships preserve margin concentration in traditional bridal and ceremonial segments. EU REACH restrictions on nickel release force palladium-white gold substitution in Vicenza and Arezzo manufacturing zones. Femtosecond laser platforms for precision alloy-layer identification compress same-day certification turnaround.
United Arab Emirates
Wealth-storage and ceremonial exchange contexts sustain 24K pure gold specifications among Gulf clientele. Dubai Multi Commodities Centre traceability frameworks intersect with blockchain-anchored provenance systems for high-value transactions. Gold Souk and Dubai Design District clusters serve cross-border retail re-export to South Asian and African corridors.
Global Gold Jewelry Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Swiss and French heritage maisons command exclusivity through vertically integrated workshops and controlled scarcity. Thai and Chinese volume manufacturers compete on scalable 14K and 18K throughput. Strategic moves concentrate on laser-based manufacturing adoption and recycled gold certification for premium positioning.
Among heritage European maisons, Cartier and Van Cleef & Arpels exemplify the vertically integrated workshop archetype, anchoring high-jewelry creation through controlled provenance documentation. Pandora occupies a position within the scalable manufacturing tier, representing accessible 14K and 18K collection strategies. Tiffany & Co. sits between these archetypes, bridging heritage positioning with broader retail penetration.
| Leading Market Players |
|---|
| Graff |
| Pandora |
| Cartier |
| Mikimoto |
| Mejuri |
| Tiffany & Co. |
| Van Cleef & Arpels |
| Boucheron |
| Bulgari |
| Others |
Supply Flow & Price Mechanics
India's BIS hallmarking mandate gates both supply qualification and price differentiation simultaneously, forcing mid-tier fabricators to deploy capital into testing infrastructure while heritage ateliers capture purity-premium positioning through controlled scarcity.
Pricing Analysis
After-sales service revenue from resizing, polishing, and lifetime maintenance drives lifetime value capture across bridal procurement cycles. Three-tier pricing structure across heritage atelier, certified retail, and unorganized market tiers anchors the market, with purity verification and provenance documentation as the primary differentiation drivers. Pricing pressure stems from London Bullion Market Association gold price volatility compressing margin predictability for 22K and 24K fabricators. Indian bridal buyers exhibit extreme price sensitivity to alloy fluctuations, while Swiss heritage purchasers demonstrate inelastic demand for high-jewelry craftsmanship.
Supply Chain Analysis
Inventory holding periods compress as laser-based micro-hallmarking enables same-day certification turnaround for export batches. Supply concentrates in Thailand, Italy, and India for volume manufacturing, with Swiss and French workshops anchoring high-jewelry fabrication. Raw material flows draw from LBMA-certified refineries, recycled gold streams, and Dubai Multi Commodities Centre trading hubs. Single-source vulnerability clusters in Jaipur hand-fabrication capacity create bottleneck risk during Q3-Q4 wedding-season demand spikes. Distribution runs through family-owned retail networks in South Asia, live-stream commerce platforms in Chinese tier-one cities, and suburban mall networks across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with digital traceability platforms penetrating high-value transactions and compressing provenance verification timelines across Swiss and UAE trading hubs.
For Market Incumbents: Compound defensive positioning through backward integration into LBMA-certified refining capacity and captive control over laser-hallmarking infrastructure. Displacement risk from AI-driven design personalization tools threatens traditional atelier relationships. Priority investment in femtosecond laser platforms and blockchain-anchored provenance systems secures certification workflow dominance.
For New Entrants and Emerging Players: LBMA Responsible Gold Guidance certification fast-tracks premium positioning in EU and North American retail channels previously gated by heritage brand incumbency. Vietnam's emerging bridal market in Ho Chi Minh City and Hanoi offers the most penetrable white-space, with urbanization expanding ceremonial procurement outside traditional South Asian corridors. Direct-to-consumer platforms with generative design tools enable rapid customization cycles for anniversary and gift-giving occasions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mid-tier fabricators facing BIS-mandated testing infrastructure deployment. Long-term viability favors acquisition targets with established recycled gold certification and scalable Thai or Chinese manufacturing footprints. The signal to watch is hallmarking digitization mandate expansion beyond India into Southeast Asian manufacturing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Gold Certification | LBMA Responsible Gold Guidance compliance unlocks premium EU and North American retail channel access. |
| Laser-Hallmarking Infrastructure | Femtosecond laser platforms compress certification turnaround and displace mechanical stamping in Thai and Italian facilities. |
| Blockchain Provenance Systems | Dubai Multi Commodities Centre traceability frameworks intersect with digital platforms for high-value transaction verification. |
| Direct-to-Consumer Platform Launch | Live-stream commerce penetration in Chinese tier-one cities displaces traditional Shenzhen showroom traffic. |
| AI-Driven Design Personalization | Generative tools converging with 3D printing compress custom jewelry development cycles for digitally native purchasers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs records, LBMA trade data, and BIS regulatory filings. Primary interviews engaged jewelry manufacturing executives, heritage atelier owners, retail procurement managers, and precious metals traders across Swiss, Indian, Thai, and Chinese trading hubs. Secondary validation drew from BIS hallmarking compliance databases, EU ECHA REACH restriction notices, and Dubai Multi Commodities Centre traceability frameworks. Bottom-up fabrication capacity estimates triangulate against top-down retail channel throughput analysis.
Segmentation dimensions modeled span product type, customer segment, design style, and metal purity across the projection horizon. Analytical framework projects volume and value outputs through alloy-specific demand elasticity curves and regulatory compliance cost trajectories. CAGRs derive from purity-mandate adoption timelines and digital channel penetration rates in ceremonial procurement cycles.
Underlying assumptions cover BIS hallmarking enforcement continuity, LBMA pricing regime stability, and REACH nickel restriction compliance deadlines, with deviation risk concentrated in gold price volatility spikes and artisanal craftsperson generational attrition. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Luxury Apparels Market