
 Pearl Jewelry Market | 2026-2036
Pearl Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Pearl Jewelry Market Analysis
Lab-grown diamond and moissanite competition is hardening price discipline in the fine jewelry tier. Mikimoto leverages its Akoya pearl farming heritage to sustain premium positioning across Asian retail corridors. Paspaley anchors its supply chain through captive South Sea pearl operations in Australian waters. Tiffany & Co. differentiates via vertically controlled sourcing narratives and heritage design codes.
Pearl jewelry comprises ornamental pieces featuring nacreous gems formed within mollusk shells, graded by luster, surface quality, shape, and nacre thickness measured in millimeters. These pieces serve ceremonial, investment, and fashion accessorization purposes across consumer segments. Freshwater pearl necklaces occupy the highest volume tier due to accessible price points and scalable Chinese supply. South Sea pearl earrings command concentrated margin pools among ultra-luxury buyers. Akoya pearl bracelets retain entrenched demand in Japanese bridal traditions.
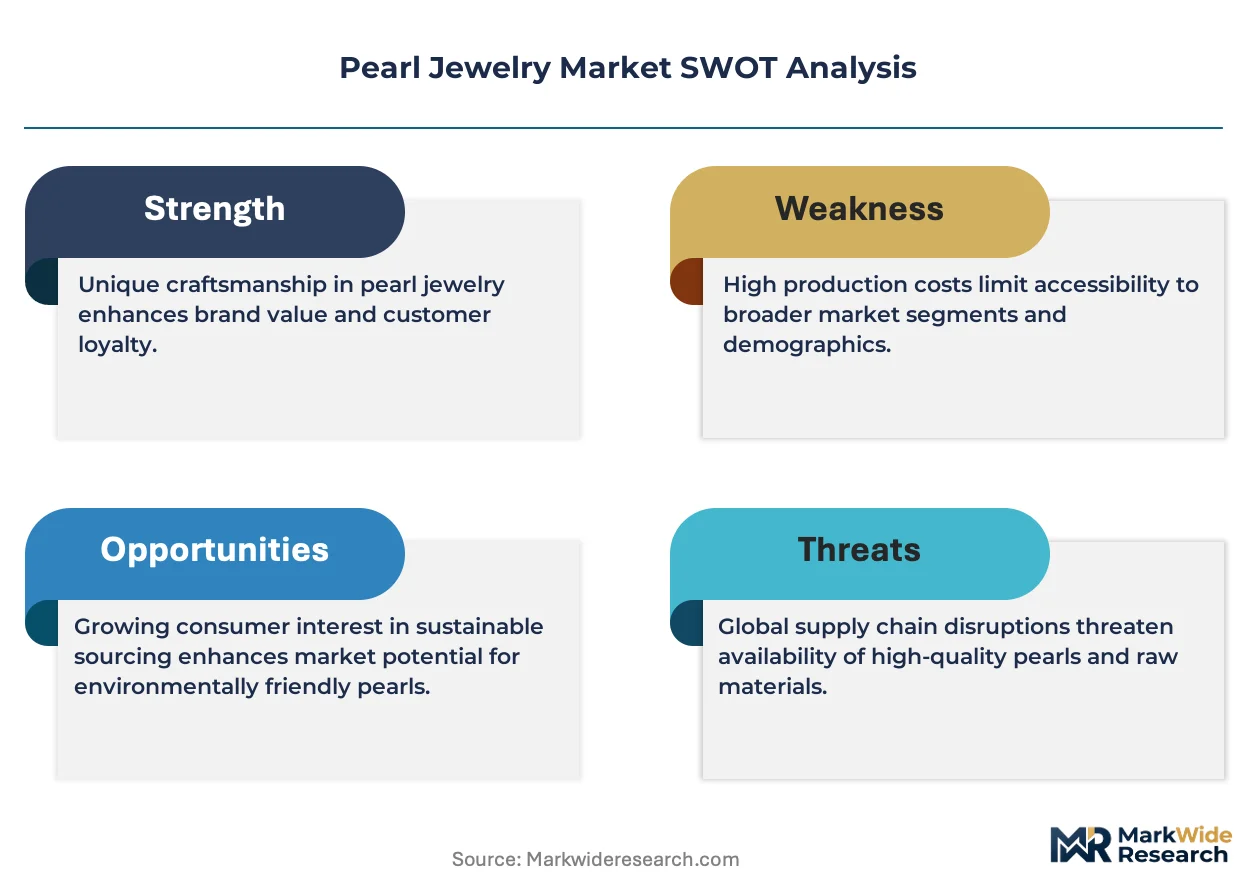
Japan's Ministry of Economy, Trade and Industry (METI) enforces jewelry labeling standards that protect consumer transparency on pearl origin and treatment. Australia's biosecurity frameworks and CITES export controls govern Pinctada maxima shell movement, constraining raw material availability. Stakeholders must monitor evolving EU Green Deal due diligence requirements on precious materials sourcing and decide whether to front-run compliance investments or risk market access friction.
Market Dynamics
Cultured pearl nucleation automation is compressing production timelines while CITES traceability mandates restructure sourcing hierarchies, forcing mid-tier operators to consolidate or exit.
Growth Catalysts
- EU Green Deal due diligence:Mandatory supply chain disclosure for precious materials is redirecting procurement toward certified Australian and Japanese farms with established documentation systems.
- Biometric pearl grading:Spectral imaging technology now maps nacre thickness with 0.1mm precision, reducing valuation disputes and accelerating wholesale transactions.
- East Asian bridal demand:Multi-piece pearl sets for traditional ceremonies in Japan and South Korea sustain volume commitments from heritage retailers.
Market Restraints
- Pinctada maxima shell concentration:Australian biosecurity frameworks limit broodstock export, constraining South Sea pearl farm expansion in Southeast Asia.
- Lab-grown diamond substitution:Moissanite and synthetic diamond price compression in fine jewelry tiers erodes pearl's accessible-luxury positioning among younger buyers.
- Akoya harvest volatility:Climate-induced red tides in Japanese coastal waters have destabilized annual yield predictability for traditional cultivators.
Strategic Opportunities
- Direct-to-consumer authentication:Blockchain-traceable pearl provenance platforms are capturing margin previously absorbed by layered wholesale networks.
- Menswear accessory expansion:Cufflinks and lapel pins featuring Tahitian pearls represent underdeveloped territory outside formal Japanese business attire.
- India's organized retail penetration:Heritage jewelry houses in Mumbai and Hyderabad are building dedicated pearl galleries targeting pre-wedding gifting occasions.
Industry Challenges
- Master grafter scarcity:Surgical nucleation of oyster tissue requires 5-7 year apprenticeships, and aging practitioner pools in Japan and Australia threaten knowledge transfer.
- Multi-jurisdiction compliance layering:Simultaneous METI labeling, CITES export permits, and emerging EU deforestation regulations create documentation bottlenecks for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearl Jewelry Market |
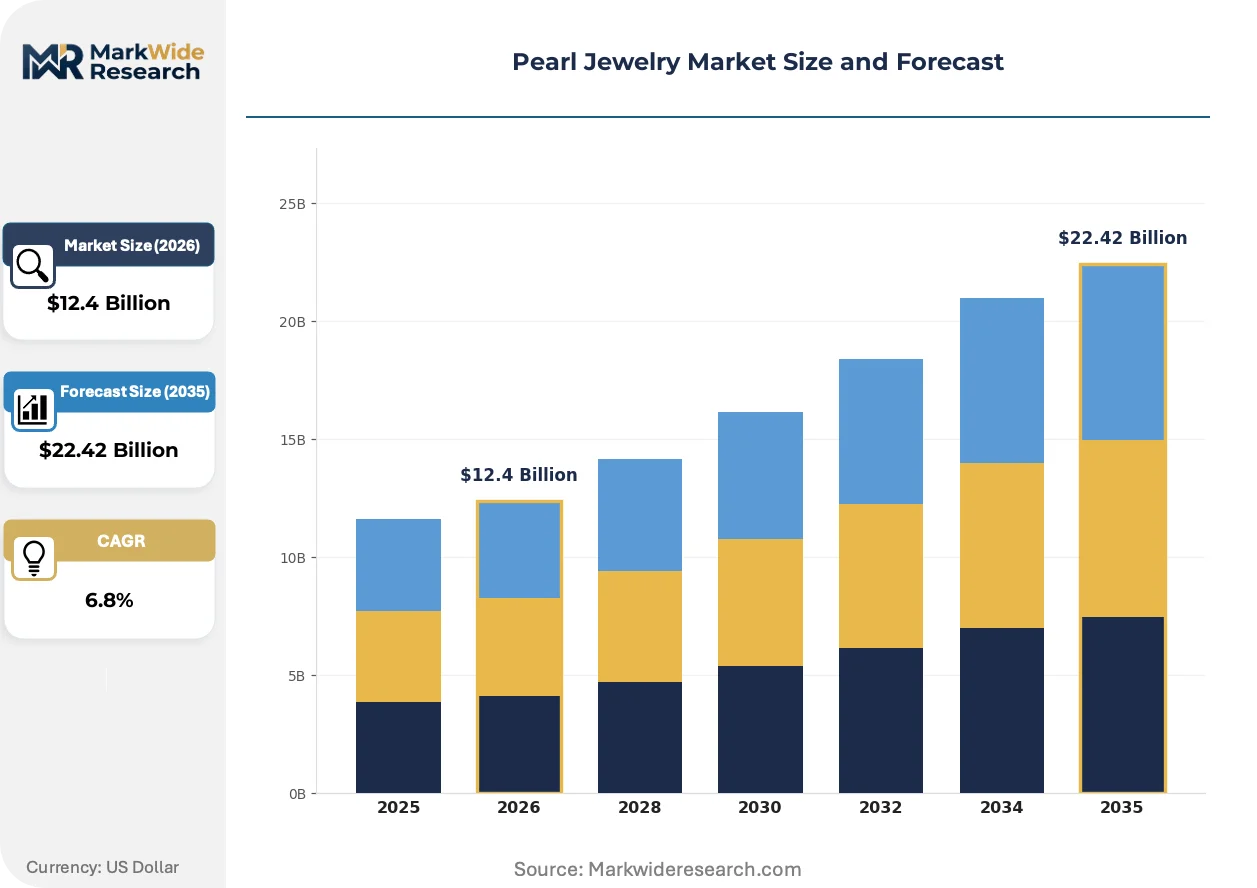
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Earrings, Bracelets, Rings Material: Freshwater Pearls, Akoya Pearls, Tahitian Pearls, South Sea Pearls Customer Type: Retail Consumers, Wholesale Buyers, Online Shoppers, Gift Buyers Price Tier: Luxury, Mid-Range, Affordable, Discount |
| Companies Covered | Wing Wo Hing Jewelry Group, Zearrow, Mikimoto, Pearl Paradise, DWS Jewellery Pvt. Ltd., Tiffany & Co., Fine Chic, Paspaley, Tasaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearl Jewelry Market Emerging Trajectories
Digital provenance infrastructure and biometric quality assessment are displacing traditional valuation hierarchies while regulatory disclosure requirements accelerate supply chain consolidation.
X-ray computed tomography is automating non-destructive nacre thickness mapping across entire harvest lots. Major auction houses in Hong Kong and Kobe have adopted this protocol for pre-sale certification. The technology is automating what previously required destructive sampling and master grader consensus, compressing transaction timelines from weeks to days.
Japan's METI labeling standards now mandate explicit disclosure of pearl origin, treatment history, and cultivation method on consumer-facing documentation. Retailers must maintain auditable chain-of-custody records or face market withdrawal penalties. Akoya pearl bracelet segments with incomplete documentation are experiencing inventory velocity degradation as buyers demand verified provenance.
Certification-driven purchasing now dominates ultra-luxury pearl acquisition, with buyers requesting third-party laboratory reports before committing to South Sea pearl earrings above threshold values. Heritage auction channels in Geneva and New York are ceding volume to private treaty sales where documentation completeness is guaranteed. Japanese bridal retailers report that un-certified inventory now requires 40-60% longer sell-through cycles compared to documented equivalents.
Pearl Jewelry Market Segmentation
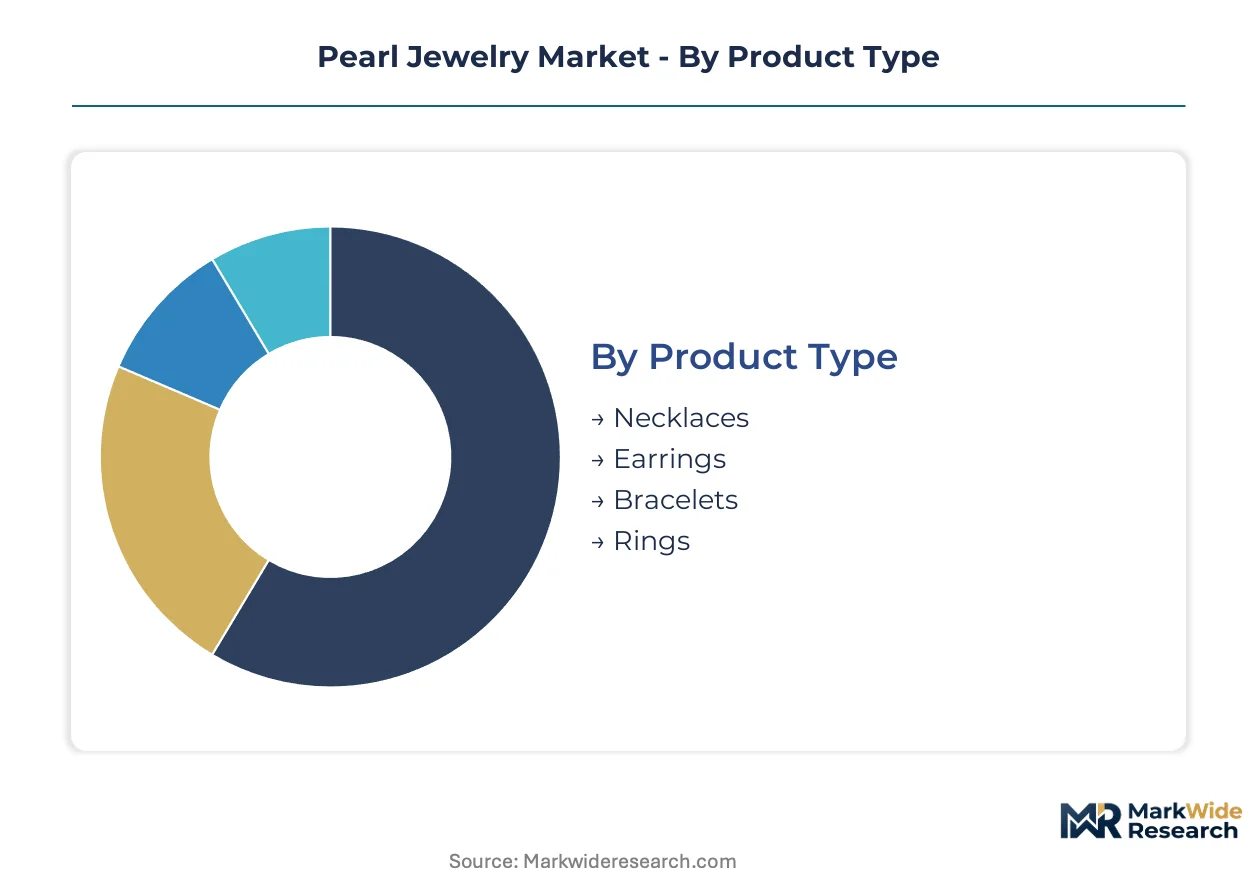
Pearl jewelry segmentation reflects divergent upgrade cycles across ceremonial, investment, and fashion accessorization contexts. Purchase frequency and replacement timing vary sharply between bridal heirloom acquisitions and trend-driven fashion rotations.
Product Type:
Upgrade cycles stretch from single lifetime ceremonial purchases to seasonal fashion refresh patterns, with ceremonial pieces commanding extended replacement timelines.
- Necklaces:Multi-strand and pendant configurations dominate ceremonial gifting in Japanese bridal traditions. Strand length and clasp precious metal content determine tier placement in heritage retailer assortments.
- Earrings:Stud and drop configurations concentrate margin in ultra-luxury South Sea pearl segments, with biometric grading now standard for transactions above threshold values in Hong Kong auction channels.
- Bracelets:Akoya pearl strands retain entrenched demand in East Asian anniversary gifting cycles, with incomplete documentation now requiring 40-60% longer sell-through cycles versus verified equivalents.
- Rings:Solitaire and cluster settings represent emerging territory for Tahitian pearl differentiation outside traditional Japanese markets.
Necklaces sit at the top of the volume ranking, with rings climbing the fastest.
Material:
Cost tier alignment separates scalable supply from constrained premium sourcing, with nacre thickness and luster metrics driving price stratification.
- Freshwater Pearls:Chinese cultivation at scale enables accessible price points and highest volume throughput. Scalable nucleation automation compresses production timelines while maintaining surface quality consistency for fashion-tier jewelry.
- South Sea Pearls:Pinctada maxima cultivation in Australian waters operates under strict biosecurity frameworks limiting broodstock export. CITES traceability mandates and nacre thickness above 2.0mm command concentrated margin pools among ultra-luxury buyers.
- Akoya Pearls:Japanese coastal cultivation faces climate-induced harvest volatility from red tide events, destabilizing yield predictability for traditional METI-compliant producers.
- Tahitian Pearls:French Polynesian Pinctada margaritifera operations supply the distinctive dark nacre segment, with color variation driving differentiation in menswear accessory expansion.
Freshwater pearls hold volume leadership, while South Sea pearls gain share fastest in certified provenance channels.
Customer Type:
Channel preferences fragment across documentation requirements and authentication infrastructure availability, reshaping procurement hierarchies.
- Retail Consumers:Brick-and-mortar purchasers in heritage jewelry corridors demand METI-compliant labeling and explicit treatment disclosure, with biometric grading reducing valuation disputes.
- Wholesale Buyers:Layered distribution networks face margin compression from blockchain-traceable direct-to-consumer platforms capturing provenance premiums.
- Online Shoppers:Digital-native purchasers prioritize third-party laboratory reports and spectral imaging certification before commitment, accelerating private treaty sales volume.
- Gift Buyers:Pre-wedding and anniversary gifting occasions in Indian organized retail drive dedicated pearl gallery development in Mumbai and Hyderabad.
Retail consumers anchor volume concentration, with online shoppers expanding most quickly in authenticated channels.
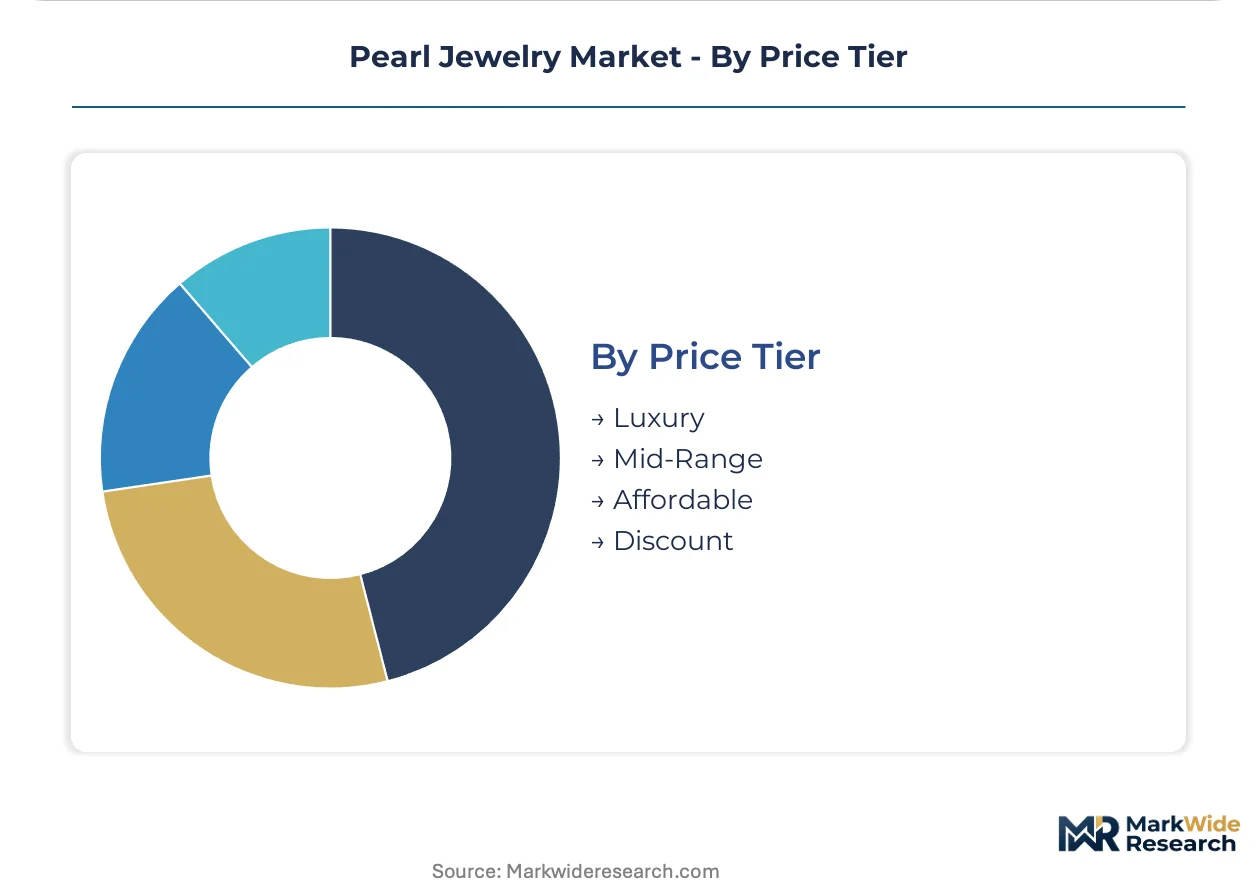
Price Tier:
Margin structure reflects supply chain documentation completeness and cultivation method transparency, with regulatory disclosure requirements accelerating tier consolidation.
- Luxury:Vertically controlled sourcing narratives and heritage design codes differentiate offerings above threshold values, with X-ray computed tomography certification now standard for pre-sale verification.
- Mid-Range:Akoya pearl segments with established chain-of-custody records maintain inventory velocity against undocumented competitors facing market withdrawal penalties.
- Affordable:Freshwater pearl fashion accessorization competes with lab-grown diamond substitution pressure among younger buyer cohorts.
- Discount:Unverified provenance inventory experiences elongated sell-through cycles as certification-driven purchasing dominates acquisition behavior.
Mid-range tier holds steady volume position, with luxury tier showing steepest expansion trajectory in documented provenance channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Kobe and Tokyo metropolitan corridors anchor the highest-value pearl jewelry trading infrastructure, with heritage auction houses and bridal retail networks commanding concentrated margin pools for certified Akoya and South Sea specimens.
Japan
East Asian bridal traditions sustain multi-piece pearl set acquisitions for ceremonial occasions, with Japanese retailers reporting 40-60% faster inventory velocity for METI-compliant documented inventory. Japan's Ministry of Economy, Trade and Industry enforces jewelry labeling standards mandating explicit origin and treatment disclosure. Kobe's pearl auction houses have adopted X-ray computed tomography protocols for pre-sale nacre thickness certification.
Australia
Ultra-luxury South Sea pearl demand concentrates among buyers requesting third-party laboratory reports for specimens above threshold values. Australian biosecurity frameworks and CITES export controls govern Pinctada maxima shell movement, constraining raw material availability. Broome and Darwin harbor operations anchor captive cultivation infrastructure with established chain-of-custody documentation systems.
China
Freshwater pearl necklaces occupy the highest volume tier due to accessible price points and scalable nucleation automation compressing production timelines. The country's national standards body maintains cultivation quality benchmarks for export-oriented production. Zhuji and Weitang industrial clusters supply fashion-tier jewelry to wholesale distribution networks across domestic and international corridors.
India
Pre-wedding gifting occasions in organized retail drive dedicated pearl gallery development targeting gift buyer segments. The Bureau of Indian Standards oversees jewelry hallmarking requirements for precious metal content in pearl mountings. Mumbai and Hyderabad heritage jewelry houses are building specialized retail formats for ceremonial acquisition patterns.
United States
Luxury bridal wear and anniversary gifting segments sustain volume commitments from heritage retailers in metropolitan corridors. The Federal Trade Commission monitors jewelry advertising claims for origin and treatment disclosure accuracy. New York and Los Angeles retail corridors concentrate vertically controlled sourcing narratives and heritage design code differentiation.
Pearl Jewelry Market Vendor Landscape
Portfolio diversification dominates the current landscape as operators respond to documentation requirements and biometric grading technology. The vendor base separates into heritage cultivators with captive farming operations, vertically integrated luxury houses, and digital-native direct-to-consumer platforms. Three archetypes define competitive positioning: Akoya heritage specialists, South Sea ultra-luxury anchors, and scalable freshwater fashion suppliers. M&A activity and direct-to-consumer authentication infrastructure represent the dominant competitive vectors reshaping margin capture.
Within the heritage cultivator tier, Mikimoto, Paspaley, and Tasaki occupy positions exemplifying divergent geographic and material specializations. Mikimoto represents Japanese Akoya farming lineage with entrenched bridal retail corridor presence. Paspaley anchors Australian South Sea pearl operations through captive Pinctada maxima cultivation under strict biosecurity frameworks. Tasaki sits within the integrated luxury jewelry house archetype, bridging cultivation heritage with contemporary design codes for East Asian and Western metropolitan markets.
| Leading Market Players |
|---|
| Wing Wo Hing Jewelry Group |
| Zearrow |
| Mikimoto |
| Pearl Paradise |
| DWS Jewellery Pvt. Ltd. |
| Tiffany & Co. |
| Fine Chic |
| Paspaley |
| Tasaki |
| Others |
Supply Flow & Price Mechanics
Family-owned heritage cultivators in Japan and Australia anchor supply-side discipline through generational farming operations that resist price volatility while maintaining premium positioning against scalable Chinese freshwater production. Their captive Pinctada maxima and Akoya operations create natural cost pass-through mechanisms when biosecurity constraints tighten raw material availability.
Pricing Analysis
Input-cost pass-through from nucleation labor and CITES documentation fees stratifies pricing across certified provenance tiers. Price differentiation hinges on nacre thickness certification and METI-compliant chain-of-custody records, with biometrically graded South Sea specimens commanding sustained premiums. Cost compression in freshwater fashion tiers intensifies from lab-grown diamond substitution among younger buyers. Gift buyers in Indian organized retail show highest price sensitivity, while ultra-luxury collectors demonstrate minimal elasticity for documented Australian harvests.
Supply Chain Analysis
Direct-to-consumer authentication platforms handle rising volume from digital-native purchasers seeking bypassed wholesale markups. Raw material concentration centers on Japanese Akoya coastal farms, Australian Pinctada maxima operations, and Chinese freshwater nucleation clusters. Supply chains draw from master grafter labor pools, CITES-permitted broodstock, and spectral imaging equipment. Single-source vulnerability threatens South Sea expansion as Australian biosecurity frameworks constrain Pinctada maxima shell export. Distribution runs through heritage auction houses in Kobe, private treaty channels in Geneva, and dedicated pearl galleries in Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pearl jewelry market reads as a late-cycle quality story where certification-driven purchasing redirects volume toward documented provenance channels. East Asian bridal demand for multi-piece ceremonial sets sustains premium specification commitments despite accessible-luxury substitution pressure.
For Market Incumbents: Deploy biometric grading infrastructure to defend margin position against undocumented competitors facing inventory velocity degradation. Consolidate master grafter apprenticeship programs to address knowledge transfer gaps threatening Japanese and Australian cultivation continuity. Deepen captive farming control over Pinctada maxima broodstock as biosecurity restrictions harden.
For New Entrants and Emerging Players: Launch via blockchain-traceable direct-to-consumer platforms targeting menswear accessory white space in Tahitian pearl cufflinks and lapel pins outside formal Japanese business attire. Penetrate Indian pre-wedding gifting corridors through dedicated pearl gallery formats in Hyderabad and Mumbai heritage retail clusters.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier Akoya operators with incomplete documentation facing METI compliance investment requirements. Long-term viability favors vertically controlled Australian South Sea assets with established CITES permitting infrastructure. Watch biometric certification adoption rates at Hong Kong auction houses as inflection indicator for provenance premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Investment | X-ray computed tomography adoption at Kobe auction houses compresses transaction timelines from weeks to days. |
| Direct-to-Consumer Authentication Platform | Blockchain-traceable provenance captures margin previously absorbed by layered wholesale networks. |
| Master Grafter Apprenticeship Expansion | Five-to-seven year surgical nucleation training programs address aging practitioner pools in Japan. |
| Menswear Accessory Line Development | Tahitian pearl cufflinks target underpenetrated formal attire segments outside Japanese markets. |
| Indian Organized Retail Gallery Buildout | Dedicated pearl galleries in Mumbai and Hyderabad capture pre-wedding gifting occasion demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with heritage cultivator executives, METI compliance officers, auction house certification specialists, and Indian organized retail jewelry buyers with secondary validation. Sources included CITES trade permit databases, METI labeling enforcement records, Hong Kong and Kobe auction transaction protocols, and Australian biosecurity framework documentation. Bottom-up harvest volume estimates and top-down retail channel assessments triangulated market sizing.
Segment-weighting across product type, material origin, customer channel, and price tier informed analytical framework construction throughout the projection horizon. CAGRs derived from time-series modeling of cultivation output, regulatory compliance cost trajectories, and bridal demand cyclicality in East Asian markets. Forecast inputs incorporated climate-induced harvest volatility patterns and spectral imaging technology diffusion curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal enforcement acceleration or Pinctada maxima disease outbreaks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
China Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Latin America Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Customized Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Artificial Jewellery Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Crystal Bracelets Market