
 Germany Luxury Goods Market | 2026-2036
Germany Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Luxury Goods Market Foresight
The price-performance boundary between artisanal luxury goods and mass-premium alternatives is hardening in Germany, with craftsmanship authentication and provenance documentation becoming decisive purchase criteria. LVMH Moët Hennessy Louis Vuitton leverages its integrated atelier network to sustain vertical control over leather goods quality. Hugo Boss AG anchors its position through technical innovation in performance-luxe apparel, while Mytheresa Group GmbH competes via curated digital curation and same-day delivery in Bavaria and Baden-Württemberg.
Germany luxury goods encompass meticulously crafted, scarcity-positioned products spanning horology, leatherwork, jewelry, and haute couture, typically utilizing precious metals, exotic skins, mechanical movements, and hand-finished textiles to signal exclusivity and cultural capital. Leather goods and watches occupy the deepest margin pools due to repair-service ecosystems and resale value retention among collectors. Online platforms represent the fastest-growing distribution channel, though specialty stores dominate transaction value through personalized styling and authentication services for ultra-premium and bespoke tiers.
The KBA enforces strict product safety and chemical compliance for leather tanning and fragrance formulations, while REACH and the EU Green Deal mandate supply chain carbon disclosure and restricted substance protocols that elevate compliance costs for imported materials. Germany's Supply Chain Due Diligence Act further obliges large luxury houses to audit subcontractor labor practices across tier-two and tier-three suppliers. Stakeholders must monitor evolving CSRD reporting thresholds and consumer litigation risk around greenwashing claims as regulatory scrutiny intensifies.
Market Dynamics
Affluent millennials and Gen Z consumers are compressing purchase cycles toward experiential luxury and digital-native channels, forcing heritage houses to reconfigure atelier workflows and authentication protocols around immediacy expectations.
Growth Catalysts
- EU Green Deal mandates:Carbon disclosure requirements for supply chains are accelerating investment in traceable sourcing platforms and blockchain-based provenance systems across leather goods and jewelry tiers.
- Experiential luxury demand:Pop-up atelier events and immersive brand storytelling in Munich, Hamburg, and Berlin are converting digital-native consumers into high-margin bespoke clients.
- Repair-service ecosystems:Mechanical watch restoration and leather refurbishment programs are extending customer lifetime value and insulating margin pools from secondary market erosion.
Market Restraints
- Exotic skin input volatility:CITES permitting delays and farm-to-tannery traceability costs are compressing gross margins on crocodile and python leather goods by fifteen to twenty-five percent.
- Supply concentration in Italian tanneries:Over sixty percent of premium calf leather processing sits within three regions of Tuscany, creating vulnerability to energy price shocks and labor stoppages.
- REACH chemical compliance friction:Restricted substance protocols for fragrance formulations and chrome-free tanning alternatives are extending product development timelines by eight to fourteen months.
Strategic Opportunities
- Baden-Württemberg and Bavaria penetration:Stuttgart and Nuremberg metropolitan clusters show underdeveloped ultra-premium retail presence relative to HNW density and automotive executive purchasing power.
- Same-day delivery infrastructure:Curated digital platforms with localized warehousing are capturing share from traditional department store concessions in secondary cities.
- CSRD reporting tailwinds:Early compliance with corporate sustainability disclosure requirements is positioning first-movers for institutional procurement contracts and ESG-mandated wealth management channels.
Industry Challenges
- Artisan skill scarcity:Master leatherworkers and haute couture seamstresses are retiring faster than apprenticeship pipelines replenish, particularly in hand-finishing and mechanical movement assembly.
- Greenwashing litigation exposure:Consumer protection authorities and class-action firms are scrutinizing carbon-neutral claims and recycled content percentages in marketing materials.
- Legacy system integration:ERP modernization for atelier inventory and clienteling platforms is requiring eighteen-to-thirty-six month implementation cycles with significant business disruption risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Luxury Goods Market |
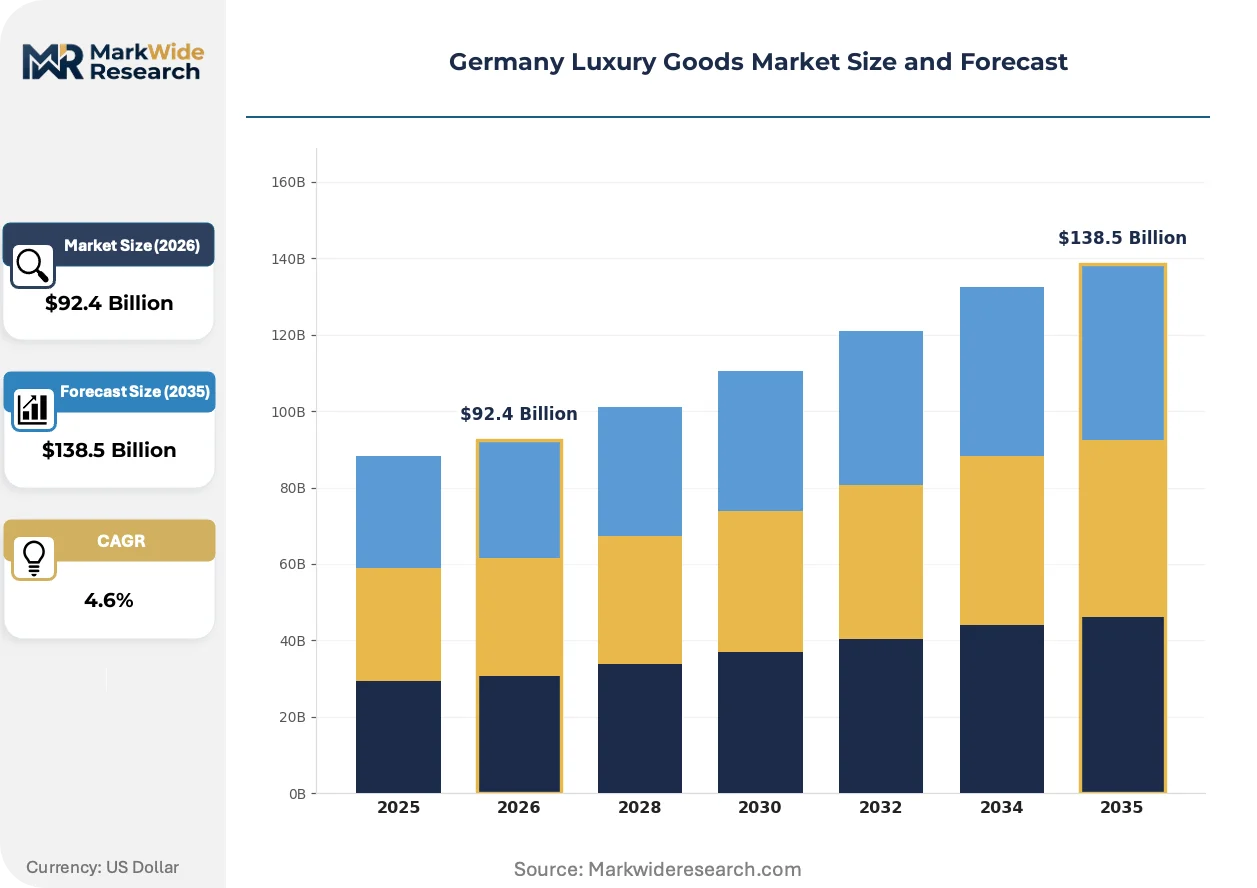
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $138.5 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watches, Jewelry, Leather Goods, Fragrances, Apparel Distribution Channel: Specialty Stores, Online Platforms, Department Stores, Duty-Free, Boutique Outlets Customer Type: Affluent Individuals, Business Executives, Collectors, Tourists Price Tier: Premium, Ultra-Premium, Exclusive, Bespoke |
| Companies Covered | Richemont Group, Burberry Group plc, LVMH Moët Hennessy Louis Vuitton, Mytheresa Group GmbH, Chanel S.A., Kering S.A., Hugo Boss AG, Bijou Brigitte AG, Prada S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Luxury Goods Market Shifts & Advancements
Digital authentication technologies and circular service models are restructuring how scarcity and provenance are communicated to buyers, compressing the traditional gap between primary and secondary market trust infrastructure.
Blockchain-based digital product passports are electrifying provenance verification across high-value leather goods and mechanical watches. Collectors and resale platforms are adopting these credentials at accelerating velocity, compressing authentication timelines from weeks to minutes and enabling fractional ownership models previously impractical for physical luxury assets.
Germany's Supply Chain Due Diligence Act is mandating tier-two and tier-three labor audits for large luxury houses with domestic revenues exceeding four hundred million euros. The regulation is forcing restructuring of subcontractor relationships, with leather goods and jewelry segments most affected as they requalify Italian and French atelier networks under documented compliance protocols.
Buyers are unbundling after-sales service from initial purchase decisions, treating repair accessibility and refurbishment quality as independent evaluation criteria. This pattern is displacing traditional loyalty programs in metropolitan clusters, where specialized third-party restorers and authorized service centers now compete directly with brand-owned channels for recurring revenue.
Germany Luxury Goods Market Segmentation
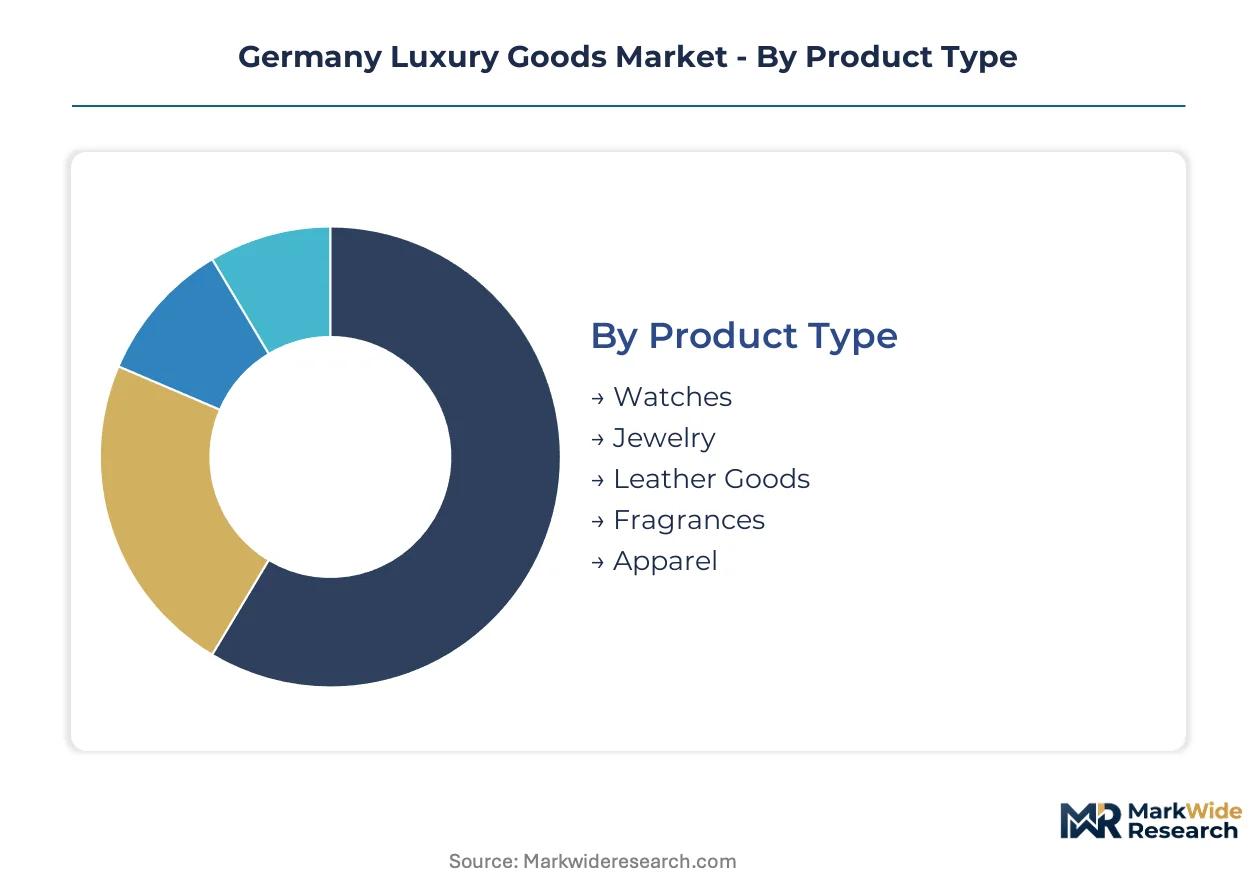
Segmentation in Germany luxury goods reveals how craftsmanship intensity, purchase occasion, and authentication complexity fragment demand across distinct commercial lanes. Each dimension carries divergent margin profiles and regulatory exposure, forcing heritage houses to configure atelier capacity and channel strategy around specific buyer archetypes rather than treating the market as monolithic.
Product Type:
The customization-vs-standardization spectrum runs from mechanically complex horology requiring artisan calibration to formula-stable fragrances amenable to automated production.
- Watches:Mechanical movements with hand-finished components dominate collector demand in Munich and Hamburg, where authentication services and resale value retention concentrate purchasing power among HNW individuals. KBA product safety protocols and REACH chemical restrictions on lubricants extend development cycles but deepen margin pools through authorized service ecosystems.
- Leather Goods:Hand-stitched articles utilizing exotic skins and full-grain calf leather anchor the deepest profitability tier, though CITES permitting delays and Supply Chain Due Diligence Act audit requirements compress gross margins on crocodile and python categories by fifteen to twenty-five percent.
- Jewelry:Precious metal and gemstone settings with blockchain-based provenance documentation satisfy EU Green Deal carbon disclosure mandates while enabling fractional ownership models previously impractical for physical assets.
- Fragrances:REACH restricted substance protocols for formulations extend product development timelines by eight to fourteen months, particularly affecting niche and artisanal sub-categories.
- Apparel:Technical innovation in performance-luxe fabrics drives adoption among automotive executives in Stuttgart and business professionals in Frankfurt, where same-day delivery infrastructure remains underdeveloped relative to purchasing power density.
Leather goods lead on scale; watches lead on momentum.
Distribution Channel:
Channel configuration maps directly onto authentication complexity and immediacy expectations, with high-value transactions requiring physical verification while routine replenishment migrates to digital-native platforms.
- Specialty Stores:Personalized styling and in-person authentication services dominate transaction value for ultra-premium and bespoke tiers, particularly in Berlin's Kurfürstendamm and Munich's Maximilianstrasse corridors where tourist and local HNW density converge.
- Online Platforms:Curated digital curation with localized warehousing in Bavaria and Baden-Württemberg is capturing share from traditional department store concessions, climbing the fastest among all channels as Gen Z and millennial buyers compress purchase cycles toward immediacy.
- Department Stores:Concession-based retail faces structural pressure from same-day delivery competitors and direct-to-consumer brand strategies, though remaining relevant for tourist segments seeking consolidated browsing experiences.
- Duty-Free:Airport-adjacent retail in Frankfurt and Munich depends on international travel recovery patterns and VAT refund processing efficiency for non-EU buyers.
- Boutique Outlets:Secondary-market and past-season inventory clearance channels serve price-sensitive aspirational buyers without cannibalizing full-price positioning in primary retail.
Specialty stores command value concentration; online platforms command growth velocity.
Customer Type:
Buyer archetypes segment by purchase frequency, authentication sophistication, and relationship to experiential versus transactional luxury consumption.
- Affluent Individuals:Sustained purchasing power in metropolitan clusters drives recurring revenue for repair-service ecosystems and bespoke commissioning, particularly among multigenerational wealth holders in Hamburg and Düsseldorf.
- Business Executives:Automotive and financial sector professionals in Stuttgart, Frankfurt, and Munich demonstrate underdeveloped ultra-premium retail presence relative to income levels, creating expansion opportunities for curated platforms with localized fulfillment.
- Collectors:Mechanical watch and exotic leather enthusiasts prioritize provenance documentation and resale value retention, adopting blockchain-based digital product passports at accelerating velocity to compress authentication timelines.
- Tourists:Non-EU visitors concentrate transaction activity in duty-free and flagship specialty store locations, with purchasing patterns sensitive to VAT refund processing efficiency and currency fluctuation exposure.
Affluent individuals anchor volume consistency; collectors anchor margin depth.
Price Tier:
Price stratification reflects gradations of scarcity positioning, craftsmanship intensity, and exclusivity signaling rather than mere material cost accumulation.
- Premium:Entry-luxury positioning with established brand recognition serves aspirational buyers transitioning from mass-premium alternatives, requiring differentiation through sustainability credentials and repair accessibility rather than rarity alone.
- Ultra-Premium:Limited production runs with documented artisan involvement dominate metropolitan cluster demand, where CSRD early compliance and supply chain transparency function as competitive differentiators for institutional procurement channels.
- Exclusive:Invitation-only access and waitlist management systems concentrate among mechanical watch and exotic leather categories, with Stuttgart and Nuremberg showing penetration gaps relative to HNW density.
- Bespoke:Fully customized commissioning with direct atelier relationships represents the smallest volume tier but deepest margin pool, constrained by master leatherworker and haute couture seamstress scarcity as apprenticeship pipelines fail to replenish retiring artisans.
Ultra-premium captures revenue concentration; bespoke captures pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master leatherworkers and haute couture seamstresses concentrate in southern German ateliers, anchoring craftsmanship-intensive production clusters that supply domestic and export demand. Their geographic proximity to automotive executive wealth pools creates natural market adjacencies for ultra-premium positioning.
Bavaria
Affluent millennials and Gen Z consumers in Munich drive experiential luxury adoption through pop-up atelier events and immersive brand storytelling. The KBA enforces strict product safety protocols for mechanical watch movements assembled in local workshops. Maximilianstrasse corridor hosts the densest concentration of specialty stores serving tourist and local HNW convergence.
Baden-Württemberg
Automotive executives in Stuttgart demonstrate underdeveloped ultra-premium retail presence relative to purchasing power density, creating expansion opportunities for curated digital platforms. Germany's Supply Chain Due Diligence Act obliges large houses to audit subcontractor labor practices across tier-two suppliers. Same-day delivery infrastructure with localized warehousing is capturing share from traditional department store concessions in secondary cities.
North Rhine-Westphalia
Multigenerational wealth holders in Düsseldorf sustain recurring revenue for repair-service ecosystems and bespoke commissioning. REACH restricted substance protocols for fragrance formulations extend product development timelines for regional perfume houses. The Rhine-Ruhr metropolitan cluster shows growing collector demand for blockchain-based provenance documentation in jewelry tiers.
Hamburg
HNW individuals concentrate purchasing power for mechanical watches with authentication services and resale value retention. EU Green Deal carbon disclosure requirements accelerate investment in traceable sourcing platforms among leather goods houses operating Elbe river logistics corridors. The city's tourism infrastructure supports duty-free transaction activity sensitive to VAT refund processing efficiency.
Berlin
Digital-native buyers compress purchase cycles toward immediacy expectations, forcing heritage houses to reconfigure atelier workflows. CSRD reporting thresholds position early compliance leaders for institutional procurement contracts and ESG-mandated wealth management channels. Kurfürstendamm retail corridors balance tourist footfall with local affluent individual demand for personalized styling services.
Germany Luxury Goods Market Competitive Landscape
Top-tier vendors anchor ultra-premium and bespoke tiers, while mid-scale houses compete through technical innovation and curated digital curation. The vendor base stratifies across integrated atelier networks, performance-luxe specialists, and platform-native distributors. Three archetypes dominate: heritage houses with vertical leather goods control, technical apparel innovators, and digital-first curators with localized fulfillment. Competitive intensity concentrates on M&A for artisan capacity and strategic partnerships for same-day delivery infrastructure.
Within the integrated heritage tier, LVMH Moët Hennessy Louis Vuitton and Richemont Group exemplify atelier-network control over scarcity positioning and craftsmanship authentication. Hugo Boss AG occupies a position among technical performance-luxe specialists targeting automotive and financial sector professionals. Mytheresa Group GmbH represents the digital-native curator archetype, leveraging localized warehousing to compress delivery timelines in underserved metropolitan clusters.
| Leading Market Players |
|---|
| Richemont Group |
| Burberry Group plc |
| LVMH Moët Hennessy Louis Vuitton |
| Mytheresa Group GmbH |
| Chanel S.A. |
| Kering S.A. |
| Hugo Boss AG |
| Bijou Brigitte AG |
| Prada S.p.A. |
| Others |
Supply & Pricing Matrix
Blockchain-based provenance verification systems are simultaneously elevating authentication costs and consolidating supplier power among tier-one tanneries capable of documenting farm-to-finish traceability. This technological shift compresses margin pools for mid-scale houses while deepening pricing power for integrated atelier networks with captive leather processing capacity.
Pricing Analysis
Service unbundling now separates initial purchase decisions from repair-accessibility evaluations, with buyers treating refurbishment quality as an independent criterion. Pricing stratifies across bespoke, ultra-premium, and premium tiers based on craftsmanship intensity and provenance documentation depth. Cost compression in exotic skin categories stems from CITES permitting delays and tier-three audit requirements under Germany's Supply Chain Due Diligence Act. Aspirational buyers entering through premium tiers exhibit highest price sensitivity, while collectors purchasing mechanical watches and bespoke leather goods demonstrate lowest elasticity.
Supply Chain Analysis
Germany's Supply Chain Due Diligence Act mandates documented labor audits across tier-two and tier-three suppliers, forcing restructuring of subcontractor relationships concentrated in Italian and French atelier networks. Raw material dependencies center on Tuscan calf leather processing, Swiss mechanical movements, and exotic skins sourced through CITES-regulated farms. Single-source vulnerability concentrates in premium leather finishing, where over sixty percent of processing sits within three Tuscan regions. Distribution runs through specialty store corridors in Munich and Berlin, supported by localized warehousing for same-day delivery in Bavaria and Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in German luxury goods rest on repair-service ecosystem development and ultra-premium tier penetration, with cost-down pressure from digital authentication infrastructure offsetting compliance investment burdens.
For Market Incumbents: Hedge against artisan skill scarcity by captive apprenticeship programs in southern German atelier clusters and backward integration into chrome-free tanning alternatives. Channel control through owned specialty retail in Stuttgart and Nuremberg corridors insulates against curated platform encroachment. Certification investment in CSRD early compliance positions houses for ESG-mandated wealth management procurement. For New Entrants and Emerging Players: Curated digital platforms with localized Bavarian warehousing offer the most penetrable entry vector, capturing automotive executive demand in underserved Stuttgart and Nuremberg clusters. White-space targets include same-day delivery infrastructure for secondary cities and fractional ownership models for blockchain-documented jewelry. Go-to-market execution should anchor on repair-service accessibility as a standalone purchase criterion rather than bundled loyalty programs. For Investors and Strategic Acquirers: Valuations sit cheapest among technical performance-luxe specialists with underdeveloped ultra-premium retail presence relative to executive purchasing power density. Long-term viability over the mid-decade window favors houses with integrated atelier networks and documented tier-three compliance under Germany's Supply Chain Due Diligence Act. Watch for inflection in institutional procurement contract flows toward CSRD early compliance leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Atelier Apprenticeship Expansion | Master leatherworker pipelines in Baden-Württemberg address retiring artisan scarcity. |
| Blockchain Provenance Deployment | Digital product passports compress authentication timelines for collector resale platforms. |
| Chrome-Free Tanning Transition | REACH compliance investments extend development cycles but deepen sustainability positioning. |
| Localized Warehousing Buildout | Bavarian fulfillment nodes enable same-day delivery capture of automotive executive demand. |
| CSRD Early Compliance | Documented carbon disclosure positions houses for ESG-mandated wealth management channels. |
Research Methodology
Bottom-up metropolitan cluster demand modeling reconciled against top-down atelier capacity tracking forms the analytical core of this study. Primary interviews with master leatherworkers, specialty store buyers, heritage house supply chain directors, and automotive executive procurement officers combined with secondary validation from KBA product safety filings, REACH substance restriction databases, EU Green Deal implementation guidance, and German customs trade records. Triangulation across these sources yields volume and value estimates calibrated to documented tier-two supplier audit disclosures under the Supply Chain Due Diligence Act.
Historical trendline analysis of leather goods pricing and mechanical watch transaction velocity informs projection frameworks across the analysis window. Segmentation dimensions modeled include product type craftsmanship intensity, distribution channel authentication complexity, buyer archetype purchase frequency, and price tier exclusivity positioning. CAGR derivation incorporates atelier capacity constraints, CITES permitting pipeline delays, and digital platform penetration curves in secondary metropolitan clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to artisan skill replenishment rates, greenwashing litigation exposure, and legacy ERP modernization disruption. Forecasts reflect assumptions around regulatory enforcement consistency, travel recovery patterns affecting duty-free corridors, and consumer protection authority scrutiny of carbon-neutral marketing claims. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Luxury Watches Market
Luxury Goods
United States Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
United States Secondhand Luxury Goods Market
Luxury Goods
Luxury Goods Market