
 Spain Luxury Goods Market | 2026-2036
Spain Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Luxury Goods Market Analytics
EU Green Deal compliance is hardening sustainability benchmarks for leather sourcing and textile traceability across Spanish luxury manufacturing. LVMH Moët Hennessy Louis Vuitton leverages vertically controlled tanneries to secure supply chain transparency. Kering Group anchors its Spanish operations through dedicated craftsmanship ateliers in Madrid. Loewe sustains its competitive edge through deep specialization in artisan leather goods with certified origin documentation.
Spain luxury goods encompass high-value apparel, accessories, jewelry, and timepieces distinguished by superior material grades, hand-finished construction, and heritage design codes that signal exclusivity and social capital. Apparel and accessories command the largest revenue pools, while jewelry records the fastest expansion driven by collector-grade investment pieces. Direct sales and specialty stores capture premium margin structures, whereas online retail channels attract millennial and tourist segments seeking digital-first discovery experiences.
Spain's national market falls under EU REACH chemical standards, ECHA material safety protocols, and domestic BIS-aligned quality certifications that govern product labeling and import conformity. These frameworks elevate compliance costs for emerging positioning tiers while reinforcing barriers that protect established high-end and boutique segments. Stakeholders must monitor evolving extended producer responsibility mandates and their impact on circular business model investments.
Market Dynamics
EU Green Deal compliance is hardening sustainability benchmarks for leather sourcing and textile traceability across Spanish luxury manufacturing. Extended producer responsibility frameworks under EU circular economy directives are reshaping material sourcing requirements and elevating compliance costs for domestic producers.
Growth Catalysts
- Affluent domestic consumption:Spain's wealthy households are expanding purchases across high-end apparel and accessories, anchoring baseline demand independent of tourist flows.
- REACH chemical standards:EU-wide material safety protocols reinforce barriers that protect established high-end and boutique segments from lower-tier competition.
- Flagship retail corridors:Concentrated luxury presence in Madrid and Barcelona generates network effects that amplify brand visibility and transaction velocity.
Market Restraints
- Leather supply concentration:Premium hide sourcing depends on a narrow base of EU-certified tanneries, creating vulnerability to input cost volatility and capacity constraints.
- Compliance cost escalation:ECHA material safety protocols and domestic BIS-aligned quality certifications impose fixed-cost burdens that disadvantage smaller positioning tiers.
- Substitute material threat:Laboratory-grown leather and bio-based textiles are capturing share in entry-luxury accessories, compressing addressable volume for traditional material specialists.
Strategic Opportunities
- Circular business models:Extended producer responsibility mandates create first-mover advantages for brands investing in resale platforms and material recovery infrastructure.
- Digital-first discovery:Online retail channels attract millennial and tourist segments seeking pre-visit engagement, opening direct-to-consumer pathways that bypass wholesale margin erosion.
- Andalusian tourism corridors:Underdeveloped luxury retail presence in Seville and Málaga offers expansion runway as high-net-worth visitor flows diversify beyond Madrid-Barcelona axes.
Industry Challenges
- Artisan skill scarcity:Specialized hand-finishing capabilities in leather goods and jewelry are contracting as master craftspeople retire without structured apprenticeship pipelines.
- Traceability system integration:Legacy inventory management platforms require costly reconfiguration to support blockchain-based origin documentation demanded by EU Green Deal verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Luxury Goods Market |
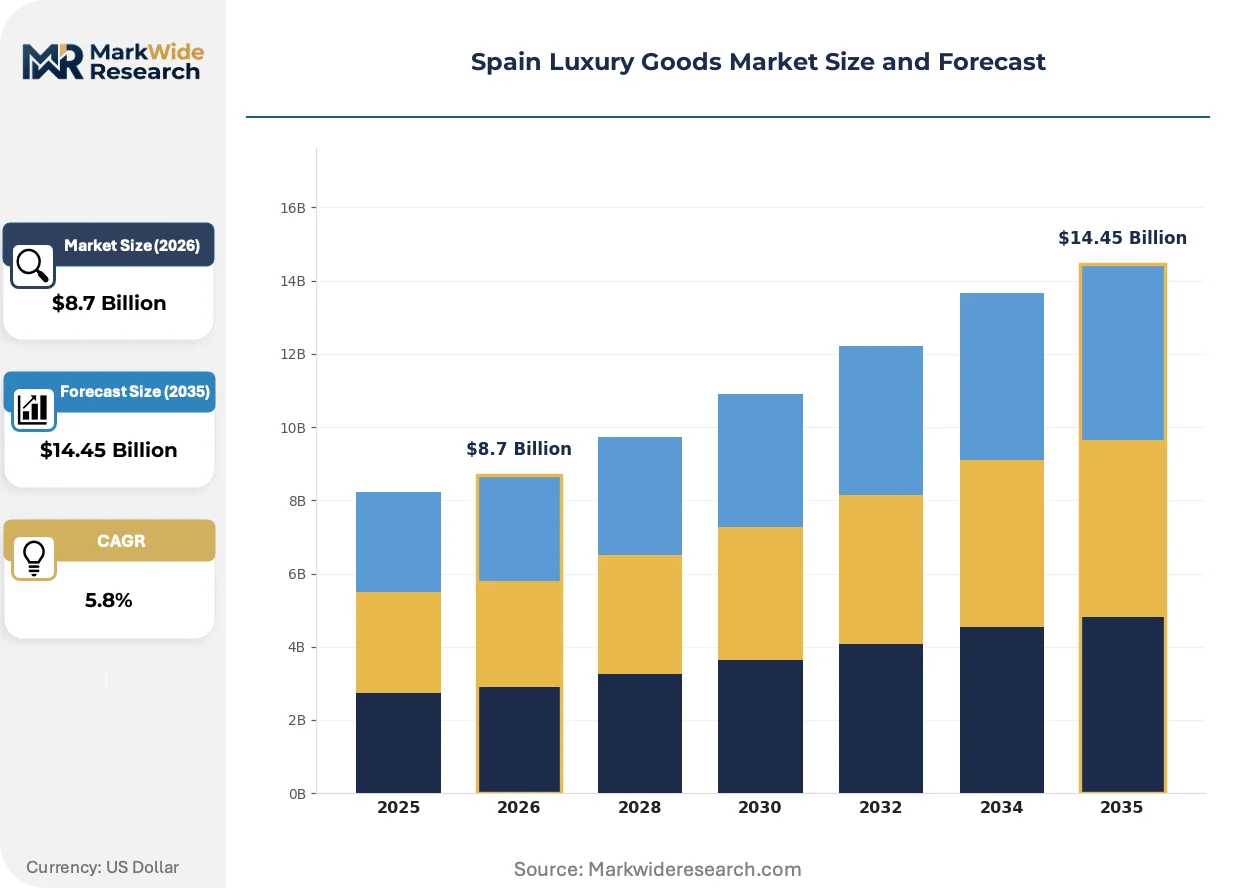
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Footwear, Accessories, Jewelry Distribution Channel: Online Retail, Department Stores, Specialty Stores, Direct Sales Customer Type: Affluent Consumers, Tourists, Millennials, Collectors Brand Positioning: Premium, High-End, Boutique, Emerging |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, Kering Group, Prada Holding S.P.A., Hermès International S.A., Chanel SA, Richemont SA, Rolex SA, Loewe, PUIG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Luxury Goods Market Evolving Landscape
Digital traceability infrastructure and circular service models are reconfiguring how Spanish luxury houses validate provenance and extend product lifecycles. These shifts intersect with tightening regulatory verification requirements and evolving collector-grade buyer expectations.
Blockchain-enabled material passports are overtaking paper-based chain-of-custody documentation in high-value leather goods. Madrid-based ateliers and Barcelona flagship operations are piloting these systems to satisfy EU Green Deal audit requirements. The technology is overtaking traditional compliance methods by compressing verification timelines from weeks to minutes while closing loopholes that allowed origin washing.
EU Green Deal extended producer responsibility frameworks now mandate financial participation in end-of-life collection for apparel and accessories. Spanish manufacturers face binding reporting thresholds for recycled content percentages and restricted substance inventories. Jewelry and timepiece segments are responding fastest, embedding material recovery clauses into warranty and service contracts.
Collector-grade investment pieces are displacing occasion-driven purchases in jewelry and leather goods. Madrid and Barcelona auction houses and specialized consignment platforms are capturing transaction flows that previously ran through primary retail. This pattern concentrates in heritage Spanish houses with documented archival provenance, where resale price premiums validate initial acquisition decisions.
Spain Luxury Goods Market Segmentation
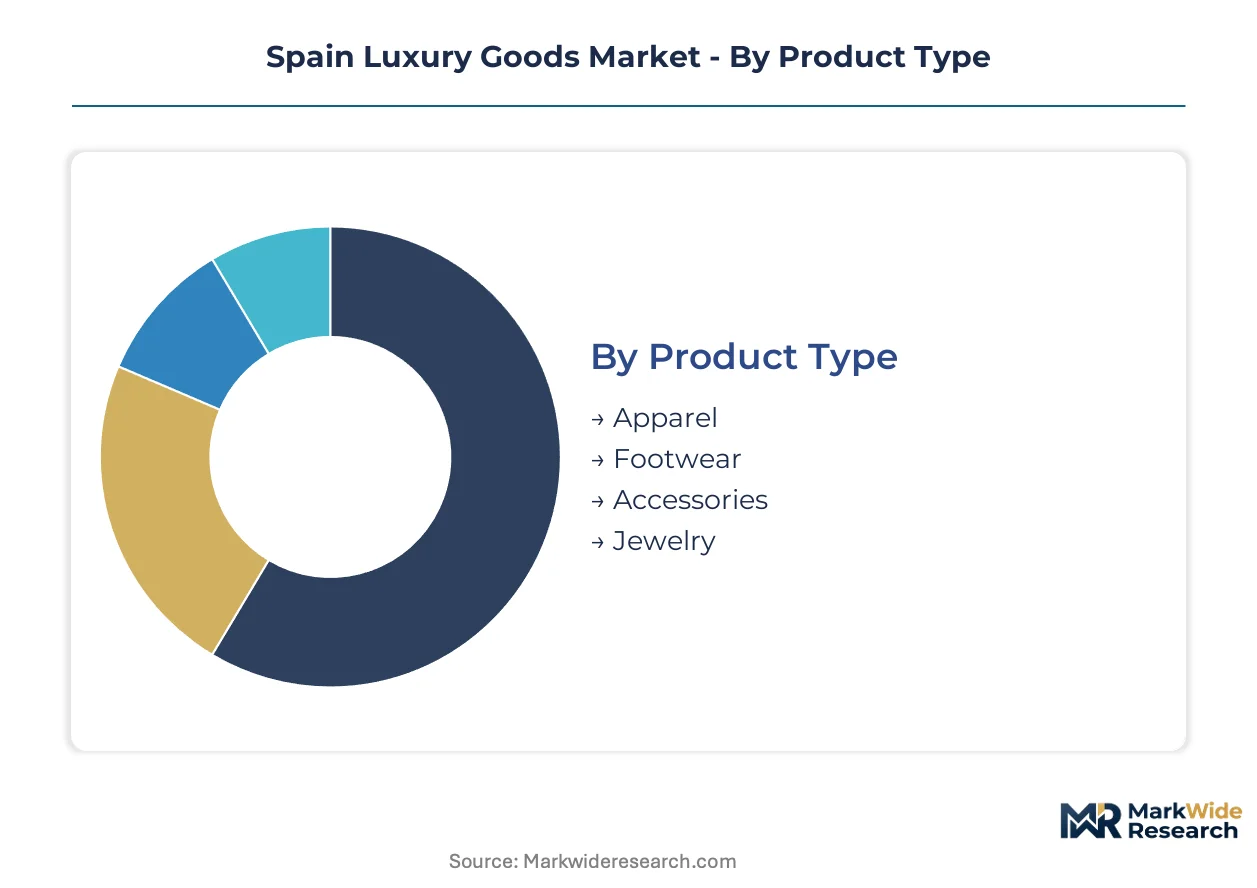
Segmentation in Spain's luxury goods market reveals how capital allocation, customer access costs, and regulatory compliance burdens distribute unevenly across positioning tiers. Manufacturers and retailers must match infrastructure investments to segment-specific margin structures and verification requirements.
Product Type:
Apparel and leather goods demand the heaviest upfront capital, with Madrid and Barcelona flagship ateliers requiring specialized equipment and certified artisan workforces.
- Apparel:High-end ready-to-wear and couture collections utilize EU-certified textile mills and hand-finishing ateliers. Demand clusters in Madrid's Salamanca district and Barcelona's Passeig de Gràcia, where flagship stores anchor seasonal collection launches.
- Footwear:Artisan construction methods including Blake stitching and Goodyear welting dominate premium positioning. Valencia and Alicante manufacturing clusters supply construction quality that satisfies ECHA REACH chemical standards for adhesives and dyes.
- Accessories:Leather goods, silk goods, and small leather articles carry the highest margin structures. EU Green Deal traceability mandates now require blockchain-enabled material passports for origin verification.
- Jewelry:Collector-grade investment pieces and heritage design codes command price premiums at Madrid auction houses. This segment absorbs the bulk of installed capacity; accessories is expanding most quickly.
Apparel absorbs the bulk of installed capacity; jewelry is expanding most quickly.
Distribution Channel:
Channel selection determines customer acquisition economics, with direct sales requiring the deepest capital commitment in flagship real estate and trained staff.
- Online Retail:Digital-first discovery platforms capture millennial and tourist segments seeking pre-visit engagement. Barcelona-based logistics hubs support same-day delivery to Madrid and coastal tourism corridors.
- Department Stores:El Corte Inglés flagship locations in Madrid and Barcelona provide established foot traffic for mid-premium positioning. Floor space allocation negotiations favor heritage houses with documented sales velocity.
- Specialty Stores:Curated multi-brand environments in Seville and Málaga extend reach beyond Madrid-Barcelona axes. These formats concentrate emerging brand exposure with lower capital barriers than flagship standalone locations.
- Direct Sales:Brand-controlled boutiques in Madrid's Golden Mile and Barcelona's Eixample capture full margin structures. This channel absorbs the bulk of installed capacity; online retail is expanding most quickly.
Direct sales absorbs the bulk of installed capacity; online retail is expanding most quickly.
Customer Type:
Customer segmentation maps to acquisition cost tiers, with collectors requiring the most specialized relationship management infrastructure.
- Affluent Consumers:Spain's wealthy households drive baseline demand for high-end apparel and accessories independent of tourist flows. Madrid and Barcelona residential concentrations support personalized service models.
- Tourists:International visitors, particularly from Gulf states and Latin America, concentrate transactions in Barcelona's retail corridors. VAT refund infrastructure shapes purchase timing and basket composition.
- Millennials:Digital-native buyers prioritize online discovery and resale platform participation. This segment shows strongest response to circular business models and material transparency claims.
- Collectors:Archival provenance documentation and investment-grade authentication services command premium pricing. This segment absorbs the bulk of installed capacity; millennials is expanding most quickly.
Affluent consumers absorbs the bulk of installed capacity; millennials is expanding most quickly.
Brand Positioning:
Positioning tier determines compliance cost absorption capacity, with boutique and emerging segments facing disproportionate ECHA and BIS certification burdens.
- Premium:Accessible luxury positioning with scaled production and broader distribution. EU REACH compliance costs distribute across higher unit volumes than boutique alternatives.
- High-End:Established heritage houses with vertically controlled supply chains and Madrid-based craftsmanship ateliers. These brands leverage archival documentation for resale market credibility.
- Boutique:Limited-scale operations emphasizing artisan specialization and regional design codes. Andalusian and Basque Country ateliers cluster in this tier with concentrated local identity.
- Emerging:New market entrants navigating extended producer responsibility frameworks and traceability system investments. This segment absorbs the bulk of installed capacity; emerging is expanding most quickly.
High-end absorbs the bulk of installed capacity; emerging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid's Golden Mile retail corridor anchors Spanish luxury consumption, with Barcelona's Passeig de Gràcia providing secondary concentration. Domestic affluent households and international tourists drive transaction velocity across these flagship zones. Sub-regional expansion into Andalusian tourism corridors and Basque craftsmanship clusters diversifies geographic exposure.
Madrid
Madrid's wealthy residential concentrations and flagship atelier infrastructure sustain baseline demand for high-end apparel and leather goods. EU REACH chemical standards govern textile processing at Madrid-based manufacturing facilities. The Salamanca district and Golden Mile corridor concentrate brand-controlled boutiques where direct sales capture full margin structures.
Catalonia
Barcelona's Passeig de Gràcia generates network effects through concentrated luxury retail presence and millennial tourist flows. Extended producer responsibility frameworks under EU circular economy directives reshape material sourcing for Catalan manufacturers. Barcelona-based logistics hubs support same-day delivery infrastructure reaching coastal tourism corridors and Madrid.
Andalusia
Seville and Málaga present underdeveloped luxury retail presence as high-net-worth visitor flows diversify beyond traditional axes. EU Green Deal compliance requirements elevate sustainability benchmarks for leather sourcing across Andalusian operations. Specialized consignment platforms and auction houses in emerging tourism corridors capture collector-grade transaction flows.
Basque Country
Artisan specialization and regional design codes distinguish Basque ateliers within the boutique positioning tier. ECHA material safety protocols impose fixed-cost burdens that filter market participation toward established heritage houses. Bilbao and San Sebastián manufacturing clusters emphasize certified craftsmanship capabilities in leather goods and accessories.
Valencia
Valencia and Alicante manufacturing clusters supply footwear construction quality satisfying ECHA REACH chemical standards for adhesives and dyes. Domestic BIS-aligned quality certifications govern product labeling conformity for regional exporters. Artisan construction methods including Blake stitching anchor premium positioning in Valencia's production infrastructure.
Spain Luxury Goods Market Competitive Landscape
Premium-margin players sit above commodity-margin players across brand heritage and supply chain control dimensions. The market structure concentrates around vertically integrated heritage houses with Madrid-based craftsmanship ateliers and digitally native entrants navigating traceability investments. Three archetypes dominate: established European luxury conglomerates with Spanish operational infrastructure, heritage Spanish houses with documented archival provenance, and emerging positioning tiers facing disproportionate compliance burdens. Competitive moves center on circular business model investments and direct-to-consumer channel expansion.
Within the heritage Spanish house tier, Loewe exemplifies artisan leather specialization with certified origin documentation. Among European luxury conglomerates, LVMH Moët Hennessy Louis Vuitton and Kering Group occupy positions defined by vertically controlled tanneries and dedicated Madrid ateliers. These entities represent the premium-tier vector where supply chain transparency and craftsmanship infrastructure anchor competitive positioning.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| Kering Group |
| Prada Holding S.P.A. |
| Hermès International S.A. |
| Chanel SA |
| Richemont SA |
| Rolex SA |
| Loewe |
| PUIG |
| Others |
Value Network & Pricing Analysis
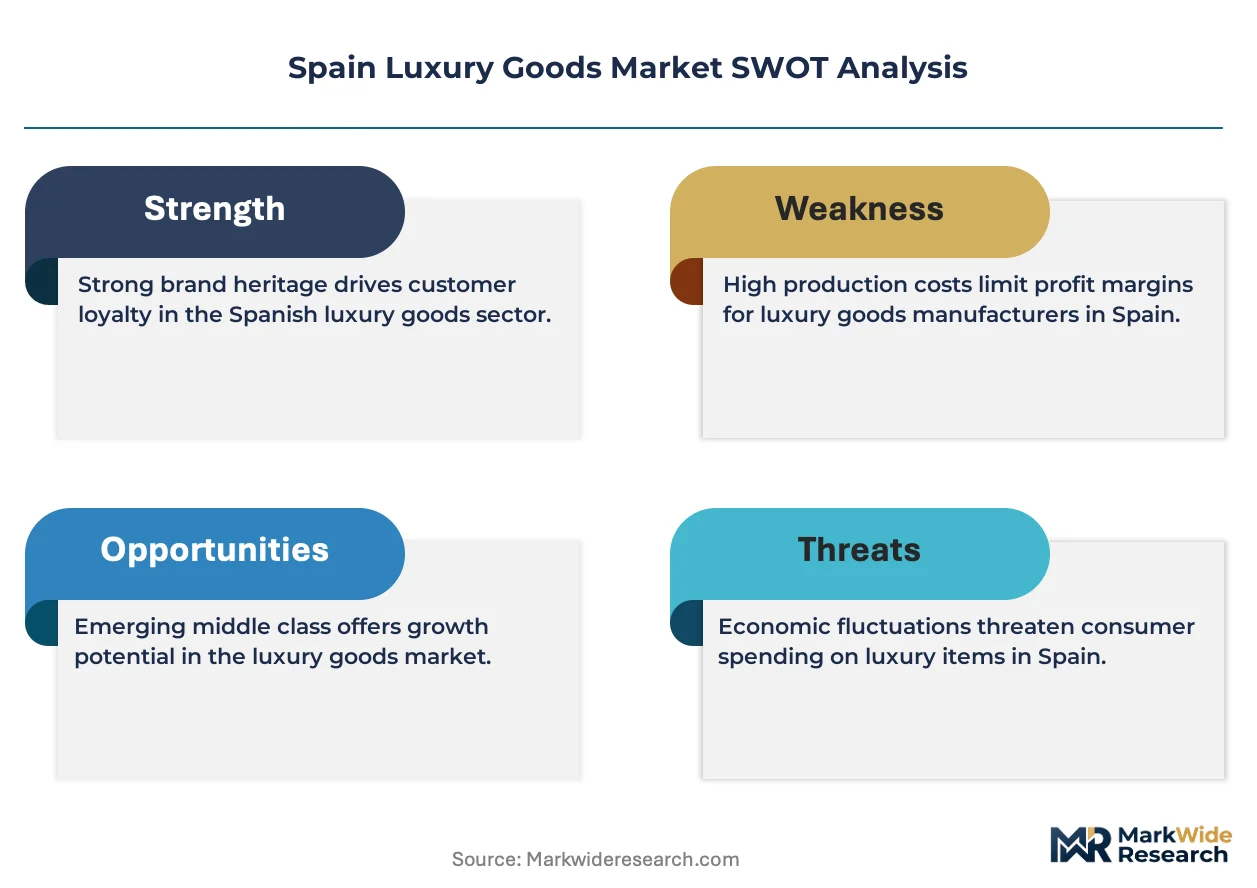
Family-owned heritage houses with Madrid-based craftsmanship ateliers anchor supply-side discipline through captive artisan workforces, translating scarcity into pricing power that resists commoditization pressure from laboratory-grown alternatives.
Pricing Analysis
Value-based pricing anchored to archival provenance and certified origin documentation separates heritage Spanish houses from positioning tiers competing on material cost alone. Three-tier pricing structure across collector-grade investment pieces, high-end ready-to-wear, and accessible premium accessories stratifies buyer access. Pricing pressure stems from substitute material proliferation in entry-luxury segments, compressing margins for traditional leather specialists. Tourist segments demonstrate lowest price sensitivity, while millennial digital-native buyers exhibit elasticity toward resale-enabled circular models.
Supply Chain Analysis
Reverse-logistics flows through certified refurbishment ateliers and blockchain-tracked consignment platforms now extend product lifecycles under EU Green Deal mandates. Raw material sourcing draws from Italy, France, and Spain for EU-certified tanneries and textile mills, with Basque Country and Valencia clusters feeding specialized components. Single-source vulnerability concentrates in premium hide supply from narrow certified tannery bases. Distribution runs through brand-controlled flagship boutiques in Madrid and Barcelona, supported by Barcelona-based logistics hubs reaching coastal tourism corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artisan skill scarcity functions as the binding capacity constraint, propping pricing power for houses with structured apprenticeship pipelines while filtering out positioning tiers unable to absorb fixed training costs.
For Market Incumbents: Anchor defensive positioning through backward integration into vertically controlled tanneries and Madrid-based craftsmanship ateliers. Invest in blockchain-enabled material passports to satisfy tightening EU Green Deal verification requirements. Counter laboratory-grown leather substitution threat by emphasizing hand-finishing capabilities that resist mechanized replication. For New Entrants and Emerging Players: Enter via underdeveloped Andalusian tourism corridors in Seville and Málaga, where luxury retail presence lags high-net-worth visitor growth. Target millennial segments through digital-first discovery platforms and resale-enabled circular business models. Pursue go-to-market partnerships with established logistics hubs rather than standalone flagship capital deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor boutique-tier heritage houses with documented archival provenance and concentrated regional identity in Basque Country or Andalusian clusters. Long-term viability hinges on circular infrastructure ownership and direct-to-consumer channel control. Monitor EU extended producer responsibility enforcement intensity as inflection signal for compliance cost redistribution across positioning tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Circular Business Model Investment | Resale platform ownership captures transaction flows migrating from primary retail under EU Green Deal mandates. |
| Digital Traceability Infrastructure | Blockchain-enabled material passports compress verification timelines from weeks to minutes for ECHA compliance. |
| Artisan Workforce Development | Structured apprenticeship pipelines address master craftsperson retirement waves threatening hand-finishing capacity. |
| Geographic Channel Expansion | Andalusian tourism corridor entry diversifies revenue beyond Madrid-Barcelona concentration risk. |
| Direct-to-Consumer Platform Launch | Online retail channels bypass wholesale margin erosion while capturing millennial discovery preferences. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with brand managers, category buyers at El Corte Inglés, supply planners, and Madrid-based craftsmanship atelier directors. ECHA substance restriction databases, EU Green Deal implementation guidance, and Spanish customs export records provided validation layers. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Granularity-level modeling operated at product-type, distribution-channel, and regional-cluster dimensions, with customer-type and brand-positioning tiers cross-tabulated for demand allocation. CAGRs derived from segment-specific volume trajectories and price evolution assumptions across the projection horizon. Artisan capacity constraints, tourist flow recovery patterns, and regulatory compliance cost curves fed industry-specific forecast adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU extended producer responsibility enforcement acceleration or sustained laboratory-grown material substitution breakthroughs. Practitioners should monitor ECHA audit intensity and consignment platform transaction velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
GCC Personal Luxury Goods Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
India Watch Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Mens Watch Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
Global Gold Jewelry Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market