
 Luxury Goods Market | 2026-2036
Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Goods Market Analysis
The capital-intensity divergence between vertically integrated leather-goods specialists and asset-light licensed fragrance operators is rotating competitive advantage toward in-house tanneries and atelier networks. Hermès International SCA anchors its position through captive crocodile farms and saddle-stitch craftsmanship that defy mechanization. Kering SA leverages decentralized brand autonomy to sustain margin discipline across Gucci, Saint Laurent, and Bottega Veneta. Chanel controls distribution through exclusive boutique networks that limit wholesale exposure and preserve pricing power.
Luxury goods encompass tangible products commanding price premiums through scarcity, artisanal provenance, and symbolic status attribution rather than utilitarian function alone; specifications include hand-finished construction, precious metal content verified by assay, and limited-batch production runs below industrial scale. Fine Jewelry occupies the highest margin pool per unit, driven by gemstone provenance documentation and bespoke commission workflows. Fashion Apparel competes on seasonal narrative velocity, with ready-to-wear cycles compressing from biannual to monthly drops. Accessories dominates volume contribution through leather goods and silk products with repeatable silhouettes and lower size-risk than apparel.
The EU Green Deal and CSRD compel Paris and Milan-based houses to map Scope 3 emissions across Italian tanneries and French embroidery ateliers, reshaping supplier qualification criteria. REACH chemical restrictions and ECHA substance-of-very-high-concern listings limit chrome-tanning alternatives and dye formulations, elevating compliance costs for entry-tier accessible luxury players. China's SAMR anti-counterfeiting enforcement and cross-border e-commerce tax rules determine market access velocity for direct-to-consumer digital channels. Stakeholders must monitor whether regulatory fragmentation between Brussels sustainability mandates and Beijing consumption stimulus creates divergent product-line requirements that fragment global assortment planning.
Market Dynamics
The EU Green Deal and CSRD reporting mandates are forcing Paris and Milan-based houses to reconfigure supply chain transparency, while Asia-Pacific collectors drive demand concentration toward rare timepieces and haute couture acquisition.
Growth Catalysts
- Regulatory Transparency Mandates:The EU Green Deal compels European houses to document Scope 3 emissions across Italian tanneries and French embroidery ateliers, creating competitive differentiation for early adopters of supply chain traceability.
- Asia-Pacific Collector Demand:Ultra-high-net-worth individuals in Shanghai, Tokyo, and Singapore are expanding acquisition of rare timepieces and heritage maison products, outpacing outbound luxury tourism spending from China's tier-one cities.
- Artisanal Craft Preservation:Captive crocodile farms and saddle-stitch craftsmanship that defy mechanization are anchoring margin pools for vertically integrated leather-goods specialists against asset-light licensed operators.
Market Restraints
- Input Cost Volatility:REACH chemical restrictions and ECHA substance-of-very-high-concern listings limit chrome-tanning alternatives and dye formulations, elevating compliance costs for entry-tier accessible luxury players dependent on industrial-scale production.
- Supply Concentration Risk:Italian tanneries and French embroidery ateliers represent concentrated artisanal capacity; disruption to these geographic clusters fragments production timelines for houses lacking backward integration into captive supply networks.
- Regulatory Fragmentation:Divergent requirements between Brussels sustainability mandates and Beijing consumption stimulus through SAMR anti-counterfeiting enforcement create conflicting product-line specifications that complicate global assortment planning.
Strategic Opportunities
- Underpenetrated Digital Channels:China's SAMR cross-border e-commerce tax rules are reshaping market access velocity for direct-to-consumer platforms, creating white space for houses that master domestic digital distribution in tier-one cities.
- Heritage Provenance Documentation:Gemstone origin verification and bespoke commission workflows in Fine Jewelry represent margin expansion potential through technology convergence of blockchain traceability and artisanal authentication protocols.
- Circular Economy Incentives:EU Green Deal circularity provisions and extended producer responsibility frameworks create regulatory tailwinds for resale authentication services and refurbishment atelier networks.
Industry Challenges
- Artisanal Skill Scarcity:Saddle-stitch craftsmanship and hand-finishing techniques require decade-long training pipelines; demographic contraction in French and Italian atelier networks threatens production capacity for heritage construction methods.
- Certification Timeline Compression:ECHA substance-of-very-high-concern listings and REACH chemical restrictions demand accelerated reformulation cycles for dye and tanning processes, straining R&D bandwidth at mid-scale houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Goods Market |
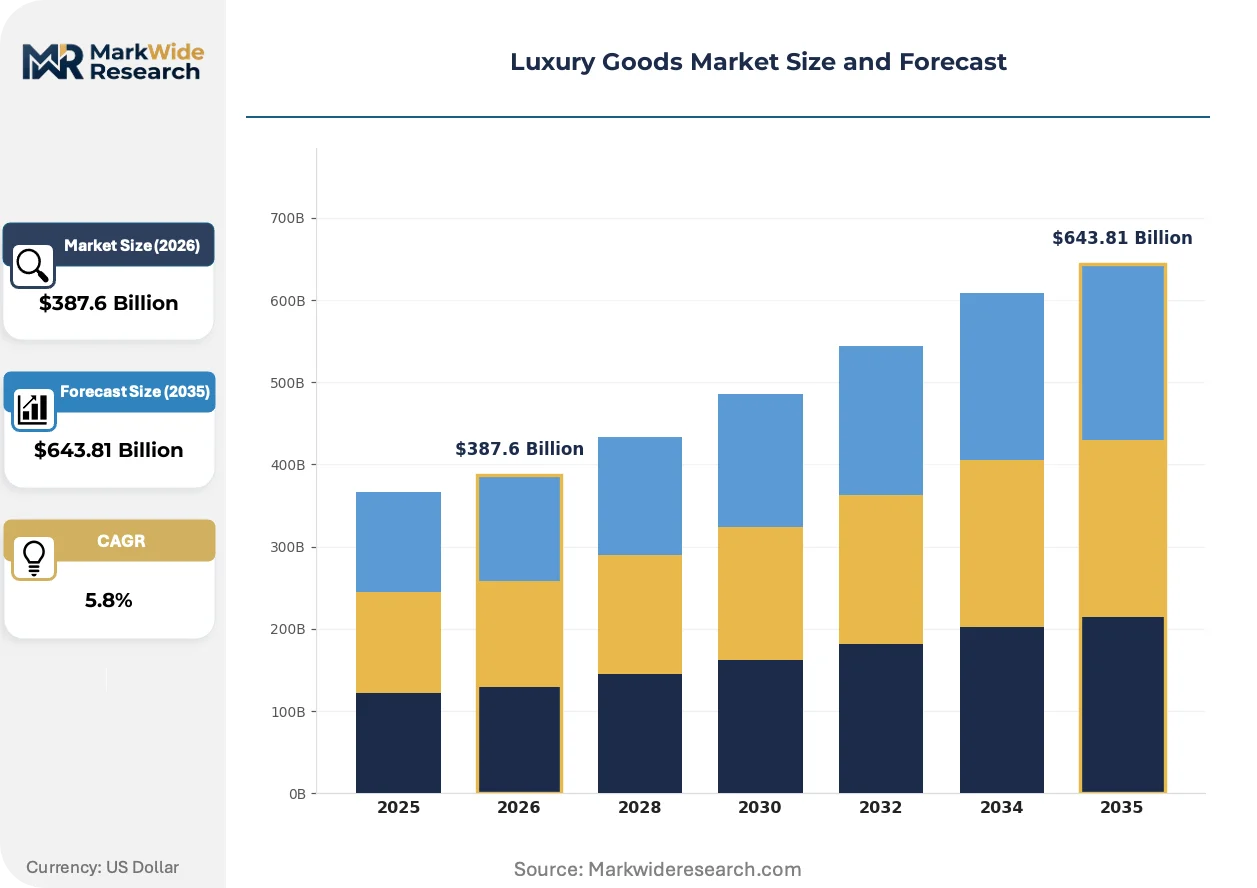
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion Apparel, Accessories, Footwear, Fine Jewelry Customer Type: High Net Worth Individuals, Millennials, Celebrities, Collectors Distribution Channel: Luxury Retailers, E-commerce, Department Stores, Exclusive Boutiques Price Tier: Premium, Ultra-Premium, Accessible Luxury, Heritage Brands |
| Companies Covered | Kering SA, Louis Vuitton, LVMH Moët Hennessy - Louis Vuitton, SE, Cartier, Rolex, Hermès International SCA, Christian Dior SE, Porsche, Chanel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Goods Market Emerging Trajectories
Digital authentication protocols and circular service models are restructuring how provenance is verified and value is captured across the ownership lifecycle, compressing traditional resale channel margins.
Blockchain-based gemstone provenance documentation is supplanting paper-based certificate workflows in Fine Jewelry. High-value collectors in Geneva and Hong Kong are demanding immutable origin records for colored stones and cultured pearls. This technology is compressing due-diligence timelines for auction houses while elevating compliance standards for conflict-mineral screening.
CSRD sustainability disclosure requirements are mandating granular Scope 3 emissions mapping across European luxury supply chains. Italian tanneries must now document energy consumption and chemical inputs for leather destined for Paris-based houses. Fine Jewelry and Fashion Apparel segments face the steepest compliance ramps, with smaller maisons accelerating partnerships with third-party verification platforms.
Collector behavior is pivoting toward domestic heritage maison consumption over outbound luxury tourism spending. China's tier-one cities—Shanghai, Beijing, Shenzhen—are seeing boutique network expansion replace airport retail dependence. This geographic demand rotation is forcing wholesale channel reconfiguration and exclusive distribution investments that limit parallel import exposure.
Luxury Goods Market Segmentation

Segmentation in luxury goods separates volume-driven accessible categories from scarcity-driven collector markets. Product construction methods and distribution control determine margin capture across each divide.
Product Type:
Fashion Apparel and Accessories concentrate demand in China's tier-one cities, while Fine Jewelry and Footwear retain stronger export-led dynamics toward Geneva and Hong Kong auction circuits.
- Fashion Apparel:Seasonal narrative velocity drives ready-to-wear cycles compressing from biannual to monthly drops. Shanghai and Beijing now outpace outbound luxury tourism spending for heritage maison consumption, forcing wholesale channel reconfiguration.
- Accessories:Leather goods and silk products with repeatable silhouettes dominate volume contribution through lower size-risk than apparel. Italian tanneries and French embroidery ateliers supply concentrated artisanal capacity that fragments timelines for houses lacking backward integration.
- Footwear:Industrial-scale production competes with hand-lasted construction for limited editions; sneaker drops and formal leather command divergent supply chains.
- Fine Jewelry:Gemstone provenance documentation and bespoke commission workflows occupy the highest margin pool per unit.
Accessories holds the largest share; momentum sits with Fine Jewelry.
Customer Type:
Collector and celebrity demand concentrates acquisition in rare timepieces and haute couture, while millennial and accessible HNI segments drive digital channel velocity.
- High Net Worth Individuals:Ultra-high-net-worth collectors in Singapore and Tokyo expand acquisition of heritage maison products. SAMR cross-border e-commerce tax rules reshape market access velocity for this segment's direct-to-consumer platforms.
- Millennials:Domestic consumption in China's tier-one cities now outpaces outbound luxury tourism spending; this cohort forces boutique network expansion over airport retail dependence.
- Celebrities:Red carpet placement and brand ambassadorship drive seasonal narrative velocity for fashion apparel drops.
- Collectors:Geneva and Hong Kong auction circuits demand immutable blockchain origin records for colored stones and cultured pearls.
High Net Worth Individuals anchor revenue concentration; millennials are expanding most quickly through digital channels.
Distribution Channel:
Exclusive boutiques and e-commerce are gaining share fastest as department stores and traditional luxury retailers face channel compression.
- Luxury Retailers:Multi-brand doors face margin pressure from exclusive distribution investments that limit parallel import exposure.
- E-commerce:China's SAMR anti-counterfeiting enforcement and cross-border tax rules determine market access velocity; tier-one city digital mastery creates white space for houses controlling domestic distribution.
- Department Stores:Wholesale exposure erodes pricing power; Paris and Milan-based houses reduce reliance on this channel.
- Exclusive Boutiques:Controlled distribution networks preserve margin discipline through limited wholesale exposure and geographic exclusivity.
Exclusive boutiques command the steepest margin expansion; e-commerce shows the steepest trajectory.
Price Tier:
Ultra-premium and heritage brand segments concentrate in European atelier networks, while accessible luxury faces REACH chemical restriction cost elevation.
- Premium:Mid-tier positioning competes on seasonal narrative velocity without captive supply chain control.
- Ultra-Premium:Rare timepieces and haute couture acquisition by Asia-Pacific collectors drives demand concentration; decade-long training pipelines for saddle-stitch craftsmanship constrain supply.
- Accessible Luxury:ECHA substance-of-very-high-concern listings and REACH chemical restrictions elevate compliance costs for industrial-scale production dependent on chrome-tanning alternatives.
- Heritage Brands:Captive crocodile farms and defiance of mechanization anchor margin pools against asset-light licensed operators.
Heritage brands command pricing power; ultra-premium is gaining share fastest among collector cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: Chinese collectors absorb ultra-premium markups with minimal volume sensitivity, while accessible luxury segments in Western Europe face demand compression from inflationary pressure and sustainability compliance costs.
France
Paris-based heritage maisons anchor global pricing power through exclusive boutique networks and captive atelier capacity. The EU Green Deal and CSRD reporting mandates compel houses to document Scope 3 emissions across French embroidery workshops and subcontractor networks. Lyon and Paris cluster the densest concentration of hand-finishing ateliers, where demographic contraction in artisanal labor pools threatens production timelines for saddle-stitch and haute couture construction.
Italy
Milan and Florence concentrate leather-goods demand from Asia-Pacific collectors seeking provenance-verified accessories. REACH chemical restrictions and ECHA substance-of-very-high-concern listings limit chrome-tanning alternatives, elevating compliance costs for Tuscan tanneries supplying Paris-based houses. The Veneto and Tuscany regions host concentrated artisanal capacity that fragments production timelines for brands lacking backward integration into captive supply networks.
China
Shanghai, Beijing, and Shenzhen now outpace outbound luxury tourism spending for heritage maison consumption. SAMR anti-counterfeiting enforcement and cross-border e-commerce tax rules reshape market access velocity for direct-to-consumer digital channels. Hainan duty-free zones and tier-one city boutique expansion replace airport retail dependence as the primary demand capture mechanism.
Switzerland
Geneva anchors rare timepiece acquisition from ultra-high-net-worth collectors in Singapore and Hong Kong. Swissmedic and federal hallmarking standards enforce precious metal content verification that underpins auction-house confidence. The Jura Arc and Geneva cluster represent concentrated mechanical watchmaking capacity where decade-long training pipelines constrain supply expansion for haute horlogerie complications.
United States
New York and Los Angeles concentrate celebrity-driven seasonal narrative velocity for fashion apparel drops. FTC guidelines on green marketing claims and state-level extended producer responsibility frameworks create compliance complexity for resale authentication services. Miami and Aspen serve as secondary collector markets where domestic consumption of heritage maison products accelerates through private clienteling events.
Luxury Goods Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage rotating toward in-house tanneries and atelier networks that defy mechanization. The structure concentrates margin capture among vertically integrated leather-goods specialists, while asset-light licensed fragrance operators face compression. Three archetypes dominate: heritage houses with captive supply chains, decentralized brand conglomerates sustaining margin discipline through autonomous creative direction, and exclusive distribution players limiting wholesale exposure. M&A activity targets atelier network acquisition and digital authentication platform integration.
Within the integrated heritage tier, Hermès International SCA and Chanel exemplify pricing power anchored by captive production capacity and controlled distribution. Kering SA occupies a position representing decentralized brand autonomy across multiple creative houses. These three entities illustrate how competitive positioning separates vertically integrated specialists from asset-light operators dependent on licensed production and wholesale channels.
| Leading Market Players |
|---|
| Kering SA |
| Louis Vuitton |
| LVMH Moët Hennessy - Louis Vuitton, SE |
| Cartier |
| Rolex |
| Hermès International SCA |
| Christian Dior SE |
| Porsche |
| Chanel |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with Italian tanneries and French embroidery ateliers lock in multi-year supply access for Paris-based heritage houses while anchoring price visibility against REACH chemical restriction cost volatility. These arrangements bind ultra-premium tier producers to geographic clusters where artisanal skill scarcity limits expansion, transmitting supply concentration directly into pricing power for captive supply network operators.
Pricing Analysis
After-sales revenue from authentication services and refurbishment atelier networks drives lifetime value capture beyond initial transaction margins. Three-tier pricing structure across heritage, ultra-premium, and accessible luxury levels stratifies by captive supply chain control and provenance documentation depth. Cost compression in accessible luxury intensifies because ECHA substance-of-very-high-concern listings accelerate dye reformulation cycles. Accessible luxury segments exhibit highest price sensitivity; heritage brand collectors absorb markups with minimal volume response.
Supply Chain Analysis
Inbound logistics costs from Geneva and Hong Kong auction circuits to Asia-Pacific collector destinations hinge on secure transport protocols for high-value timepieces and gemstones. Supply concentrates in France, Italy, and Switzerland, drawing from crocodile farms, Tuscan tanneries, and Jura Arc watchmaking clusters. Raw material dependencies span precious metals, exotic leathers, and colored gemstones. Single-source vulnerability in French embroidery ateliers threatens production timelines. Distribution runs through exclusive boutique networks that limit parallel import exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where blockchain provenance documentation and circular service models restructure value capture across ownership lifecycles, interoperability between digital authentication protocols and resale marketplaces redefining competitive moats.
For Market Incumbents: Secure captive atelier capacity through decade-long training pipeline investments and exclusive supplier contracts before demographic contraction in French and Italian artisanal labor pools deepens. Defend margin position by accelerating CSRD compliance documentation ahead of smaller competitors, converting regulatory burden into differentiation. Channel control through boutique network expansion in China's tier-one cities limits wholesale exposure erosion from SAMR cross-border e-commerce rule changes. For New Entrants and Emerging Players: Differentiate on circular economy service integration, targeting resale authentication and refurbishment workflows where heritage houses remain underinvested. White space concentrates in digital-native provenance platforms for mid-tier colored stones and accessible leather goods. Penetrate China's tier-one cities through domestic e-commerce mastery rather than airport retail dependence. Go-to-market leverage rests on SAMR anti-counterfeiting compliance as table stakes for platform credibility. For Investors and Strategic Acquirers: Specialist atelier networks with backward integration into raw material sourcing represent priority acquisition archetypes, their scarcity value compounding as REACH restrictions elevate compliance barriers. Long-term viability favors vertically integrated operators with decade-plus artisanal training infrastructures over asset-light licensed fragrance models. Signal to monitor: ECHA substance-of-very-high-concern listing velocity for chrome-tanning alternatives, which would accelerate consolidation pressure on mid-scale houses.| Strategic Initiative | Industry Significance |
|---|---|
| Atelier Network Acquisition | Captive supply capacity in Lyon and Florence clusters locks in heritage construction methods against labor pool contraction. |
| Blockchain Provenance Integration | Immutable origin records for Geneva and Hong Kong auction circuits compress due-diligence timelines while elevating compliance standards. |
| Circular Service Launch | EU Green Deal extended producer responsibility frameworks create regulatory tailwinds for resale authentication revenue streams. |
| Boutique Expansion in Tier-One Cities | Shanghai and Beijing domestic consumption growth replaces airport retail dependence as primary demand capture mechanism. |
| CSRD Compliance Acceleration | Early Scope 3 emissions documentation across Italian tanneries converts regulatory mandate into competitive differentiation. |
Methodological Framework
A spread of perspectives from creative directors at heritage maisons, supply chain heads at leather-goods specialists, procurement leads at Tuscan tanneries, and digital platform strategists converged on the working assumptions underpinning demand forecasts. Primary fieldwork with these stakeholders combined with secondary validation from customs records, auction house transaction databases, SEC filings for listed luxury conglomerates, and EU regulatory disclosure filings. Bottom-up product-line buildups and top-down macroeconomic scenario triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product type, customer archetype, distribution channel, and price tier across the analysis window. The analytical framework projected growth trajectories by calibrating collector behavior shifts, regulatory compliance cost pass-through rates, and digital channel penetration curves. CAGRs derived from trend extrapolation adjusted for supply-side constraints in atelier capacity and raw material availability. Industry-specific inputs included artisanal labor pool demographics and SAMR cross-border e-commerce rule implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained Asia-Pacific collector demand concentration, stable REACH chemical restriction enforcement, and intact EU Green Deal circularity provisions would require recalibration. Forecasts reflect documented assumptions about supply chain transparency investment rates and blockchain provenance adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
China Luxury Market
Luxury Goods
Malaysia Luxury Goods Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
India Watch Market
Luxury Goods
Thailand Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Watch Winder Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
GCC Personal Luxury Goods Market