
 North America Footwear Market | 2026-2036
North America Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Footwear Market Analytics
Buyer concentration across North American athletic retail is rebalancing as specialty fitness studios and direct-to-consumer platforms fragment demand away from traditional department store gatekeepers. Nike, Inc. leverages vertical integration in foam midsole chemistry to control performance-tier supply chains. Skechers USA, Inc. anchors its position through volume-scale casual comfort distribution across big-box retail. New Balance, Inc. differentiates via domestic manufacturing capacity in Massachusetts and Maine facilities.
Footwear encompasses engineered protective and fashion apparel for the human foot, constructed through injection-molded EVA midsoles, cemented or stitch-down outsole attachment, and upper materials ranging from full-grain leather to knitted polyester engineered mesh, serving functions from impact attenuation in sport to occupational safety compliance. The sneakers category leads volume throughput as athleisure permeates workplace dress codes, while the leather material segment commands premium margin pools in formal and heritage work-boot applications. Online distribution channels are capturing fastest growth as augmented-reality sizing tools reduce fit-related return rates.
The US Federal Trade Commission polishes marketing claims through its Green Guides, while OSHA maintains workplace safety boot standards that shape industrial procurement specifications across manufacturing and construction sectors. California's SB 657 transparency regulations compel supply chain disclosure that affects brand positioning decisions for companies selling into the state's consumer base. Stakeholders must monitor how state-level extended producer responsibility frameworks evolve to determine whether circular collection infrastructure becomes a cost center or competitive differentiator.
Market Dynamics
The North America Footwear Market faces structural pressure from California's SB 657 supply chain disclosure mandates, which force brands to reconfigure sourcing transparency or forfeit access to the continent's largest consumer corridor. Specialty fitness studios and direct-to-consumer platforms are fragmenting demand away from traditional department store gatekeepers.
Growth Catalysts
- CrossFit and Specialty Running Collectives:These communities are expanding purchases of performance-engineered sneakers with biomechanical customization features. Demand concentrates in metropolitan fitness hubs across the United States and Canada.
- FTC Green Guides Enforcement:The US Federal Trade Commission's substantiation requirements for recycled-material claims are pressuring brands to invest in verified circular supply chains, creating competitive differentiation for compliant manufacturers.
- Athleisure Workplace Penetration:Knitted polyester engineered mesh uppers and injection-molded EVA midsoles are displacing leather formal footwear as workplace dress codes relax across professional services sectors.
Market Restraints
- Petrochemical Input Volatility:EVA foam and synthetic rubber prices fluctuate with crude oil derivatives, compressing margin predictability for mid-tier manufacturers dependent on petroleum-based midsole chemistry.
- Asian Supply Concentration:Upper material knitting and outsole molding capacity clusters in Vietnam and China, exposing North American brands to tariff volatility and shipping cost spikes.
- Biodegradable Midsole Technical Limitations:Current bio-based foams lack the compression-set durability of petroleum-derived EVA, restricting adoption in high-mileage running applications.
Strategic Opportunities
- Domestic Manufacturing Reshoring:Massachusetts and Maine facilities offer tariff-advantaged production for brands targeting federal and military procurement specifications.
- Augmented Reality Sizing Integration:Smartphone-based foot-scanning applications are reducing fit-related return rates in online channels, opening direct-to-consumer expansion without physical retail overhead.
- Extended Producer Responsibility Frameworks:California and Canadian provincial regulations are mandating post-consumer collection infrastructure, creating first-mover advantages for brands with circular logistics capabilities.
Industry Challenges
- Footwear Pattern Engineering Talent Scarcity:Last design and biomechanical fit specialists command premium compensation, constraining speed-to-market for new silhouettes.
- OSHA Certification Timeline Compression:Industrial safety boot testing protocols require 12-18 month validation cycles, delaying product launches in the high-margin occupational segment.
- Legacy ERP Integration Friction:Direct-to-consumer order management systems clash with wholesale-focused inventory platforms, complicating omnichannel fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Footwear Market |
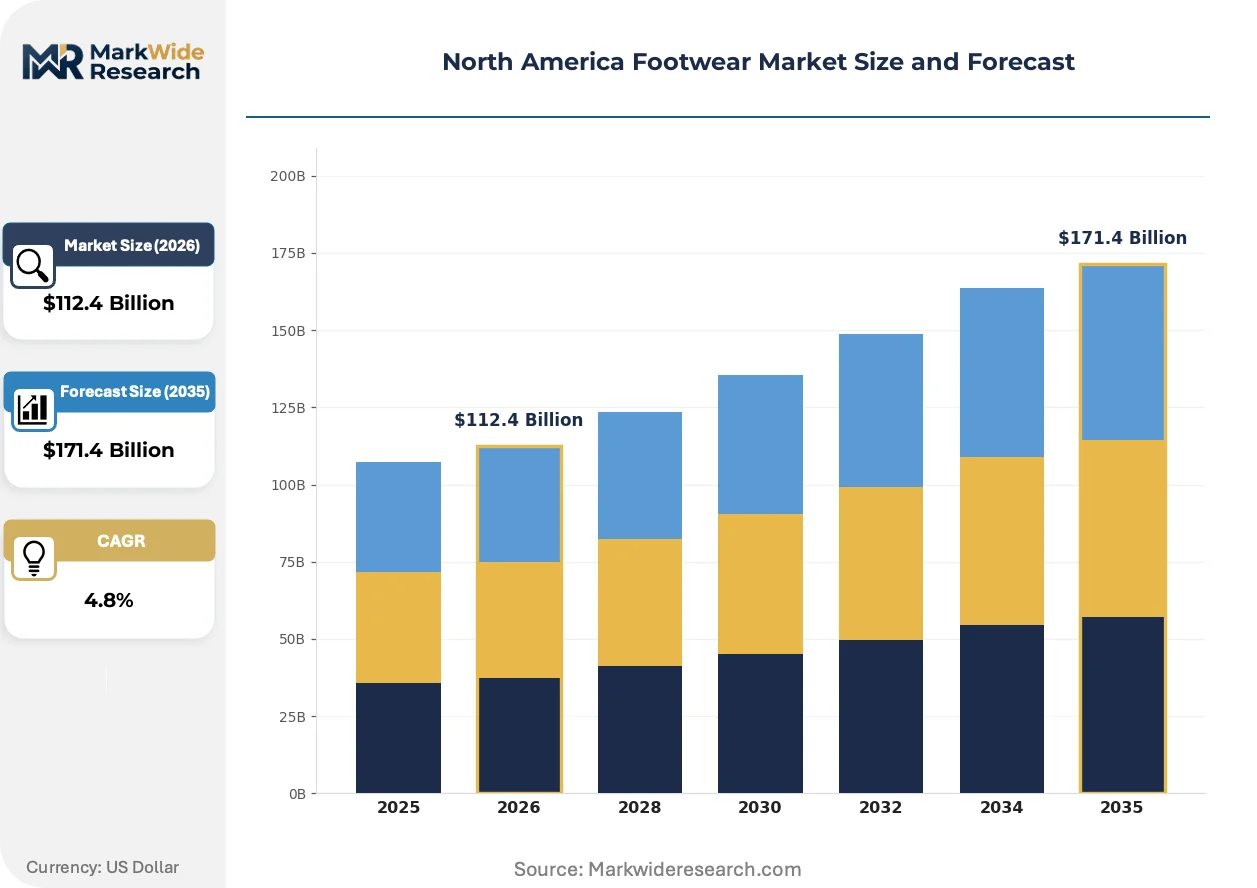
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boots, Sneakers, Sandals, Formal Shoes Material: Leather, Synthetic, Rubber, Canvas End User: Men, Women, Kids, Unisex Distribution Channel: Online, Hypermarkets, Specialty Stores, Department Stores |
| Companies Covered | Nike, Inc., Adidas AG, Skechers USA, Inc., Deckers Outdoor Corporation, VF Corporation, Under Armour, Inc., Wolverine World Wide, Inc., Crocs, Inc., New Balance, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Footwear Market Evolving Landscape
Three intersecting developments are restructuring how North American footwear reaches end users: manufacturing technology dispersion, regulatory transparency mandates, and channel disintermediation. These forces are compressing traditional wholesale hierarchies while elevating technical performance requirements.
Distributed 3D printing of midsole lattice structures is decentralizing production geography for custom orthotic and performance running applications. Regional fabrication hubs in Austin, Toronto, and Portland are adopting multi-material jetting systems to produce region-specific cushioning geometries within 48-hour fulfillment windows. This capability is decentralizing inventory risk from centralized Asian manufacturing toward localized responsive production.
The FTC Green Guides are tightening substantiation standards for recycled-content marketing claims across the United States. Brands must now maintain chain-of-custody documentation from post-consumer collection through reprocessing to finished upper material. Athletic and outdoor segments are responding by partnering with certified recycling facilities to secure audit trails that satisfy California's consumer protection scrutiny.
Specialty fitness studios are consolidating procurement authority previously dispersed across individual athletes. CrossFit affiliates and boutique running clubs now negotiate direct supply agreements with performance brands, bypassing traditional sporting goods retail markups. This concentration is most visible in California's metropolitan corridor and Vancouver's fitness studio density, where collective purchasing power exceeds single-store volumes.
North America Footwear Market Segmentation
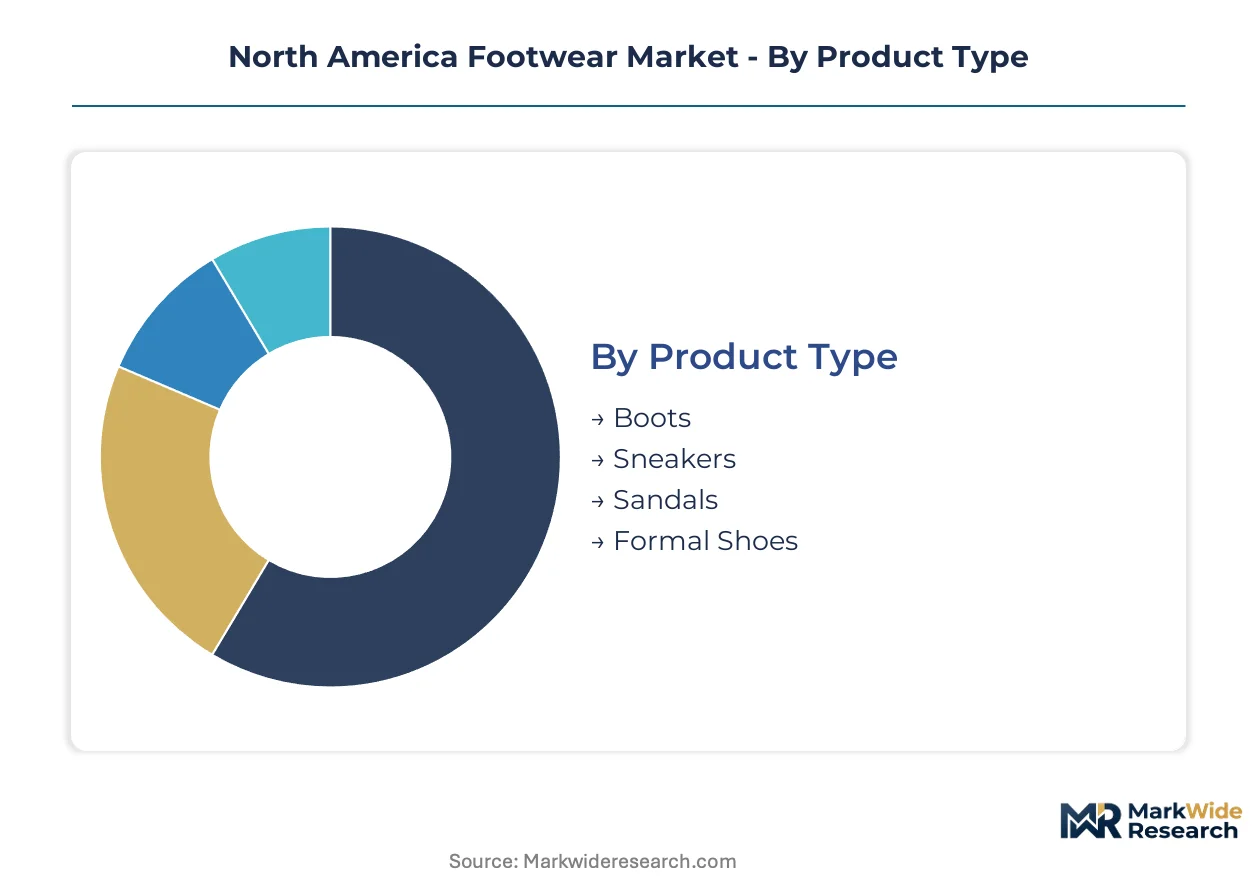
Footwear segmentation in North America tracks divergent paths between performance-engineered athletic products and commodity casual wear. Category boundaries are blurring as workplace dress codes relax and biomechanical customization penetrates mass-market tiers.
Product Type:
Customization intensity varies sharply across this category, from made-to-measure performance runners to standardized casual silhouettes.
- Sneakers:Knitted polyester engineered mesh uppers and injection-molded EVA midsoles dominate construction. Demand concentrates in California's metropolitan corridor and CrossFit affiliate networks, driven by athleisure workplace penetration and specialty fitness studio procurement consolidation.
- Boots:Full-grain leather uppers with cemented or stitch-down outsole attachment serve occupational safety compliance and heritage fashion applications. Demand clusters in industrial Midwest manufacturing hubs and Pacific Northwest outdoor retail, constrained by OSHA certification timeline compression.
- Sandals:Molded EVA footbeds with synthetic or rubber strap configurations target warm-climate casual wear.
- Formal Shoes:Calfskin leather construction with Blake or Goodyear welt attachment persists in professional services and ceremonial end-uses.
Leading the category by volume: Sneakers. Growing fastest: Boots.
Material:
Cost tier stratification separates premium natural inputs from petroleum-derived synthetics and mass-market rubbers.
- Synthetic:Knitted polyester engineered mesh and TPU overlays enable biomechanical customization at scale. Massachusetts and Maine domestic manufacturing facilities are expanding synthetic upper capacity to serve federal procurement specifications.
- Leather:Full-grain and top-grain hides command premium margin pools in formal, heritage work-boot, and luxury sneaker applications. California's SB 657 transparency regulations are forcing chain-of-custody documentation from tannery through finished goods.
- Rubber:Natural and synthetic compounds predominate in outsole molding for traction and durability.
- Canvas:Cotton duck and twill weaves sustain entry-level casual and vulcanized sneaker segments.
Margin concentration peaks in Leather. Volume leadership sits with Synthetic.
End User:
Application maturity separates established adult segments from emerging kids' customization platforms.
- Men:Occupational safety boots and performance athletic silhouettes drive procurement, with federal and military specifications shaping domestic manufacturing investment.
- Women:Athleisure workplace penetration and boutique fitness studio demand are expanding performance-engineered purchases beyond traditional fashion footwear.
- Kids:Rapid size turnover and parental price sensitivity sustain mass-market volume through big-box retail.
- Unisex:Standardized sizing and neutral aesthetics are gaining traction in direct-to-consumer minimalist sneaker launches.
Revenue concentration favors Men. Steepest expansion trajectory: Women.
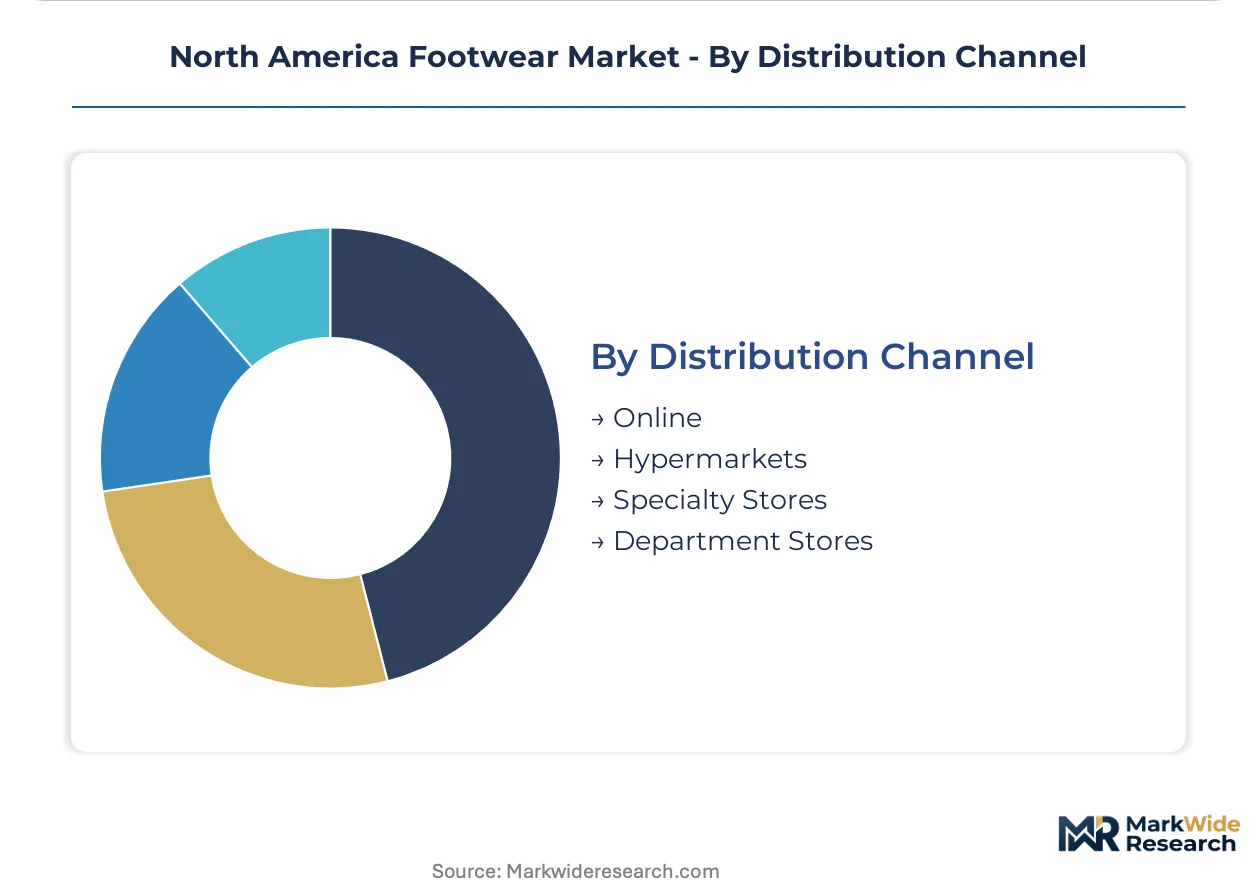
Distribution Channel:
Supply concentration is fragmenting as digital platforms disintermediate traditional wholesale hierarchies.
- Online:Augmented-reality sizing tools and smartphone foot-scanning applications are reducing fit-related return rates. Vancouver and Austin are emerging as direct-to-consumer fulfillment hub locations.
- Specialty Stores:Running collectives and CrossFit affiliates are consolidating procurement authority previously dispersed across individual athletes.
- Hypermarkets:Skechers and casual comfort brands anchor volume-scale distribution with limited SKU breadth.
- Department Stores:Traditional gatekeepers are losing share as brand-owned flagship density concentrates in California metropolitan corridors.
Fastest channel expansion: Online. Legacy volume anchor: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived synthetic rubber and EVA foam feedstock networks anchor North American footwear production geography, with concentration patterns tracking tariff exposure and domestic manufacturing incentives across the continent's three primary markets.
United States
California's metropolitan corridor drives premium athletic demand through CrossFit affiliate density and direct-to-consumer flagship concentration. OSHA workplace safety boot standards shape industrial procurement specifications across Midwest manufacturing hubs. Massachusetts and Maine facilities expand domestic synthetic upper capacity to serve federal and military procurement requirements.
Canada
Vancouver's fitness studio density consolidates specialty running collective purchasing power exceeding single-store volumes. Health Canada maintains product safety standards for footwear materials that parallel US regulatory frameworks. Toronto and Calgary distribution hubs service direct-to-consumer fulfillment networks targeting northern climate performance requirements.
Mexico
Nuevo León and Jalisco industrial corridors attract outsole molding and upper material knitting capacity serving nearshoring strategies. The country's national consumer protection authority enforces labeling standards for imported footwear products. Mexico City metropolitan area concentrates mass-market casual footwear distribution through hypermarket and department store networks.
North America Footwear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biomechanical customization and circular supply chain verification. The market structure consolidates around vertically integrated foam chemistry specialists, volume-scale casual comfort distributors, and domestic manufacturing advocates. Three archetypes dominate: performance-engineered athletic specialists, mass-market casual comfort providers, and heritage work-boot manufacturers. Competitive moves concentrate on strategic partnerships with certified recycling facilities and augmented-reality sizing technology licensing.
Among US-based incumbents, Nike, Inc. and Skechers USA, Inc. exemplify divergent scale strategies, with the former representing upstream chemical integration archetypes and the latter anchoring big-box retail volume distribution. New Balance, Inc. occupies a position within the domestic manufacturing tier, leveraging Massachusetts and Maine facilities for tariff-advantaged federal procurement access. These three entities collectively illustrate how competitive positioning fragments across performance premium, casual volume, and manufacturing origin vectors.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Skechers USA, Inc. |
| Deckers Outdoor Corporation |
| VF Corporation |
| Under Armour, Inc. |
| Wolverine World Wide, Inc. |
| Crocs, Inc. |
| New Balance, Inc. |
| Others |
Value Network & Pricing Analysis
Footwear pattern engineering talent scarcity in Massachusetts and Maine feeds labor-cost differentials that widen pricing-tier spreads between domestic performance manufacturing and Asian volume production. The FTC Green Guides enforcement and California SB 657 compliance burdens layer certification premiums atop base manufacturing costs.
Pricing Analysis
Volume-mass sneakers and premium-performance runners split the pricing architecture across distinct margin profiles. Three-tier pricing structure across premium, standard, and economy levels separates biomechanical customization tiers from commodity casual wear. Price differentiation hinges on domestic manufacturing origin and FTC-verified recycled-content certification. Cost compression in mid-tier EVA-foam sneakers is intensifying because petrochemical input volatility compresses margin predictability. Big-box retail buyers exhibit highest price sensitivity; federal procurement specifications show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Vietnam and China for upper material knitting and outsole molding capacity. Raw material dependencies center on petroleum-derived EVA foam, synthetic rubber compounds, and knitted polyester engineered mesh. Tariff exposure and shipping cost spikes constitute the dominant structural risk. Distribution runs through direct-to-consumer platforms augmented by specialty fitness studio procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable midsole technical limitations constrain supply expansion, propping pricing power for petroleum-derived EVA specialists. Capacity scarcity in domestic Massachusetts and Maine facilities amplifies tariff-advantaged positioning.
For Market Incumbents: Lock in circular supply chain verification through certified recycling facility partnerships ahead of California extended producer responsibility mandates. Secure Massachusetts and Maine capacity additions to defend federal procurement access against tariff volatility. Biomechanical customization platforms threaten commodity sneaker margins; prioritize foam chemistry R&D differentiation.
For New Entrants and Emerging Players: Enter via augmented-reality sizing integration for direct-to-consumer channels, exploiting fit-related return rate reduction. Target women's athleisure workplace penetration as the most penetrable segment. CrossFit affiliate direct supply agreements offer a specific go-to-market angle bypassing traditional retail markups.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic manufacturing specialists given federal procurement specification tightening. Long-term viability favors tariff-advantaged production footprints over Asian supply concentration. Monitor California SB 657 enforcement intensity as the signal to watch for circular logistics capability valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Reshoring | Massachusetts and Maine facilities secure tariff-advantaged federal procurement access. |
| Circular Supply Chain Verification | FTC Green Guides compliance creates competitive differentiation through certified recycling partnerships. |
| Augmented-Reality Sizing Integration | Smartphone foot-scanning applications reduce fit-related return rates in direct-to-consumer channels. |
| Biomechanical Customization Platform | 3D-printed midsole lattice structures enable 48-hour regional fulfillment for performance runners. |
| Extended Producer Responsibility Infrastructure | California and Canadian provincial mandates create first-mover advantages in post-consumer collection. |
Research Methodology
SEC 10-K filings, customs and trade databases, and OSHA regulatory guidance documents formed the secondary backbone of this analysis. Primary interviews with footwear brand supply chain directors, specialty retail buyers, CrossFit affiliate owners, and Massachusetts manufacturing facility managers complemented secondary validation. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Historical trendline analysis across product type, material, end user, and distribution channel dimensions established baseline growth patterns. Segmentation modeling tracked sneakers, boots, sandals, and formal shoes alongside synthetic, leather, rubber, and canvas materials. CAGRs derived from regression analysis of shipment volumes and average selling price movements throughout the forecast period. Petrochemical input cost indices and California regulatory enforcement timelines served as footwear-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff regime shifts and biodegradable material breakthrough scenarios. Forecasts reflect documented assumptions regarding workplace dress code relaxation and specialty fitness studio procurement consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Snow Boots for Women Market
Footwear
North America Athletic Footwear Market
Footwear
Chunky Sneaker Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Europe Barefoot Shoes Market
Footwear
GCC Footwear Market
Footwear
Cowboy Boots Market
Footwear
US Slip Resistant Shoes Market
Footwear
Slip Resistant Shoes Market
Footwear
Women's Sneakers Market
Footwear
Luxury Footwear Market
Footwear
Global Men Leather Shoes Market
Footwear
Womens Footwear Market
Footwear
Winter Footwear Market
Footwear
Running Shoes Market
Footwear
Footwear Testing Services Market