
 Global Automotive 3PL Market | 2026-2036
Global Automotive 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive 3PL Market Foresight
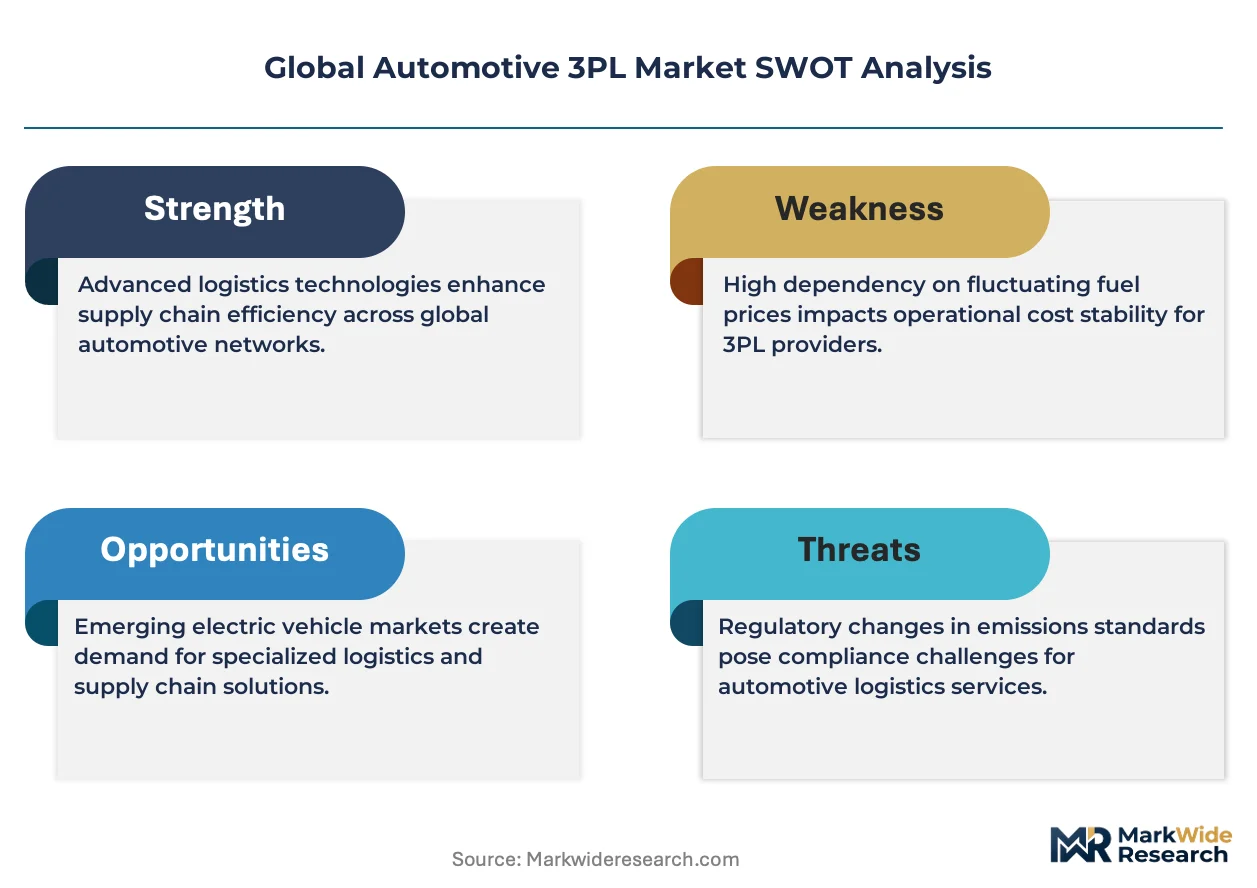
Asset-light leasing models for warehouse fleets and transport equipment is reconfiguring competitive entry barriers across the automotive logistics sector. DHL Group leverages its multi-modal network to dominate inbound-to-plant sequencing for European OEMs. CEVA Logistics anchors its position through deep specialization in finished vehicle logistics and yard management. Kuehne Nagel Management AG sustains competitive differentiation via temperature-controlled solutions for battery cell transport.
Automotive third-party logistics encompasses the outsourcing of supply chain execution functions—including transport, warehousing, inventory optimization, and value-added services—through contracted providers operating on behalf of vehicle manufacturers and component suppliers. These services integrate just-in-time delivery protocols, real-time tracking systems, and specialized handling equipment to maintain production continuity across geographically dispersed assembly operations. Transportation services occupy the largest value pool within the service type dimension, while value-added services such as kitting, sequencing, and quality inspection represent the fastest-expanding margin segment as OEMs push non-core activities downstream. Within the end user dimension, aftermarket providers are accelerating their 3PL engagement faster than OEMs as electric vehicle part proliferation and predictive maintenance programs demand more sophisticated distribution architectures.
The EPA enforces emissions standards that compel automotive shippers to optimize route efficiency and modal shifts toward rail and short-sea options across North American corridors. EMA and REACH frameworks in Europe impose chemical handling and battery substance documentation requirements that filter directly into 3PL operational specifications and qualification criteria. China's MIIT and GB standards mandate connected vehicle data governance that shapes how logistics platforms integrate telematics and IoT infrastructure. Stakeholders must monitor how regulatory fragmentation across these jurisdictions influences platform interoperability and compliance cost allocation between shippers and their logistics partners.
Market Dynamics
Electric vehicle OEMs are forcing a wholesale reconfiguration of automotive logistics infrastructure, as battery supply chains demand temperature-controlled transport, hazardous materials certification, and reverse logistics capabilities that legacy combustion-era networks cannot accommodate.
Growth Catalysts
- EU Green Deal:Mandatory emissions reporting across automotive supply chains compels OEMs to outsource to 3PLs with verified carbon accounting systems and multi-modal optimization platforms.
- Battery chemistry specialization:Solid-state and lithium-iron-phosphate cell formats require distinct handling protocols, expanding contract logistics scope for hazardous materials-qualified providers.
- China:Domestic EV production scaling past internal logistics capacity creates captive demand for local 3PLs building dedicated automotive competencies.
Market Restraints
- Lithium price volatility:Battery raw material cost swings compress OEM margins and constrain logistics budget flexibility, forcing 3PLs to absorb rate pressure or lose contracts.
- Specialized fleet scarcity:Temperature-controlled vehicle availability concentrates among fewer carriers in Europe and North America, creating capacity bottlenecks during seasonal demand spikes.
- REACH compliance:Chemical substance documentation requirements for battery materials add administrative overhead that disqualifies smaller logistics operators from tier-one supplier status.
Strategic Opportunities
- India:PLI scheme incentives for domestic EV manufacturing outpace local logistics infrastructure development, creating first-mover advantage for global 3PLs establishing battery supply chain operations.
- Predictive maintenance programs:Connected vehicle data streams enable 3PLs to offer anticipatory parts positioning services, shifting aftermarket logistics from reactive to preemptive models.
- ISO 14064:Carbon verification standards create service differentiation for 3PLs that can document Scope 3 emissions reductions across automotive customer portfolios.
Industry Challenges
- Battery technician certification:Hazardous materials handling credentials for high-voltage systems face 18-24 month training pipelines, constraining workforce scaling for EV-dedicated logistics operations.
- Telematics integration:OEM-specific data protocols fragment IoT platform standardization, forcing 3PLs to maintain multiple proprietary interfaces for connected vehicle visibility.
- Sequencing precision:Just-in-time inbound-to-plant delivery tolerances compress to sub-hour windows, requiring yard management system upgrades that demand capital deployment without guaranteed contract extensions.
Report Scope
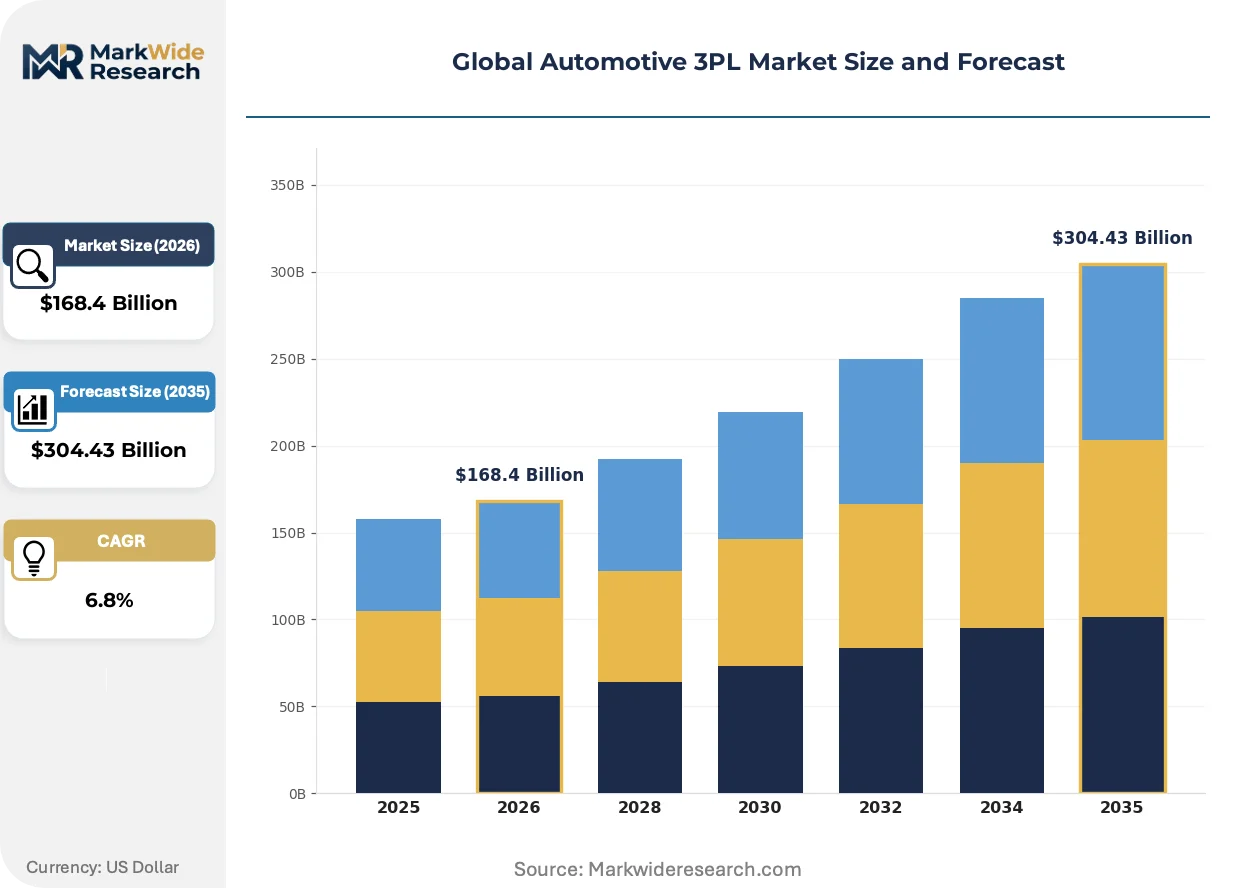
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive 3PL Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $304.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Value-Added Services End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: Automation, IoT, Cloud Based Solutions, Artificial Intelligence Delivery Model: Managed Services, On-Demand Services, Dedicated Services, Integrated Solutions |
| Companies Covered | CEVA Logistics, DHL Group, DSV, DB Schenker, XPO Logistics, Kuehne Nagel Management AG, Nippon Express Holdings Inc., BLG Logistics, GXO Logistics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive 3PL Market Shifts & Advancements
Digital twins and autonomous yard vehicles are converging with battery-specific handling protocols to create a new operational baseline for automotive logistics, separating capitalized technology leaders from asset-heavy traditional operators.
Autonomous mobile robots for yard shunting and vehicle positioning are hybridizing warehouse automation with outdoor logistics environments. Tier-one suppliers in Germany and South Korea are piloting these systems at scale. The technology is hybridizing fixed infrastructure requirements with flexible fleet deployment, reducing dedicated trailer staging areas by compressing dwell times through continuous rather than batch vehicle movements.
CSRD mandates in Europe now require listed automotive OEMs to report Scope 3 emissions from logistics activities, forcing disclosure down to contracted 3PL performance. This regulatory pressure is accelerating modal shift investments toward rail and short-sea corridors. Battery supply chains face the steepest compliance cost escalation, as cell transport represents the highest-emission segment within EV production logistics.
Aftermarket procurement patterns are fragmenting as EV part proliferation outpaces traditional distribution center SKU density limits. Independent repair networks in the United States and United Kingdom are bypassing OEM captive logistics for specialized battery component distributors. This channel disintermediation concentrates demand among 3PLs offering cross-docking and quality inspection services for high-voltage parts outside authorized dealer networks.
Global Automotive 3PL Market Segmentation
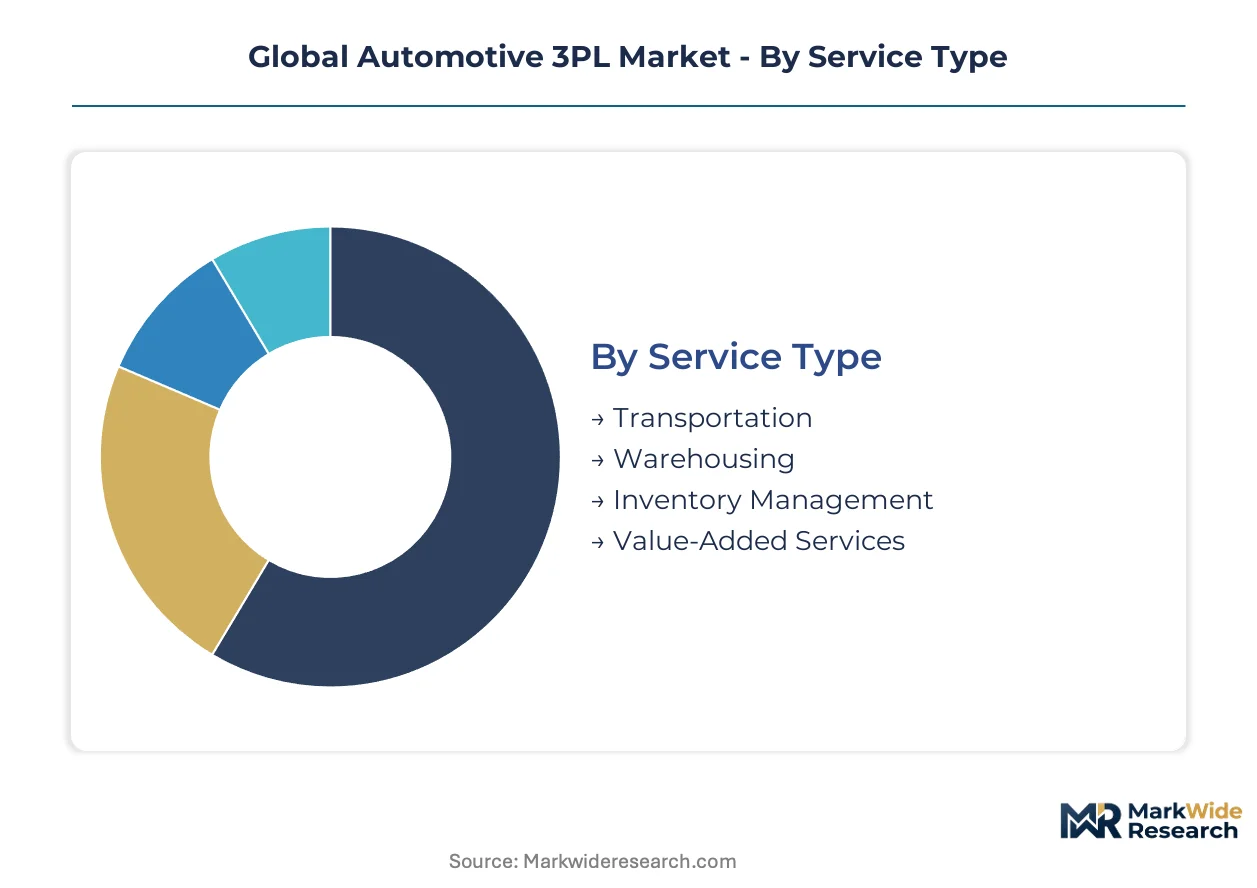
Automotive 3PL segmentation reflects divergent capital intensity and regulatory exposure across service delivery modes. Each category maps distinct operational requirements onto customer procurement patterns shaped by electrification timelines and regional compliance mandates.
Service Type:
Use cases span high-velocity sequencing for assembly plants through specialized handling for hazardous battery materials.
- Transportation:Multi-modal freight execution dominates contract value, with temperature-controlled vehicle pools commanding premium positioning for lithium-ion cell movements. Demand concentrates in Germany and China where OEMs outsource inbound-to-plant logistics to qualified hazardous materials carriers facing EPA and MIIT certification requirements.
- Value-Added Services:Kitting, sequencing, and quality inspection represent the steepest expansion trajectory as OEMs push non-core activities downstream. Procurement from tier-1 battery suppliers in South Korea and Japan drives contract growth for providers with ISO 14064 carbon verification and REACH-compliant documentation systems.
- Warehousing:Asset-light leasing models reconfigure competitive entry barriers, with dedicated EV battery storage facilities requiring fire suppression and thermal management infrastructure.
- Inventory Management:Real-time tracking systems integrate OEM telematics protocols to maintain production continuity across dispersed assembly operations.
Established volume favors Transportation; emerging adoption favors Value-Added Services.
End User:
Customer types exhibit divergent outsourcing maturity and electrification-driven logistics complexity.
- Aftermarket Providers:Independent repair networks bypass OEM captive logistics for specialized battery component distributors, concentrating demand among 3PLs offering cross-docking and quality inspection for high-voltage parts. Channel disintermediation accelerates in the United States and United Kingdom as EV part proliferation outpaces traditional distribution center SKU density limits.
- OEMs:Electric vehicle manufacturers expand outsourced logistics for battery supply chains, with CSRD mandates compelling disclosure down to contracted 3PL performance. European OEMs prioritize providers with verified carbon accounting and multi-modal optimization platforms.
- Tier-1 Suppliers:Battery cell manufacturers require hazardous materials certification and reverse logistics capabilities that legacy networks cannot accommodate.
- Dealerships:Finished vehicle logistics and yard management anchor 3PL relationships, with autonomous mobile robots piloting at scale in Germany and South Korea.
Procurement concentration sits with OEMs; margin expansion favors Aftermarket Providers.
Technology:
Deployment patterns track capital availability and interoperability requirements across OEM data protocols.
- IoT:Connected vehicle data governance under China's GB standards shapes platform integration, with telematics fragmentation forcing 3PLs to maintain multiple proprietary interfaces. Sensor networks for battery state-of-monitoring dominate implementation roadmaps.
- Automation:Autonomous yard vehicles and mobile robots compress dwell times through continuous vehicle movements, hybridizing warehouse automation with outdoor logistics environments. German tier-1 suppliers pilot these systems at scale.
- Artificial Intelligence:Predictive maintenance programs enable anticipatory parts positioning, shifting aftermarket logistics from reactive to preemptive models.
- Cloud Based Solutions:Real-time visibility platforms aggregate multi-modal tracking data across geographically dispersed operations.
Capital deployment favors Automation; service differentiation favors IoT.
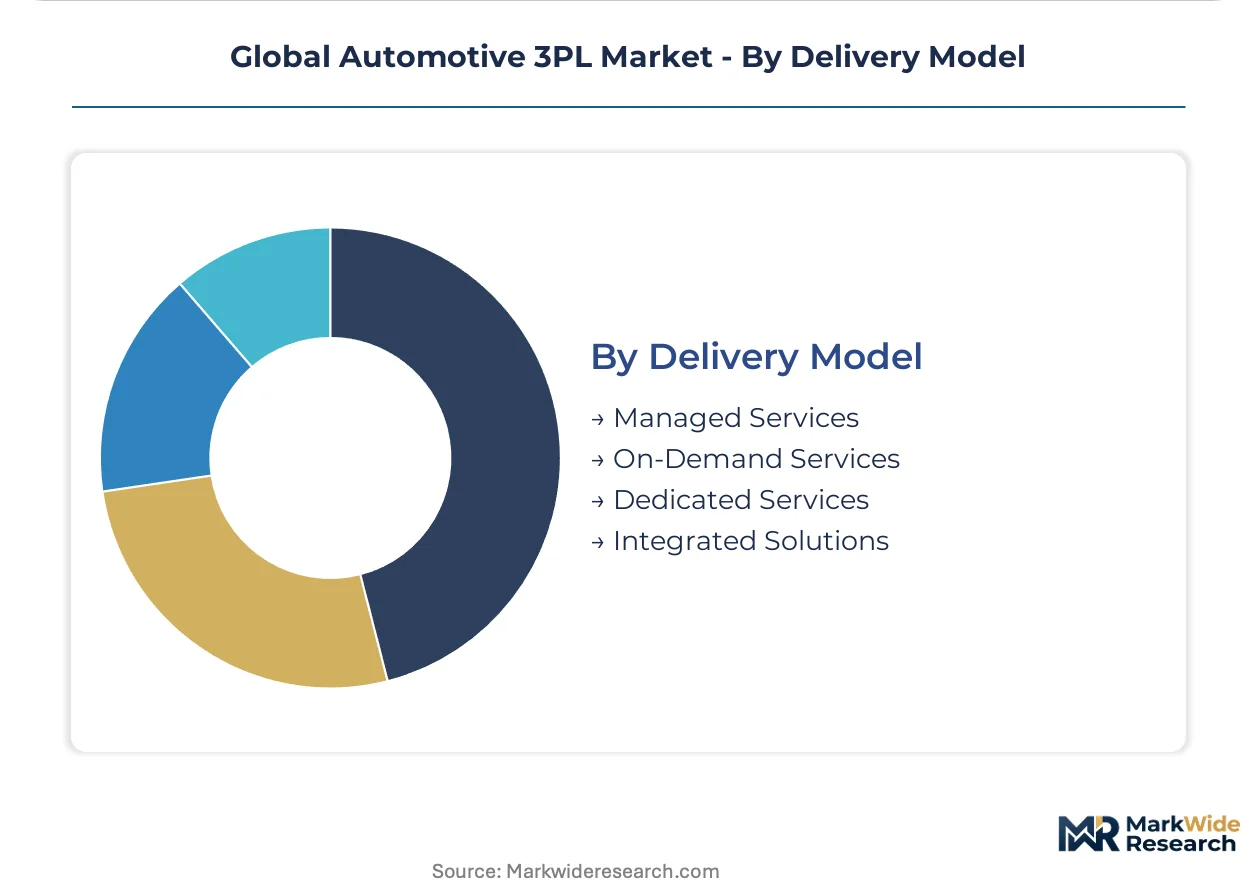
Delivery Model:
Contract structures align asset commitment with demand predictability and regulatory compliance duration.
- Dedicated Services:Long-term contracts with guaranteed volume underpin specialized fleet investments for temperature-controlled battery transport. European carriers face capacity bottlenecks during seasonal demand spikes due to qualified vehicle scarcity.
- Integrated Solutions:End-to-end supply chain control combines inbound sequencing with aftermarket distribution, capturing margin across the full vehicle lifecycle. Indian PLI scheme incentives for domestic EV manufacturing outpace local logistics infrastructure, creating first-mover opportunity for global 3PLs establishing battery supply chain operations.
- Managed Services:Outsourced operational control without asset ownership appeals to OEMs seeking flexibility amid lithium price volatility.
- On-Demand Services:Spot-market access provides surge capacity for production ramp events and recall-driven reverse logistics.
Contract stability favors Dedicated Services; growth optionality favors Integrated Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in automotive logistics are widening as battery component trade flows reshape traditional vehicle shipping corridors. China now runs substantial surpluses in EV-related freight movements while Germany and the United States absorb inbound battery cell volumes that strain existing customs and handling infrastructure.
China
Domestic EV production scaling past internal logistics capacity creates captive demand for local 3PLs building dedicated automotive competencies. MIIT and GB standards mandate connected vehicle data governance that shapes how logistics platforms integrate telematics and IoT infrastructure. The Yangtze River Delta cluster around Shanghai concentrates battery cell manufacturing and outbound export consolidation operations.
Germany
European OEMs prioritize providers with verified carbon accounting and multi-modal optimization platforms under tightening CSRD disclosure requirements. REACH frameworks impose chemical handling and battery substance documentation requirements that filter directly into 3PL operational specifications. The Bavaria and Baden-Württemberg industrial corridors anchor inbound-to-plant sequencing contracts for premium vehicle manufacturers.
United States
Independent repair networks bypass OEM captive logistics for specialized battery component distributors, concentrating demand among 3PLs offering cross-docking and quality inspection for high-voltage parts. EPA emissions standards compel automotive shippers to optimize route efficiency and modal shifts toward rail and short-sea options across North American corridors. The Southeast manufacturing belt spanning Tennessee, South Carolina, and Georgia hosts expanding EV assembly plants driving regional 3PL contract growth.
India
PLI scheme incentives for domestic EV manufacturing outpace local logistics infrastructure development, creating first-mover advantage for global 3PLs establishing battery supply chain operations. BIS certification requirements for battery safety and handling protocols shape qualification criteria for logistics operators entering the market. The Gujarat and Maharashtra industrial clusters concentrate new EV manufacturing investments and associated warehousing demand.
South Korea
Tier-one battery cell manufacturers require hazardous materials certification and reverse logistics capabilities that legacy networks cannot accommodate, expanding contract scope for qualified providers. MFDS and related industrial standards govern chemical transport documentation for lithium-ion materials. The Busan-Ulsan coastal corridor handles major export volumes for battery components bound for European and North American assembly plants.
Global Automotive 3PL Market Competitive Landscape
On the supply side, the industry is consolidating around multi-modal network operators with hazardous materials certifications and carbon accounting capabilities. Tier-one global integrators with dedicated automotive divisions now control the majority of battery supply chain contracts. Two strategic archetypes dominate: asset-light technology platforms specializing in sequencing and visibility, and capital-heavy fleet operators controlling temperature-controlled vehicle pools. Competitive moves concentrate on M&A targeting regional battery logistics specialists and strategic partnerships with cell manufacturers for dedicated transport capacity.
Among European-based integrated logistics providers, DHL Group, CEVA Logistics, and Kuehne Nagel Management AG exemplify the tier-one archetype combining multi-modal networks with automotive-specific certifications. These operators occupy positions that span inbound sequencing, finished vehicle logistics, and emerging battery transport specializations. Their scale enables compliance investment for REACH documentation and CSRD-aligned carbon reporting that disqualifies smaller competitors from OEM tender processes. The concentration of qualified providers in this tier creates pricing leverage during contract renewals as battery supply chain complexity escalates.
| Leading Market Players |
|---|
| CEVA Logistics |
| DHL Group |
| DSV |
| DB Schenker |
| XPO Logistics |
| Kuehne Nagel Management AG |
| Nippon Express Holdings Inc. |
| BLG Logistics |
| GXO Logistics Inc. |
| Others |
Supply & Pricing Matrix
China's Yangtze River Delta battery cell manufacturing cluster anchors upstream supply concentration, concentrating pricing power among hazardous materials-certified carriers and compressing margin pools toward downstream sequencing and carbon verification services. Temperature-controlled fleet scarcity in Europe and North America amplifies rate premiums for qualified providers while OEMs push cost absorption downstream.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered rate schedules. Price differentiation hinges on ISO 14064 carbon verification grade and REACH-compliant documentation tier. Cost compression in mid-market logistics tiers is intensifying because lithium price volatility constrains OEM logistics budgets. Aftermarket distributors exhibit highest price sensitivity due to channel disintermediation pressures, while premium OEMs prioritize certification over rate.
Supply Chain Analysis
Lithium carbonate and cathode active materials feed from Chile, Australia, and China's Sichuan processing corridors. Cell manufacturing rests on separator films, electrolyte salts, and nickel-cobalt-manganese precursors sourced from South Korea and Japan. Single-source vulnerability concentrates in European temperature-controlled vehicle pools. Distribution runs through dedicated contract logistics networks with multi-modal optimization platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through REACH certification and CSRD-aligned carbon accounting creates switching costs that lock out unqualified competitors. Network effects concentrate among multi-modal operators with hazardous materials credentials.
For Market Incumbents: Entrench position through backward integration into temperature-controlled fleet assets across Germany and China, and deepen certification pipelines for battery technician credentials. Emerging asset-light technology platforms threaten margin capture in sequencing and visibility software, making captive fleet investment the priority lever for contract renewal leverage.
For New Entrants and Emerging Players: Build out specialized cross-docking and quality inspection capabilities for high-voltage aftermarket parts in the United States and United Kingdom, where independent repair network demand outpaces qualified provider supply. India's PLI scheme incentives for domestic EV manufacturing present the most penetrable geography for battery supply chain establishment.
For Investors and Strategic Acquirers: Capital is best deployed toward regional battery logistics specialists with hazardous materials certifications and existing OEM relationships, as these assets command scarcity premiums across a multi-year consolidation horizon. Watch for inflection in autonomous yard vehicle pilot scale-up at German tier-one suppliers as signal of technology-leader separation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures dedicated temperature-controlled capacity for lithium-ion cell movements under EPA and MIIT protocols. |
| Carbon Verification Investment | Enables CSRD-aligned Scope 3 disclosure for European OEM contract qualification and renewal. |
| Autonomous Yard Deployment | Compresses dwell times through continuous vehicle positioning at German and South Korean assembly plants. |
| Regional Logistics Acquisition | Captures qualified hazardous materials carriers facing capacity bottlenecks in European corridors. |
| Aftermarket Channel Partnership | Positions cross-docking infrastructure for independent repair network battery component distribution. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and hazardous materials logistics operators, and refined through secondary validation against vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed logistics providers. Bottom-up contract value estimates triangulated with top-down market sizing across service type and end user dimensions.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation across transportation mode, service tier, propulsion architecture, OEM tier, and regional production cluster. CAGRs derived from trend extrapolation of electrification-driven outsourcing penetration, overlaid with regulatory compliance cost escalation and fleet capacity constraints specific to temperature-controlled battery transport.
Stress conditions across lithium price volatility bands, REACH documentation requirement amendments, and temperature-controlled vehicle availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IEA EV outlook projections and automotive OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Weigh in Motion Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Latin America Cross Border Road Freight Market
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
North America Road Freight Transportation Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
UAE Cold Chain Logistics Market