
 United States Retail 3PL Market | 2026-2036
United States Retail 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
United States Retail 3PL Market Analytics
The capital-intensity divergence between automated warehouse operators and labor-dependent regional carriers is redrawing competitive tiers in United States retail logistics. C.H. Robinson Worldwide leverages its digital freight brokerage platform to sustain pricing power across fragmented truckload markets. GXO Logistics anchors its position through robotics-heavy fulfillment centers that reduce unit labor costs in high-velocity e-commerce operations. FedEx Logistics competes by extending its integrated air-ground network into dedicated retail replenishment lanes.
United States Retail 3PL encompasses outsourced supply chain management services—spanning transportation brokerage, contract warehousing, inventory optimization, and fulfillment execution—typically governed by service-level agreements specifying order accuracy thresholds, inventory shrinkage limits, and on-time delivery percentages. The primary commercial purpose centers on converting fixed logistics infrastructure into variable costs for retailers facing demand volatility. Warehousing services capture the dominant margin pool as automated storage and retrieval systems raise facility-level barriers to entry. Last Mile Delivery represents the fastest-growing delivery model segment as same-day expectations from e-commerce retailers compress transit windows. Small Businesses and Startups increasingly access shared-use fulfillment networks that previously required enterprise-scale volume commitments.
The Department of Transportation's hours-of-service regulations constrain driver availability and push retailers toward dedicated fleet arrangements with large 3PL providers. OSHA warehouse safety standards and the EPA's Phase 2 greenhouse gas emissions rules for heavy-duty trucks elevate compliance costs that favor scaled operators with in-house regulatory teams. Stakeholders must monitor how California's Advanced Clean Trucks regulation spreads to other states and whether autonomous vehicle exemptions reshape driver-cost structures before the decade closes.
Market Dynamics
The Federal Motor Carrier Safety Administration's electronic logging device mandate is compressing driver capacity and forcing retailers toward dedicated 3PL partnerships with compliance infrastructure already embedded. This regulatory pressure is redrawing competitive tiers between scaled national operators and regional carriers lacking real-time fleet visibility systems.
Growth Catalysts
- California's Inland Empire corridor:Warehouse absorption rates in this distribution cluster are pulling investment toward automated fulfillment centers serving West Coast e-commerce demand.
- OSHA warehouse safety standards:Heightened enforcement of powered industrial truck regulations is accelerating consolidation toward 3PLs with dedicated safety compliance teams.
- Same-day delivery compression:Consumer expectations for sub-24-hour fulfillment are expanding micro-fulfillment networks and shared-use warehousing among mid-market retailers.
Market Restraints
- Diesel price volatility:Fuel represents 25-30% of linehaul costs for truckload carriers, and price spikes transmit directly to contracted rate structures with limited pass-through mechanisms.
- Driver pool contraction:The FMCSA Drug and Alcohol Clearinghouse has disqualified over 100,000 commercial drivers since implementation, tightening capacity across for-hire trucking.
- Real estate concentration:Industrial vacancy rates below 4% in Dallas-Fort Worth and Phoenix are influring site selection costs and extending facility commissioning timelines.
Strategic Opportunities
- Midwestern secondary markets:Columbus, Indianapolis, and Kansas City offer lower land costs and central positioning for two-day ground coverage of coastal population centers.
- Reverse logistics integration:Returns processing now represents 15-20% of e-commerce fulfillment costs, creating white space for 3PLs with specialized refurbishment and liquidation capabilities.
- EPA SmartWay certification:Shipper sustainability scorecards are prioritizing carriers with verified emissions reductions, creating preference premiums for certified fleets.
Industry Challenges
- Warehouse automation technician scarcity:Maintenance of autonomous mobile robots and goods-to-person systems requires electro-mechanical skills that outpace vocational training pipeline output.
- Multi-client WMS integration:Retailers running proprietary order management systems demand API connectivity that strains legacy 3PL technology stacks and extends onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Retail 3PL Market |
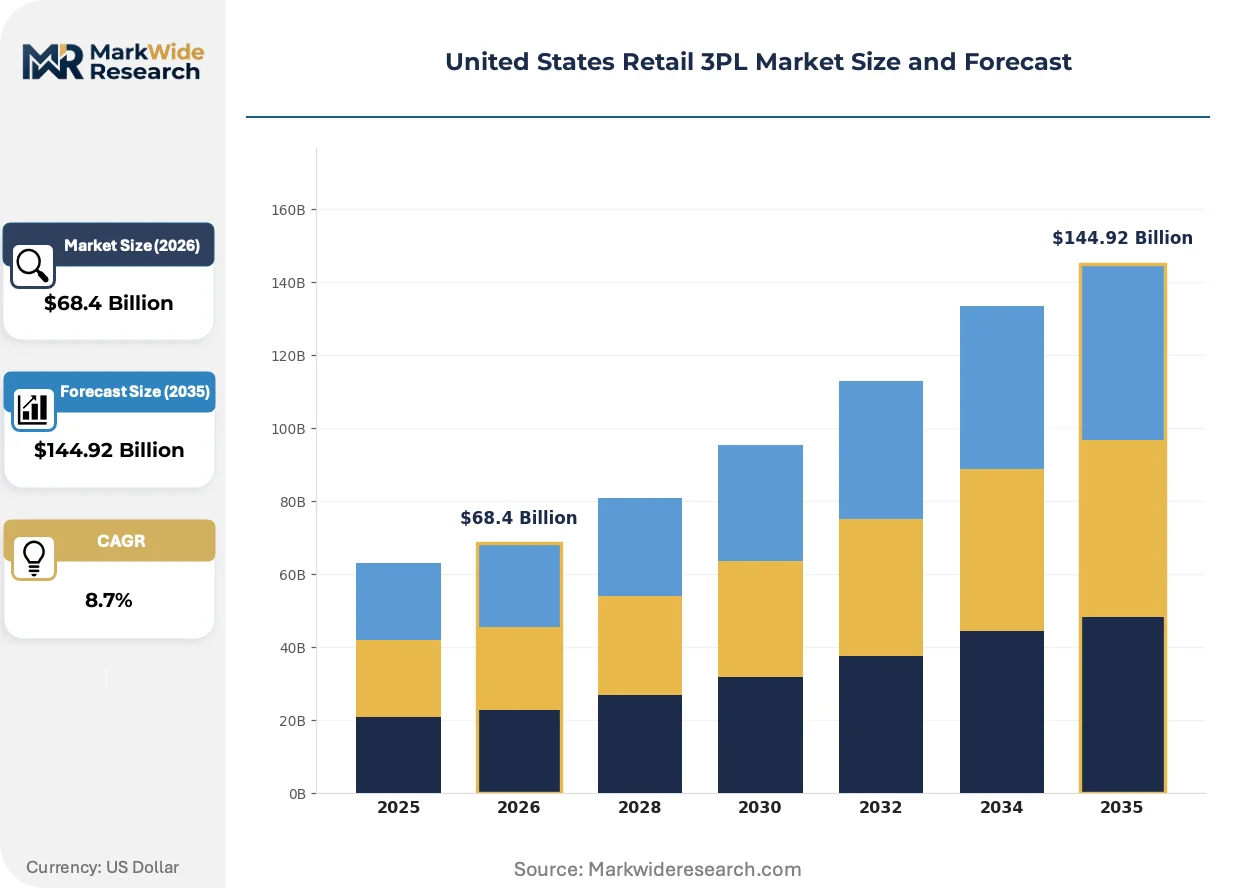
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Order Fulfillment Delivery Model: Direct Shipping, Cross-Docking, Hub and Spoke, Last Mile Delivery Customer Type: Small Businesses, E-commerce Retailers, Large Enterprises, Startups Capacity: Low Capacity, Medium Capacity, High Capacity, Specialized Capacity |
| Companies Covered | DHL Supply Chain, C.H. Robinson Worldwide, Inc., UPS Supply Chain Solutions, GXO Logistics, Inc., CEVA Logistics, Kuehne + Nagel, FedEx Logistics, Inc., Expeditors International of Washington, Inc., Ryder System, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Retail 3PL Market Evolving Landscape
Digital freight matching platforms are compressing procurement cycles and exposing rate transparency that was previously opaque to mid-market shippers. This technological shift is forcing incumbent brokerages to defend position through predictive pricing algorithms and guaranteed capacity contracts.
Autonomous mobile robots in goods-to-person configurations are supplanting conventional pick-to-cart operations in high-velocity e-commerce facilities. DTC brands and flash-sale retailers are deploying these systems at 200,000+ square foot thresholds previously reserved for enterprise-scale operators. The technology is supplanting labor-dependent picking models and compressing unit fulfillment costs below $3.50 per order in select automated environments.
The Department of Transportation's forthcoming autonomous vehicle exemption framework is creating regulatory uncertainty around driverless truck deployment timelines. Fleet operators are diverting R&D capital toward platooning technologies and advanced driver-assistance systems as intermediate compliance pathways. Long-haul corridors between Texas and California are becoming testbed jurisdictions where state-level permitting precedes federal harmonization.
Shippers are consolidating vendor relationships and demanding integrated control-tower visibility across transportation and warehousing functions. This procurement consolidation is displacing point-solution providers and favoring 3PLs with unified technology platforms spanning inventory, order, and fleet management. Food and beverage retailers in the Southeast are most aggressive in requiring single-source accountability for temperature-controlled supply chains.
United States Retail 3PL Market Segmentation
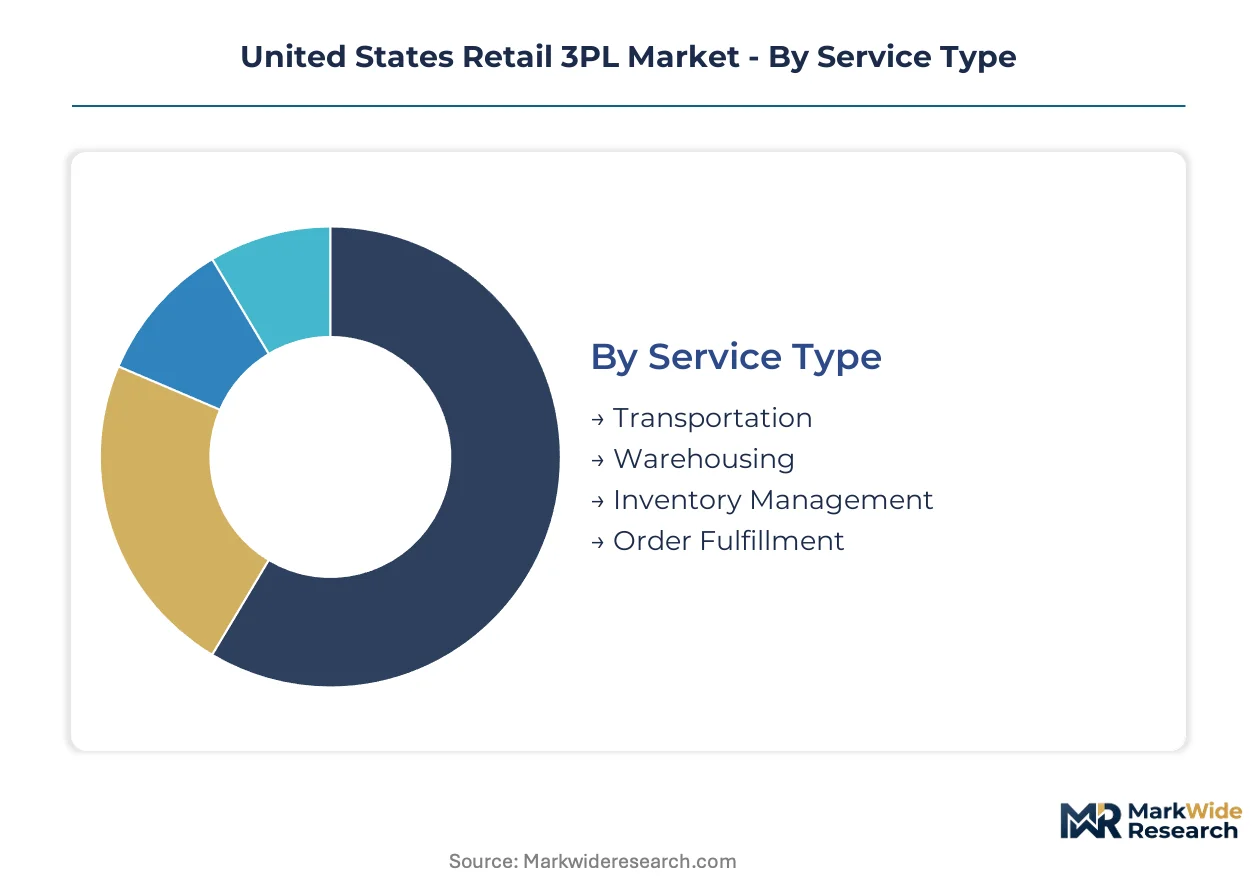
Service differentiation in United States retail 3PL determines margin capture and contract tenure. Segmentation reveals where automation investments concentrate versus where labor arbitrage still governs profitability.
Service Type:
Transportation brokerage faces the strongest substitution pressure from digital freight platforms that disintermediate traditional carrier relationships.
- Transportation:Truckload and less-than-truckload brokerage governed by FMCSA hours-of-service compliance. Demand concentrates among e-commerce retailers seeking dedicated fleet arrangements as driver availability tightens under Drug and Alcohol Clearinghouse enforcement.
- Warehousing:Contract facilities with automated storage and retrieval systems raising barriers to entry. California's Inland Empire corridor anchors investment as West Coast distribution absorption rates pull capital toward robotics-heavy fulfillment centers.
- Inventory Management:Demand forecasting and safety stock optimization through proprietary algorithms. Mid-market retailers access shared-use networks that previously required enterprise-scale commitments.
- Order Fulfillment:Pick-pack-ship execution with service-level agreements specifying order accuracy thresholds. Same-day delivery compression expands micro-fulfillment networks among DTC brands.
Warehousing anchors the volume base while order fulfillment gains share at the steepest rate.
Delivery Model:
Cost tier differentiation separates asset-heavy hub infrastructure from variable-cost direct shipping arrangements.
- Direct Shipping:Point-to-point parcel movement bypassing intermediate sortation. Large enterprises deploy this model for high-velocity replenishment between owned distribution nodes.
- Cross-Docking:Minimal dwell-time freight consolidation requiring precise inbound-outbound synchronization. Food and beverage retailers in the Southeast demand this for temperature-controlled supply chains.
- Hub and Spoke:Centralized sortation feeding regional last-mile spokes. FedEx Logistics extends integrated air-ground networks into dedicated retail replenishment lanes through this configuration.
- Last Mile Delivery:Final-mile execution with sub-24-hour service windows. Consumer expectations compress transit timelines and expand shared-use warehousing among mid-market retailers.
Hub and spoke carries the heaviest infrastructure burden while last mile delivery expands most quickly.
Customer Type:
Application requirements diverge sharply between compliance-heavy large enterprises and agility-prioritized startups.
- Small Businesses:Shared-use fulfillment networks with volume-flexible contracts. These retailers convert fixed logistics infrastructure into variable costs through 3PL partnerships.
- E-commerce Retailers:High-velocity fulfillment with returns processing integration. GXO Logistics anchors position through robotics-heavy centers that reduce unit labor costs for this segment.
- Large Enterprises:Integrated control-tower visibility across transportation and warehousing. Procurement consolidation favors 3PLs with unified technology platforms spanning inventory and fleet management.
- Startups:API-first onboarding with minimal legacy system integration. C.H. Robinson Worldwide leverages digital freight brokerage platforms to serve this segment across fragmented truckload markets.
Large enterprises anchor contract value while startups drive platform innovation cycles.
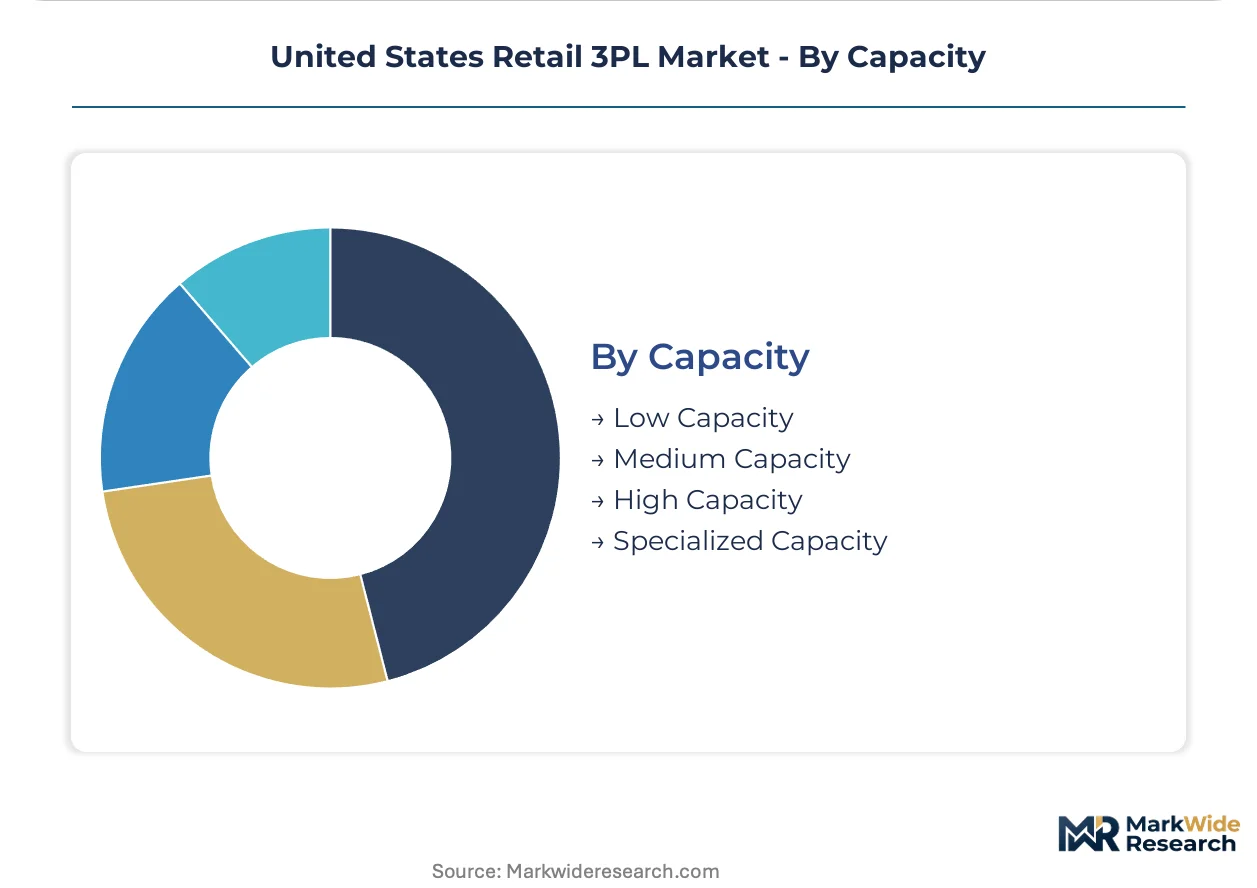
Capacity:
Supply concentration in high-capacity automated facilities creates tiered access barriers.
- Low Capacity:Flexible warehousing for seasonal demand spikes and promotional surges. Regional carriers serve this tier with limited compliance infrastructure.
- Medium Capacity:Multi-client facilities with standardized WMS platforms. OSHA warehouse safety standards accelerate consolidation toward 3PLs with dedicated compliance teams.
- High Capacity:Automated fulfillment centers at 200,000+ square foot thresholds. DTC brands deploy autonomous mobile robots in goods-to-person configurations previously reserved for enterprise operators.
- Specialized Capacity:Temperature-controlled and hazardous materials infrastructure. EPA Phase 2 greenhouse gas emissions rules elevate compliance costs that favor scaled operators with in-house regulatory teams.
High capacity commands the steepest investment requirements while specialized capacity captures the strongest pricing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California's Inland Empire corridor exceeds that of Midwestern secondary markets by a factor of two to three, reflecting vacancy rates below 4% versus 8-12% in Columbus or Indianapolis. This asymmetry concentrates capital deployment toward automated fulfillment centers on the West Coast while pushing volume-sensitive retailers toward central positioning strategies.
California
E-commerce absorption rates in the Inland Empire distribution cluster pull investment toward robotics-heavy fulfillment centers serving West Coast demand. The California Air Resources Board's Advanced Clean Trucks regulation mandates zero-emission vehicle sales quotas that elevate compliance costs for regional carriers. Los Angeles-Long Beach port complex throughput drives drayage demand and concentrates 3PL warehousing within the 60-mile inland radius.
Texas
Dallas-Fort Worth industrial vacancy rates below 4% inflate site selection costs and extend facility commissioning timelines for retail 3PL operators. The Texas Department of Transportation's freight corridor investments improve last-mile connectivity to suburban population centers. Houston's petrochemical infrastructure supports specialized capacity for hazardous materials handling in retail chemical and cosmetics distribution.
Illinois
Chicago's central rail-hub positioning enables two-day ground coverage of coastal population centers at lower land costs than coastal markets. The Illinois Commerce Commission's motor carrier safety enforcement aligns with FMCSA hours-of-service constraints on driver availability. Rockford and Joliet sub-markets attract automated fulfillment investment from retailers seeking Midwest distribution redundancy.
Ohio
Columbus offers lower land costs and central positioning for e-commerce fulfillment networks targeting East Coast and Midwest consumers simultaneously. The Ohio Department of Transportation's highway freight programs support dedicated fleet arrangements with large 3PL providers. Rickenbacker Airport's cargo infrastructure anchors air-ground integration for high-velocity retail replenishment.
Georgia
Atlanta's southeastern rail and highway nexus positions 3PL operators for next-day coverage of Florida and Carolinas consumer markets. The Georgia Department of Transportation's freight and logistics plans prioritize last-mile corridor improvements in exurban counties. Savannah port expansion drives inland warehousing demand along the I-16 and I-75 corridors for import-dependent retailers.
United States Retail 3PL Market Competitive Landscape
Concentration sits with scaled national operators possessing embedded compliance infrastructure and unified technology platforms spanning inventory, order, and fleet management. Regional carriers lacking real-time fleet visibility systems face displacement as FMCSA electronic logging device mandates compress driver capacity. Three archetypes dominate: integrated parcel-network extensions, digital freight brokerage platforms, and robotics-heavy fulfillment specialists. Competitive moves center on M&A consolidation of mid-market warehousing operators and strategic partnerships for micro-fulfillment network expansion.
Within the integrated network tier, FedEx Logistics and UPS Supply Chain Solutions anchor positions through air-ground infrastructure extensions into dedicated retail replenishment lanes. C.H. Robinson Worldwide occupies the digital brokerage archetype with freight-matching platform scale across fragmented truckload markets. GXO Logistics exemplifies the automation-heavy fulfillment specialist, deploying autonomous mobile robots in goods-to-person configurations that reduce unit labor costs for high-velocity e-commerce operations.
| Leading Market Players |
|---|
| DHL Supply Chain |
| C.H. Robinson Worldwide, Inc. |
| UPS Supply Chain Solutions |
| GXO Logistics, Inc. |
| CEVA Logistics |
| Kuehne + Nagel |
| FedEx Logistics, Inc. |
| Expeditors International of Washington, Inc. |
| Ryder System, Inc. |
| Others |
Value Network & Pricing Analysis
Autonomous mobile robot deployments replacing conventional pick-to-cart labor pools simultaneously compress unit fulfillment costs below $3.50 per order in select automated environments and redraw facility location economics toward high-vacancy Midwestern secondary markets. This substitution dynamic redistributes pricing power from labor-dependent regional carriers toward scaled operators with embedded robotics infrastructure and compliance teams.
Pricing Analysis
The customization-premium spread separates configured-to-order dedicated fleet arrangements from standard shared-use warehousing contracts across the United States retail 3PL landscape. Contract-based long-term offtake structures dominate enterprise relationships, while per-unit transactional pricing governs mid-market spot demand. Price differentiation rests on automation density and FMCSA compliance certification tier, with small businesses exhibiting acute price sensitivity and large enterprises prioritizing service-level guarantees. Margins are tightening in labor-dependent transportation brokerage as digital freight platforms compress procurement cycles and expose rate transparency.
Supply Chain Analysis
Just-in-time inventory strategies dominate high-velocity e-commerce fulfillment, while strategic stockpiling persists among food and beverage retailers requiring temperature-controlled redundancy. Supply concentration centers on the United States, with Mexico anchoring nearshoring alternatives for cross-border consolidation and Canada supporting specialized cold-chain infrastructure. Raw material dependencies include warehouse automation hardware, heavy-duty truck chassis, and diesel fuel feedstocks. Single-source vulnerability concentrates in California's Inland Empire distribution corridor where vacancy rates below 4% create logistics chokepoints. Distribution runs through hub-and-spoke configurations feeding regional last-mile spokes, with micro-fulfillment nodes emerging as satellite extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across mid-market warehousing operators and regional carrier tiers creates acquisition opportunities as e-commerce retailers consolidate vendor relationships and demand unified control-tower visibility.
For Market Incumbents: Consolidate through targeted acquisition of OSHA-compliant mid-market warehousing operators lacking capital for autonomous mobile robot deployment. Acquire dedicated safety compliance teams to defend margin position against heightened enforcement of powered industrial truck regulations. Scale robotics-heavy fulfillment centers in Columbus and Indianapolis to exploit land cost arbitrage versus coastal markets. For New Entrants and Emerging Players: Anchor in reverse logistics integration white space where returns processing represents 15-20% of e-commerce fulfillment costs and incumbent specialization remains thin. Target Midwestern secondary markets with EPA SmartWay-certified fleet offerings that capture sustainability scorecard premiums from shipper procurement teams. Deploy API-first warehouse management system architectures to compress onboarding cycles for startup retailers running proprietary order management systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional carriers possessing FMCSA compliance infrastructure but lacking robotics capital for tier migration. Five-to-ten year viability hinges on automation deployment pace and regulatory harmonization around autonomous vehicle exemptions. Watch California Air Resources Board zero-emission vehicle mandate spread to other states as inflection indicator for fleet replacement capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-Heavy Fulfillment Center Expansion | Autonomous mobile robots in goods-to-person configurations reduce unit labor costs for GXO Logistics and comparable operators. |
| Digital Freight Platform Integration | C.H. Robinson Worldwide leverages freight-matching scale to defend pricing power across fragmented truckload markets. |
| Micro-Fulfillment Network Partnership | FedEx Logistics extends air-ground infrastructure into shared-use warehousing for mid-market DTC brands. |
| Reverse Logistics Capability Buildout | Specialized refurbishment and liquidation infrastructure captures returns processing demand from flash-sale retailers. |
| EPA SmartWay Certification Program | Verified emissions reductions create preference premiums on shipper sustainability scorecards for certified fleets. |
Research Methodology
A standing panel of 3PL operations executives, transportation brokerage directors, warehouse automation engineers, and retail supply chain procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FMCSA regulatory filings, Department of Transportation hours-of-service enforcement data, OSHA warehouse safety incident reports, and EPA Phase 2 greenhouse gas compliance disclosures. Bottom-up facility-level capacity assessments triangulated against top-down market sizing from trade association absorption metrics.
Consistency checks validated volume and value outputs against external benchmarks including industrial vacancy rate surveys from brokerage houses and automation capital expenditure disclosures from publicly traded operators. Segmentation modeling spanned service type, delivery model, customer archetype, and capacity tier across the projection horizon. CAGRs were derived from regression analysis of historical absorption rates against e-commerce penetration trajectories and driver pool contraction trends from Drug and Alcohol Clearinghouse data.
Decision-makers should treat outputs as directional under assumptions of continued e-commerce volume growth and regulatory stability around autonomous vehicle deployment timelines; material deviation in diesel price volatility or California emissions rule adoption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
India Intra-City Logistics Market
Transportation & Logistics
Thailand Road Freight Transport Market
Transportation & Logistics
Parcel Delivery Market
Transportation & Logistics
Japan Road Freight Transport Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Canada Customs Brokerage Market
Transportation & Logistics
Refrigerated Transport Market