
 Mexico Cold Chain Logistics Market | 2026-2036
Mexico Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Cold Chain Logistics Market Insights
HACCP certification is collapsing as the baseline qualification for cold chain operators seeking pharmaceutical and fresh produce contracts. Frialsa Frigorificos leverages its specialized frozen warehousing footprint to dominate northern Mexico's protein export corridor. Americold Logistics sustains temperature integrity across multi-modal handoffs through proprietary warehouse management systems. Lineage Logistics anchors its position with automated blast freezing capacity that serves Pacific coast seafood processors.
Mexico cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods from origin through final delivery, requiring continuous maintenance between 25°C and -30°C depending on product category, with refrigeration units employing cascade or single-stage compression systems using synthetic or natural refrigerants. The primary purpose is preserving biochemical stability across pharmaceuticals, fresh produce, and protein products while satisfying COFEPRIS, USDA equivalence, and customer audit requirements. Warehousing commands margin concentration due to real estate scarcity near Mexico City and Guadalajara, while IoT Solutions represent the fastest-expanding technology category as shippers replace manual temperature logs with real-time cloud telemetry. Dairy end users increasingly demand sub-zero distribution networks that eliminate temperature excursion risks during last-mile delivery in tropical southern states.
COFEPRIS enforces pharmaceutical storage and distribution standards that mandate validated cold rooms and documented chain-of-custody protocols for vaccines and biologics. NOM-051-SCFI/SSA1-2010 and evolving SEMARNAT refrigerant regulations are accelerating fleet replacement toward lower-GWP refrigeration units across Mexican transport operators. SADER sanitary checkpoints at state borders enforce temperature compliance for interstate meat and dairy movements. Stakeholders must monitor whether proposed updates to Mexico's General Law of Climate Change will impose carbon accounting obligations on refrigerated transport fleets before committing to long-term equipment procurement cycles.
Market Dynamics
COFEPRIS pharmaceutical storage mandates and SEMARNAT refrigerant phase-down rules are compressing equipment replacement cycles across Mexican cold chain operators. Fleet owners face simultaneous pressure to validate temperature integrity for biologics while retiring high-GWP refrigeration units.
Growth Catalysts
- COFEPRIS cold chain validation:Biologics distributors must deploy validated cold rooms and documented chain-of-custody protocols, expanding demand for compliant warehousing in Mexico City and Guadalajara.
- IoT telemetry adoption:Real-time cloud monitoring replaces manual temperature logs, enabling pharmaceutical shippers to satisfy customer audit requirements without labor-intensive documentation.
- Bajío agricultural concentration:Strawberry and berry exporters in Guanajuato and Michoacán require dedicated pre-cooling and controlled-atmosphere storage to access US retail channels.
Market Restraints
- Real estate scarcity:Cold storage development near Mexico City faces land cost inflation and zoning restrictions that limit greenfield warehouse construction.
- Natural refrigerant capex burden:CO2 and ammonia systems require 40-60% higher upfront investment than synthetic alternatives, straining mid-size fleet operators.
- Interstate checkpoint delays:SADER sanitary inspections at state borders create temperature excursion risks for meat and dairy movements between northern production zones and central consumption markets.
Strategic Opportunities
- Yucatán Peninsula seafood export corridor:Underdeveloped blast freezing and containerized cold storage capacity creates white space for Pacific coast logistics operators to establish captive supply networks.
- Dual-use pharmaceutical-food facilities:COFEPRIS-certified warehouses can capture overflow demand from fresh produce exporters during pharmaceutical volume troughs.
- Last-mile electric refrigeration:Battery-powered transport refrigeration units align with Mexico City emissions restrictions while serving tropical southern states where diesel unit reliability degrades.
Industry Challenges
- HVAC-R technician shortage:Cascade refrigeration systems and CO2 transcritical installations require specialized certification that Mexican technical institutes are not producing at replacement rates.
- Multi-modal temperature integrity:Port-to-warehouse handoffs at Lázaro Cárdenas and Manzanillo create custody gaps where manual data logging fails to capture excursion events.
- Legacy warehouse management integration:Automated blast freezing and robotic palletizing systems require API connectivity that older Mexican cold storage facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Cold Chain Logistics Market |
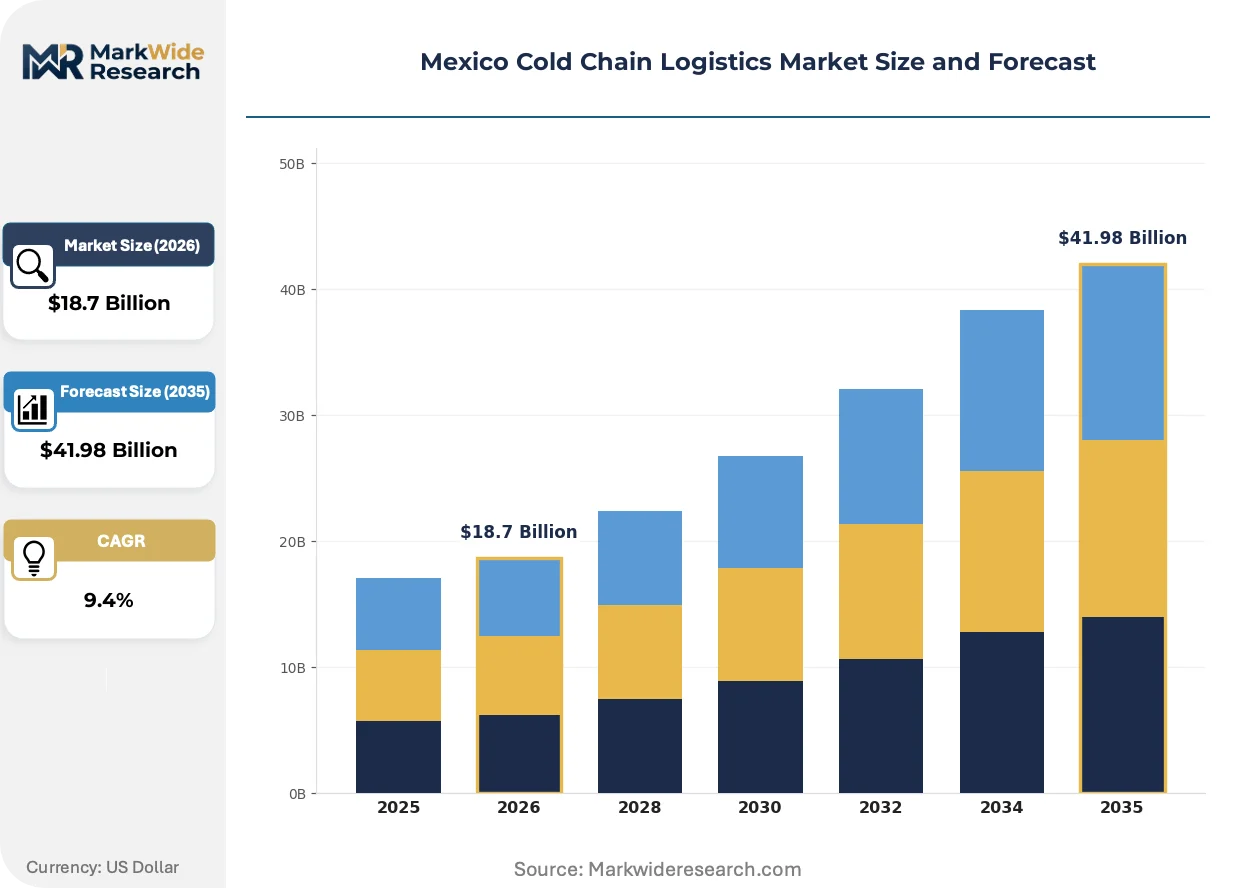
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution End User: Pharmaceuticals, Food & Beverage, Floriculture, Dairy Temperature Range: Chilled, Frozen, Ambient, Sub-zero Technology: IoT Solutions, Temperature Monitoring, Refrigeration Units, Tracking Systems |
| Companies Covered | DHL Group, Frialsa Frigorificos, United Parcel Service, Americold Logistics, Lineage Logistics, FedEx Logistics Mexico, Kuehne + Nagel Mexico, CEVA Logistics Mexico, Maersk Mexico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Cold Chain Logistics Market Trends and Innovations
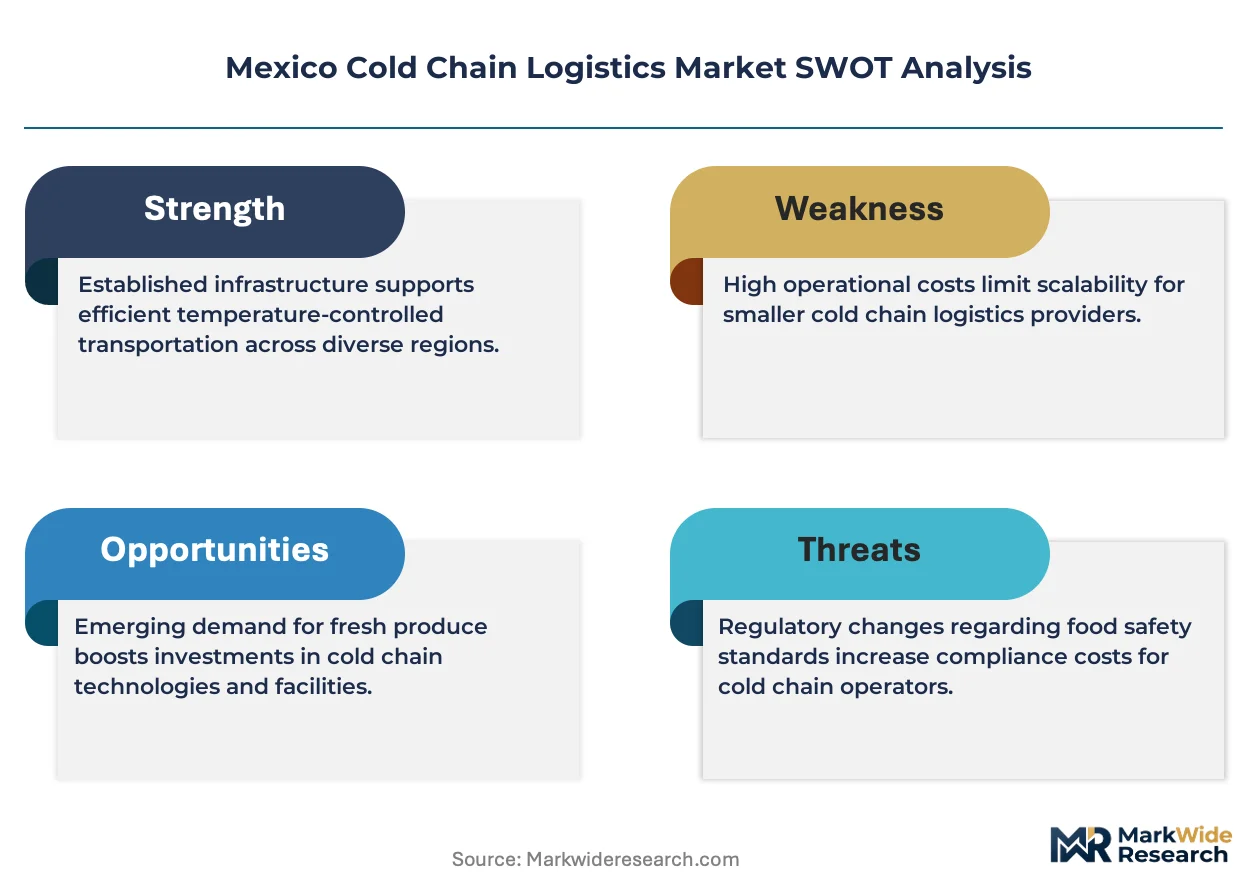
Refrigeration technology deployment is splitting between premium pharmaceutical-grade systems and cost-optimized produce handling, with regulatory compliance as the dividing line. This bifurcation reshapes vendor strategies and buyer procurement patterns simultaneously.
Telematics hardware is bifurcating cold chain visibility into two performance tiers. Pharmaceutical shippers demand satellite-connected sensors with 30-second reporting intervals and blockchain-anchored custody records. Fresh produce distributors accept cellular-based loggers with 15-minute intervals that satisfy USDA equivalence without premium pricing. The technology divergence is compressing mid-tier sensor vendors into commodity positioning while enabling specialized players to capture pharmaceutical audit premiums.
SEMARNAT's accelerating hydrofluorocarbon phase-down timeline is forcing transport refrigeration fleet decisions. Operators must choose between near-term synthetic refrigerant compliance and long-term natural refrigerant infrastructure. Dairy and protein distributors in tropical Veracruz and Chiapas face compounded technical risk as high-ambient conditions degrade synthetic refrigerant performance while natural alternatives require untested service networks.
Certification-driven procurement now separates contract winners from price competitors. Retailers and pharmaceutical manufacturers specify HACCP-plus-GDP (Good Distribution Practice) combined audits that exceed baseline regulatory minimums. Cold chain operators in Querétaro and San Luis Potosí are restructuring quality departments to manage dual certification maintenance, recognizing that audit scores determine allocation in contracted lane assignments.
Mexico Cold Chain Logistics Market Segmentation
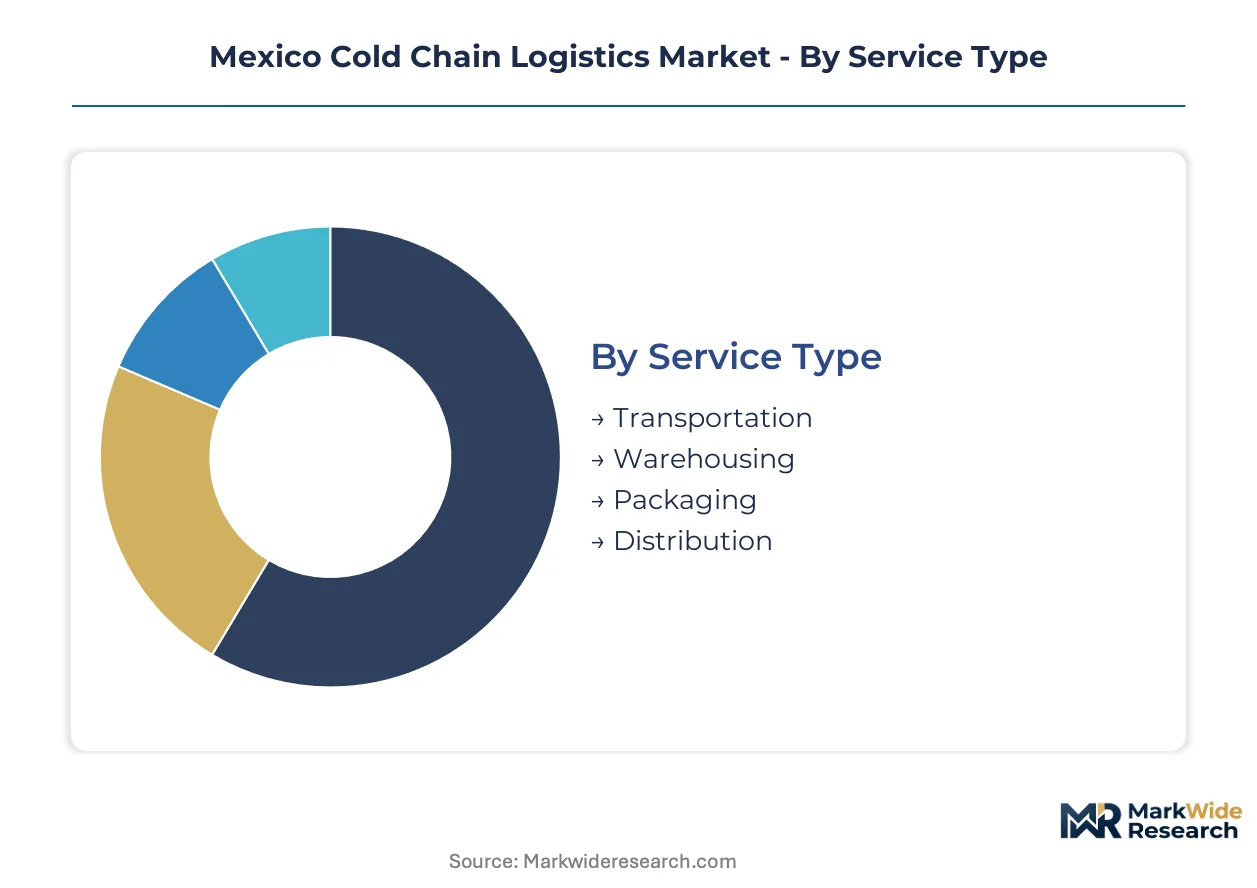
Cold chain logistics in Mexico operates across distinct operational layers where service specialization, temperature precision, and regulatory compliance create divergent margin profiles. Segment boundaries increasingly blur as pharmaceutical-grade capabilities migrate into premium food handling.
Service Type:
Domestic consumption corridors anchor warehousing demand while export-oriented transportation commands premium pricing across the Bajío and northern border zones.
- Transportation:Refrigerated trucking fleets with multi-temperature zone trailers handle interstate protein and dairy movements. SADER checkpoint delays at state borders create excursion risks that specialized carriers mitigate through pre-cooled staging yards in Querétaro.
- Warehousing:Validated cold rooms with COFEPRIS-compliant documentation systems concentrate near Mexico City and Guadalajara where land scarcity inflames lease rates. Automated blast freezing and robotic palletizing now separate tier-one facilities from legacy operators.
- Packaging:Insulated shippers with phase-change materials protect biologics during last-mile delivery in tropical southern states where ambient temperatures degrade passive cooling performance.
- Distribution:Cross-dock facilities with rapid product turnover serve quick-service restaurant chains and retail banners requiring daily replenishment cycles.
Warehousing holds the largest share; momentum sits with distribution as quick-commerce formats compress delivery windows.
End User:
Regulatory intensity separates pharmaceutical-grade operations from commodity food handling, with certification thresholds determining facility investment levels.
- Pharmaceuticals:Vaccine and biologics distributors must deploy validated cold rooms with documented chain-of-custody protocols. COFEPRIS mandates are expanding refrigerated capacity across Mexican states as domestic vaccine production scales.
- Food & Beverage:Strawberry and berry exporters in Guanajuato require dedicated pre-cooling and controlled-atmosphere storage to access US retail channels through USDA-equivalent certification.
- Floriculture:Rose and ornamental producers in Michoacán leverage temperature-controlled logistics to extend vase life during trans-Pacific shipments to US wholesalers.
- Dairy:Sub-zero distribution networks eliminate temperature excursion risks during last-mile delivery in tropical Veracruz and Chiapas where high-ambient conditions stress mechanical refrigeration.
Food & Beverage holds the largest share; Pharmaceuticals are climbing the fastest on COFEPRIS compliance spending.
Temperature Range:
Equipment configuration and energy intensity vary dramatically across temperature bands, with sub-zero systems commanding specialized technical expertise.
- Chilled:Systems maintaining 0°C to 4°C dominate fresh produce and dairy distribution through single-stage compression units using lower-GWP synthetic refrigerants.
- Frozen:Blast freezing capacity serves Pacific coast seafood processors and northern Mexico protein export corridors with rapid temperature pull-down capabilities.
- Ambient:Controlled-temperature storage without active refrigeration handles chocolate, wine, and certain pharmaceuticals where thermal stability suffices.
- Sub-zero:Cascade refrigeration systems reaching -30°C preserve ultra-frozen seafood and certain biologics; Mexican technical institutes produce insufficient certified technicians for replacement rates.
Chilled holds the largest share; Sub-zero is gaining share fastest on pharmaceutical and premium seafood demand.
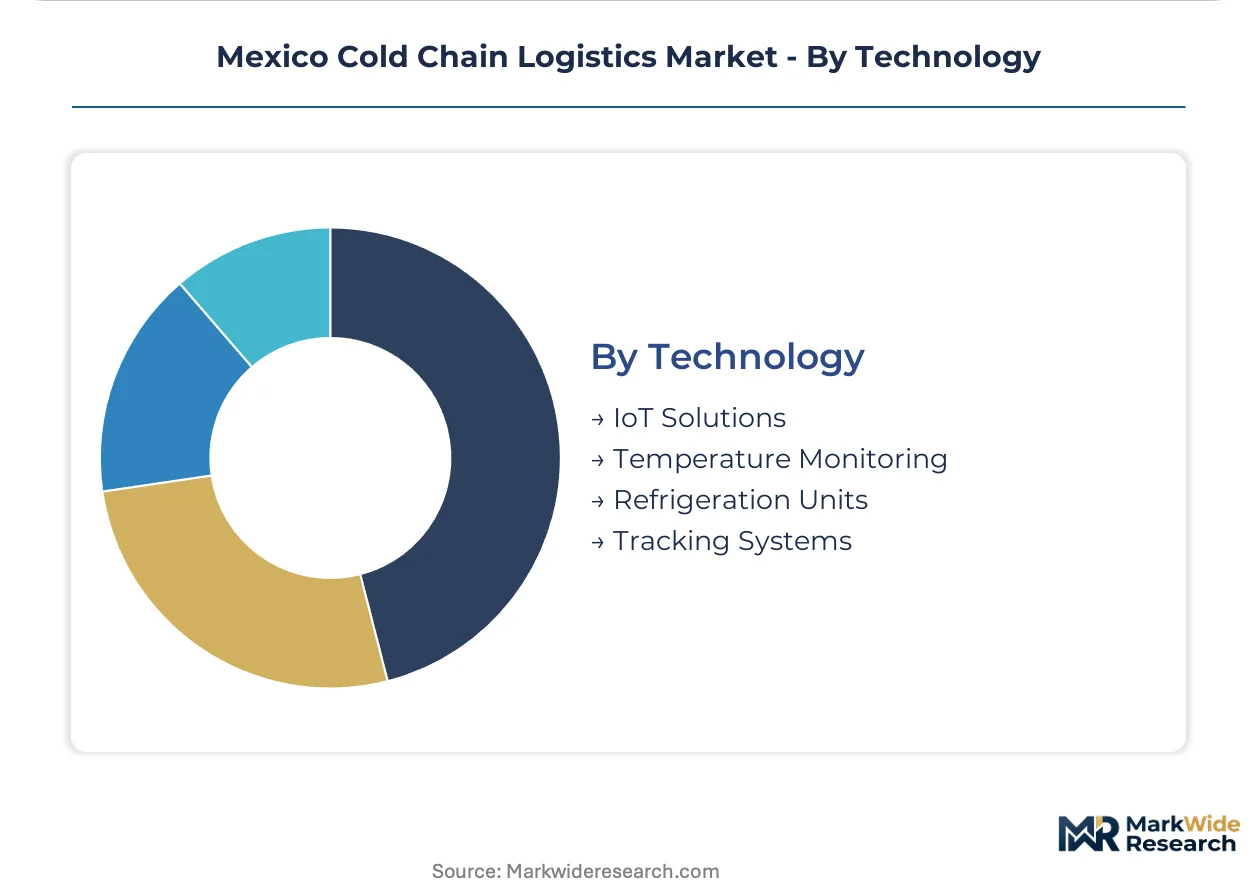
Technology:
Adoption timelines split between real-time telemetry for audit-intensive verticals and cost-optimized monitoring for commodity produce.
- IoT Solutions:Real-time cloud telemetry replaces manual temperature logs, enabling pharmaceutical shippers to satisfy customer audit requirements without labor-intensive documentation. Cellular and satellite connectivity tiers match sensor reporting intervals to compliance stringency.
- Temperature Monitoring:Blockchain-anchored custody records with 30-second reporting intervals serve biologics distributors, while 15-minute cellular loggers satisfy fresh produce USDA equivalence.
- Refrigeration Units:SEMARNAT's hydrofluorocarbon phase-down forces fleet decisions between near-term synthetic compliance and long-term natural refrigerant infrastructure requiring 40-60% higher upfront investment.
- Tracking Systems:GPS-enabled fleet management with geofencing capabilities secures high-value pharmaceutical loads against diversion and theft during interstate movements.
Refrigeration Units holds the largest share; IoT Solutions are expanding most quickly as manual documentation becomes commercially untenable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
COFEPRIS pharmaceutical storage mandates and SEMARNAT refrigerant regulations are redistributing cold chain investment across Mexican sub-regions. Operators prioritize locations that combine regulatory compliance infrastructure with export corridor access.
Mexico City Metropolitan Zone
Vaccine distributors and biologics manufacturers require validated cold rooms with documented chain-of-custody protocols. COFEPRIS enforcement concentrates compliance investment in the capital region. Toluca and Cuautitlán Izcalli host the densest cluster of pharmaceutical-grade warehousing serving domestic distribution networks.
Bajío Agricultural Corridor
Strawberry and berry exporters in Guanajuato and Michoacán drive demand for pre-cooling and controlled-atmosphere storage. SADER sanitary checkpoints at state borders enforce temperature compliance for interstate movements. Irapuato and Celaya function as consolidation hubs where produce exporters access USDA-equivalent certification for US retail channels.
Nuevo León
Monterrey anchors northern Mexico's protein export corridor with blast freezing capacity serving beef and poultry processors. SEMARNAT's hydrofluorocarbon phase-down accelerates fleet replacement toward natural refrigerant systems. Apodaca and Salinas Victoria concentrate multi-temperature warehousing at the intersection of domestic consumption and cross-border logistics.
Jalisco
Guadalajara's pharmaceutical manufacturing base expands refrigerated distribution networks for domestic vaccine production. Real estate scarcity near the metropolitan zone inflames cold storage lease rates. El Salto and Tlajomulco de Zúñiga attract automated warehousing investment as operators seek greenfield development outside core urban restrictions.
Yucatán Peninsula
Underdeveloped blast freezing capacity creates white space for seafood export logistics. High-ambient tropical conditions stress mechanical refrigeration reliability. Mérida and Progreso offer port access for Pacific coast operators establishing captive supply networks for octopus and grouper processors.
Mexico Cold Chain Logistics Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base splits between multinational platforms with integrated global networks and domestic operators with regional density. Three archetypes dominate: temperature-validated pharmaceutical specialists, multi-temperature food logistics providers, and port-centric export handlers. Capacity expansion and certification stacking represent the dominant competitive moves as operators seek COFEPRIS validation alongside HACCP-plus-GDP combined audits.
Among integrated logistics platforms, DHL Group and United Parcel Service occupy positions spanning pharmaceutical validation and express delivery density. Frialsa Frigorificos exemplifies the regional specialist archetype with concentrated frozen warehousing footprints. Americold Logistics and Lineage Logistics represent the scale-driven real estate play, anchoring automated blast freezing and robotic palletizing capabilities near Pacific coast seafood processors and northern protein corridors.
| Leading Market Players |
|---|
| DHL Group |
| Frialsa Frigorificos |
| United Parcel Service |
| Americold Logistics |
| Lineage Logistics |
| FedEx Logistics Mexico |
| Kuehne + Nagel Mexico |
| CEVA Logistics Mexico |
| Maersk Mexico |
| Others |
Pricing and Supply Chain Analysis
Natural refrigerant substitution for hydrofluorocarbon systems is simultaneously redrawing equipment sourcing geography and compressing margin structures across Mexican cold chain operators. SEMARNAT's accelerated phase-down timeline forces fleet owners toward CO2 and ammonia infrastructure that demands 40-60% higher capital outlays while technical certification scarcity inflates service premiums.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade warehousing and commodity produce handling. Three-tier pricing structure across COFEPRIS-validated, HACCP-certified, and baseline cold storage segments reflects audit intensity and documentation depth. Cost compression in standard-tier facilities is intensifying because land scarcity near Mexico City and Guadalajara inflates lease rates faster than revenue growth. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, while vaccine distributors accept premium positioning for validated chain-of-custody protocols.
Supply Chain Analysis
China and the United States anchor refrigeration equipment manufacturing, with Mexican assembly operations concentrated in Nuevo León and Querétaro. Compressor units, IoT sensors, and insulated paneling feed from East Asian component networks tethered to Pacific port logistics. Single-source vulnerability sits with cascade refrigeration system controllers sourced from limited German and Japanese suppliers. Distribution runs through Mexico City metropolitan consolidation hubs before radiating to Bajío agricultural corridors and northern border export zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT telemetry and compliance documentation services are expanding faster than warehousing square footage, creating recurring-revenue attach opportunities that outperform capital-intensive cold storage development.
For Market Incumbents: Compound certification depth by stacking COFEPRIS validation atop existing HACCP frameworks to capture pharmaceutical overflow demand during produce volume troughs. Deepen backward integration into automated blast freezing technology to defend margin position against regional specialists with captive freezing capacity. Threat substitution by electric last-mile refrigeration units demands preemptive fleet electrification investment before Mexico City emissions restrictions harden. For New Entrants and Emerging Players: Anchor in Yucatán Peninsula seafood export corridors where blast freezing capacity remains underdeveloped against Pacific coast processor demand. White space concentrates in tropical southern states where high-ambient conditions degrade incumbent diesel unit reliability. Go-to-market positioning should emphasize battery-powered transport refrigeration with satellite telemetry for audit-intensive octopus and grouper export lanes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cold storage operators holding concentrated Bajío or northern Mexico footprints but lacking pharmaceutical certification depth. Long-term viability hinges on regulatory compliance infrastructure rather than commodity storage volume. Signal to monitor: COFEPRIS enforcement intensity at state-level SADER checkpoints as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Certification Investment | Validates cold rooms for vaccine distribution, unlocking pharmaceutical contract access in Mexico City corridor. |
| Natural Refrigerant Fleet Conversion | Aligns with SEMARNAT hydrofluorocarbon phase-down while future-proofing against carbon accounting obligations. |
| IoT Telemetry Platform Deployment | Replaces manual temperature logs with blockchain-anchored custody records for biologics audit requirements. |
| Yucatán Peninsula Capacity Buildout | Captures underdeveloped blast freezing demand from Pacific coast seafood processors seeking export logistics. |
| Dual-Use Facility Development | Enables COFEPRIS-certified warehouses to serve pharmaceutical and fresh produce demand through volume troughs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold chain logistics directors, pharmaceutical distribution managers, SADER compliance officers, refrigerated fleet procurement leads, and warehousing real estate developers. Secondary validation drew from COFEPRIS regulatory filings, SEMARNAT refrigerant phase-down schedules, SADER sanitary checkpoint records, customs trade data for refrigerated equipment imports, and refrigerated warehousing lease rate indices. Bottom-up capacity modeling and top-down market sizing were triangulated against operator-reported utilization rates.
Across the analysis window, value projections were derived from segment-level CAGRs applied to baseline capacity and pricing data. Segmentation dimensions modeled include service type, end-user vertical, temperature range tier, and technology adoption intensity. Forecast inputs incorporated SEMARNAT enforcement timelines, COFEPRIS validation expansion patterns, and IoT sensor penetration curves reported by cellular and satellite connectivity providers.
Material uncertainties — regulatory acceleration or delay, refrigerant technology substitution rates, and land use restriction changes — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance cost trajectories and equipment replacement cycles. Recalibration cycles align with material shifts in SEMARNAT rulemaking and COFEPRIS enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
United States Retail 3PL Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
Pipeline Transportation Software Market
Transportation & Logistics
Latin America Customs Brokerage Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
India Direct-To-Consumer (D2C) Logistics Market
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
Road Haulage Market