
 Manganese Dioxide Lithium Battery Market | 2026-2036
Manganese Dioxide Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Manganese Dioxide Lithium Battery Market Insights
Medical device power requirements are restructuring procurement patterns across the manganese dioxide lithium battery supply chain. Tosoh Corporation sustains Japanese domestic cathode material quality benchmarks through integrated manganese refining operations. Xiangtan Electrochemical Scientific dominates electrolytic manganese dioxide output from its Hunan manufacturing base. CITIC Dameng Holdings anchors global ore-to-chemical supply security through captive mine assets in Guangxi and Australia.
Manganese dioxide lithium batteries employ manganese dioxide as the cathode active material paired with lithium metal or lithium alloy anodes, delivering nominal voltages of 3.0V in primary configurations and stable discharge profiles under low-drain conditions. These electrochemical systems serve as compact, long-shelf-life power sources for consumer electronics, medical implants, and industrial monitoring equipment. Primary batteries occupy the dominant revenue position due to irreplaceable demand in pacemakers, smart meters, and military communication devices where recharging infrastructure is absent. Secondary batteries represent the fastest-expanding category as researchers advance lithium-manganese dioxide chemistries toward limited cycle stability for wearable health monitors. Industrial users command the deepest margin pools through multi-year supply agreements with specified purity grades and lot traceability.
The EU Battery Regulation and REACH compliance frameworks in Europe mandate carbon footprint disclosure and recycled content thresholds for manganese-based active materials entering member states. China's SAMR enforces GB/T standards governing electrolytic manganese dioxide purity specifications for domestic battery manufacturing. Japan's METI coordinates national stockpiling policies for critical manganese resources to insulate domestic cell producers from supply disruption. Stakeholders must monitor evolving cathode chemistry substitution risks as lithium iron phosphate and sodium-ion technologies encroach on traditional manganese dioxide applications in cost-sensitive segments.
Market Dynamics
Medical device manufacturers are consolidating cathode material procurement around certified electrolytic manganese dioxide suppliers capable of lot-level traceability for implantable power cells. This demand concentration is restructuring supplier qualification timelines and purity benchmarking across the supply chain.
Growth Catalysts
- EU Battery Regulation carbon disclosure mandates:Battery manufacturers sourcing manganese dioxide for European medical device markets must document embedded emissions and recycled content thresholds, accelerating certified supplier adoption.
- Pacemaker and neurostimulator miniaturization:Implantable cardiac rhythm management devices require thinner form-factor cells with stable 3.0V discharge profiles, sustaining primary battery demand.
- Hunan and Jiangsu cathode precursor clusters:Concentrated electrolytic manganese dioxide production capacity in these provinces enables just-in-time raw material supply for East Asian cell manufacturers.
Market Restraints
- Manganese ore grade volatility:Fluctuating high-purity ore availability from South African and Gabonese deposits compresses cathode material margins during supply disruptions.
- Single-source dependency for medical-grade EMD:Three suppliers control qualified electrolytic manganese dioxide for FDA-cleared implantable batteries, creating concentration risk.
- Lithium iron phosphate substitution in consumer electronics:Cost-sensitive portable electronics manufacturers are transitioning to LFP cells for non-critical applications, eroding addressable volume.
Strategic Opportunities
- Remote patient monitoring wearables:Secondary lithium-manganese dioxide chemistries with limited cycle stability are penetrating ambulatory cardiac monitoring devices for home-based care.
- Japan METI critical mineral stockpiling:National manganese reserve policies create preferential offtake agreements for qualified cathode material suppliers.
- Industrial IoT sensor networks:Smart manufacturing facilities in Germany and South Korea are deploying manganese dioxide lithium batteries for wireless vibration and temperature monitoring nodes.
Industry Challenges
- Electrochemical engineer scarcity:Cell manufacturers face recruitment gaps for specialists capable of optimizing lithium-manganese dioxide interface stability in secondary configurations.
- Multi-jurisdiction certification complexity:Medical battery suppliers must synchronize FDA 510(k), EU MDR, and PMDA approval timelines for global implantable device launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manganese Dioxide Lithium Battery Market |
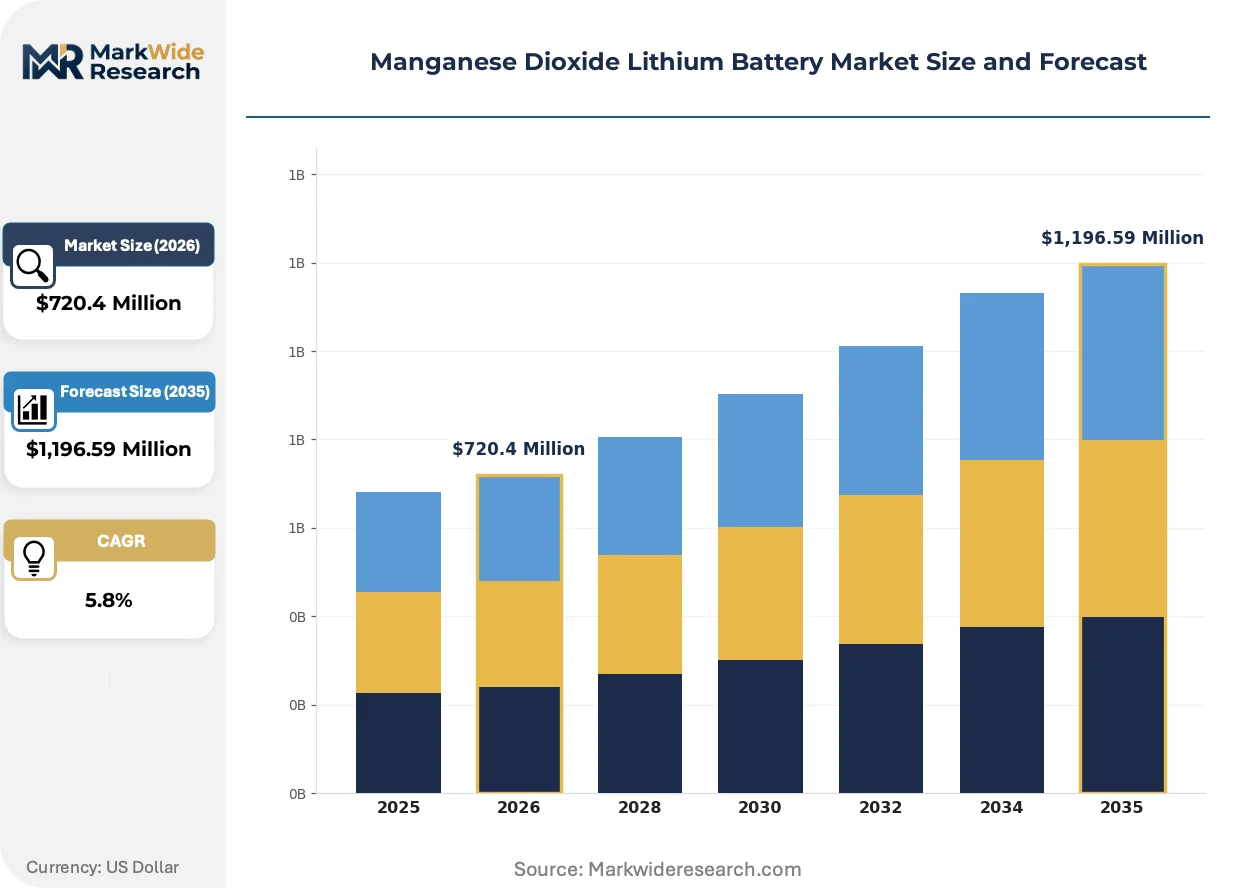
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,196.59 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Secondary Batteries, Rechargeable Batteries, Disposable Batteries Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Retail Customers, Industrial Users, OEMs, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | CITIC Dameng Holdings, Tosoh Corporation, Xiangtan Electrochemical Scientific, Prince International, Tronox Holdings, ERACHEM, Vibrantz, LANDF CORP, POSCO FUTURE M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manganese Dioxide Lithium Battery Market Trends and Innovations
Electrolytic manganese dioxide processing automation is compressing cathode material qualification cycles while regulatory carbon accounting is embedding traceability requirements into procurement contracts. These forces are reshaping how cell manufacturers qualify and source active materials.
Automated particle size distribution control systems are automating quality consistency in electrolytic manganese dioxide production lines. Medical battery manufacturers adopting these materials report reduced lot-to-lot variation in discharge curve stability. The technology is automating supplier audit frequency reductions for qualified cathode material streams.
REACH substance of very high concern screening protocols are extending manganese dioxide supplier registration timelines for EU market entry. Battery manufacturers must now submit full supply chain chemical safety dossiers before placing medical cells on European markets. Implantable device OEMs are responding by pre-qualifying dual-source EMD suppliers to mitigate regulatory delay risks.
Direct contracting between cathode material producers and medical device OEMs is displacing distributor-mediated procurement in high-reliability segments. Tier-one pacemaker manufacturers now negotiate multi-year manganese dioxide supply agreements with specified purity bands and forensic traceability. This pattern is most visible in Swiss and Japanese implantable device manufacturing clusters where supply security outweighs spot-price optimization.
Manganese Dioxide Lithium Battery Market Segmentation
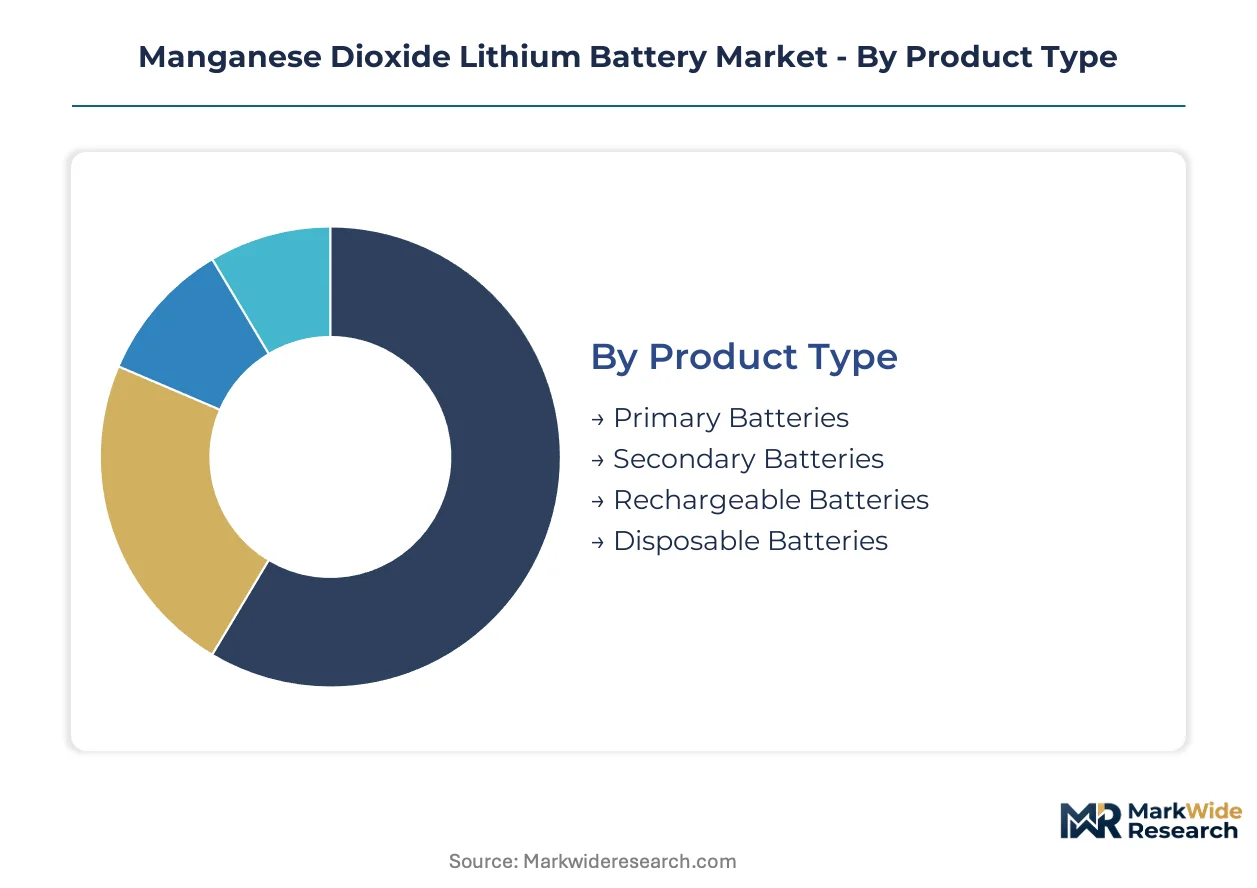
Segmentation in manganese dioxide lithium batteries reveals how procurement patterns diverge between irreplaceable medical applications and cost-sensitive consumer segments. Understanding these divisions exposes where margin pools concentrate and where substitution risks loom largest.
Product Type:
Upgrade cycles vary dramatically across electrochemical configurations, with primary cells offering decades-long service life in implantables while secondary formats face compressed replacement windows in wearable monitors.
- Primary Batteries:Non-rechargeable cells with lithium metal anodes and manganese dioxide cathodes deliver stable 3.0V output across multi-year discharge profiles. Demand concentrates in Swiss and Japanese pacemaker manufacturing clusters where FDA and PMDA lot-traceability requirements sustain premium procurement. These cells command the deepest margins due to irreplaceable demand in cardiac rhythm management devices.
- Secondary Batteries:Limited-cycle rechargeable configurations are penetrating ambulatory cardiac monitoring wearables for home-based patient surveillance. Expansion concentrates in South Korean and German remote patient monitoring OEMs seeking lighter form factors than lithium-ion alternatives permit.
- Rechargeable Batteries:Advanced lithium-manganese dioxide chemistries with improved cycle stability target industrial IoT sensor networks requiring field-deployed power without maintenance access.
- Disposable Batteries:Single-use formats serve cost-optimized consumer electronics and military communication equipment where recharging infrastructure remains absent.
Volume placements concentrate in Primary Batteries; the faster expansion belongs to Secondary Batteries.
Application:
Cost tier differentiation separates medical-grade certification requirements from industrial procurement specifications, creating distinct supplier qualification pathways.
- Consumer Electronics:Portable devices including calculators, remote controls, and digital cameras utilize standard-grade manganese dioxide cells. Procurement concentrates in East Asian electronics manufacturing clusters around Shenzhen and Seoul where cost optimization dominates supplier selection.
- Industrial Equipment:Smart manufacturing facilities deploy these batteries for wireless vibration monitoring, temperature sensors, and asset tracking tags in Germany and South Korea. Demand drivers include explosion-safety certifications and extended operating temperature ranges.
- Electric Vehicles:Auxiliary power units and emergency backup systems in select EV architectures employ manganese dioxide cells for critical safety functions.
- Renewable Energy Storage:Remote monitoring equipment for solar and wind installations uses these cells for data transmission modules where grid connectivity is unavailable.
Revenue pools concentrate in Industrial Equipment; the steepest expansion trajectory appears in Consumer Electronics.
End User:
Customer type determines whether procurement flows through distributor networks or direct long-term agreements with forensic traceability requirements.
- Industrial Users:Manufacturing facilities and infrastructure operators negotiate multi-year supply agreements with specified purity grades and lot-level documentation. These buyers command the deepest margin pools through volume commitments and technical service requirements.
- OEMs:Medical device and electronics manufacturers pre-qualify dual-source suppliers to mitigate regulatory delay risks from REACH and EU MDR compliance frameworks.
- Retail Customers:Individual consumers purchase replacement cells through electronics retailers and online marketplaces with minimal technical specification involvement.
- Research Institutions:Universities and national laboratories procure specialized cell formats for electrochemical research and prototype development.
Contract value concentrates in Industrial Users; the fastest share gain belongs to OEMs.
Distribution Channel:
Supply concentration in Hunan and Jiangsu cathode precursor clusters shapes how finished cells reach end markets across different reliability tiers.
- Direct Sales:Tier-one pacemaker and neurostimulator manufacturers negotiate directly with qualified electrolytic manganese dioxide suppliers, bypassing distributor markups for implantable-grade materials.
- Distributors:Authorized industrial distributors maintain inventory of certified cells for medical device subcontractors and industrial automation integrators requiring rapid replenishment.
- Online Retail:E-commerce platforms serve consumer electronics replacement demand and small-scale industrial procurement with standard-grade products.
- Wholesalers:Volume resellers supply military and government procurement channels with specified shelf-life and storage condition documentation.
Transaction volume concentrates in Distributors; the most rapid channel expansion appears in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian cathode precursor production clusters supply the majority of global electrolytic manganese dioxide output, while medical device manufacturing concentrates in Swiss and Japanese implantable electronics corridors. This geographic split between raw material refining and high-value cell assembly shapes procurement logistics and regulatory compliance pathways across the value chain.
China
Hunan and Jiangsu provinces host concentrated electrolytic manganese dioxide production serving East Asian cell manufacturers with just-in-time raw material supply. SAMR enforces GB/T standards governing purity specifications for domestic battery manufacturing. Xiangtan Electrochemical Scientific anchors output from its Hunan manufacturing base, while CITIC Dameng Holdings secures ore-to-chemical supply through captive mine assets in Guangxi.
Japan
Domestic cathode material quality benchmarks sustain premium procurement for implantable medical devices requiring FDA and PMDA lot-traceability. METI coordinates national stockpiling policies for critical manganese resources to insulate domestic cell producers from supply disruption. Tosoh Corporation maintains integrated manganese refining operations serving Japanese medical battery manufacturers.
Switzerland
Swiss implantable device manufacturing clusters drive demand for certified electrolytic manganese dioxide with forensic traceability requirements. EU Battery Regulation carbon disclosure mandates apply to cells entering European medical device markets through Swiss distribution channels. Direct contracting between cathode material producers and Swiss OEMs is displacing distributor-mediated procurement in high-reliability segments.
Germany
Industrial IoT sensor networks in German smart manufacturing facilities deploy manganese dioxide lithium batteries for wireless vibration and temperature monitoring nodes. REACH substance of very high concern screening protocols extend supplier registration timelines for EU market entry. German automation integrators negotiate multi-year supply agreements with specified purity grades and lot-level documentation.
South Korea
Remote patient monitoring OEMs in South Korea seek secondary lithium-manganese dioxide chemistries with limited cycle stability for ambulatory cardiac monitoring wearables. POSCO FUTURE M participates in cathode material supply chains serving Korean electronics manufacturers. Seoul-based cell producers qualify dual-source EMD suppliers to mitigate regulatory delay risks from REACH compliance frameworks.
Manganese Dioxide Lithium Battery Market Competitive Landscape
Top-tier vendors anchor medical-grade electrolytic manganese dioxide supply, while mid-scale chemical processors serve industrial and consumer segments. The vendor base stratifies across three tiers: integrated mining-to-chemical conglomerates with captive ore assets, specialized electrochemical refiners focused on high-purity manganese dioxide, and diversified materials companies with battery-grade product lines. Strategic moves concentrate on backward integration into manganese ore assets and direct contracting partnerships with implantable device OEMs bypassing traditional distribution channels.
Within the integrated resource tier, CITIC Dameng Holdings exemplifies the mining-to-chemical archetype through captive assets spanning Guangxi and Australia. Among specialized electrochemical refiners, Xiangtan Electrochemical Scientific occupies a position representing concentrated Hunan-based production capacity. Tosoh Corporation anchors the quality-focused tier serving Japanese domestic medical battery manufacturers with integrated refining operations. These three entities represent distinct competitive positioning vectors across ore security, geographic production concentration, and quality certification depth.
| Leading Market Players |
|---|
| CITIC Dameng Holdings |
| Tosoh Corporation |
| Xiangtan Electrochemical Scientific |
| Prince International |
| Tronox Holdings |
| ERACHEM |
| Vibrantz |
| LANDF CORP |
| POSCO FUTURE M |
| Others |
Pricing and Supply Chain Analysis
Tier-one pacemaker manufacturers concentrate procurement around certified electrolytic manganese dioxide suppliers, anchoring contract-based long-term offtake agreements that bypass spot-market volatility. This buyer archetype concentration sustains premium pricing tiers for implantable-grade materials while industrial users negotiate volume-scaled standard-grade contracts.
Pricing Analysis
Margin tightening in medical-grade tiers reflects REACH compliance costs and dual-source qualification investments. Three-tier pricing structure across implantable-certified, industrial-standard, and consumer-economy levels separates FDA-cleared cathode materials from general-purpose cells. Cost-down pressure on consumer electronics grades accelerates as lithium iron phosphate substitutes erode addressable volume. Industrial users exhibit highest price sensitivity through competitive bidding, while Swiss and Japanese implantable OEMs prioritize supply security over unit cost.
Supply Chain Analysis
China's GB standards and the EU Battery Regulation are reshaping sourcing through domestic-content traceability mandates and carbon disclosure requirements. Electrolytic manganese dioxide supply concentrates in China, Japan, and South Korea, with Hunan and Jiangsu clusters feeding East Asian cell manufacturers. Raw material flows draw from South African and Gabonese ore deposits, Japanese refined chemical outputs, and Australian captive mine assets. Single-source vulnerability for medical-grade EMD creates concentration risk at three qualified suppliers. Distribution runs through direct contracting for implantable tiers and authorized industrial distributors for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards consolidation as EU Battery Regulation compliance costs force sub-scale cathode material processors toward exit or acquisition.
For Market Incumbents: Cement supply security through backward integration into Australian or Gabonese manganese ore assets and captive electrolytic manganese dioxide refining capacity. Deepen FDA and PMDA certification moats against emerging sodium-ion substitution threats in cardiac rhythm management applications. Prioritize direct contracting partnerships with Swiss and Japanese pacemaker OEMs to lock in multi-year offtake visibility. For New Entrants and Emerging Players: Launch via secondary lithium-manganese dioxide chemistries targeting South Korean and German remote patient monitoring wearables, where limited cycle stability requirements lower technical barriers. Penetrate industrial IoT sensor networks in German smart manufacturing facilities through explosion-safety certification and extended temperature range specifications. Lead with ambulatory cardiac monitoring applications as the most penetrable white-space segment. For Investors and Strategic Acquirers: The window for entry favors specialized electrochemical refiners with existing GB/T or JIS quality certifications and proven medical battery supplier relationships. Long-term viability hinges on cathode chemistry diversification resilience across the next decade. Watch lithium-manganese dioxide cycle stability breakthroughs in secondary configurations as the critical inflection signal for wearable health monitor penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Ore Assets | CITIC Dameng Holdings secures supply security through captive Guangxi and Australian mine holdings. |
| Long-term Supply Agreement with Medical OEMs | Direct contracting with Swiss pacemaker manufacturers displaces distributor-mediated procurement channels. |
| Green Manufacturing Transition | EU Battery Regulation carbon disclosure mandates accelerate certified supplier adoption across European markets. |
| Joint Venture for Secondary Chemistry Development | South Korean remote patient monitoring OEMs seek lighter form factors than lithium-ion alternatives permit. |
| Capacity Expansion in Hunan Cathode Precursor Cluster | Xiangtan Electrochemical Scientific anchors electrolytic manganese dioxide output with just-in-time regional supply. |
Research Methodology
Independent corroboration across primary interviews with cathode material procurement leads, electrochemical R&D directors, and medical device supply chain managers, combined with secondary validation through SAMR GB/T filings, METI critical mineral policy documents, and EU Battery Regulation implementation guidance, underwrites the qualitative findings. Bottom-up cell production estimates and top-down cathode material demand modeling triangulate volume outputs.
Rate-of-change decomposition across primary, secondary, rechargeable, and disposable product types, segmented by consumer electronics, industrial equipment, and medical device applications, structures the analytical framework over the projection horizon. CAGRs derive from electrolytic manganese dioxide purity grade trajectories, implantable device miniaturization trends, and lithium-manganese dioxide cycle stability research progressions.
Ore grade volatility from South African and Gabonese deposits, lithium iron phosphate substitution acceleration in consumer tiers, and multi-jurisdiction certification timeline delays are the dominant revision risks to the forecast envelope. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Thin Film Lithium-Ion Battery Market
Lithium-ion Battery
HEV Li-Ion Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Canada Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market