
 Specialty Flours Market | 2026-2036
Specialty Flours Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Flours Market Analytics
ISO 22000 certification is rotating as the decisive gate for millers supplying European retail chains, filtering out smaller operations lacking hazard-analysis documentation. Cargill leverages its integrated grain-handling network to secure consistent specialty crop supply across North American growing regions. King Arthur Baking Company differentiates through direct-to-baker technical support programs that embed its flours into commercial recipes. Bob's Red Mill sustains its position via certified gluten-free processing lines that command shelf-space premiums in natural-channel retail.
Specialty flours denote milled products derived from non-wheat sources or wheat processed to achieve specific functional, nutritional, or allergen-exclusion properties, typically milled to particle sizes between 74 and 149 microns and often treated to protein contents ranging from 6% to 14% depending on end-use requirements. These flours serve industrial bakeries, pasta manufacturers, and nutritional formulators seeking texture modification, allergen avoidance, or macronutrient profile adjustment in finished goods. Almond flour and chickpea flour occupy the fastest-expanding product positions, with almond flour capturing premium margins in paleo and ketogenic product formulations while chickpea flour gains traction in plant-protein fortification applications. The gluten-free form category commands the highest price positioning, reflecting dedicated facility requirements and batch-level testing burdens that standard refined or whole-grain lines do not carry.
The FDA enforces gluten-free labeling standards below 20 parts per million, compelling domestic millers to maintain segregated production environments and third-party laboratory verification. The EU Green Deal's Farm-to-Fork strategy pressures European suppliers to document sustainable sourcing and reduce chemical inputs in specialty crop cultivation. Stakeholders must monitor evolving allergen threshold harmonization between FDA and EMA frameworks, as divergence in maximum permitted gluten residues could fragment export compliance strategies and force dual-specification production runs.
Market Dynamics
Specialty flour supply chains are compressing as FDA and EFSA allergen thresholds tighten in parallel, forcing millers to choose between dedicated facility investments or export market exclusion. This regulatory convergence is accelerating capital concentration among larger operators capable of sustaining multi-jurisdiction compliance.
Growth Catalysts
- EU Green Deal Farm-to-Fork:The strategy mandates chemical input reduction in specialty crop cultivation, creating certified-sourcing premiums for compliant millers supplying European retail chains.
- Ketogenic formulation demand:Almond flour captures formulation slots in paleo and low-carbohydrate bakery applications, pulling non-wheat ingredients into mainstream industrial recipes.
- Germany:Artisan bread culture intersects with rising celiac diagnoses, concentrating demand for high-purity gluten-free wheat alternatives in Central European milling.
Market Restraints
- Almond input volatility:California drought cycles and water allocation disputes generate price instability for nut-flour processors dependent on single-origin supply.
- Segregated facility capex:FDA gluten-free rules below 20 parts per million compel dedicated production lines that smaller regional millers cannot finance.
- Chickpea protein competition:Plant-meat formulators divert chickpea supply from flour milling toward isolate extraction, tightening feedstock availability.
Strategic Opportunities
- India:FSSAI gluten-free labeling formalization creates first-mover positioning for exporters establishing certified supply chains into urban bakery manufacturing.
- Precision fermentation convergence:Microbial protein production is fragmenting traditional plant-protein sourcing, opening novel feedstock partnerships for specialty flour blenders.
- Direct-to-baker technical support:Recipe embedding services create switching costs and recurring revenue streams beyond commodity flour sales.
Industry Challenges
- ISO 22000 documentation burden:Hazard-analysis protocols require specialized food-safety personnel that regional millers struggle to recruit and retain.
- Batch-level testing timelines:Third-party laboratory verification for gluten-free certification extends production cycles and compresses working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Flours Market |
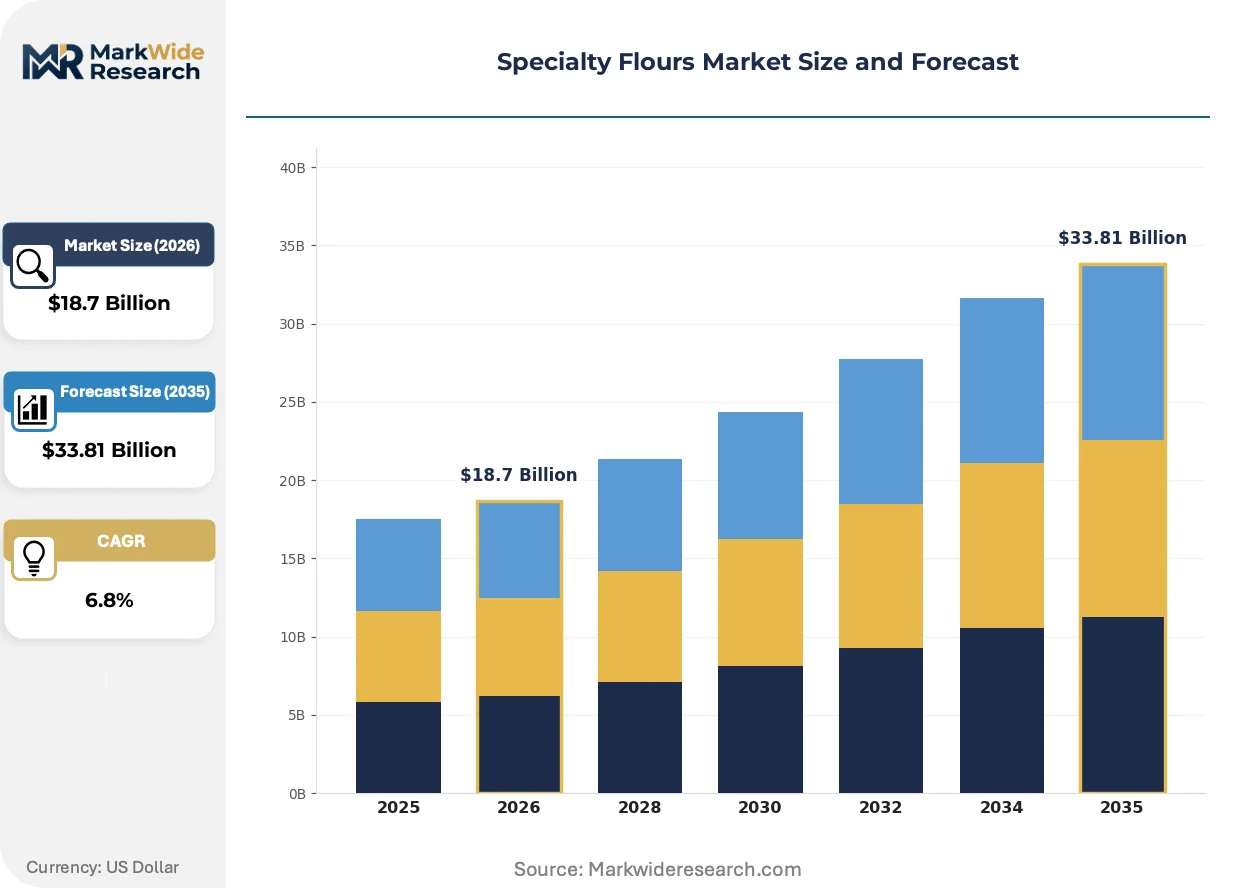
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Coconut Flour, Chickpea Flour, Rice Flour Application: Baking, Pasta Production, Snacks, Nutritional Products Form: Whole Grain, Refined, Organic, Gluten-Free Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Archer Daniels Midland Company, General Mills, Ardent Mills, Cargill, Associated British Foods, Conagra Brands, Bunge Limited, King Arthur Baking Company, Bob’s Red Mill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Flours Market Evolving Landscape
Novel milling technologies and shifting procurement patterns are restructuring how specialty flours move from grain handling to finished goods formulation, with certification requirements now functioning as technical barriers to trade.
Impact milling and air classification systems are fragmenting traditional roller-mill dominance in specialty flour production. Artisan bakeries and small-scale commercial manufacturers adopt these systems for particle-size precision below 74 microns. The technology is fragmenting capital requirements, enabling regional processors to enter markets previously controlled by integrated grain handlers.
REACH chemical registration requirements in Europe are extending compliance timelines for imported specialty crop treatments. Millers sourcing non-EU almonds and chickpeas face documentation burdens that delay new supplier onboarding. Gluten-free formulators targeting German retail channels absorb these costs through dedicated supply contracts that exclude spot-market sourcing.
Certification-driven procurement now dominates European retail chain purchasing, with ISO 22000 documentation replacing price as the primary supplier filter. Industrial bakeries in France and Italy are consolidating vendor lists to millers with pre-approved hazard-analysis systems. This behavior concentrates contract volumes among fewer suppliers, compressing margins for uncertified competitors in Mediterranean milling clusters.
Specialty Flours Market Segmentation
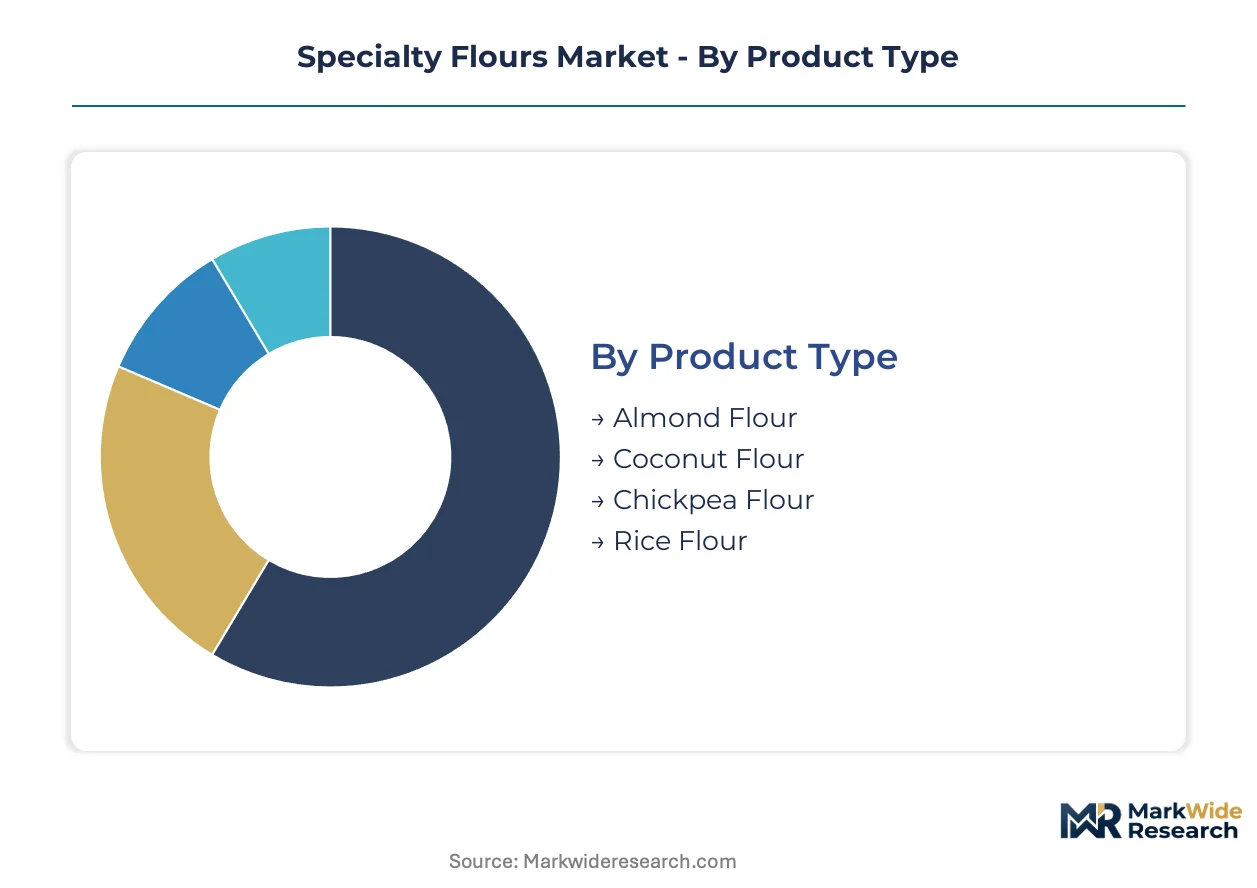
Segmentation in specialty flours reveals how functional properties, certification tiers, and channel access fragment margin capture across milling operations. Understanding these divides exposes where capital concentrates and where smaller processors can wedge into profitable niches.
Product Type:
Margin pools concentrate in nut-derived and legume-based categories where input scarcity and processing complexity sustain premium positioning.
- Almond Flour:Milled from blanched almonds to particle sizes between 74-149 microns with fat content typically 50-55%. Demand concentrates in paleo and ketogenic bakery formulations across US coastal markets, where California drought cycles inject price volatility that disciplined processors hedge through forward contracts.
- Chickpea Flour:Produced from dehulled split chickpeas with protein content ranging 20-25%, delivering binding properties in gluten-free applications. German industrial bakeries absorb expanding volumes as celiac diagnoses climb, though plant-meat formulators now compete aggressively for the same feedstock.
- Coconut Flour:Defatted coconut meal milled to high fiber content, serving low-cohydrate nutritional products.
- Rice Flour:White or brown rice milled to varying amylose ratios, dominating cost-sensitive Asian noodle manufacturing.
The dominant share belongs to almond flour, while chickpea flour is closing the gap fastest.
Application:
Volume concentration diverges sharply from value concentration, with industrial-scale pasta and snack manufacturing running on thinner margins than precision baking applications.
- Baking:Encompasses artisan bread, commercial cake mixes, and frozen dough systems requiring specific protein networks and hydration profiles. France and Italy anchor formulation demand, where millers embed technical support services to lock in recurring supply contracts.
- Pasta Production:Durum wheat alternatives and legume-enriched semolina substitutes for gluten-free and high-protein product lines. Italian extrusion houses drive specification standards that ripple through Mediterranean supplier networks.
- Snacks:Coating systems, extruded crisps, and baked crackers utilizing specialty flours for texture modification.
- Nutritional Products:Meal replacements, protein fortification, and clinical nutrition formulations commanding batch-level documentation.
Baking commands the largest revenue pool, though nutritional products are expanding most quickly.
Form:
Certification tiers create the steepest price gradients, with segregated-facility requirements filtering out regional competitors.
- Gluten-Free:Produced in dedicated environments with third-party verification below 20 parts per million gluten residue. FDA enforcement and EFSA alignment compel capital investments that only integrated handlers sustain, concentrating supply among North American and European operators with multi-jurisdiction compliance systems.
- Organic:Cultivated without synthetic pesticides or fertilizers, documented through accredited certification bodies. EU Green Deal Farm-to-Fork pressures intensify traceability demands, extending compliance timelines for non-EU suppliers.
- Whole Grain:Retains bran and germ fractions, serving fiber-focused nutritional positioning.
- Refined:Standard milled products with specific ash and protein specifications for texture-critical applications.
Gluten-free holds the premium pricing position, while organic is gaining share fastest.
Distribution Channel:
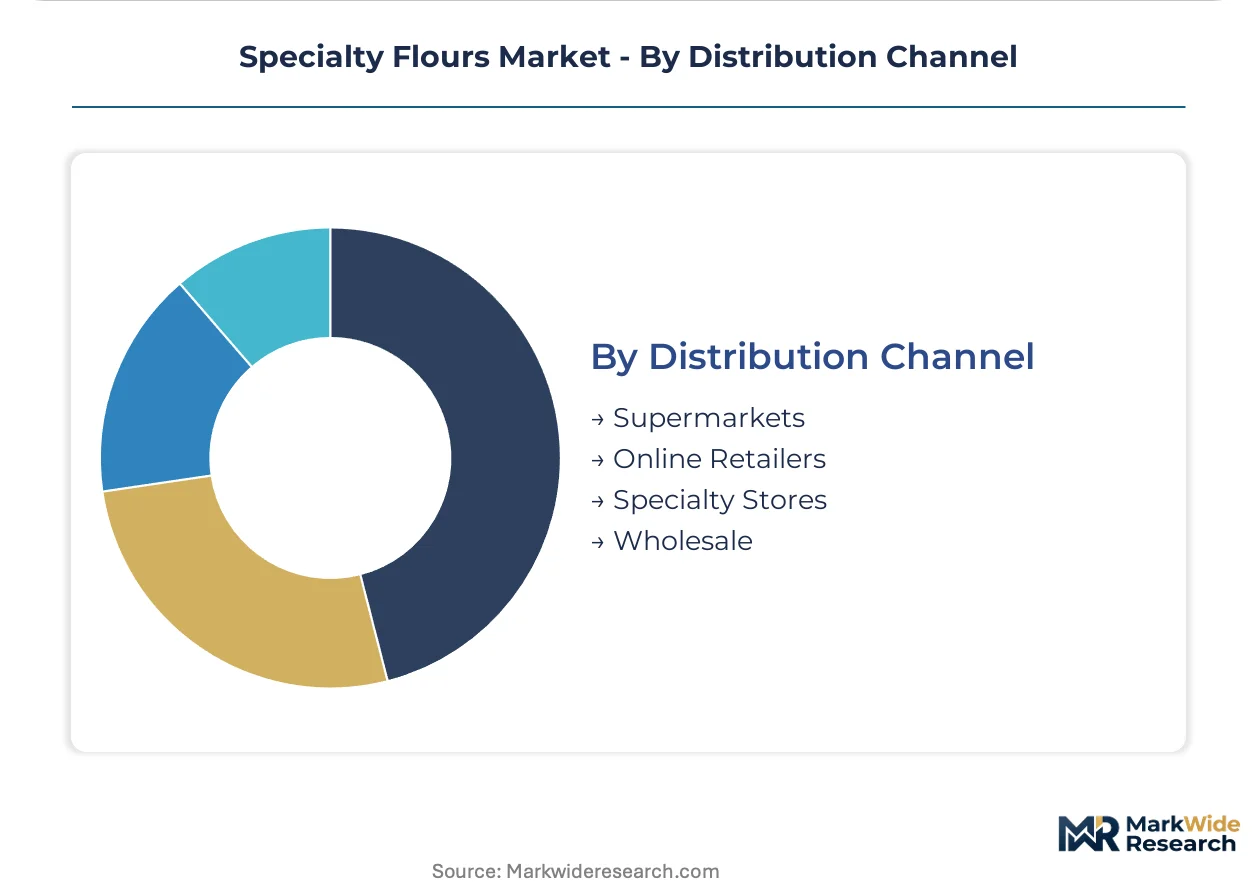
Channel selection determines working capital intensity and customer concentration risk, with wholesale contracts locking volume and direct retail capturing margin.
- Wholesale:Bulk supply to industrial bakeries, pasta manufacturers, and nutritional formulators with multi-year contracts. ISO 22000 documentation now functions as a gatekeeping filter, with European retail chains excluding uncertified millers from approved vendor lists.
- Supermarkets:Packaged consumer flours competing on shelf placement and branded gluten-free assurance. King Arthur Baking Company and Bob's Red Mill dominate through technical support programs and certified processing lines.
- Specialty Stores:Natural-channel retail emphasizing organic and allergen-free credentials.
- Online Retailers:Direct-to-consumer and small-batch commercial supply with compressed delivery timelines.
Wholesale retains the dominant volume position, though online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal Farm-to-Fork strategy is redirecting procurement toward certified-sourcing premiums, while FDA gluten-free enforcement below 20 parts per million compels parallel compliance investments across export-oriented millers.
United States
California almond cultivation supplies the dominant nut-flour feedstock, though drought cycles inject price volatility that disciplined processors hedge through forward contracts. FDA gluten-free labeling rules mandate dedicated facility environments and third-party laboratory verification. Minneapolis-St. Paul anchors integrated grain-handling networks where Cargill leverages captive supply chains to secure consistent specialty crop volumes.
Germany
Artisan bread culture intersects with rising celiac diagnoses, concentrating demand for high-purity gluten-free wheat alternatives in Central European milling. EFSA allergen thresholds align with FDA frameworks, accelerating capital concentration among larger operators capable of sustaining multi-jurisdiction compliance. Hamburg and Berlin industrial bakery clusters absorb expanding volumes of chickpea flour as plant-protein fortification penetrates mainstream formulations.
India
FSSAI gluten-free labeling formalization is creating first-mover positioning for exporters establishing certified supply chains into urban bakery manufacturing. The country's national food regulator tightens documentation requirements for imported specialty crop treatments. Maharashtra and Gujarat host emerging milling operations targeting domestic nutritional product formulators seeking texture modification in gluten-free applications.
France
Industrial bakeries consolidate vendor lists to millers with pre-approved ISO 22000 hazard-analysis systems, filtering out smaller operations lacking documentation. REACH chemical registration extends compliance timelines for imported specialty crop treatments. Lyon and Paris extrusion houses drive specification standards that ripple through Mediterranean supplier networks for pasta production alternatives.
Italy
Durum wheat alternatives and legume-enriched semolina substitutes command formulation slots in gluten-free and high-protein product lines. EU Green Deal pressures intensify traceability demands, extending compliance timelines for non-EU suppliers. Emilia-Romagna anchors pasta manufacturing clusters where technical support services embed supplier flours into commercial recipes, creating switching costs.
Specialty Flours Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access, creating a bifurcated structure where scale-driven handlers face off against niche-focused artisans. Public grain conglomerates leverage integrated networks to absorb input volatility, while family-owned millers capture shelf-space premiums through certified gluten-free processing lines. Three archetypes dominate: integrated agricultural conglomerates with captive supply chains, specialty-focused private millers with technical support capabilities, and regional processors adopting impact milling technologies. Competitive moves concentrate on facility certification investments and direct-to-baker recipe embedding services that create recurring revenue streams.
Among North American integrated handlers, Archer Daniels Midland Company and Cargill occupy positions exemplifying scale-driven supply security, while King Arthur Baking Company represents the technical support archetype through direct-to-baker programs. Bob's Red Mill sits within the certified-specialist tier, anchoring natural-channel retail through dedicated gluten-free processing lines that command shelf-space premiums.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| General Mills |
| Ardent Mills |
| Cargill |
| Associated British Foods |
| Conagra Brands |
| Bunge Limited |
| King Arthur Baking Company |
| Bob's Red Mill |
| Others |
Value Network & Pricing Analysis
Chickpea flour substitution for wheat alternatives in German industrial baking is redrawing procurement geography toward India and Australia while compressing price premiums previously commanded by almond-based formulations. This input shift simultaneously exposes buyers to new tariff structures and forces price recalibration across gluten-free certification tiers.
Pricing Analysis
Certification level creates the primary spread between commodity and specialty-grade flour offerings. Three-tier pricing structure across premium, standard, and economy levels segments buyers by documentation requirements, with ISO 22000-certified gluten-free products commanding sustained premiums over uncertified alternatives. Cost compression in standard-grade rice and coconut flours is intensifying because Indian and Thai millers are expanding export-oriented capacity. Industrial bakeries in France and Italy exhibit lowest price sensitivity due to recipe-embedding switching costs, while Asian noodle manufacturers remain most responsive to per-kilogram differentials.
Supply Chain Analysis
California almond processing capacity functions as a chokepoint that constrains North American nut-flour availability during drought-intensified harvest cycles. Geographic supply concentrates in the United States, India, and Germany, with raw material dependencies spanning California almonds, Australian desi chickpeas, and Italian durum wheat alternatives. Single-source vulnerability runs through California water allocation disputes that disrupt almond flour feedstock. Distribution runs through integrated grain-handling networks for wholesale industrial buyers and natural-channel retail chains for consumer-packaged goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA gluten-free labeling enforcement below 20 parts per million has triggered capital-intensive facility segregation that is consolidating milling capacity among multi-jurisdiction operators. This regulatory inflection creates asymmetric growth trajectories across certification tiers and geographic markets.
For Market Incumbents: Secure dedicated gluten-free processing lines ahead of EFSA-FDA threshold harmonization to preempt export market exclusion. Cargill and Ardent Mills should extend backward integration into specialty crop origination to hedge California almond volatility and capture Farm-to-Fork certified-sourcing premiums. Certification investment represents the decisive lever for retaining European retail chain contracts as ISO 22000 documentation filters out regional competitors. For New Entrants and Emerging Players: Differentiate on precision fermentation partnerships that fragment traditional plant-protein sourcing and open novel feedstock channels for specialty flour blenders. White-space targets include FSSAI-compliant supply chains into Indian urban bakery manufacturing and impact milling system deployment for artisan particle-size precision below 74 microns. Direct-to-baker technical support programs offer the most penetrable go-to-market angle, embedding proprietary flours into commercial recipes that create recurring revenue beyond commodity sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty millers possessing ISO 22000 certification but lacking integrated grain-handling scale. Long-term viability over the coming decade hinges on multi-jurisdiction compliance capability and captive specialty crop supply. The signal to watch is EFSA-FDA allergen threshold divergence, which would force dual-specification production runs and compress margins for single-jurisdiction operators.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Gluten-Free Facility Investment | FDA enforcement below 20 ppm compels segregated production environments that filter out regional millers. |
| Direct-to-Baker Technical Support Programs | King Arthur Baking Company embeds flours into commercial recipes, creating switching costs and recurring supply contracts. |
| Backward Integration into Specialty Crop Origination | Cargill leverages captive supply chains to hedge California drought cycles and secure consistent feedstock. |
| Precision Fermentation Feedstock Partnerships | Microbial protein production fragments traditional plant-protein sourcing for novel flour blending applications. |
| FSSAI Certification for Indian Market Entry | First-mover positioning into urban bakery manufacturing as India's national food regulator tightens gluten-free documentation. |
Research Methodology
Desk research of FDA enforcement records, EFSA allergen threshold documentation, EU Green Deal Farm-to-Fork strategy filings, and customs trade data preceded structured interviews with specialty flour procurement managers at industrial bakeries, mill operations directors, retail chain category buyers, and third-party food safety certification auditors. Primary fieldwork combined with secondary validation across SEC 10-K filings from integrated grain handlers and specialty crop cultivation databases. Bottom-up volume modeling triangulated against top-down market sizing from trade association production statistics.
Variance decomposition across product type, application, certification tier, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory compliance cost trajectories. Forecast inputs incorporated California water allocation projections, celiac diagnosis trend extrapolations, and plant-meat formulator chickpea demand competition.
Material uncertainties — drought-induced almond price spikes, EFSA-FDA threshold divergence, FSSAI implementation delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained ketogenic formulation demand and stable EU Green Deal chemical input restrictions. Practitioners should keep alternative scenarios live as regulatory harmonization negotiations and precision fermentation scale-up timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Pea Peptones Market
Ingredients
Clean Label Starch Market
Ingredients
Meat Extract Market
Ingredients
South Africa Sodium Reduction Ingredients Market
Ingredients
Omega Ingredients Market
Ingredients
Synephrine Market
Ingredients
Global Gelatin Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Global Cocoa Products Market
Ingredients
Dill Seed Oil Market
Ingredients
Liquid Malt Extract Products Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
North America Cocoa Products Market