
 Tissue Microarrayer Market | 2026-2036
Tissue Microarrayer Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Microarrayer Market Analytics
Asset-light leasing models for precision pathology equipment is fragmenting competitive dynamics among mid-sized laboratories that previously could not justify capital purchases. Thermo Fisher Scientific leverages its global service infrastructure to sustain long-term instrument placement contracts. Agilent Technologies differentiates through integrated workflow solutions spanning sample prep to data analysis. 3DHISTECH dominates digital pathology-adjacent microarray positioning across European research hospitals.
A tissue microarrayer is an automated or semi-automated instrument that constructs paraffin blocks containing hundreds of cylindrical tissue cores, typically 0.6 to 2.0 millimeters in diameter, arranged in precise grid arrays for simultaneous histological or molecular analysis. The device enables high-throughput screening of tumor specimens, biomarker validation, and translational research applications where parallel processing of hundreds of samples reduces reagent consumption and experimental variability. Automated systems command the largest installed base due to throughput requirements in pharmaceutical toxicology screening, though microfluidics-based platforms represent the fastest-expanding technology segment as labs miniaturize assay volumes. Contact printing retains cost advantages in academic settings with lower sample volumes, while laser capture microdissection integration creates premium positioning for genomics workflows requiring spatial transcriptomics precision.
The FDA's 21 CFR Part 820 quality system regulation and the European Union's In Vitro Diagnostic Regulation (IVDR) impose divergent clinical validation burdens that shape product development roadmaps and market access timelines for instrument manufacturers. ISO 13485 certification serves as a baseline requirement for suppliers serving both jurisdictions, though IVDR's heightened performance scrutiny for devices with diagnostic claims is forcing portfolio segmentation between research-use-only and clinical-grade platforms. Stakeholders must monitor evolving harmonization negotiations between the FDA and European notified bodies, as divergent post-market surveillance requirements threaten to duplicate compliance investments across transatlantic supply chains.
Market Dynamics
Pharmaceutical toxicology screening is compressing assay timelines and forcing laboratories to automate tissue core extraction workflows at unprecedented throughput levels. This demand compression is reshaping equipment procurement patterns across contract research organizations and academic medical centers.
Growth Catalysts
- IVDR Performance Scrutiny:The European Union's In Vitro Diagnostic Regulation mandates enhanced clinical validation for diagnostic-grade platforms, creating tiered demand for research-use-only versus clinical-grade microarrayers.
- Spatial Transcriptomics Integration:Genomics workflows requiring precise tissue architecture preservation are pulling laser capture microdissection-compatible microarrayers into translational research pipelines.
- Germany's Pathology Infrastructure:Dense networks of university hospitals and tissue banks in Baden-Württemberg and Bavaria sustain concentrated procurement of CE-marked automated systems.
Market Restraints
- Paraffin Block Standardization Gaps:Inconsistent tissue core diameter specifications across legacy sample archives complicate cross-study reproducibility and limit secondary use of biobank specimens.
- Specialized Technician Scarcity:Histopathology technologists trained in automated microarrayer operation remain concentrated in major metropolitan medical centers, constraining deployment in mid-tier laboratories.
- Microfluidics Patent Thickets:Dense intellectual property landscapes around miniaturized liquid handling create licensing friction for instrument manufacturers developing next-generation platforms.
Strategic Opportunities
- Asset-Light Leasing Models:Equipment-as-a-service arrangements enable mid-sized pathology laboratories to access automated microarrayers without capital expenditure commitment.
- Digital Pathology Convergence:Integration of whole-slide imaging with microarray construction creates unified workflows from tissue sampling to quantitative image analysis.
- India's Biobank Expansion:The country's national cancer grid and regional tissue repository initiatives generate demand for high-throughput specimen processing equipment.
Industry Challenges
- ISO 13485 Certification Timelines:Extended audit cycles and documentation requirements delay product launches for manufacturers targeting both FDA and CE-marked instrument markets.
- Legacy LIMS Integration:Proprietary data formats from established microarrayer systems create interoperability barriers with modern laboratory information management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Microarrayer Market |
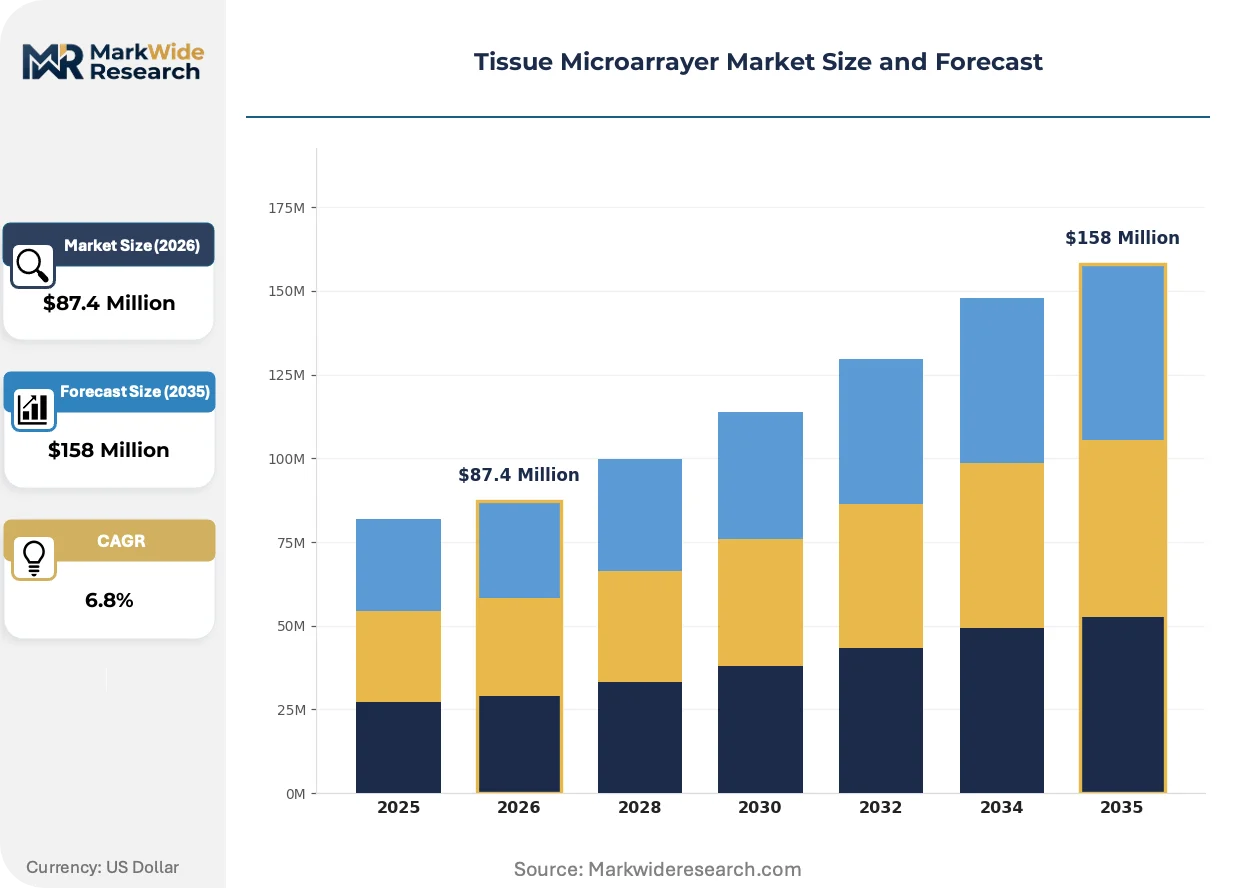
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Hybrid Systems, Slide-Based Systems Technology: Laser Capture Microdissection, Inkjet Printing, Contact Printing, Microfluidics End User: Research Laboratories, Diagnostic Laboratories, Academic Institutions, Pharmaceutical Companies Application: Pathology, Genomics, Proteomics, Drug Discovery |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Arrayit Corporation, OriGene Technologies, BioChain Institute, US Biomax, Bio SB, ProteoGenex, 3DHISTECH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Microarrayer Market Evolving Landscape
Microfluidics is compressing assay volumes while digital pathology integration is redefining workflow boundaries. These forces are converging to reshape how tissue specimens transition from physical blocks to analyzable data.
Contact printing microarrayers are migrating from academic research settings toward pharmaceutical toxicology screening operations. Large molecule drug developers now require parallel processing of hundreds of specimens for biomarker validation studies. This migration is compressing the price-performance gap between manual and automated systems.
REACH chemical safety assessments are tightening restrictions on xylene and other histological clearing agents used in tissue processing workflows. European pathology laboratories face reformulation requirements for paraffin embedding protocols. Germany's chemical industry is responding with bio-based substitute development programs.
Service unbundling is fragmenting traditional instrument placement contracts. Pharmaceutical companies now separate hardware procurement from maintenance agreements and consumable supply arrangements. This pattern is most visible in the United States, where contract research organizations negotiate multi-vendor service tiering.
Tissue Microarrayer Market Segmentation
Tissue microarrayer procurement patterns diverge sharply across operational scales and technical sophistication levels. Pharmaceutical toxicology screening demands throughput velocity that academic biobanking operations rarely require. These structural differences fragment vendor pricing power and service bundling strategies.
Product Type:
Cost tier separation between capital-intensive automated platforms and manual alternatives shapes laboratory procurement cycles and financing structures.
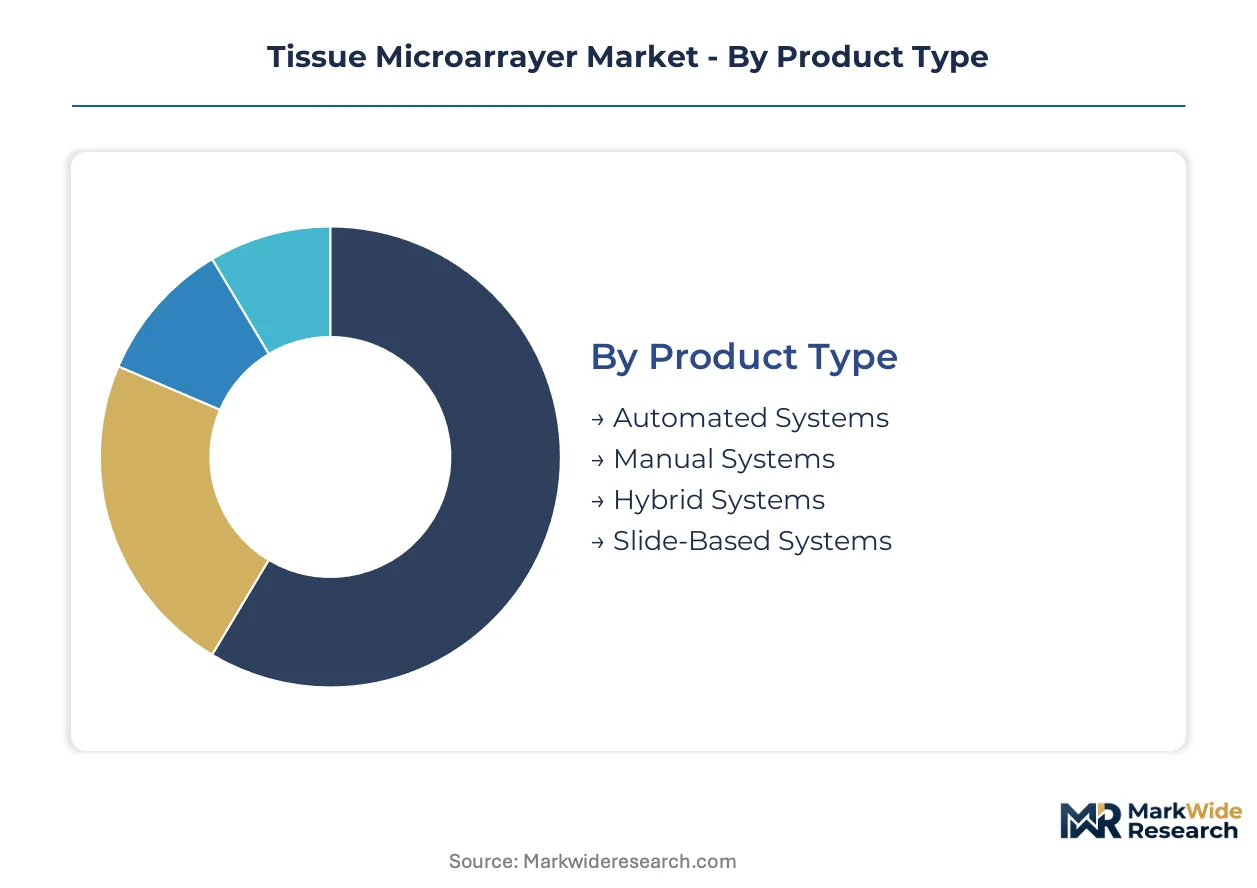
- Automated Systems:Robotic core extraction and precision grid arraying enable processing of 500+ specimens per batch. Pharmaceutical contract research organizations in Germany and the United States concentrate demand here, driven by FDA 21 CFR Part 820 validation requirements for toxicology screening workflows.
- Manual Systems:Hand-operated punch-and-place mechanisms suit lower-volume academic settings with budget constraints under €50,000. Indian cancer biobanks and Southeast Asian research hospitals rotate toward these systems as national tissue repository networks expand.
- Hybrid Systems:Semi-automated positioning with manual core loading bridges throughput and capital efficiency.
- Slide-Based Systems:Direct array construction on glass substrates eliminates paraffin embedding steps for specific immunohistochemistry protocols.
Automated systems hold installed capacity. Hybrid systems are rotating up the share rankings.
Technology:
Application requirements for spatial precision versus throughput velocity determine technology selection across genomics and pathology workflows.
- Microfluidics:Miniaturized liquid handling reduces reagent volumes to nanoliter scales while preserving tissue architecture. European research hospitals in Switzerland and the Netherlands lead adoption, responding to REACH restrictions on xylene-based clearing agents through solvent-free processing alternatives.
- Laser Capture Microdissection:UV laser ablation enables single-cell precision for spatial transcriptomics. Genomics workflows at Boston and Heidelberg academic medical centers drive premium positioning, where RNA integrity preservation justifies 3-5x equipment cost multiples.
- Contact Printing:Pin-based deposition retains cost advantages for biomarker validation studies with moderate sample volumes.
- Inkjet Printing:Piezoelectric droplet ejection suits protein microarray fabrication with non-contact sample handling.
Contact printing holds installed capacity. Microfluidics is climbing the fastest among technology segments.
End User:
Customer type determines service contract structures, with pharmaceutical buyers unbundling maintenance agreements while academic purchasers prioritize capital efficiency.
- Pharmaceutical Companies:Large-molecule drug developers require parallel processing of hundreds of specimens for biomarker validation. Toxicology screening compression timelines at Merck KGaA and Roche facilities in Germany force equipment refresh cycles below five years.
- Research Laboratories:Core facilities at university hospitals balance throughput against multi-user accessibility demands.
- Diagnostic Laboratories:Clinical-grade platforms face IVDR performance scrutiny for diagnostic claims in European markets.
- Academic Institutions:Grant-funded procurement favors modular systems with upgrade pathways.
Pharmaceutical companies hold installed capacity. Research laboratories are rotating up the share rankings.
Application:
Volume requirements and regulatory classification diverge across translational research versus clinical diagnostic use cases.
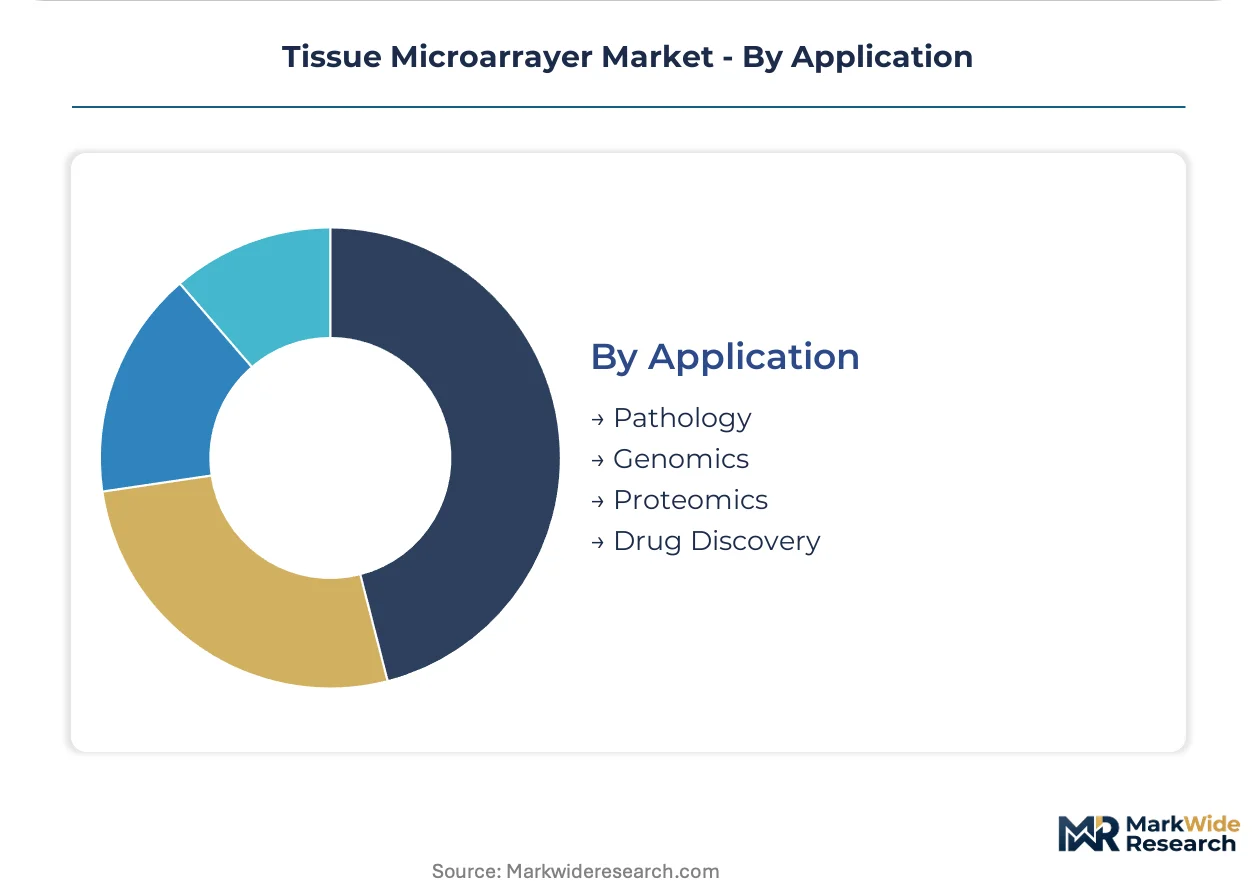
- Pathology:High-throughput immunohistochemistry screening of tumor microarrays dominates current utilization. University hospital networks in Baden-Württemberg and Bavaria sustain concentrated procurement of CE-marked systems for diagnostic-grade workflows.
- Drug Discovery:Lead optimization phases require rapid compound-tissue interaction profiling across diverse specimen archives.
- Genomics:DNA and RNA extraction from arrayed cores supports genome-wide association studies.
- Proteomics:Mass spectrometry-compatible tissue processing demands specialized paraffin formulations.
Pathology holds installed capacity. Drug discovery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's IVDR enforcement timeline and the United States' FDA 21 CFR Part 820 quality system regulation are creating divergent compliance pathways that reshape instrument deployment patterns across major pathology markets.
United States
Pharmaceutical toxicology screening at contract research organizations in Massachusetts and North Carolina drives automated system procurement. FDA 21 CFR Part 820 mandates rigorous device validation protocols for clinical-grade platform entry. The Boston-Cambridge corridor concentrates demand from genomics workflows requiring laser capture microdissection precision.
Germany
University hospital networks in Baden-Württemberg and Bavaria sustain Europe's densest installed base of CE-marked automated microarrayers. IVDR performance scrutiny forces portfolio segmentation between research-use-only and diagnostic-grade platforms. Heidelberg and Tübingen academic medical centers anchor spatial transcriptomics adoption for RNA integrity preservation applications.
China
National cancer biobank expansion and regional tissue repository initiatives generate demand for high-throughput specimen processing equipment. NMPA medical device registration requirements shape product localization strategies for multinational suppliers. The Yangtze River Delta concentrates pathology research infrastructure investment in Shanghai and Suzhou hospital networks.
India
The national cancer grid and state-level tissue bank programs drive manual and semi-automated system adoption across mid-tier laboratories. CDSCO medical device rules create registration pathways for imported instruments serving diagnostic workflows. Maharashtra and Karnataka host concentrated procurement from Tata Memorial Centre and regional cancer centre networks.
Switzerland
Swissmedic regulatory alignment with EU IVDR standards supports seamless CE-marked instrument deployment across cantonal hospital systems. REACH chemical safety assessments accelerate solvent-free processing alternatives in Zurich and Basel pathology laboratories. The Basel pharmaceutical cluster generates specialized demand for biomarker validation platforms serving large-molecule drug development.
Tissue Microarrayer Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by service infrastructure depth and workflow integration breadth. Thermo Fisher Scientific leverages global service networks to sustain long-term instrument placement contracts, while Agilent Technologies competes through integrated sample prep-to-analysis solutions. 3DHISTECH occupies digital pathology-adjacent positioning across European research hospitals. Competitive moves center on asset-light leasing model expansion and strategic partnerships for microfluidics patent licensing.
Among diversified life science conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify the full-workflow integration archetype, bundling hardware with consumable supply and maintenance agreements. 3DHISTECH represents the specialized European precision pathology segment, anchoring digital imaging convergence with microarray construction workflows. Arrayit Corporation and OriGene Technologies occupy positions within the focused reagent and instrument specialist tier, serving grant-funded academic procurement cycles with modular system architectures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Arrayit Corporation |
| OriGene Technologies |
| BioChain Institute |
| US Biomax |
| Bio SB |
| ProteoGenex |
| 3DHISTECH |
| Others |
Value Network & Pricing Analysis
Frankfurt-Rotterdam freight corridor cost volatility feeds directly into automated microarrayer landed pricing for German university hospital networks, compressing margins on CE-marked systems while amplifying price spreads between FDA-validated and research-use-only tiers across European distribution channels.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 13485 plus IVDR clinical-grade validation commanding substantial premiums over research-use-only platforms. Three-tier pricing structure separates FDA-grade automated systems from CE-marked clinical platforms and economy manual alternatives. Cost compression in mid-tier hybrid systems is intensifying because pharmaceutical buyers now unbundle service contracts from hardware procurement. Academic institutions exhibit highest price sensitivity, while contract research organizations prioritize throughput velocity over capital efficiency.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for precision motion control components and optical sensor modules. Manufacturing concentration in Germany, Switzerland, and Japan feeds downstream assembly operations. Component sourcing draws from Taiwanese semiconductor foundries for control electronics and German specialty steel suppliers for precision punching mechanisms. Single-source vulnerability around piezoelectric positioning stages threatens production continuity. Distribution runs through authorized service distributors with captive installation and validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through ISO 13485 and IVDR certification timelines creates substantial switching costs that defend incumbent positioning across European hospital networks.
For Market Incumbents: Insulate installed base relationships by embedding field service engineers within major pharmaceutical toxicology operations, countering emerging microfluidics specialists who threaten core extraction automation with solvent-free processing alternatives. Deepen backward integration into precision punching consumables to capture recurring revenue streams and lock out third-party reagent suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's national cancer grid expansion, where CDSCO registration pathways remain less congested than FDA or IVDR channels and manual system demand outpaces established supplier coverage. Target state-level tissue bank procurement in Maharashtra and Karnataka with lease-to-own financing structures that circumvent capital budget constraints at mid-tier laboratories. For Investors and Strategic Acquirers: Digital pathology workflow integrators with captive microarrayer positioning represent the most defensible acquisition archetype, given convergence tailwinds between whole-slide imaging and tissue construction automation. Monitor IVDR notified body capacity expansion as the inflection signal; approval queue compression would accelerate clinical-grade platform revenue recognition timelines across European markets.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Clinical-Grade Certification Pathway | Unlocks diagnostic-grade revenue streams in German university hospital networks. |
| Microfluidics Patent Licensing Partnership | Resolves IP thickets blocking next-generation solvent-free platform development. |
| Asset-Light Leasing Model Expansion | Captures mid-tier laboratory demand without capital expenditure approval barriers. |
| Laser Capture Microdissection Integration | Penetrates spatial transcriptomics workflows at Heidelberg and Boston medical centers. |
| Digital Pathology Platform Convergence | Unifies tissue construction with whole-slide imaging for seamless quantitative analysis. |
Research Methodology
Cross-validation between primary interviews with pathology laboratory directors and secondary analysis of FDA 510(k) filings anchors the qualitative findings on regulatory validation requirements. Conversations with biomedical engineers at German university hospitals, histopathology technologists at contract research organizations, GPO contracts managers, and precision pathology equipment procurement officers informed operational workflow insights. Secondary sources include EMA IVDR guidance documents, ISO 13485 certification databases, hospital procurement records, and trade customs data on histological equipment imports. Bottom-up demand modeling triangulates against top-down pharmaceutical R&D expenditure allocations.
Calibration against historical instrument placement volumes and replacement cycle patterns shapes the projection framework across the analysis window. Segmentation dimensions span product type, technology platform, end-user category, application area, and regional regulatory cluster. CAGRs derive from logistic adoption curve fitting and price elasticity modeling. Forecast inputs incorporate IVDR enforcement timeline phasing and REACH chemical restriction implementation schedules.
Stress conditions across IVDR notified body capacity, xylene substitute availability, and microfluidics patent litigation outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory harmonization progress and biobank infrastructure investment trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Gel Column Agglutination Test System Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Biobanking Equipment Market