
 Global Plant Cell Culture Equipment Market | 2026-2036
Global Plant Cell Culture Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Cell Culture Equipment Market Intelligence
The divide between high-precision, automated bioreactors and basic, manual culture vessels is rebalancing the competitive landscape. Thermo Fisher Scientific leverages its broad portfolio to serve large pharmaceutical clients with integrated solutions. Sartorius AG specializes in advanced bioprocessing equipment for high-value applications. In contrast, Conviron caters to academic and agroforestry sectors with cost-effective growth chambers.
Plant cell culture equipment comprises instruments for the aseptic cultivation of plant cells in a controlled environment. These systems precisely manage parameters like temperature, pH, and gas exchange to optimize growth. Within the product landscape, bioreactors command the highest value, driven by their use in pharmaceutical applications for metabolite production. The academic research sector, conversely, sustains demand for more standardized incubators and shakers.
Regulatory frameworks from the US FDA and the European EMA mandate stringent Good Manufacturing Practices (GMP), directly influencing equipment design and validation. China's NMPA similarly imposes strict standards on equipment used for producing traditional medicines, shaping market access. Consequently, manufacturers face a strategic choice between investing in costly GMP-compliant systems for pharmaceutical clients or serving the less regulated, price-sensitive academic sector.
Market Dynamics
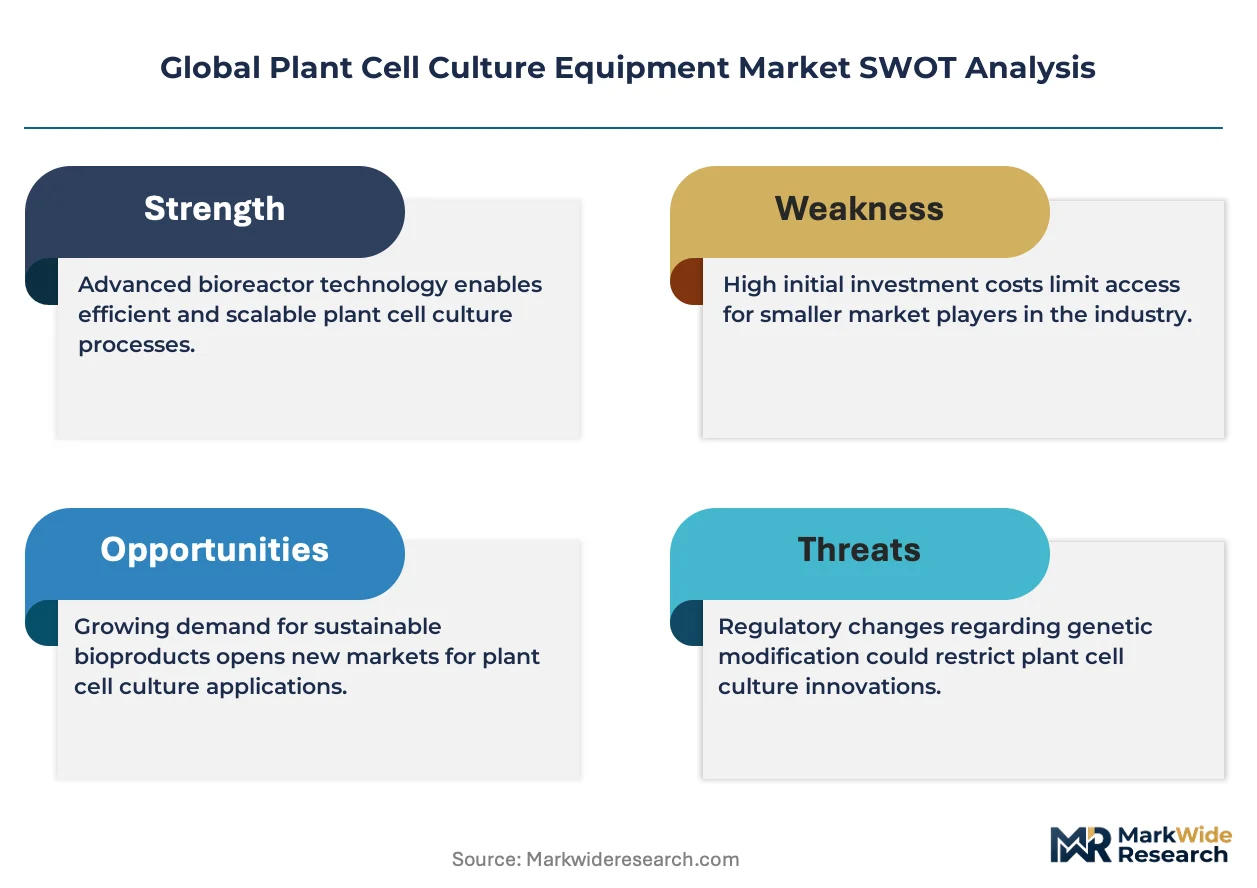
The market's structure is defined by a strategic bifurcation between high-cost, GMP-compliant systems for pharmaceutical production and lower-cost, standardized equipment for academia. This divergence forces manufacturers to choose a target market, which in turn dictates equipment design, validation costs, and overall business strategy.
Growth Catalysts
- Secondary Metabolite Production:Pharmaceutical sector demand for complex plant-derived compounds, such as paclitaxel, requires advanced, scalable bioreactor systems. This drives investment in high-precision cultivation technology to ensure product consistency and yield.
- Chinese Biotechnology Initiative:Government support in China, including favorable policies for its biotechnology sector, is accelerating domestic investment in new plant cell culture facilities. This is particularly evident in applications related to traditional medicine production.
- Single-Use Systems:The adoption of single-use bioreactors reduces cross-contamination risks and shortens changeover times. This improves operational efficiency for contract manufacturing organizations handling multiple client campaigns.
Market Restraints
- High Capital Expenditure:The significant initial investment required for GMP-certified bioreactors and associated validation services creates a high barrier to entry. This limits adoption by smaller companies and academic research institutes.
- Shear Stress Sensitivity:Many plant cell lines are highly sensitive to mechanical shear stress within large-scale bioreactors. This physical limitation complicates process optimization and limits the scalability for producing delicate compounds.
- Stringent GMP Compliance:Navigating the rigorous Good Manufacturing Practices validation processes mandated by regulators like the US FDA and European EMA is a costly and time-consuming restraint for equipment manufacturers targeting the pharma sector.
Strategic Opportunities
- Cultivated Food Ingredients:The emerging cultivated food sector presents an opportunity for equipment adapted to produce high-value ingredients like vanillin or saffron. This expands the market beyond traditional pharmaceutical applications.
- AI-Powered Process Control:Integrating artificial intelligence for real-time monitoring and predictive control of culture parameters offers a path to optimize yields and reduce batch failures. This represents a significant value-add for manufacturers.
- Agroforestry Research in Brazil:Brazil's focus on sustainable agroforestry and biodiversity creates an opportunity for specialized growth chambers and culture systems. These would support the conservation and propagation of native plant species.
Industry Challenges
- Bioprocess Engineering Talent Gap:A shortage of skilled bioprocess engineers who can operate, validate, and maintain complex, automated plant cell culture systems constrains operational efficiency for end-users and slows technology adoption.
- Lack of Process Standardization:The absence of standardized protocols for different plant cell lines complicates equipment design. It also makes it difficult for users to transfer processes between different systems or laboratories reliably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Cell Culture Equipment Market |
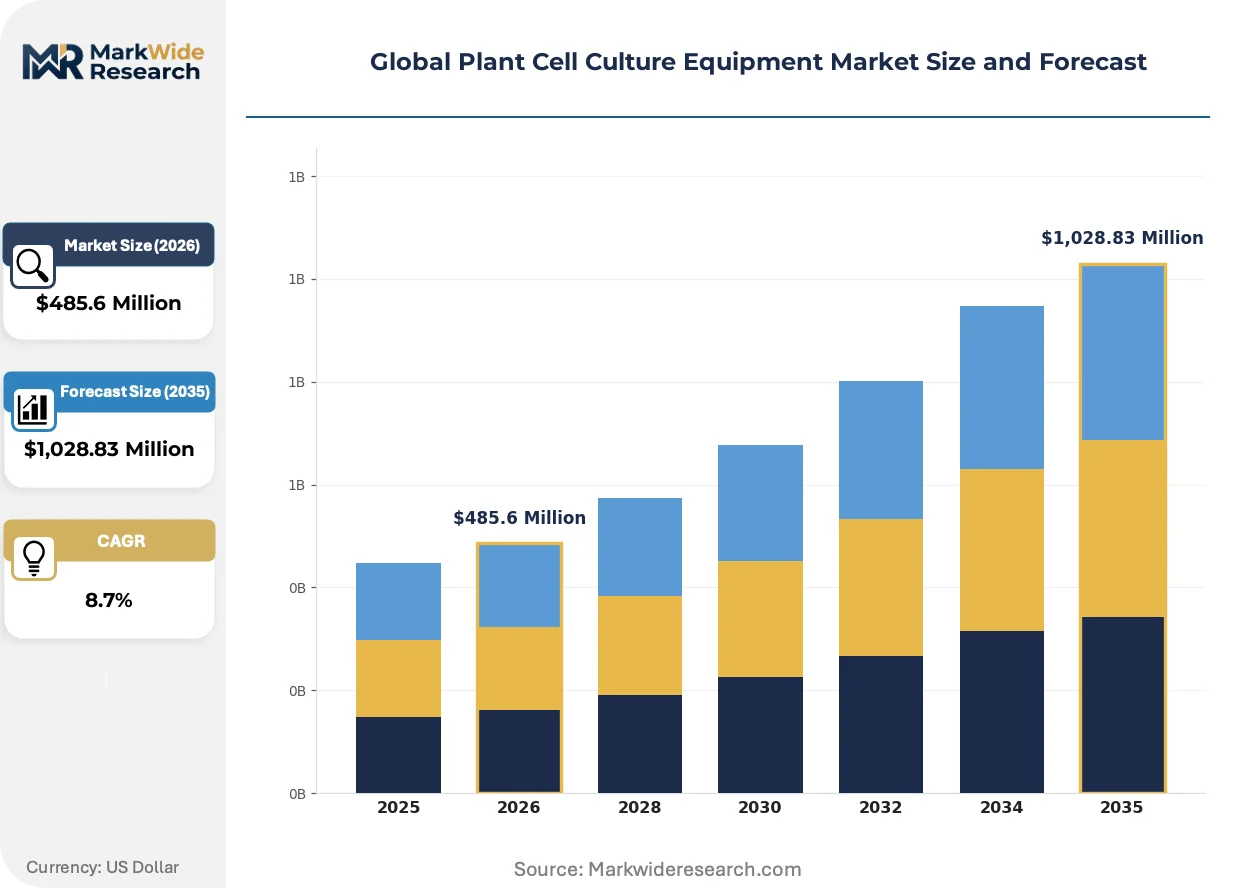
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $1,028.83 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Sartorius Equipment, Shakers, Incubators Technology: Microbial Fermentation, Tissue Engineering, Genetic Analysis, Metabolic Engineering Application: Pharmaceuticals, Biotechnology, Academic Research, Agroforestry End User: Research Institutes, Agricultural Corporations, Pharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Eppendorf AG, Merck KGaA, Danaher Corporation, Corning Incorporated, Lonza Group AG, GE Healthcare, Conviron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Cell Culture Equipment Market Strategic Shifts & Innovations
Process automation and data-driven optimization are transforming plant cell culture operations from a manual art to a precise, reproducible science. This shift enables the scalability essential for meeting stringent regulatory requirements and expanding into new commercial applications.
Advanced sensor technology, including in-situ probes for monitoring dissolved oxygen, pH, and cell density, provides real-time data from within the bioreactor. Pharmaceutical manufacturers and large-scale contract research organizations are rapidly adopting these integrated sensor suites. This continuous data stream is automating feedback loops for nutrient feeding and gas exchange, reducing the need for manual sampling and intervention.
The European EMA's emphasis on Process Analytical Technology (PAT) as part of its GMP guidelines encourages the adoption of advanced monitoring systems. This regulatory push requires equipment to provide continuous, real-time quality assurance data throughout the cultivation process. Bioreactor manufacturers are most affected, responding by integrating PAT-compliant sensors and software directly into their high-end pharmaceutical-grade systems.
A move towards modular and configurable equipment designs is gaining traction among end-users. This disrupts the traditional model of purchasing fixed, monolithic systems, allowing labs to buy a base unit and add specific modules for different cell lines or research goals. This trend is most visible in the academic research and startup biotechnology sectors, where budget flexibility and experimental versatility are paramount.
Global Plant Cell Culture Equipment Market Segmentation
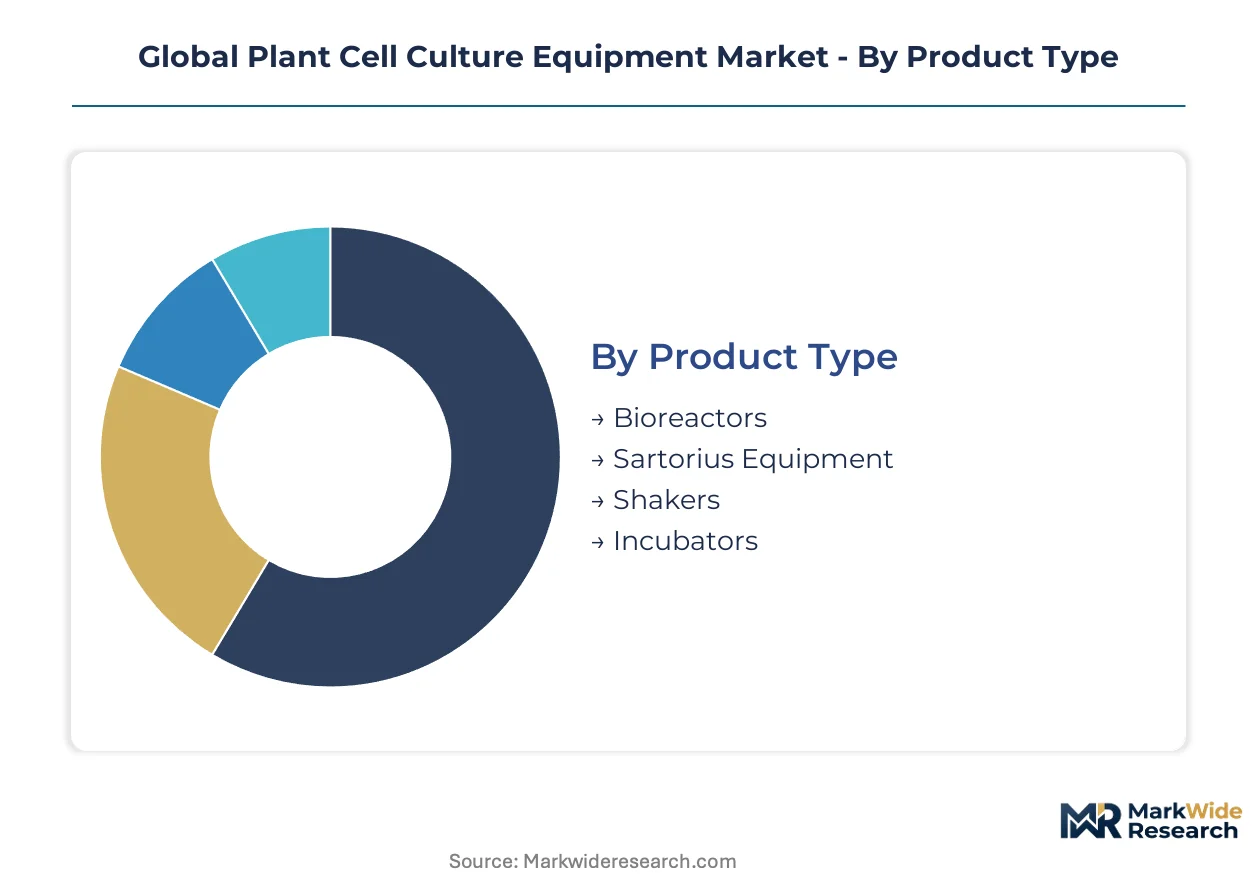
The segmentation of the global plant cell culture equipment market provides a critical framework for understanding diverse demand drivers and technological preferences. It highlights how varying end-user requirements and application complexities shape equipment design and procurement decisions. This granular analysis supports manufacturers in tailoring product portfolios and market strategies.
Product Type:
The upgrade and replacement cycles for plant cell culture equipment significantly influence demand patterns across different product types.
- Bioreactors:These systems provide a highly controlled environment for large-scale aseptic cultivation, precisely managing parameters like temperature, pH, and gas exchange. Demand from pharmaceutical applications for complex secondary metabolite production drives investment in GMP-compliant, high-precision bioreactors.
- Incubators:Equipment maintains stable temperature, humidity, and CO2 levels essential for basic plant cell growth and maintenance, often with adjustable shelving and lighting. Academic research and early-stage biotechnology companies sustain consistent demand for these standardized units for routine cell culture.
- Sartorius Equipment:This category includes specialized bioprocessing tools, such as advanced bioreactors, filtration systems, and cell culture media preparation units, often integrated into high-value pharmaceutical and biotechnology workflows.
- Shakers:These devices provide controlled orbital or reciprocal agitation for suspension cultures, supporting fundamental research, media optimization, and initial process development stages in various laboratories.
Bioreactors sit at the top of the volume ranking, with Incubators climbing the fastest.
Technology:
The specific technological applications of plant cell culture equipment dictate the required precision and scale of instrumentation.
- Tissue Engineering:This technology involves complex protocols for plant regeneration, micropropagation, and callus induction, demanding highly controlled environments and specialized media delivery systems. Agroforestry and horticulture sectors drive demand for these systems to develop new plant varieties and accelerate propagation.
- Metabolic Engineering:This field focuses on modifying plant cell pathways to enhance the production of specific high-value compounds, requiring advanced bioreactor designs with integrated sensing and precise control capabilities. Pharmaceutical companies invest heavily in this technology for novel drug precursor synthesis and yield optimization.
- Microbial Fermentation:While primarily focused on microorganisms, some plant cell culture applications leverage similar bioreactor principles for large-scale biomass production or the synthesis of specific plant-derived compounds through engineered microbial hosts.
- Genetic Analysis:Equipment supports the aseptic culture of genetically modified plant cells for trait evaluation, gene expression studies, and functional genomics research in academic and biotechnology laboratories.
High-value applications like Metabolic Engineering command premium margins, while Genetic Analysis supports broader research initiatives.
Application:
Different application sectors drive distinct cost tier requirements for plant cell culture equipment, from high-end to economical solutions.
- Pharmaceuticals:This sector requires GMP-compliant bioreactors, associated validation services, and integrated process analytical technology for producing complex secondary metabolites and therapeutic proteins. Demand is concentrated in established drug manufacturing regions like Europe, where the European EMA mandates stringent quality control.
- Academic Research:This segment sustains demand for versatile, often modular, incubators, shakers, and smaller bioreactors for fundamental studies, proof-of-concept experiments, and early-stage process development. Demand is widespread across university and public research institutions globally.
- Biotechnology:This broad category encompasses novel compound discovery, bio-pesticide production, and plant-derived vaccine development, often leveraging scalable bioreactor systems with advanced process control.
- Agroforestry:Plant cell culture is utilized here for rapid propagation of elite tree species, disease-free plantlets, and conservation efforts, primarily requiring specialized growth chambers and sterile culture facilities.
Pharmaceutical applications concentrate equipment supply among specialized vendors, whereas Academic Research relies on a broader supplier base.
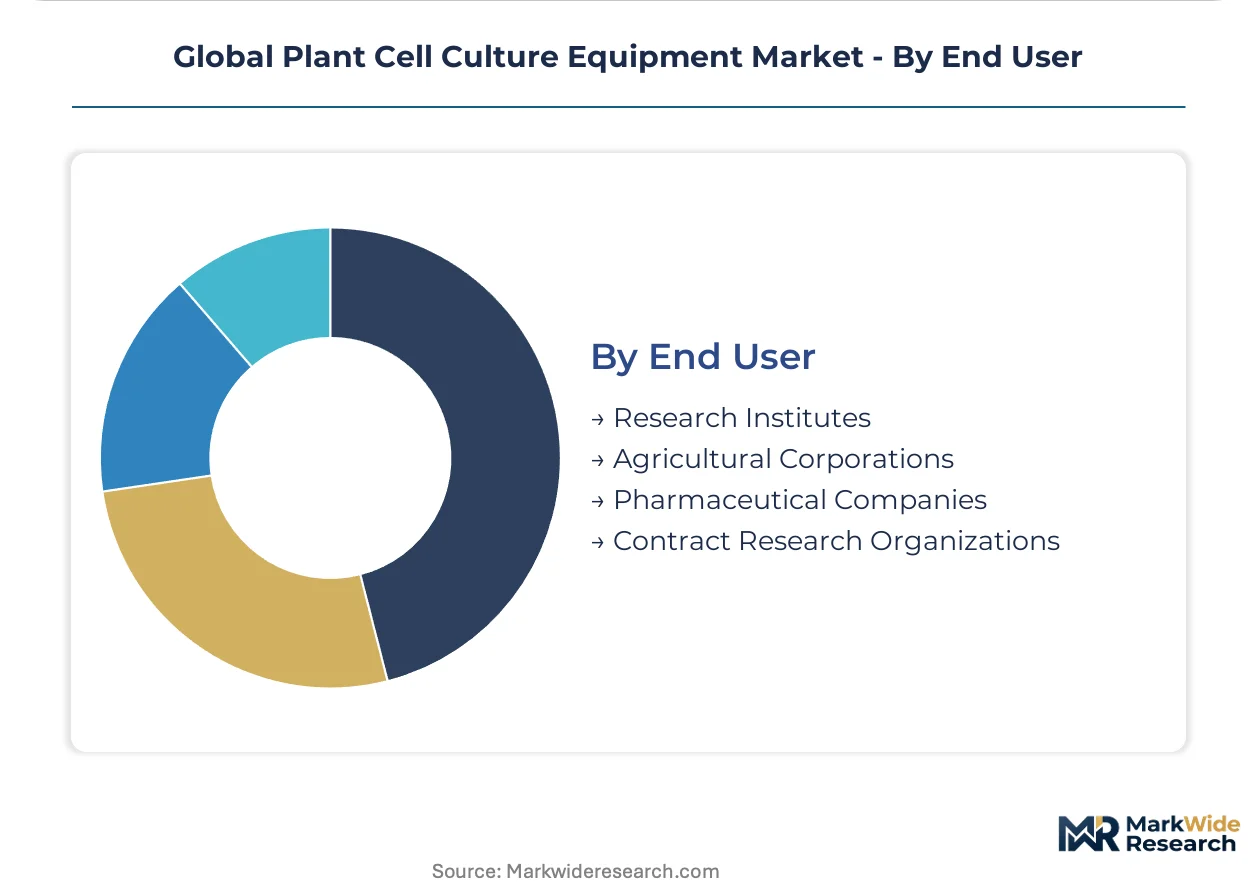
End User:
The volume of plant cell culture equipment procured varies significantly among end-user segments, reflecting their operational scale and strategic objectives.
- Pharmaceutical Companies:These entities invest in high-throughput, automated bioreactor systems for large-scale production of plant-derived therapeutics, driven by regulatory compliance and yield optimization. China's NMPA standards influence equipment design for this sector.
- Research Institutes:These organizations procure a diverse range of equipment, from basic incubators to specialized bioreactors, for fundamental science, preclinical development, and grant-funded projects. Demand is influenced by government funding cycles and academic priorities.
- Agricultural Corporations:These companies utilize plant cell culture equipment for developing improved crop varieties, producing high-value agricultural compounds, and advancing plant breeding programs, often requiring specialized growth chambers.
- Contract Research Organizations:These firms offer specialized services to pharmaceutical and biotech clients, requiring flexible, multi-purpose equipment capable of handling diverse cell lines and project scales efficiently.
Pharmaceutical Companies represent a mature end-user segment for advanced equipment, while Agricultural Corporations show emerging demand for specialized systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized bioprocess engineering talent pool in key regions anchors the development and adoption of advanced plant cell culture equipment. These geographic concentrations facilitate innovation and demand for high-precision systems for diverse applications. Regulatory environments and government initiatives further shape market dynamics across different countries.
United States
Pharmaceutical companies and academic research institutions drive demand for advanced bioreactor systems and integrated sensor technologies. The US FDA's stringent GMP guidelines necessitate sophisticated, validated equipment for therapeutic compound production. Major biotechnology hubs like Boston and San Francisco concentrate research and development activities, requiring continuous investment in new culture technologies.
Germany
Demand for high-value biopharmaceutical production and specialized research applications sustains the market for precision plant cell culture equipment. The European EMA's emphasis on Process Analytical Technology (PAT) influences equipment design for real-time monitoring and quality control. Cities like Munich and Berlin host numerous pharmaceutical companies and research institutes, fostering innovation in bioprocessing.
China
Government support for its biotechnology sector and traditional medicine production accelerates investment in new plant cell culture facilities. China's NMPA imposes strict standards on equipment used for producing traditional medicines, influencing market access. Industrial parks in Shanghai and Guangzhou are emerging as significant centers for manufacturing and research in plant cell culture applications.
India
The growing pharmaceutical sector and increasing academic research activities fuel demand for both cost-effective and advanced plant cell culture equipment. The Central Drugs Standard Control Organization (CDSCO) regulations guide equipment procurement for pharmaceutical applications. Research clusters in cities like Bangalore and Hyderabad are expanding their capabilities in plant biotechnology and metabolic engineering.
Brazil
Agroforestry research and the emerging cultivated food sector present opportunities for specialized growth chambers and culture systems. ANVISA regulations for biopharmaceuticals influence equipment choices for any therapeutic compound production from plant cells. The agricultural research centers in São Paulo and Minas Gerais are exploring plant cell culture for sustainable agriculture and novel ingredient development.
Global Plant Cell Culture Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the plant cell culture equipment market, creating a bifurcated competitive structure. The market sees a division between integrated solution providers offering comprehensive GMP-compliant systems and specialized manufacturers focusing on niche academic or agroforestry applications. Strategic archetypes include full-spectrum bioprocessing suppliers, advanced bioreactor specialists, and cost-effective growth chamber providers. Companies pursue portfolio diversification and technology licensing to maintain their competitive edge.
Specialists in advanced bioprocessing equipment, such as Sartorius AG, occupy a strong position within the high-value pharmaceutical and biotechnology sectors. Thermo Fisher Scientific, a broad portfolio provider, represents the integrated solutions archetype, serving large pharmaceutical clients with comprehensive offerings. Conviron exemplifies suppliers catering to academic and agroforestry sectors, focusing on cost-effective growth chambers for research and propagation needs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Eppendorf AG |
| Merck KGaA |
| Danaher Corporation |
| Corning Incorporated |
| Lonza Group AG |
| GE Healthcare |
| Conviron |
Cost & Logistics Intelligence
Skilled bioprocess engineering talent in established Western markets creates labor-cost differentials that contribute to the tiered pricing of plant cell culture equipment. This directly influences the premium attached to advanced, GMP-compliant systems versus more basic research tools.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing models across the plant cell culture equipment market. Project-based pricing, including validation services, applies to high-end bioreactors, while standardized incubators use per-unit transactional models. Price differentiation stems from GMP certification levels and the degree of customization required for specific cell lines. Cost compression in the academic sector, driven by budget constraints, makes this segment most price-sensitive, unlike pharmaceutical companies which prioritize compliance and performance.
Supply Chain Analysis
Dual-sourcing requirements for critical components are increasingly common among pharmaceutical buyers of plant cell culture equipment. Manufacturing concentration primarily resides in Germany, the United States, and China. The supply chain relies on specialized sensors, stainless steel, and precision control electronics. Single-source vulnerability for highly advanced components presents a significant risk, while distribution occurs through direct sales for complex bioreactors and distributor networks for standardized equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant cell culture equipment market presents a geographic-arbitrage opportunity, leveraging lower manufacturing costs in China against the stringent GMP compliance requirements in Europe. This dynamic shapes strategic investment and market entry decisions across product tiers.
For Market Incumbents: Deepen integration of AI-powered process control systems to enhance product differentiation and address the bioprocess engineering talent gap. Expanding GMP-compliant system portfolios, particularly for emerging markets like China, can mitigate competitive threats from localized manufacturers. Invest in advanced sensor technology to meet evolving Process Analytical Technology (PAT) mandates from regulatory bodies like the European EMA. This strategy reinforces market leadership against price-sensitive alternatives.
For New Entrants and Emerging Players: The price-point gap between high-precision pharmaceutical bioreactors and basic academic equipment offers a clear entry point for modular, configurable systems. Target the emerging cultivated food sector and specialized agroforestry research in regions like Brazil. Focus on cost-effective growth chambers and smaller bioreactors for academic and startup biotechnology segments. Offering flexible, adaptable solutions with lower capital expenditure provides a compelling go-to-market angle.
For Investors and Strategic Acquirers: Large pharmaceutical companies and integrated bioprocessing suppliers are the most active acquirers in this space, seeking to consolidate advanced technologies. The market shows long-term viability driven by expansion into cultivated food ingredients and advanced metabolic engineering applications. Identify acquisition targets specializing in AI-powered process control or single-use bioreactor technologies. Increased patent filings for novel plant cell lines and secondary metabolite production serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand GMP-Compliant Bioreactor Portfolio | Meets stringent regulatory demands from the US FDA for pharmaceutical production. |
| Integrate AI-Powered Process Control | Optimizes yields and reduces batch failures for complex secondary metabolite production. |
| Develop Modular Growth Chambers | Caters to the budget flexibility and experimental versatility required by academic research. |
| Target Cultivated Food Ingredient Sector | Diversifies revenue streams beyond traditional pharmaceutical applications. |
| Invest in Single-Use Bioreactor Technology | Reduces cross-contamination risks and shortens changeover times for contract manufacturing organizations. |
Research Approach
Bottom-up end-user modeling, particularly for pharmaceutical companies and research institutes, reconciled against top-down supply-side tracking of bioreactor manufacturers, forms the analytical core. This approach integrates primary interviews with R&D directors, procurement managers, and bioprocess engineers for qualitative insights. Secondary validation draws from regulatory filings like those from the US FDA and European EMA, alongside academic journals and company annual reports.
Historical trendline analysis of market evolution, combined with a forward-looking analytical framework, projects demand across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates are derived from a robust extrapolation of historical performance and anticipated technological shifts. Key industry-specific forecast inputs include R&D spending in biotechnology and government funding for agroforestry initiatives.
The model assumes a particular technology adoption path; alternative pathways for single-use bioreactor technology would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained R&D investment. Deviation in bioprocess engineering talent availability or raw material supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Genetic Analyzer Systems Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market