
 Insoluble Dietary Fibers Market | 2026-2036
Insoluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Insoluble Dietary Fibers Market Analysis
The EU Green Deal is decoupling insoluble dietary fiber sourcing from conventional grain supply chains by mandating sustainable agricultural practices and transparent ingredient provenance. Cargill, Incorporated leverages its North American grain origination network to secure consistent cellulose feedstock volumes. J. Rettenmaier & Söhne GmbH + Co KG anchors European supply through specialized wood-pulp fiber extraction capabilities in Germany. DuPont competes on modified cellulose technology leadership for beverage suspension applications.
Insoluble dietary fibers comprise non-digestible carbohydrate polymers—primarily cellulose, lignin, and hemicellulose—that resist hydrolysis by human digestive enzymes and functionally add bulk, moisture retention, and texture modification in formulated foods. Cellulose fractions typically achieve beta-1,4-glucan chain lengths exceeding 10,000 glucose units, delivering viscosity control and caloric reduction in bakery matrices. Cellulose dominates product type volumes due to established supply from wood pulp and grain hull processing, while hemicellulose extracts from cereal bran represent the fastest-growing category as prebiotic functionality gains formulation attention. Snack applications command expanding share as extruded products incorporate insoluble fiber for structural integrity and satiety claims.
The FDA's dietary fiber definition under Nutrition Facts Label regulations determines which isolated fibers qualify for health claim eligibility, directly shaping R&D investment priorities among U.S. suppliers. EFSA's health claim assessments under EU Regulation 1924/2006 enforce clinical substantiation thresholds that filter market entrants by evidence quality. China's NMPA and national food safety standards govern novel fiber ingredient approvals, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving regulatory divergence between jurisdictions to align clinical trial programs with claim substantiation requirements.
Market Dynamics
Clean-label reformulation in processed foods is forcing ingredient suppliers to demonstrate fiber provenance from non-GMO and sustainably sourced feedstocks, tightening qualification requirements for bakery and snack manufacturers.
Growth Catalysts
- FDA Nutrition Facts Label modernization:The expanded dietary fiber definition qualifies novel isolates for health claims, accelerating R&D investment in cellulose and hemicellulose variants by U.S. formulators.
- EU Green Deal Farm to Fork mandates:Nutritional labeling requirements for processed foods are tightening, creating compliance-driven demand for certified sustainable fiber ingredients across German functional food manufacturing.
- Wood-pulp extraction technology:Specialized mechanical refining processes in Central European facilities are unlocking higher-purity cellulose fractions for beverage suspension applications.
Market Restraints
- Grain hull supply volatility:Climate-induced yield fluctuations in North American wheat and oat production concentrate input cost risk for cellulose processors dependent on agricultural residues.
- EFSA clinical substantiation thresholds:EU Regulation 1924/2006 enforces evidence quality barriers that filter market entrants by requiring peer-reviewed trials for prebiotic health claims.
- Modified starch substitution:Cost-competitive texturizing agents in emerging-market bakery applications displace insoluble fiber in price-sensitive formulations.
Strategic Opportunities
- India FSSAI novel fiber pathway:India's food safety regulator is establishing approval frameworks for imported fiber isolates, creating first-mover advantage for suppliers with existing GRAS dossiers.
- Cellulose-hemicellulose hybrid systems:Convergent extraction technologies enable dual-function ingredients combining bulk with fermentable prebiotic properties for gut health positioning.
- Direct-to-manufacturer digital procurement:B2B ingredient platforms are disintermediating traditional distributor networks, allowing fiber suppliers to capture margin from mid-sized snack producers.
Industry Challenges
- Novel food approval timelines:China's NMPA extended safety assessment protocols for imported fiber ingredients create 18-24 month market entry delays.
- Extrusion equipment retrofit costs:Legacy snack manufacturing lines require capital-intensive die and screw modifications to process high-fiber matrices without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insoluble Dietary Fibers Market |
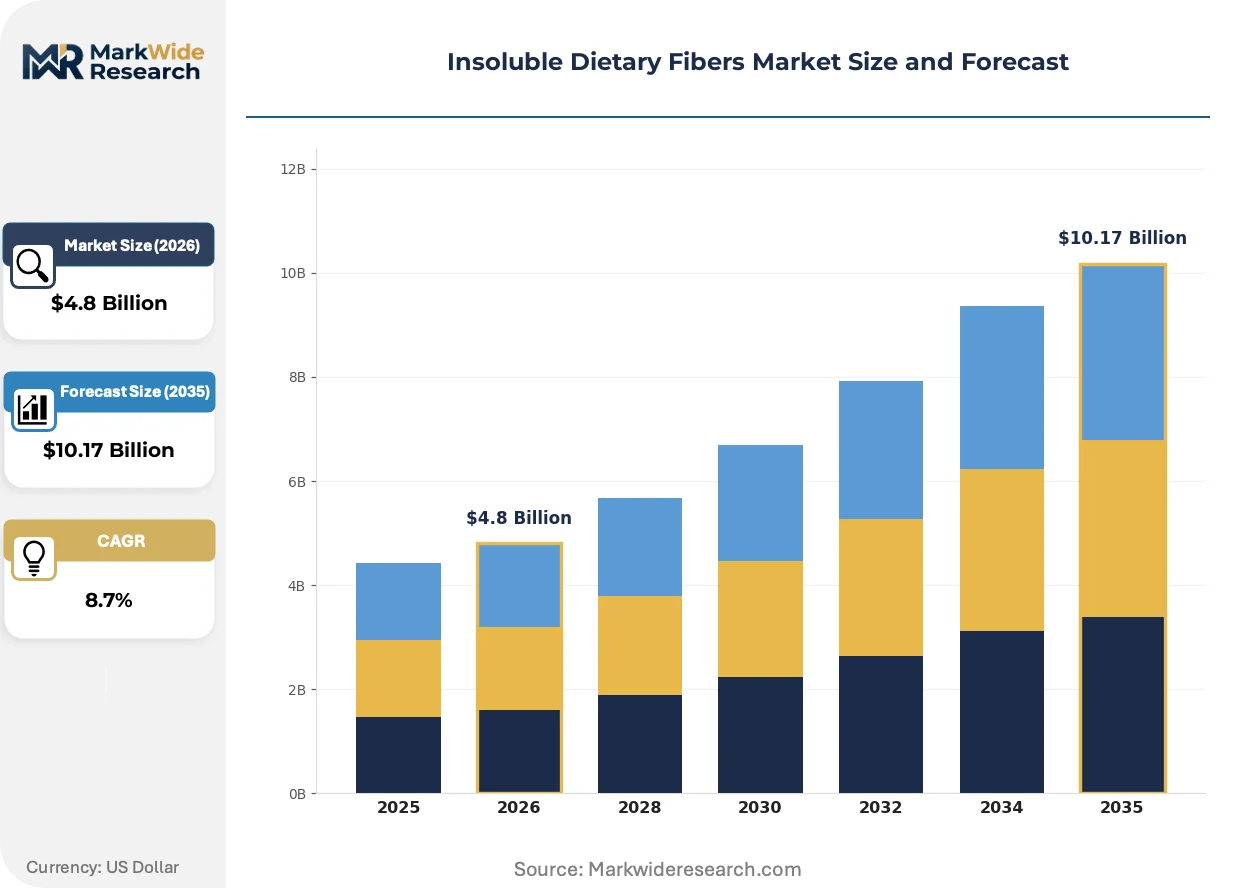
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulose, Lignin, Hemicellulose, Others Application: Beverages, Bakery Products, Dairy Products, Snacks End User: Food Industry, Pharmaceutical Sector, Nutraceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, Grain Processing Corporation, J. Rettenmaier & Söhne GmbH + Co KG, Archer Daniels Midland Company, DuPont, Tate & Lyle, InterFiber Ltd., CFF GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insoluble Dietary Fibers Market Emerging Trajectories
Mechanical and enzymatic fiber refinement technologies are converging with digital formulation tools to enable precision-tailored ingredient systems for clean-label applications.
Enzymatically treated hemicellulose from cereal bran is overtaking conventional cellulose in premium bakery segments. The modified polymer delivers enhanced water-binding capacity alongside fermentable oligosaccharide content. Artisan and industrial bakers in the United States and Germany are adopting these hybrids at accelerated qualification cycles, compressing the addressable market for unmodified cellulose in positioning above commodity price tiers.
REACH-aligned sustainability disclosure requirements are extending chemical sector transparency obligations into food ingredient supply chains. The regulation mandates granular documentation of agricultural input sourcing and processing energy intensity. Wood-pulp fiber extractors in Nordic and German facilities face the steepest compliance ramps, driving investment in certified chain-of-custody systems and third-party carbon accounting.
Formulation laboratories at major food manufacturers are consolidating supplier relationships around integrated fiber-plus-probiotic systems. Bundled ingredient procurement replaces discrete single-component purchasing, compressing vendor counts and elevating technical service expectations. This concentration is most visible in U.S. clean-label snack development, where co-development agreements lock in multi-year supply commitments with preferred fiber suppliers.
Insoluble Dietary Fibers Market Segmentation
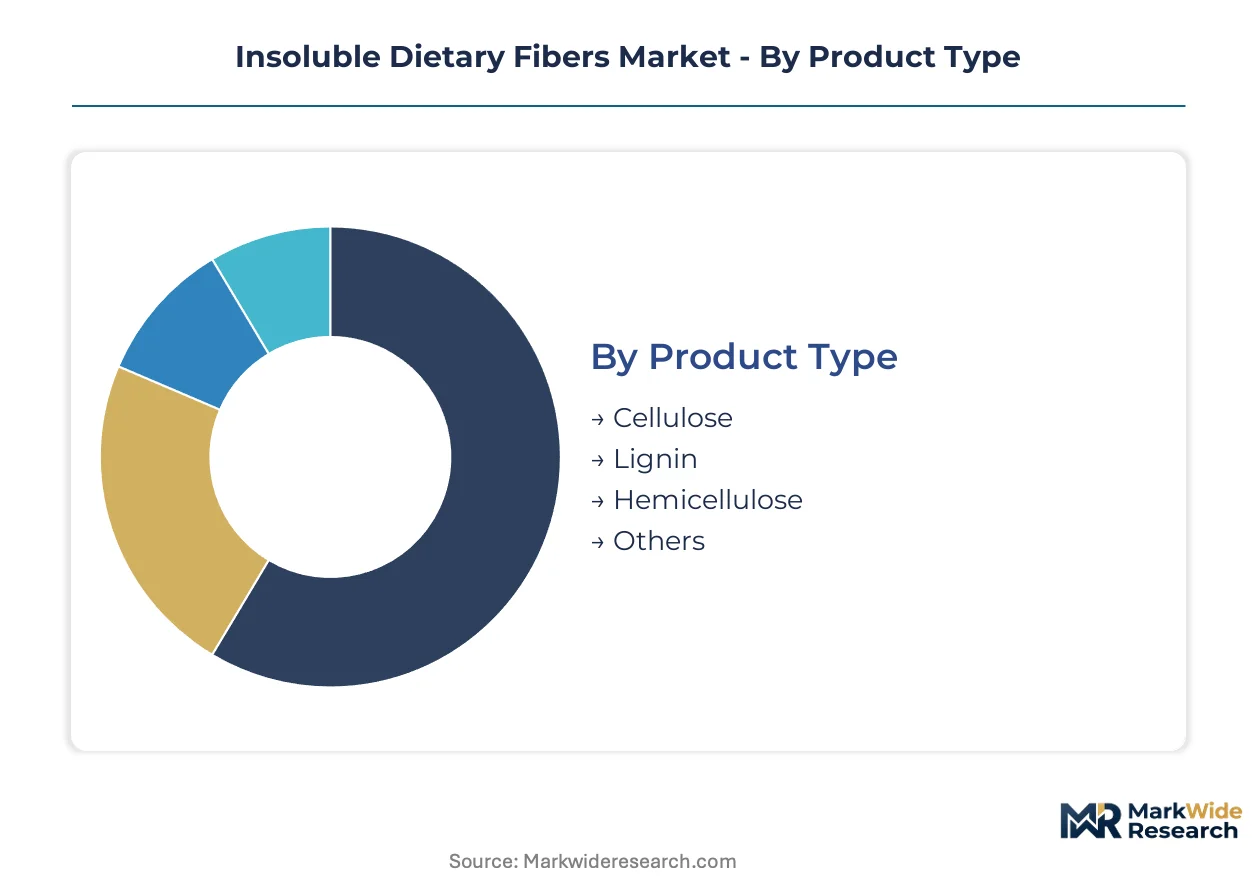
Insoluble dietary fiber suppliers structure product portfolios around extraction technology capabilities and end-use formulation requirements. Segmentation reveals where capital deployment yields durable competitive position versus commodity exposure.
Product Type:
Cellulose extraction demands the heaviest upfront investment in mechanical refining and purification infrastructure, while lignin and hemicellulose processing requires specialized enzymatic or chemical treatment capabilities.
- Cellulose:Beta-1,4-glucan polymers exceeding 10,000 glucose units deliver viscosity control and caloric reduction in bakery matrices. U.S. clean-label reformulation concentrates demand here as FDA-qualified health claims drive qualification cycles. Wood-pulp and grain hull feedstocks dominate supply, with Nordic and German facilities holding established capacity positions.
- Hemicellulose:Cereal bran extracts with fermentable oligosaccharide content enable dual-function positioning for gut health claims. German functional food manufacturers and U.S. artisan bakers are expanding adoption fastest as prebiotic functionality gains formulation attention over unmodified cellulose.
- Lignin:Phenolic polymer fractions from wood processing provide antioxidant properties alongside fiber content. Applications concentrate in animal feed and specialized nutraceutical formulations.
- Others:Chitin and resistant starch variants serve niche pharmaceutical and medical food applications with exacting purity specifications.
Cellulose absorbs the bulk of installed capacity; hemicellulose is expanding most quickly.
Application:
Application segmentation tracks where formulation complexity justifies premium ingredient pricing versus commodity substitution risk.
- Beverages:Modified cellulose systems achieve suspension stability in functional drinks. DuPont's technology leadership in this segment reflects specialized particle engineering for clarity and mouthfeel control.
- Bakery Products:Water-binding and texture modification drive fiber incorporation in bread and pastry matrices. U.S. reformulation accelerates as clean-label claims displace modified starches in premium positioning.
- Dairy Products:Fiber fortification in yogurt and dairy alternatives requires heat-stable variants that survive processing without viscosity breakdown.
- Snacks:Extruded products incorporate insoluble fiber for structural integrity and satiety claims. Legacy manufacturing lines require capital-intensive die modifications to process high-fiber matrices without throughput degradation.
Bakery products command the deepest supplier relationships; snack applications are climbing the fastest as extrusion technology retrofits spread.
End User:
End user segmentation distinguishes between formulation sophistication levels and regulatory scrutiny intensity.
- Food Industry:Processed food manufacturers drive volume through reformulation mandates. EU Green Deal labeling requirements and FDA modernization create compliance-driven procurement in Germany and the United States respectively.
- Pharmaceutical Sector:Excipient-grade fiber requires pharmacopeial compliance and batch documentation. Clinical substantiation thresholds filter suppliers by evidence quality.
- Nutraceuticals:Dietary supplement formulators seek prebiotic-qualified fractions with fermentable oligosaccharide content for gut health positioning.
- Animal Feed:Cost-sensitive bulk applications favor unmodified cellulose from agricultural residues with lower purity requirements.
Food industry procurement dominates volume; nutraceuticals show the steepest expansion trajectory as prebiotic claims proliferate.
Distribution Channel:
Channel segmentation reflects disintermediation pressure and technical service requirements.
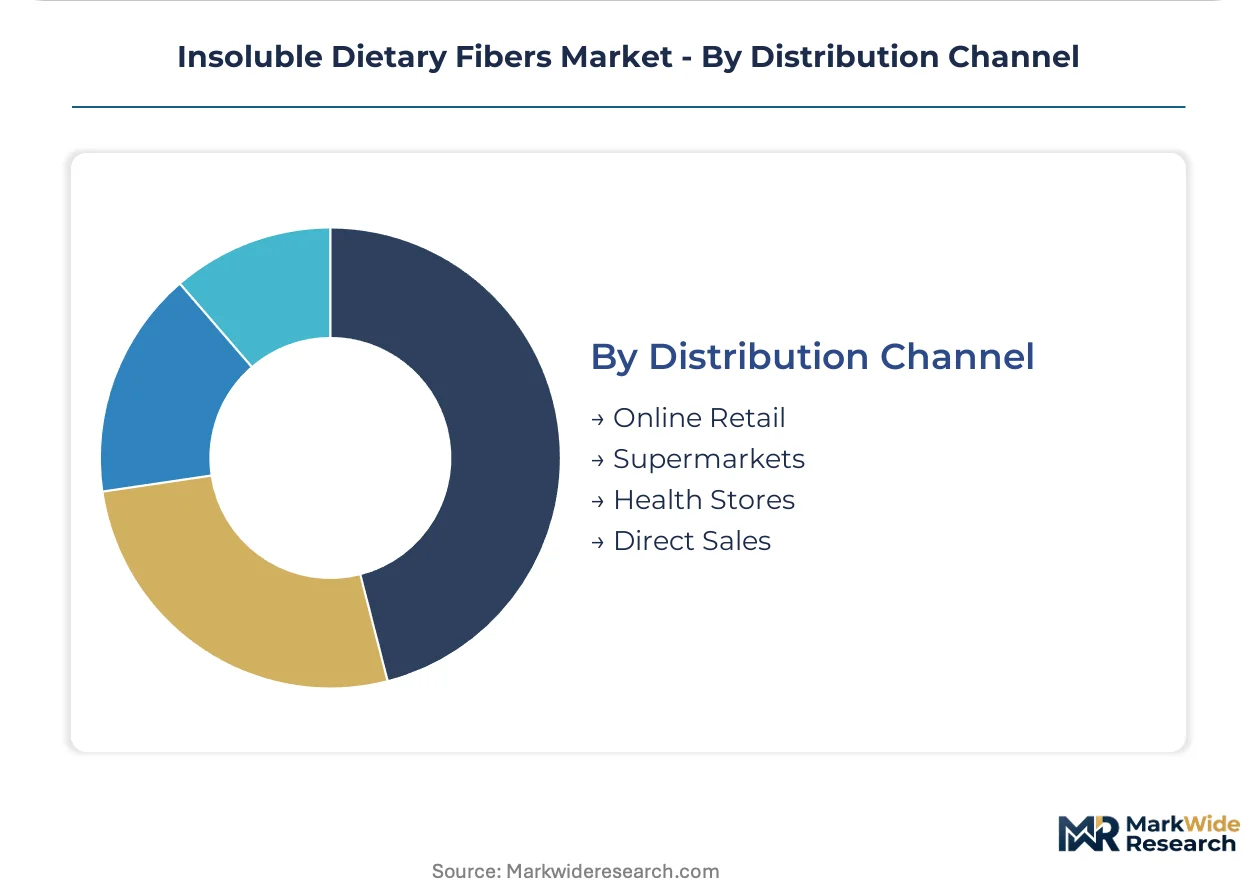
- Direct Sales:Major manufacturers lock in multi-year supply commitments through co-development agreements. Technical service integration justifies relationship concentration in U.S. snack development.
- Online Retail:B2B ingredient platforms enable mid-sized producers to bypass traditional distributors. Margin capture improves for suppliers with digitized specification documentation.
- Supermarkets:Ingredient procurement for private-label products runs through consolidated food manufacturing intermediaries.
- Health Stores:Small-batch nutraceutical and specialty food producers source through regional distributors with formulation support capabilities.
Direct sales anchor strategic accounts; online retail is gaining share fastest as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American insoluble fiber procurement through its concentration of clean-label bakery reformulation laboratories and grain processing infrastructure. The metropolitan corridor connects cellulose suppliers to midwestern agricultural residue networks while serving as a distribution node for extruded snack manufacturers.
United States
Clean-label bakery reformulation accelerates demand for cellulose and hemicellulose variants across industrial and artisan baking segments. FDA Nutrition Facts Label modernization qualifies novel fiber isolates for health claims, directing R&D investment toward clinically substantiated ingredients. Minneapolis-St. Paul clusters grain hull processors and cellulose extractors serving national bakery chains.
Germany
Functional food manufacturers in Bavaria and Baden-Württemberg expand insoluble fiber fortification programs for processed food portfolios. EU Green Deal Farm to Fork mandates tighten nutritional labeling requirements, creating compliance-driven procurement for certified sustainable fiber ingredients. Rosenheim hosts specialized wood-pulp fiber extraction facilities supplying beverage suspension applications.
China
Snack extrusion manufacturers in Shandong and Guangdong provinces incorporate insoluble fiber for structural integrity and satiety positioning in functional foods. NMPA extended safety assessment protocols for imported fiber ingredients create 18-24 month approval timelines that filter market entrants. Qingdao clusters domestic cellulose processors serving regional bakery and dairy reformulation.
India
Mid-sized snack producers in Maharashtra and Gujarat adopt fiber fortification as FSSAI establishes approval frameworks for imported isolates. The novel fiber pathway creates first-mover advantage for suppliers with existing GRAS dossiers seeking market entry. Mumbai-Pune corridor concentrates formulation laboratories evaluating hemicellulose hybrids for prebiotic positioning.
Japan
Functional beverage manufacturers in Kanto region deploy modified cellulose systems for suspension stability in health-positioned drinks. METI guidelines on food functionality claims shape clinical trial investment priorities among fiber suppliers seeking substantiation. Osaka-Kobe industrial zone hosts precision particle engineering facilities serving premium beverage applications.
Insoluble Dietary Fibers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across extraction technology sophistication and clinical substantiation capabilities. The vendor base stratifies between integrated grain processors with captive cellulose supply and specialized fiber extractors with proprietary mechanical refining systems. Three archetypes dominate: North American agricultural conglomerates with origination network advantages, Central European wood-pulp specialists with sustainability certification leadership, and modified polymer technology licensors serving beverage suspension markets. Competitive moves concentrate on co-development agreements locking multi-year supply commitments and backward integration into certified sustainable feedstock sourcing.
Within the integrated agricultural processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven positions anchored to North American grain origination networks. Among Central European specialists, J. Rettenmaier & Söhne GmbH + Co KG occupies a position representing wood-pulp extraction capabilities with REACH-aligned sustainability disclosure compliance. DuPont sits within the modified cellulose technology tier, anchoring beverage application expertise through particle engineering specialization. These three represent distinct competitive vectors: agricultural residue leverage, sustainable forestry integration, and polymer modification science.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| Grain Processing Corporation |
| J. Rettenmaier & Söhne GmbH + Co KG |
| Archer Daniels Midland Company |
| DuPont |
| Tate & Lyle |
| InterFiber Ltd. |
| CFF GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Backward integration into certified feedstock sourcing anchors both supply security and pricing power for cellulose extractors serving U.S. and German bakery reformulation. Captive wood-pulp operations in Nordic facilities and grain hull origination networks in North America insulate qualified suppliers from agricultural residue cost volatility while commanding premium positioning.
Pricing Analysis
Yield-based pricing anchors cellulose contracts to functional outcomes in bakery moisture retention and caloric reduction. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified sustainable grades from conventional wood-pulp fractions and unmodified agricultural residues. Cost compression in economy tiers intensifies because modified starch substitutes undercut fiber in price-sensitive emerging-market formulations. Mid-sized snack producers exhibit highest price sensitivity; pharmaceutical excipient buyers accept substantial premiums for pharmacopeial documentation.
Supply Chain Analysis
Agricultural residue returns and bran reprocessing flows create circular feedstock channels for hemicellulose extractors in Germany and the United States. Primary supply concentrates in Germany, the United States, and China, with Nordic wood-pulp operations and North American grain processing anchoring cellulose availability. The chain rests on wheat bran, oat hulls, and specialty wood pulp as core inputs. Single-source vulnerability runs through climate-exposed North American grain harvests. Distribution runs through direct co-development agreements with major manufacturers and emergent B2B digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over certified sustainable feedstocks and downstream technical service integration determine margin capture. Players are pursuing captive origination networks to lock in supply security and qualification priority.
For Market Incumbents: Extend sustainability certification coverage to preempt EU Green Deal compliance requirements before Farm to Fork labeling mandates tighten. Add mechanical refining capacity in Rosenheim or Minneapolis-St. Paul to defend against Central European specialists expanding North American presence. Modified starch substitution in emerging-market bakery applications represents the core displacement threat.
For New Entrants and Emerging Players: Enter via India's FSSAI novel fiber pathway before approval frameworks mature and incumbent dossiers dominate qualification. Target mid-sized Maharashtra snack producers seeking prebiotic-positioned hemicellulose hybrids with shorter lead times than established suppliers. Digital B2B procurement platforms offer direct manufacturer access without distributor margin capture.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated agricultural processors seeking cellulose technology capabilities. Long-term viability favors extractors with dual feedstock flexibility across wood pulp and grain residues. Watch NMPA approval timelines for imported fiber isolates as inflection indicator for China market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedstock Sourcing | REACH-aligned chain-of-custody systems secure EU Green Deal compliance positioning for German functional food supply. |
| Cellulose-Hemicellulose Hybrid System Development | Dual-function ingredients combining bulk with fermentable prebiotic properties capture gut health claim premiums. |
| Direct-to-Manufacturer Digital Platform Launch | B2B procurement disintermediation captures margin from mid-sized U.S. snack producers accelerating reformulation. |
| Pharmaceutical Excipient Grade Certification | Pharmacopeial compliance opens high-margin medical food and nutraceutical applications with batch documentation requirements. |
| Extrusion Equipment Partnership Program | Technical service integration with snack manufacturers reduces retrofit barriers and locks multi-year supply commitments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cellulose extraction plant managers, bakery procurement leads at national chains, technical R&D directors at functional food manufacturers, and FSSAI regulatory affairs specialists combined with secondary validation. FDA Nutrition Facts Label guidance documents, EFSA health claim assessments under EU Regulation 1924/2006, NMPA novel food safety protocols, and REACH sustainability disclosure requirements supplemented bottom-up and top-down triangulation.
Data-stream reconciliation across volume shipments, capacity utilization rates, and end-use qualification cycles informed the analytical framework. Segmentation dimensions modeled include extraction technology tier, functional application, end-user regulatory scrutiny intensity, and regional certification requirements across the projection horizon. CAGRs derived from fitted trend analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs encompassed climate-induced yield fluctuation patterns in North American grain production and extrusion equipment retrofit adoption curves.
Revisions become necessary when NMPA extends safety assessment timelines, EFSA tightens clinical substantiation thresholds, or climate events disrupt North American wheat and oat harvests. Forecasts reflect assumptions about regulatory pathway stability and feedstock supply continuity. Practitioners should monitor FSSAI novel fiber approval velocity and EU Green Deal implementation pace for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Vietnam Collagen Supplements Market