
 Isolate Whey Protein Market | 2026-2036
Isolate Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Isolate Whey Protein Market Analysis
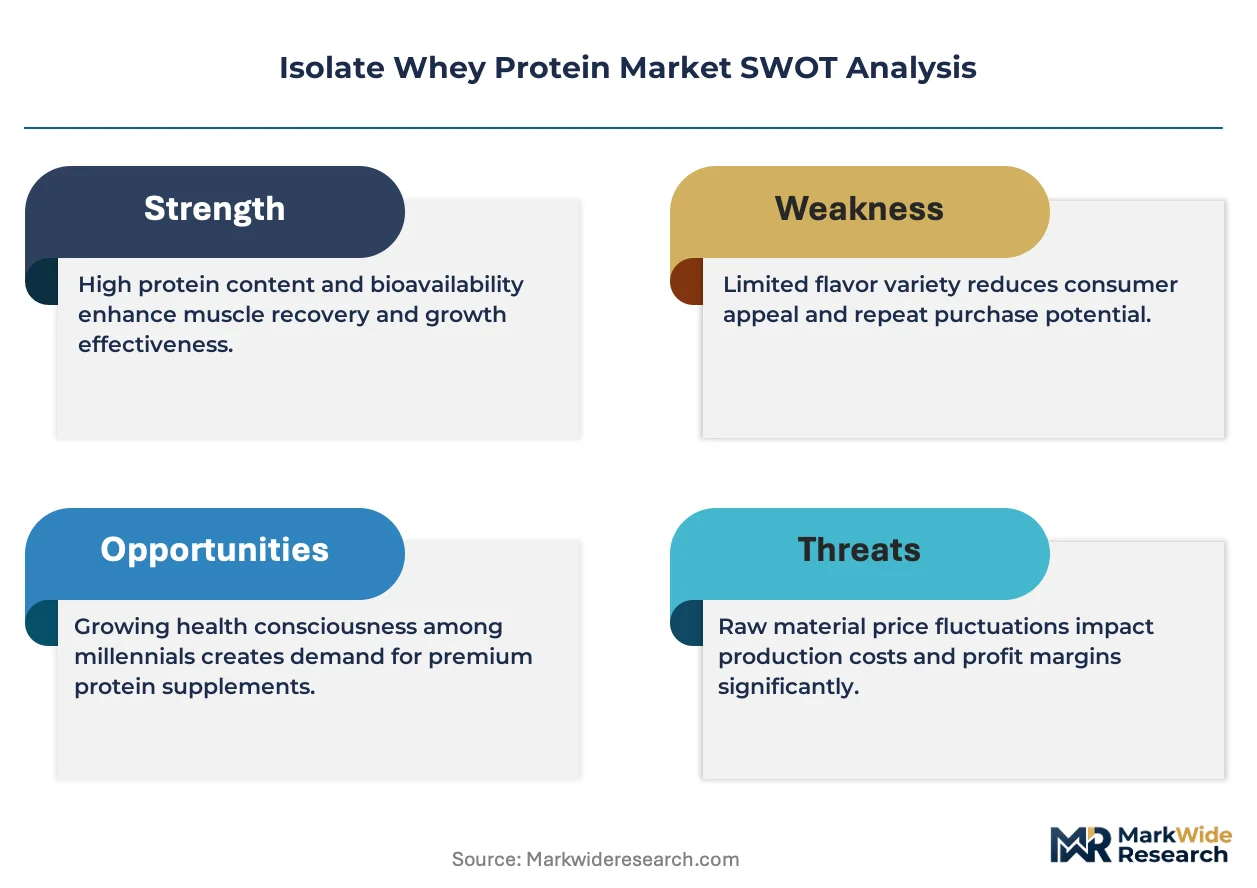
Cross-flow microfiltration and ion-exchange refinement is narrowing the quality gap between commodity whey and pharmaceutical-grade isolates. Glanbia plc leverages its Irish dairy cooperative roots to sustain vertical integration from grass-fed sourcing to finished isolate powder. Arla Foods Ingredients anchors European supply through its Danish-Swedish processing network. Fonterra Co-operative Group dominates Oceania output with farmer-owned milk collection systems spanning New Zealand.
Whey protein isolate denotes a dairy derivative containing at least 90% protein by dry weight, achieved through microfiltration or ion-exchange chromatography that strips lactose, fat, and minerals from liquid whey; manufacturers deploy this ingredient to deliver high-bioavailability amino acid profiles in low-calorie formats. Organic isolate commands premium shelf positioning as consumers scrutinize feed-source traceability, while unflavored variants occupy bulk manufacturing channels where downstream brands control flavor masking. Online retail extends fastest among distribution channels as direct-to-consumer sports nutrition brands bypass traditional wholesale markups.
FDA GRAS self-affirmation and EFSA novel food assessments govern isolate purity claims and allergen labeling across North America and Europe, while China's SAMR mandates dairy import registration that filters market access for uncertified foreign suppliers. Stakeholders must monitor how emerging precision fermentation alternatives reshape protein sourcing decisions before committing to multi-year whey processing capacity expansions.
Market Dynamics
Sports nutrition brands now command larger procurement volumes than traditional dairy channels, forcing processors to retool filtration lines for pharmaceutical-grade purity standards demanded by direct-to-consumer supplement labels.
Growth Catalysts
- EFSA Clean-Label Certification:European processors are upgrading to cross-flow microfiltration systems to meet EFSA novel food assessments, unlocking premium shelf positioning in German and French retail.
- Grass-Fed Sourcing Mandates:Organic isolate demand from US functional food manufacturers is pulling Irish and New Zealand cooperatives toward certified pasture-based supply chains.
- Sports Nutrition Channel Expansion:Direct-to-consumer brands in China are bypassing wholesale markups through SAMR-registered e-commerce platforms, accelerating volume commitments to Oceania processors.
Market Restraints
- Input Cost Volatility:Fluid milk price swings in New Zealand and Europe transmit directly to whey feedstock costs, compressing processor margins during commodity dairy downturns.
- Supply Concentration Risk:Oceania output dominance by farmer-owned cooperatives creates single-region dependency for Asian buyers seeking pharmaceutical-grade isolates.
- Precision Fermentation Substitution:Lab-grown protein alternatives from US biotech startups threaten to displace whey isolate in vegan-positioned sports nutrition formulations.
Strategic Opportunities
- Underpenetrated Chinese Clinical Nutrition:Hospital and eldercare channels in tier-two Chinese cities remain unserved by isolate suppliers focused on gym and sports positioning.
- FDA GRAS Self-Affirmation Tailwinds:Streamlined US regulatory pathways for protein ingredients enable faster product launches in medical foods and weight management segments.
- Cold-Chain Direct Distribution:Refrigerated last-mile logistics partnerships with German pharmacy chains open fresh isolate formats previously confined to powder.
Industry Challenges
- Filtration Engineering Talent Scarcity:Cross-flow membrane specialists command premium salaries as dairy processors compete with biopharma for chromatography expertise.
- Dual Certification Timelines:Simultaneous FDA GRAS and EFSA novel food approvals extend product launch cycles by 18-24 months for brands targeting transatlantic distribution.
- Legacy Dairy Equipment Retrofit Costs:Converting commodity whey plants to isolate-grade ion-exchange capacity requires capital outlays that strain mid-tier processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isolate Whey Protein Market |
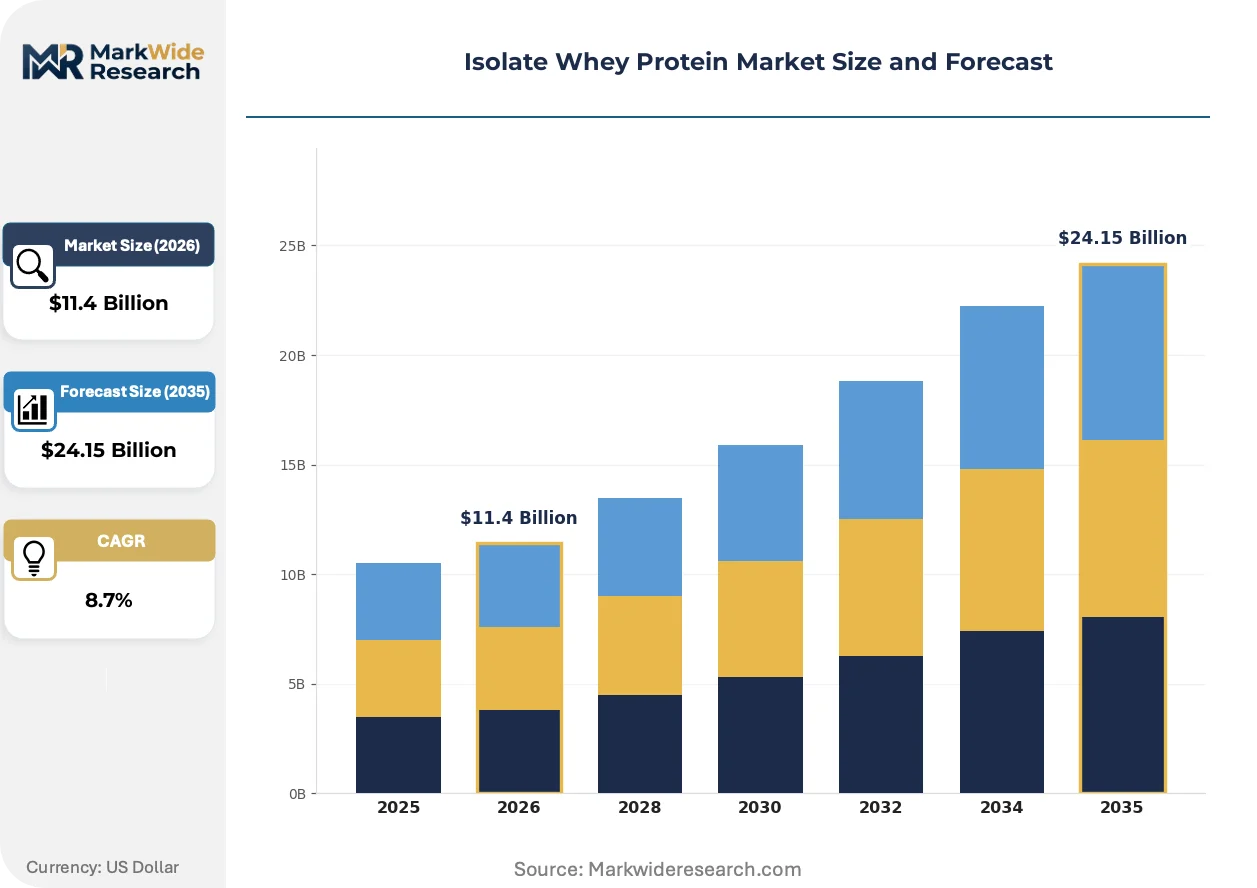
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Isolate, Non-GMO Isolate, Flavored Isolate, Unflavored Isolate End User: Athletes, Fitness Enthusiasts, Nutritional Supplement Users, Bodybuilders Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores Packaging Type: Bags, Tubs, Pouches, Sachets |
| Companies Covered | Glanbia plc, Arla Foods Ingredients, Fonterra Co-operative Group, Saputo Inc., Hilmar Cheese Company, Lactalis Ingredients, FrieslandCampina, Agropur, Carbery Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isolate Whey Protein Market Emerging Trajectories
Filtration technology convergence with pharmaceutical purification standards is collapsing the historical quality gap between commodity whey and clinical-grade isolates, while regulatory fragmentation and channel disintermediation rewrite competitive rules.
Cross-flow microfiltration paired with ceramic membrane cascades is collapsing the cost premium historically separating 90% isolate from lower-concentrate alternatives. Sports nutrition contract manufacturers in Germany and the United States are adopting these systems at replacement cycle points. The technology is collapsing three-tier pricing structures that once stratified commodity, premium, and pharmaceutical grades into a compressed premium-mid band.
EFSA's tightened novel food assessment timelines for dairy-derived ingredients are forcing European processors to front-load clinical bioavailability studies. The industrial consequence is a bifurcation between large cooperatives with in-house research capabilities and smaller operators forced into toll-manufacturing arrangements. German isolate suppliers targeting medical nutrition applications are most affected, responding by pre-submission engagement with EFSA scientific panels.
Direct-to-consumer sports nutrition brands are consolidating procurement decisions away from ingredient distributors toward processor-direct relationships. This channel compression is displacing traditional wholesale markups in the United States and United Kingdom, with online-native labels negotiating volume commitments that mirror former dairy cooperative arrangements. The shift is most visible among UK-based functional food startups sourcing unflavored isolate for in-house flavor masking and branding.
Isolate Whey Protein Market Segmentation
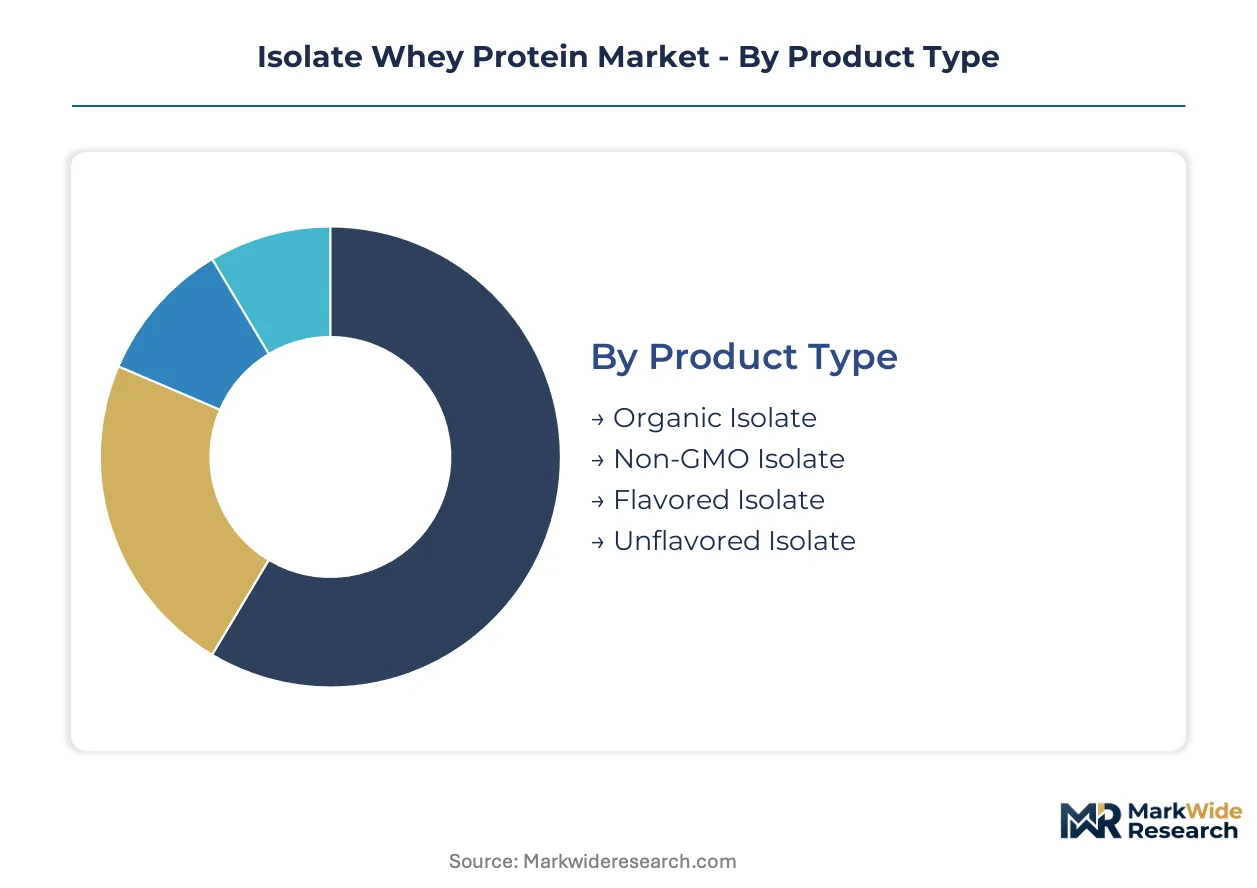
Isolate whey protein segments reflect divergent purity standards, procurement behaviors, and channel economics that processors must navigate simultaneously. Each category captures distinct margin structures and certification requirements that reshape competitive positioning across sports nutrition and clinical applications.
Product Type:
Formulation choices span feed-source traceability, genetic modification status, and flavor integration — each carrying different EFSA and FDA compliance burdens and shelf-price premiums.
- Organic Isolate:Derived from grass-fed dairy herds with certified pasture protocols, this grade commands premium positioning in German and French retail where EFSA organic labeling requirements apply. Irish and New Zealand cooperatives dominate supply as US functional food manufacturers pull certified volumes toward medical nutrition applications.
- Unflavored Isolate:Bulk powder formats with neutral taste profiles serve contract manufacturers and direct-to-consumer brands that control in-house flavor masking. UK-based functional food startups and Chinese SAMR-registered e-commerce platforms drive procurement volumes through processor-direct relationships that bypass traditional wholesale markups.
- Non-GMO Isolate:Verified absence of genetically modified feed sources meets clean-label demands from European sports nutrition brands targeting EFSA-compliant positioning.
- Flavored Isolate:Pre-formulated variants with vanilla, chocolate, or fruit profiles reduce downstream processing steps for smaller brands lacking R&D capabilities.
Established volume favors unflavored isolate; emerging adoption favors organic isolate.
End User:
Consumer archetypes range from performance-obsessed competitors to maintenance-oriented wellness seekers, with protein dosing protocols and purchase frequency varying dramatically.
- Athletes:Competitive and recreational competitors in tier-one Chinese cities and US metropolitan areas consume isolate for post-workout recovery, with direct-to-consumer brands capturing loyalty through subscription models. SAMR-registered platforms and FDA GRAS-compliant domestic suppliers compete for their recurring volume.
- Nutritional Supplement Users:Elderly and clinical populations in German hospital and eldercare channels utilize isolate for sarcopenia prevention and medical food applications. EFSA novel food assessments and streamlined FDA pathways for protein ingredients enable faster product launches in these segments compared to sports positioning.
- Fitness Enthusiasts:Gym-attending consumers seeking body composition improvement represent stable baseline demand across online retail channels.
- Bodybuilders:High-dose consumers prioritize protein-per-serving economics and bioavailability claims in their procurement decisions.
Volume concentrates with fitness enthusiasts; steepest expansion trajectory sits with nutritional supplement users.
Distribution Channel:
Channel selection determines margin capture, brand control, and regulatory exposure for isolate suppliers navigating fragmented retail landscapes.
- Online Retail:Direct-to-consumer platforms and brand-owned storefronts bypass wholesale markups, with refrigerated last-mile logistics partnerships enabling fresh isolate formats previously confined to powder. German pharmacy chains and US sports nutrition native brands drive infrastructure investment in cold-chain capabilities.
- Specialty Stores:Dedicated sports nutrition retailers in the United Kingdom and Germany provide educated staff and sampling opportunities that accelerate trial among new users.
- Supermarkets:Mass-market placement requires price compression and simplified SKUs that strain isolate-grade margin structures.
- Health Food Stores:Independent natural products retailers emphasize organic and non-GMO certification alignment in their assortment decisions.
Margin protection favors specialty stores; volume scaling favors online retail.
Packaging Type:
Format economics balance convenience, shelf stability, and shipping efficiency across consumer usage occasions and B2B procurement patterns.
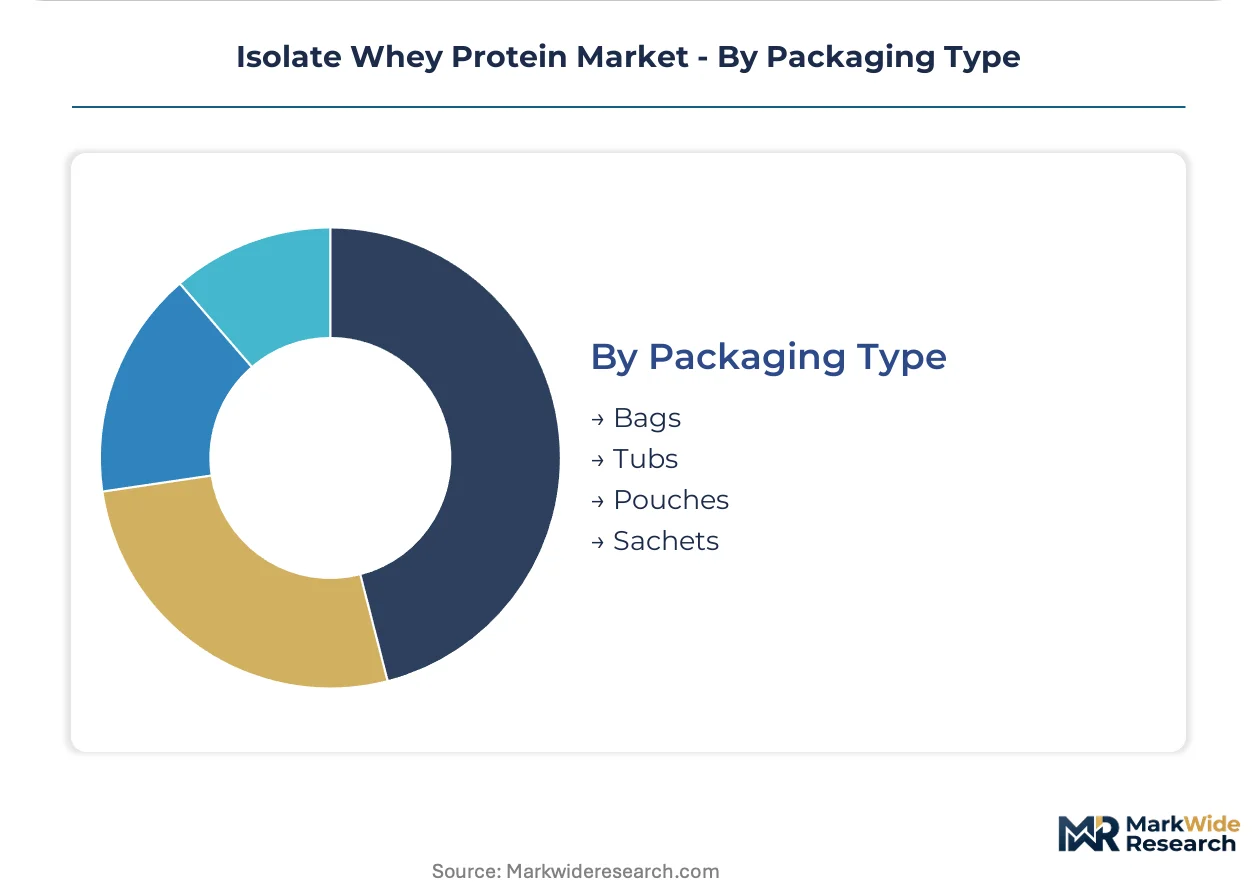
- Tubs:Rigid plastic containers with resealable lids dominate home-use scenarios in the United States and Germany, offering moisture protection and scoop convenience that supports premium pricing. Sports nutrition brands specify tub formats for their direct-to-consumer flagship products.
- Sachets:Single-serve foil packets enable precise portion control and travel convenience, gaining traction among Chinese e-commerce platforms targeting gym-goers in tier-two cities and clinical nutrition sampling programs in German eldercare facilities.
- Bags:Flexible multi-serve packaging reduces material costs for bulk purchasers and private-label distributors.
- Pouches:Stand-up flexible formats with resealable closures bridge convenience and sustainability positioning for mid-tier brands.
Household penetration favors tubs; sampling and trial conversion favor sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand isolate processors ship pharmaceutical-grade volumes to Chinese SAMR-registered importers, while Irish cooperatives feed US functional food manufacturers seeking grass-fed certification. This trade-flow architecture concentrates processing capacity in dairy-exporting nations with established cold-chain infrastructure.
United States
FDA GRAS self-affirmation pathways accelerate product launches for medical foods and weight management segments. Sports nutrition brands in metropolitan markets bypass wholesale markups through direct-to-consumer subscription models. California and Texas host the largest concentration of contract manufacturers retooling for isolate-grade ion-exchange capacity.
Germany
EFSA novel food assessments drive front-loaded clinical bioavailability studies among processors targeting medical nutrition applications. German pharmacy chains invest in refrigerated last-mile logistics for fresh isolate formats. Bavaria and North Rhine-Westphalia anchor European cross-flow microfiltration equipment adoption.
China
SAMR dairy import registration filters market access for foreign suppliers while domestic direct-to-consumer brands scale through e-commerce platforms. Tier-two cities present underpenetrated hospital and eldercare channels. Yangtze River Delta processing clusters absorb Oceania whey feedstock for regional formulation.
Ireland
Grass-fed pasture certification protocols position Irish cooperatives for premium US organic isolate procurement. EFSA organic labeling compliance enables shelf positioning in French and German retail. Munster and Leinster dairy regions sustain vertical integration from grass-fed sourcing to finished powder.
New Zealand
Farmer-owned cooperative structures dominate Oceania output, creating single-region dependency for Asian pharmaceutical-grade buyers. Fluid milk price volatility transmits directly to whey feedstock costs. Canterbury and Waikato processing hubs supply cross-flow microfiltration isolates to SAMR-registered Chinese importers.
Isolate Whey Protein Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Large dairy cooperatives leverage farmer-owned milk collection systems to secure feedstock access, while mid-tier processors rely on toll-manufacturing arrangements with limited in-house research capabilities. Three archetypes dominate: vertically integrated cooperatives with grass-fed certification, ion-exchange technology specialists, and contract manufacturers serving direct-to-consumer brands. Capacity expansion and regulatory pre-certification represent the dominant competitive moves as processors target transatlantic distribution.
Among Irish and New Zealand-based cooperatives, Glanbia plc and Fonterra Co-operative Group exemplify the vertically integrated archetype, leveraging geographic origin for grass-fed sourcing narratives. Arla Foods Ingredients occupies a position within the European technology-specialist tier, anchoring Danish-Swedish processing network capabilities.
| Leading Market Players |
|---|
| Glanbia plc |
| Arla Foods Ingredients |
| Fonterra Co-operative Group |
| Saputo Inc. |
| Hilmar Cheese Company |
| Lactalis Ingredients |
| FrieslandCampina |
| Agropur |
| Carbery Group |
| Others |
Supply Flow & Price Mechanics
New Zealand and Irish farmer-owned cooperatives anchor pharmaceutical-grade whey feedstock supply, concentrating margin capture at the grass-fed sourcing tier while downstream powder processors compete on filtration technology economics.
Pricing Analysis
Cross-flow microfiltration systems command premium positioning against legacy ion-exchange installations, with ceramic membrane cascades collapsing the cost gap between 90% isolate and lower-concentrate alternatives. Three-tier pricing structure across pharmaceutical-grade, premium sports nutrition, and bulk commodity tiers reflects certification intensity and bioavailability documentation depth. Pricing pressure stems from precision fermentation alternatives threatening vegan-positioned formulations, compressing willingness-to-pay in ethical-segment sports nutrition. Contract manufacturers exhibit highest price sensitivity due to volume procurement and thin flavor-masking margins, while direct-to-consumer brands absorb premium positioning for traceability narratives.
Supply Chain Analysis
Fluid whey feedstock draws from New Zealand, Ireland, and Denmark as dominant dairy-exporting nodes with established cold-chain infrastructure for pharmaceutical-grade isolate shipment. Raw material dependencies center on grass-fed milk collection systems, ceramic membrane filtration components, and ion-exchange resin chemistries. Single-region concentration risk runs through Oceania farmer-owned cooperatives, creating vulnerability for Asian buyers seeking SAMR-registered import pathways. Distribution runs through processor-direct relationships with direct-to-consumer sports nutrition brands, displacing traditional ingredient distributor markups in United States and United Kingdom channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isolate whey protein sits in early-cycle expansion as clinical nutrition applications penetrate Chinese hospital and eldercare channels previously confined to sports positioning, with EFSA and FDA regulatory tailwinds accelerating medical food formulation adoption.
For Market Incumbents: Insulate grass-fed sourcing narratives through certified pasture protocol investments in Ireland and New Zealand, locking in premium procurement relationships with US functional food manufacturers. Deepen backward integration into farmer-owned milk collection systems to secure feedstock access against emerging precision fermentation substitutes. Prioritize dual FDA GRAS and EFSA novel food pre-certification to compress transatlantic product launch timelines.
For New Entrants and Emerging Players: Pursue toll-manufacturing arrangements with mid-tier processors lacking in-house chromatography expertise, capturing margin from filtration engineering talent scarcity. Target tier-two Chinese cities for clinical nutrition positioning in hospital and eldercare channels underserved by gym-focused incumbents. Lead with SAMR-registered e-commerce distribution partnerships to bypass wholesale infrastructure requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward ion-exchange technology specialists with existing EFSA engagement records and scalable ceramic membrane capacity, given long-term viability hinges on regulatory pre-certification moats. Watch for inflection signals in precision fermentation cost curves that would accelerate displacement timelines in vegan-positioned sports nutrition segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Flow Microfiltration Capacity Expansion | Ceramic membrane adoption collapses quality-cost gaps between commodity and pharmaceutical grades. |
| Dual Certification Pre-Investment | Simultaneous FDA GRAS and EFSA novel food submissions compress transatlantic launch cycles. |
| Grass-Fed Sourcing Certification | Irish and New Zealand pasture protocols unlock premium US organic isolate procurement. |
| Direct-to-Consumer Channel Partnerships | Processor-direct relationships with online-native brands displace traditional wholesale markups. |
| Clinical Nutrition Format Development | Sachet packaging for German eldercare and Chinese hospital channels expands beyond powder. |
Methodological Framework
Desk research of dairy cooperative annual reports, EFSA novel food assessment databases, and SAMR import registration filings preceded structured interviews with filtration technology engineers, sports nutrition brand procurement directors, clinical nutrition product managers, and dairy processing plant operators. Primary fieldwork across Irish, New Zealand, German, and Chinese processing hubs was validated against FDA GRAS affirmation records, customs trade data, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume modeling triangulated against top-down protein ingredient market assessments.
Assumptions held fluid milk price volatility and precision fermentation cost trajectories within bounded sensitivity ranges across the projection horizon, while regulatory approval timelines and channel adoption curves were varied. Segmentation dimensions modeled include feed-source certification tier, end-use application archetype, distribution channel structure, and regional regulatory cluster. CAGRs were derived from fitted adoption curves applied to processor capacity expansion announcements and import registration volumes. Forecast inputs incorporated EFSA assessment pipeline data and Chinese e-commerce platform protein category growth metrics.
Sensitivities concentrate around precision fermentation substitution rates, New Zealand fluid milk price swings, and SAMR registration policy shifts affecting foreign supplier access. Cross-checking against dairy futures market indicators and alternative protein investment flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Diet Pills Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Global Oncology Nutrition Market