
 Global Protein Market | 2026-2036
Global Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Market Outlook
Pea protein isolate is broadening its addressable market as a cost-competitive alternative to whey and soy across beverage and bakery formulations. Cargill leverages its North American agricultural origination network to secure consistent raw material flows for plant protein extraction. Kerry Group PLC specializes in taste-masked protein systems that anchor its position within the sports nutrition and functional beverage categories. Glanbia PLC dominates whey protein concentrate supply through its Irish and US processing assets.
Proteins are nitrogen-containing macromolecules composed of amino acid chains linked by peptide bonds, typically delivering 4 kcal per gram and functional properties including emulsification, gelation, and water binding. The global protein industry supplies these macromolecules as nutritional fortifiers, texture modifiers, and complete meal replacements across packaged goods and clinical applications. Animal protein retains the largest revenue pool due to entrenched dairy and meat processing infrastructure, though plant protein registers the fastest trajectory as beverage brands reformulate for flexitarian consumers. Dairy protein commands premium positioning in infant formula and medical nutrition, where protein digestibility-corrected amino acid scores determine procurement specifications.
The US FDA oversees protein content labeling accuracy and health claim substantiation under Nutrition Labeling and Education Act provisions, while EFSA in Europe sets novel food safety benchmarks for emerging protein sources including insect and single-cell ingredients. China's SAMR enforces GB standards for protein fortification limits in complementary foods and sports products, shaping formulation ceilings for exporters. India's FSSAI mandates protein quality disclosures on packaged foods, tightening compliance costs for multinational suppliers. Stakeholders must monitor divergence between Codex Alimentarius guidelines and regional enforcement intensity when allocating R&D and registration budgets across production geographies.
Market Dynamics
Protein ingredient procurement is bifurcating between legacy animal-derived supply chains and emerging precision fermentation capacity, with facility certification timelines becoming the binding constraint on commercial rollout speed.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration-dependent dairy processors face retrofit deadlines that accelerate investment in ambient-stable plant protein extraction infrastructure.
- Sports nutrition formulations:Ready-to-drink recovery beverages in the United States absorb growing volumes of hydrolyzed collagen and clear whey isolates.
- China's GB standards evolution:Updated protein fortification ceilings for complementary foods create compliant formulation roadmaps for exporters targeting pediatric nutrition segments.
Market Restraints
- Yellow pea protein concentrate:Prairie drought cycles in Canada and North Dakota generate raw material volatility that compresses margin predictability for fractionation facilities.
- Whey permeate oversupply:Greek yogurt plant expansions in New York and Idaho concentrate lactose-rich byproduct streams with limited alternative feed or food applications.
- Single-cell protein allergenicity:Novel food safety dossiers for biomass fermentation ingredients face extended EFSA novel food assessment timelines.
Strategic Opportunities
- Cellular agriculture convergence:Precision fermentation and cultivated meat infrastructure sharing is reducing capital intensity for recombinant protein production.
- India's PLI scheme for food processing:Incentivized contract manufacturing capacity is opening import substitution pathways for imported whey and soy isolates.
- Direct-to-practitioner channels:Medical nutrition brands are bypassing hospital formulary committees through registered dietitian networks and telehealth platforms.
Industry Challenges
- Bioprocess engineering talent scarcity:Scale-up specialists with simultaneous fermentation and downstream purification expertise command premium compensation in Boston and Rotterdam hiring markets.
- Dual certification burden:Simultaneous organic and non-GMO verification for plant proteins requires parallel audit streams that extend supplier onboarding by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Market |
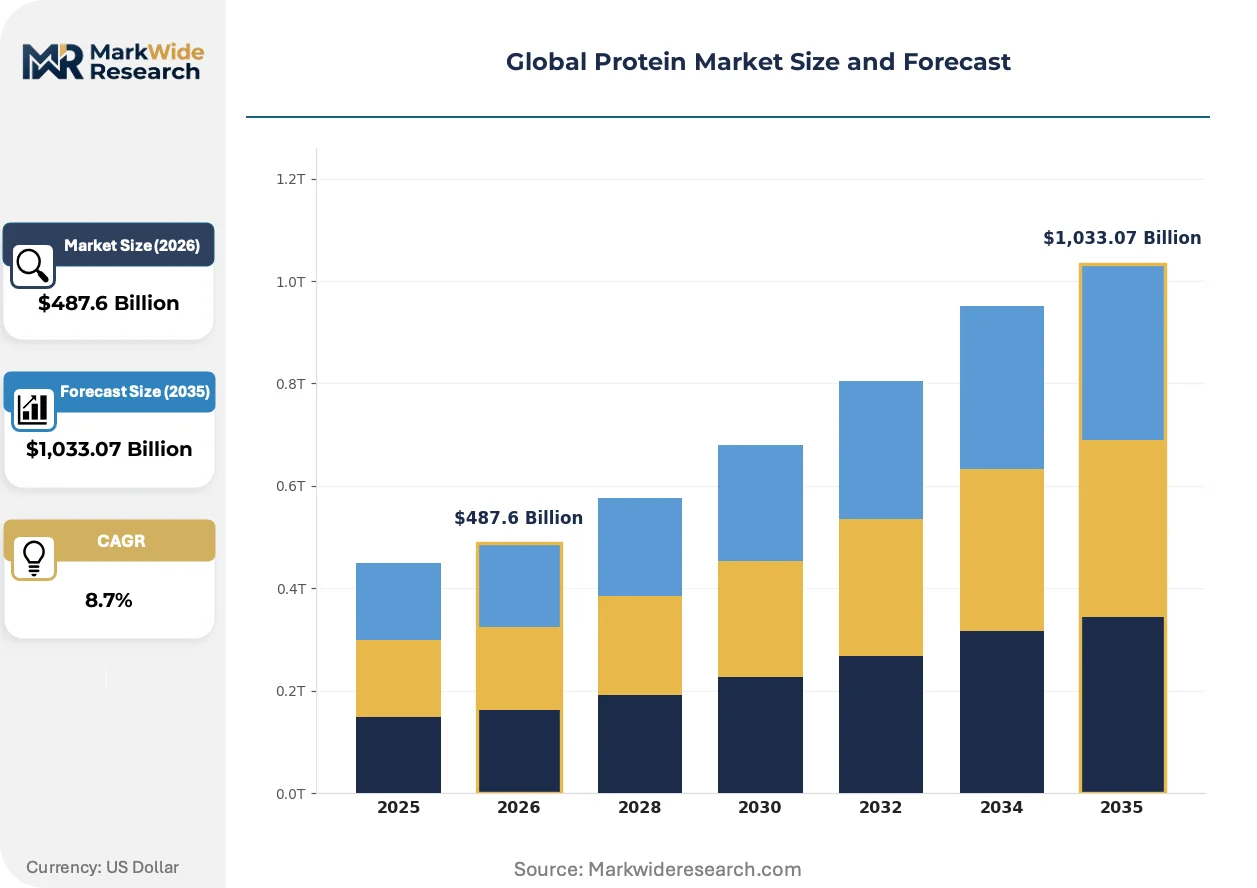
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Protein, Plant Protein, Dairy Protein, Soy Protein End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed Form: Powder, Liquid, Bars, Capsules Distribution Channel: Online, Supermarkets, Health Stores, Distributors |
| Companies Covered | Archer Daniels Midland Company, Cargill, Glanbia PLC, Kerry Group PLC, Fonterra Co-operative Group Limited, International Flavors & Fragrances Inc., Royal FrieslandCampina, Abbott, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Market Strategic Shifts
Protein manufacturing is crossing an inflection where biological production systems and digital process control are compressing batch-to-batch variability while enabling mass-customized nutritional profiles.
Continuous chromatography is automating the capture and polishing stages of monoclonal antibody-scale protein purification, with contract manufacturers in Switzerland and Singapore adopting multi-column periodic counter-current systems to reduce resin volume by half. Dairy and plant protein fractionation facilities are piloting these architectures to handle seasonal feedstock variation without yield sacrifice. The capital efficiency gains are automating the economic viability of smaller-scale regional processing plants.
REACH authorization requirements for solvent-based protein extraction are forcing European facilities to retrofit aqueous or supercritical carbon dioxide systems ahead of 2026 sunset dates. The regulatory compression is advantaging processors with existing green chemistry certifications in Germany and the Netherlands. Infant formula manufacturers are accelerating supplier qualification audits to secure compliant hydrolysate streams before authorization deadlines.
Foodservice operators are consolidating protein procurement through broadline distributors with embedded specification consulting, displacing direct relationships with ingredient suppliers. Hospital systems and university dining contracts in the United States now route through platforms that bundle nutritional compliance reporting with volume commitments. The intermediation shift is most visible in K-12 and healthcare channels where menu standardization and allergen documentation requirements have intensified.
Global Protein Market Segmentation
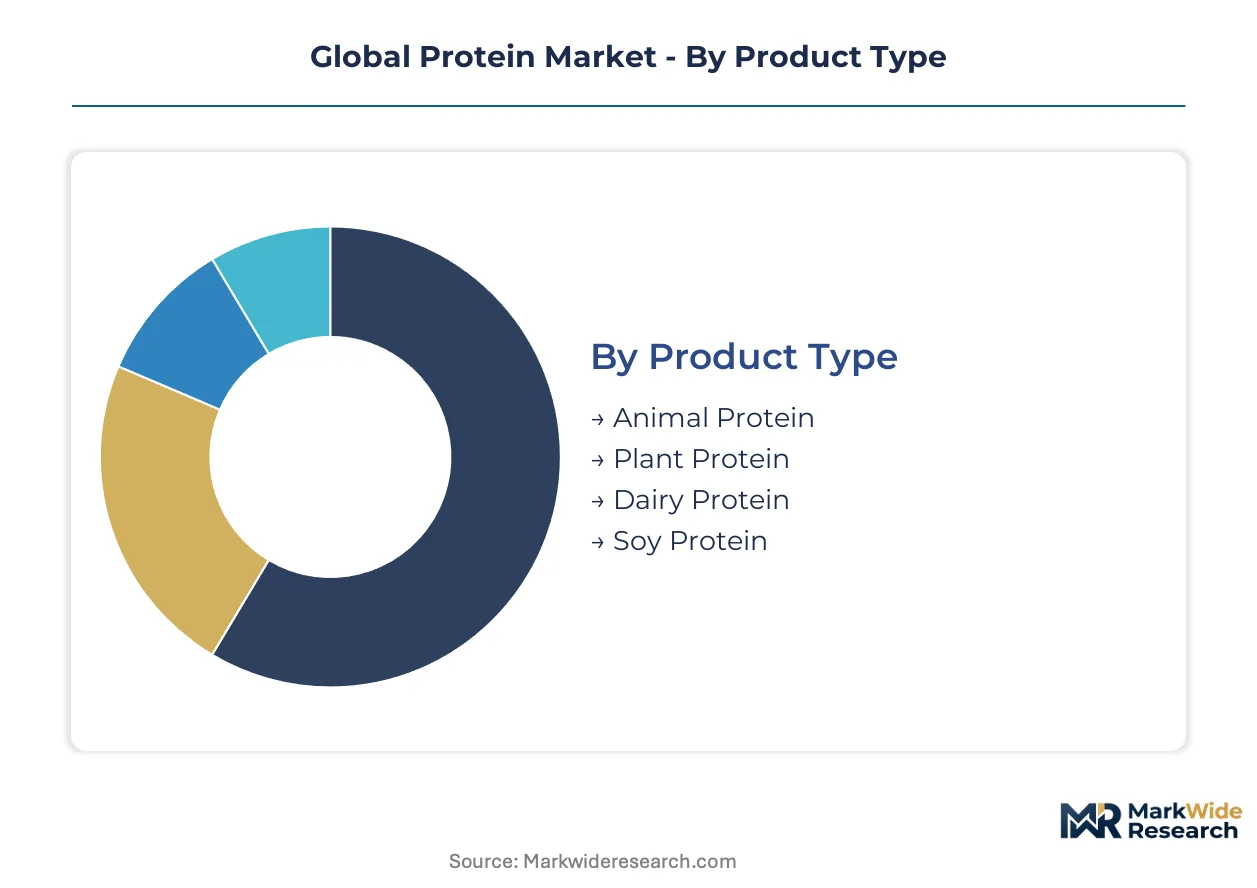
Protein market segmentation reveals how functional specifications, regulatory pathways, and channel economics create distinct competitive arenas. Understanding these divides exposes where margin pools concentrate and where formulation flexibility commands premium positioning.
Product Type:
Protein ingredient specifications diverge sharply across extraction methods, amino acid completeness, and thermal stability profiles.
- Animal Protein:Derived from meat, egg, and collagen sources with complete essential amino acid profiles and high biological value. Sports nutrition manufacturers in the United States prioritize these inputs for muscle protein synthesis claims, though EFSA novel food assessments for emerging animal sources extend commercialization timelines.
- Plant Protein:Fractionated from pea, rice, and hemp with varying leucine content and solubility challenges. Beverage brands targeting flexitarian consumers in Germany and the Netherlands drive reformulation demand as REACH solvent restrictions tighten.
- Dairy Protein:Whey and casein concentrates dominate infant formula procurement where protein digestibility-corrected amino acid scores determine supplier qualification.
- Soy Protein:Isolates and concentrates serve textured meat applications in China and Indonesia, with GMO status and allergen labeling shaping import acceptance.
Mature deployment sits with dairy protein. Newer deployment is concentrated in plant protein.
End Use Industry:
Regulatory intensity and formulation complexity create divergent margin structures across downstream sectors.
- Food & Beverage:Protein fortification spans ready-to-drink beverages, bakery, and dairy alternatives with clean-label requirements tightening in France and California. CPG brands leverage spray-dried isolates for solubility and mouthfeel control.
- Pharmaceuticals:Medical nutrition and clinical enteral feeding demand hydrolyzed peptides with documented absorption kinetics. FDA orphan drug designations for rare metabolic disorders expand addressable indications.
- Cosmetics:Keratin and collagen peptides penetrate hair care and topical anti-aging formulations, with South Korean beauty brands driving peptide molecular weight specifications.
- Animal Feed:Aquaculture and pet food applications absorb rendered protein meals and insect meal trials, constrained by EU feed ban regulations on processed animal proteins.
Volume concentration rests with food and beverage. Steepest expansion trajectory belongs to pharmaceuticals.
Form:
Delivery format selection hinges on shelf stability, dosing precision, and consumption occasion alignment.
- Powder:Bulk protein concentrates and isolates dominate sports nutrition and industrial food manufacturing, with instantized variants commanding premiums for cold-water dispersibility.
- Liquid:Ready-to-drink formulations absorb hydrolyzed collagen and clear whey isolates, with aseptic filling investments in New York and Texas supporting ambient distribution.
- Bars:Extruded and cold-pressed formats balance protein density with texture shelf life, facing moisture migration challenges in high-humidity climates.
- Capsules:Softgel and hard-shell delivery targets clinical and wellness segments with precise dosing, constrained by capsule shell supply and gelatin sourcing certifications.
Scale economies favor powder. Format innovation concentrates in liquid.
Distribution Channel:
Channel selection determines specification depth, traceability requirements, and working capital intensity.
- Online:Direct-to-consumer and marketplace platforms enable subscription models and flavor customization, with Amazon and specialized sports nutrition sites absorbing growing isolate volumes.
- Supermarkets:Mass retail placement demands price-competitive positioning and broad demographic appeal, with private label expansion compressing branded shelf space.
- Health Stores:Specialty retailers like GNC and Vitamin Shoppe emphasize third-party certification and premium sourcing narratives for discerning enthusiasts.
- Distributors:Ingredient and broadline distributors serve foodservice and manufacturing accounts with technical specification support and volume contracting.
Established infrastructure sits with distributors. Channel shift momentum favors online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest incremental protein volumes as domestic food processing scales and consumers shift toward high-protein diets. Facility investments concentrate in coastal provinces with port access for imported raw materials.
United States
Sports nutrition applications drive hydrolyzed collagen and clear whey isolate absorption across ready-to-drink recovery beverages. FDA enforces protein content labeling accuracy under Nutrition Labeling and Education Act provisions. New York and Texas host aseptic filling investments supporting ambient distribution networks.
Germany
REACH authorization requirements for solvent-based extraction force aqueous system retrofits ahead of 2026 deadlines. EFSA novel food safety benchmarks shape emerging protein source commercialization timelines. Processing clusters in North Rhine-Westphalia leverage existing green chemistry certifications for compliant hydrolysate production.
China
Domestic food processing expansion and pediatric nutrition demand concentrate procurement for whey and soy isolates. SAMR enforces GB standards for protein fortification limits in complementary foods and sports products. Yangtze River Delta facilities scale fractionation capacity for beverage brand reformulation.
India
Import substitution pathways open through PLI scheme incentivized contract manufacturing for whey and soy isolates. FSSAI mandates protein quality disclosures on packaged foods, tightening compliance costs for multinational suppliers. Maharashtra and Gujarat host emerging fractionation facilities targeting medical nutrition segments.
Netherlands
EU F-Gas Regulation retrofit deadlines accelerate ambient-stable plant protein extraction infrastructure investment. EFSA assessments for single-cell protein allergenicity extend novel food safety dossier timelines. Rotterdam hiring markets command premium compensation for bioprocess engineering talent with fermentation expertise.
Global Protein Market Competitive Environment
Capacity expansion dominates the current landscape as processors retrofit solvent-based systems and scale precision fermentation infrastructure. The vendor base stratifies across integrated agricultural traders, specialized taste and nutrition systems providers, and dairy cooperative processing networks. Three archetypes anchor competitive positioning: agricultural origination-integrated fractionators, functional ingredient formulators with sensory masking capabilities, and cooperative-owned dairy protein specialists. M&A activity concentrates on taste technology acquisitions and regional processing asset consolidation, while strategic partnerships link fermentation startups with established downstream distribution.
Within the agricultural origination tier, Archer Daniels Midland Company and Cargill exemplify integrated supply chain control from crop procurement through isolate production. Kerry Group PLC occupies a position among taste-masked protein system specialists, anchoring formulation partnerships in sports nutrition and functional beverage categories. Glanbia PLC represents the dairy cooperative archetype, with Irish and US processing assets supporting whey protein concentrate supply positions.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Glanbia PLC |
| Kerry Group PLC |
| Fonterra Co-operative Group Limited |
| International Flavors & Fragrances Inc. |
| Royal FrieslandCampina |
| Abbott |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Bioprocess engineering talent scarcity in Boston and Rotterdam compresses margin predictability for precision fermentation scale-ups, widening spreads between commodity-grade isolates and premium-certified hydrolysates as labor-cost differentials cascade through contract manufacturing tiers.
Pricing Analysis
Volume concentration in bulk whey concentrates compresses margins, while specialty hydrolysates and taste-masked systems retain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates infant formula-grade isolates from sports nutrition concentrates and feed-grade meals. Price differentiation hinges on organic certification and cold-chain logistics capability. Cost compression in standard-tier plant proteins is intensifying because prairie drought cycles in Canada generate raw material volatility. Foodservice buyers exhibit highest price sensitivity; pharmaceutical procurement committees prioritize documented absorption kinetics over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Chicago anchor hub-and-spoke patterns for temperature-sensitive isolates, with ambient-stable plant proteins bypassing cold-chain infrastructure. Raw material sourcing concentrates in Canada and North Dakota for yellow pea fractionation, Ireland and Wisconsin for whey processing, and coastal China for soy isolate production. Supply chain risk centers on single-source vulnerability for hydrolyzed collagen from Brazilian bovine hide processors. Distribution runs through broadline distributors with embedded specification consulting for foodservice and hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global protein market sits in a technology-transition phase where precision fermentation capacity is displacing legacy extraction infrastructure dependent on solvent-based systems and refrigeration-intensive dairy processing.
For Market Incumbents: Deepen backward integration into agricultural origination networks to secure consistent raw material flows against prairie drought volatility. Expand ambient-stable plant protein extraction capacity ahead of EU F-Gas Regulation retrofit deadlines. Prioritize taste-masking R&D partnerships with beverage brands reformulating for flexitarian consumers. For New Entrants and Emerging Players: Enter via direct-to-practitioner medical nutrition channels that bypass hospital formulary committees through registered dietitian networks. Target India's PLI scheme incentivized contract manufacturing capacity for import substitution in whey and soy isolates. Leverage telehealth platforms as the primary go-to-market angle for clinical peptide formulations. For Investors and Strategic Acquirers: The window for entry favors fermentation startups with simultaneous scale-up and downstream purification expertise. Long-term viability hinges on facility certification timelines as the binding constraint on commercial rollout speed. Watch EFSA novel food safety dossier approval velocity as the critical inflection indicator for single-cell protein allergenicity resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces capital intensity through infrastructure sharing with cultivated meat facilities in Boston and Rotterdam. |
| Ambient-Stable Extraction Retrofit | Positions European processors ahead of REACH authorization sunset dates for solvent-based systems. |
| Taste Technology Acquisition | Secures formulation partnerships with sports nutrition brands demanding clean-label solubility. |
| Direct-to-Practitioner Channel Buildout | Bypasses consolidated foodservice procurement through registered dietitian networks and telehealth platforms. |
| Green Chemistry Certification Investment | Accelerates supplier qualification audits from infant formula manufacturers facing hydrolysate stream deadlines. |
Study Parameters
Multi-period observation of fractionation capacity utilization, novel food approval timelines, and pediatric nutrition procurement patterns anchored the trend analysis, supplemented by interviews with plant engineering directors, sports nutrition brand formulators, regulatory affairs leads at fermentation startups, and hospital GPO contract managers. Secondary validation drew from EFSA novel food register updates, SAMR GB standards bulletins, FDA warning letter databases, and customs trade records for pea and whey isolate flows. Bottom-up facility capacity modeling triangulated against top-down protein fortification demand projections.
Segment-weighting across product type, end-use industry, form, and distribution channel dimensions calibrated value and volume outputs across the analysis window. CAGRs derived from least-squares fitting of annual capacity expansion announcements and downstream formulation reformulation cycles. Forecast inputs incorporated EU F-Gas Regulation compliance cost curves and China's GB standards evolution for complementary foods.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EFSA novel food assessment timelines and prairie drought recurrence patterns. Outputs reflect documented assumptions on precision fermentation yield improvements and regulatory harmonization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
High-Concentrated Protein Market